
 Beta Thalassemia Testing Market | 2026-2036
Beta Thalassemia Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Thalassemia Testing Market Outlook
The beta thalassemia testing landscape is shifting between premium molecular diagnostics and commodity hematology screens. Thermo Fisher Scientific leverages its Ion Torrent platform to anchor the high-complexity genetic testing tier for rare mutation profiling. BGI Genomics sustains cost leadership in population-scale screening through automated next-generation sequencing workflows. Bio-Rad Laboratories competes at the mid-market level with capillary electrophoresis systems that balance throughput and capital efficiency.
Beta thalassemia testing encompasses laboratory and clinical methodologies that detect quantitative hemoglobin chain defects through protein electrophoresis patterns, DNA mutation analysis, or red blood cell indices, with genetic assays targeting HBB gene mutations across seventeen common and over two hundred rare variants to inform transfusion therapy, chelation management, and stem cell transplant candidacy. Genetic testing and next-generation sequencing segments command the strongest margin pools due to reimbursement premiums for definitive molecular diagnosis, while hemoglobin electrophoresis remains the mature volume workhorse in resource-limited settings. Diagnostic laboratories represent the fastest-growing end user channel as centralized reference networks absorb testing from smaller hospital labs seeking to avoid capital outlays for sequencing infrastructure.
The FDA regulates in vitro diagnostic devices and laboratory-developed tests under evolving frameworks that increasingly require analytical and clinical validation data for molecular assays, while the EMA and national EU competent authorities enforce the In Vitro Diagnostic Regulation performance standards that reshape market access timelines and notified body certification burdens. WHO guidelines on hemoglobin disorder screening and the ISO 15189 accreditation standards for medical laboratories collectively shape procurement specifications and quality benchmarks that vendors must satisfy to participate in national health programs. Stakeholders must monitor how regulatory convergence between FDA and EMA post-market surveillance requirements will affect validation costs and competitive positioning for multi-market test platforms.
Market Dynamics
Centralized reference laboratories are consolidating beta thalassemia testing volumes as hospital systems divest from capital-intensive sequencing infrastructure, creating tiered service hierarchies between high-complexity molecular hubs and routine hematology screening sites.
Growth Catalysts
- Carrier screening mandates:National health programs in Cyprus, Greece, and Italy mandate premarital or prenatal screening for hemoglobinopathies, institutionalizing population-scale testing workflows.
- Next-generation sequencing:Automated NGS platforms reduce mutation detection turnaround from weeks to days, enabling definitive diagnosis before critical therapeutic windows close.
- WHO hemoglobin disorder guidelines:The WHO framework for thalassemia and sickle cell disease screening drives procurement specifications across Mediterranean and Southeast Asian national health systems.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction master mixes and fluorescent dyes concentrate among three specialty chemical suppliers, exposing testing labs to input cost volatility.
- IVDR certification timelines:The EU In Vitro Diagnostic Regulation extends notified body review periods for novel molecular assays, delaying market entry for mutation panel updates.
- Capillary electrophoresis substitution:Mature hemoglobin electrophoresis systems face displacement pressure from point-of-care lateral flow devices in resource-limited primary care settings.
Strategic Opportunities
- Underpenetrated South Asian markets:India and Pakistan maintain substantial undiagnosed carrier populations where decentralized screening programs could replicate Mediterranean prevention models.
- Non-invasive prenatal testing convergence:Cell-free fetal DNA analysis combined with targeted HBB gene sequencing enables early trimester diagnosis without invasive sampling procedures.
- Direct-to-consumer channel emergence:At-home saliva collection kits for carrier status screening bypass clinical gatekeepers, reaching reproductive-age adults outside traditional healthcare pathways.
Industry Challenges
- Molecular geneticist workforce scarcity:Interpretation of rare HBB variants requires specialized expertise that outpaces training program output in high-prevalence countries.
- Laboratory information system integration:NGS data pipelines demand costly middleware upgrades to connect with legacy hospital electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Thalassemia Testing Market |
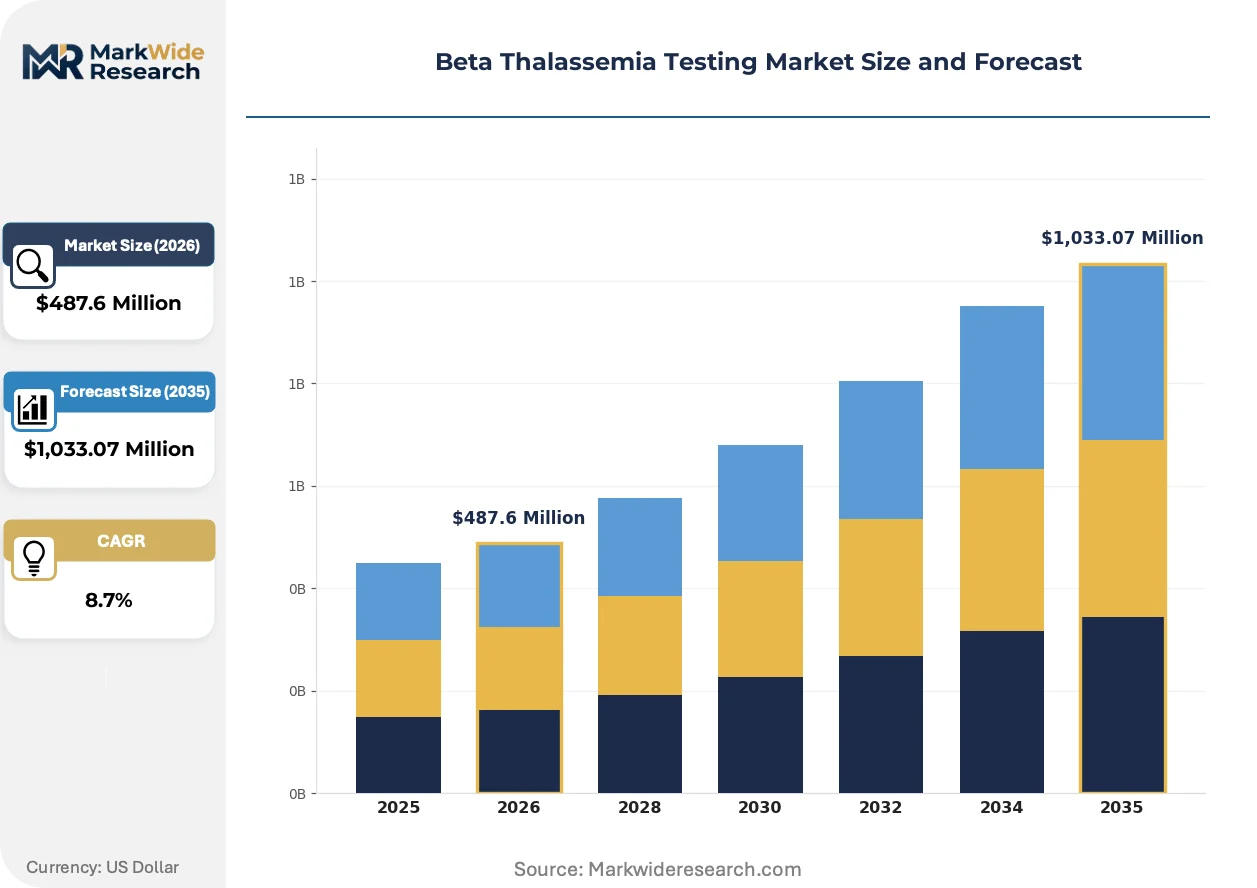
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Hemoglobin Electrophoresis, Complete Blood Count, Genetic Testing, Sickle Cell Test End User: Hospitals, Diagnostic Laboratories, Research Institutes, Blood Banks Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Capillary Electrophoresis, Microarray Service Type: Consultation, Diagnostic Services, Screening Programs, Genetic Counseling |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., QIAGEN N.V., PerkinElmer Inc., Illumina Inc., Hoffmann-La Roche Ltd., Sysmex Corporation, BGI Genomics Co. Ltd., MedGenome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Thalassemia Testing Market Strategic Shifts
Digital pathology and artificial intelligence are compressing diagnostic interpretation cycles while regulatory frameworks for laboratory-developed tests undergo substantial recalibration across major markets.
CRISPR-based diagnostic platforms are decentralizing mutation confirmation workflows by enabling isothermal amplification at ambient temperatures without thermal cycler infrastructure. Rural clinics in thalassemia-endemic regions of Sardinia and Sicily are piloting these systems for same-day carrier screening results. The technology is decentralizing confirmatory testing from urban reference centers to district hospital laboratories.
The FDA's evolving oversight framework for laboratory-developed tests now requires analytical validation studies for high-complexity molecular assays that previously operated under enforcement discretion. Academic medical centers must retrofit retrospective sample collections to satisfy premarket notification requirements. Genetic testing laboratories serving US Medicaid populations face the steepest compliance cost increases as they lack pharmaceutical sponsor funding for validation studies.
Consolidated procurement by multi-hospital health systems is compressing vendor margins as standardized mutation panel contracts replace ad-hoc test ordering. Integrated delivery networks in California and New York now mandate single-source agreements for hemoglobinopathy testing across all affiliated sites. This concentration is most visible in US metropolitan markets where three health systems control over half of tertiary obstetric referrals.
Beta Thalassemia Testing Market Segmentation
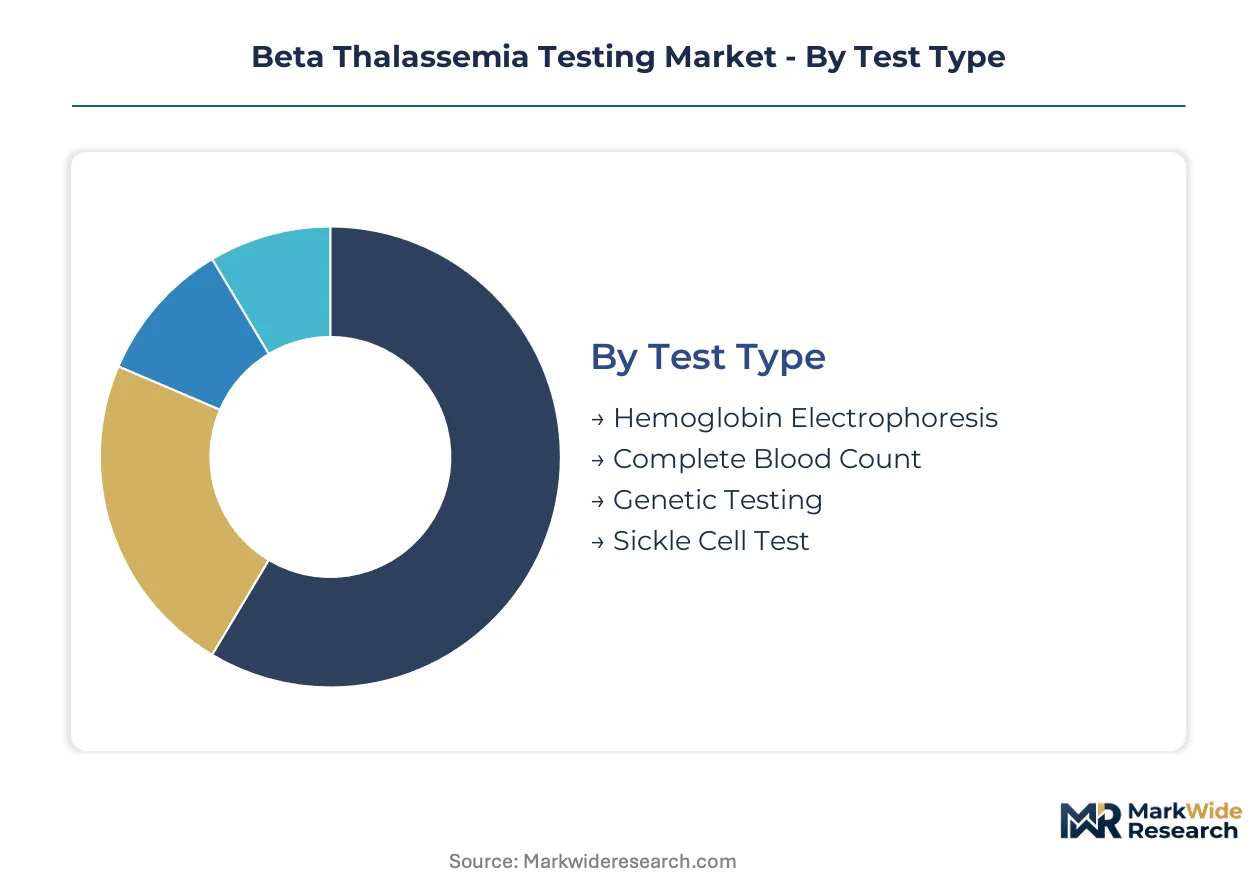
Beta thalassemia testing segments reflect divergent capital requirements and reimbursement tiers. Test type and technology choices determine whether laboratories deploy standalone instruments or embed assays within broader hematology workflows.
Test Type:
Integration depth separates point-of-care screening from laboratory-based definitive diagnosis.
- Hemoglobin Electrophoresis:Protein separation methods detect abnormal hemoglobin variants through charge-based migration patterns. District hospitals in Cyprus and Greece rely on cellulose acetate systems for premarital screening compliance under national mandates.
- Genetic Testing:DNA-based assays identify HBB gene mutations with specificity exceeding protein methods. Tertiary centers in Italy concentrate demand for pre-implantation genetic diagnosis before in vitro fertilization procedures.
- Complete Blood Count:Automated hematology analyzers flag microcytic hypochromic indices suggesting thalassemia trait. Primary care clinics embed these within routine antenatal panels.
- Sickle Cell Test:Solubility and electrophoresis methods distinguish sickle hemoglobin from beta thalassemia variants. Neonatal screening programs in Saudi Arabia and Pakistan combine these assays for hemoglobinopathy detection.
Volume placements concentrate in Hemoglobin Electrophoresis; the faster expansion belongs to Genetic Testing.
End User:
Cost tiers separate capital-intensive molecular hubs from routine screening sites.
- Diagnostic Laboratories:Centralized reference networks absorb complex genetic testing from smaller facilities. Academic medical centers in Milan and Athens operate high-throughput sequencing platforms serving multi-hospital catchment areas.
- Hospitals:Inpatient and outpatient departments manage transfusion-dependent patients requiring periodic monitoring. Pediatric hematology units in India maintain in-house electrophoresis for urgent pre-transfusion matching.
- Blood Banks:Donor screening operations prevent transfusion-transmitted hemoglobinopathies. National blood services in the UK extend testing to donor extended phenotyping programs.
- Research Institutes:Biorepositories and clinical trial sites generate epidemiological data on mutation frequencies. Population genetics studies in Sardinia leverage archived samples for rare variant cataloging.
Diagnostic Laboratories capture the premium pricing tier; Hospitals retain the highest absolute test volumes.
Technology:
Application focus distinguishes research-grade platforms from clinical diagnostic workhorses.
- Next-Generation Sequencing:Massively parallel sequencing enables simultaneous detection of common and rare HBB variants. Commercial laboratories in California deploy automated workflows for expanded carrier panels.
- Polymerase Chain Reaction:Targeted amplification methods detect specific point mutations and deletions with rapid turnaround. Regional hospitals in Southeast Asia favor gap-PCR for Southeast Asian deletion variants.
- Capillary Electrophoresis:High-resolution separation methods resolve hemoglobin fractions with quantitative precision. Mid-market laboratories balance throughput against capital constraints.
- Microarray:Solid-phase hybridization platforms screen for known mutations across multiple hemoglobinopathy genes. Research applications predominate as clinical adoption lags sequencing alternatives.
Capillary Electrophoresis maintains installed base dominance; Next-Generation Sequencing shows the steepest expansion trajectory.
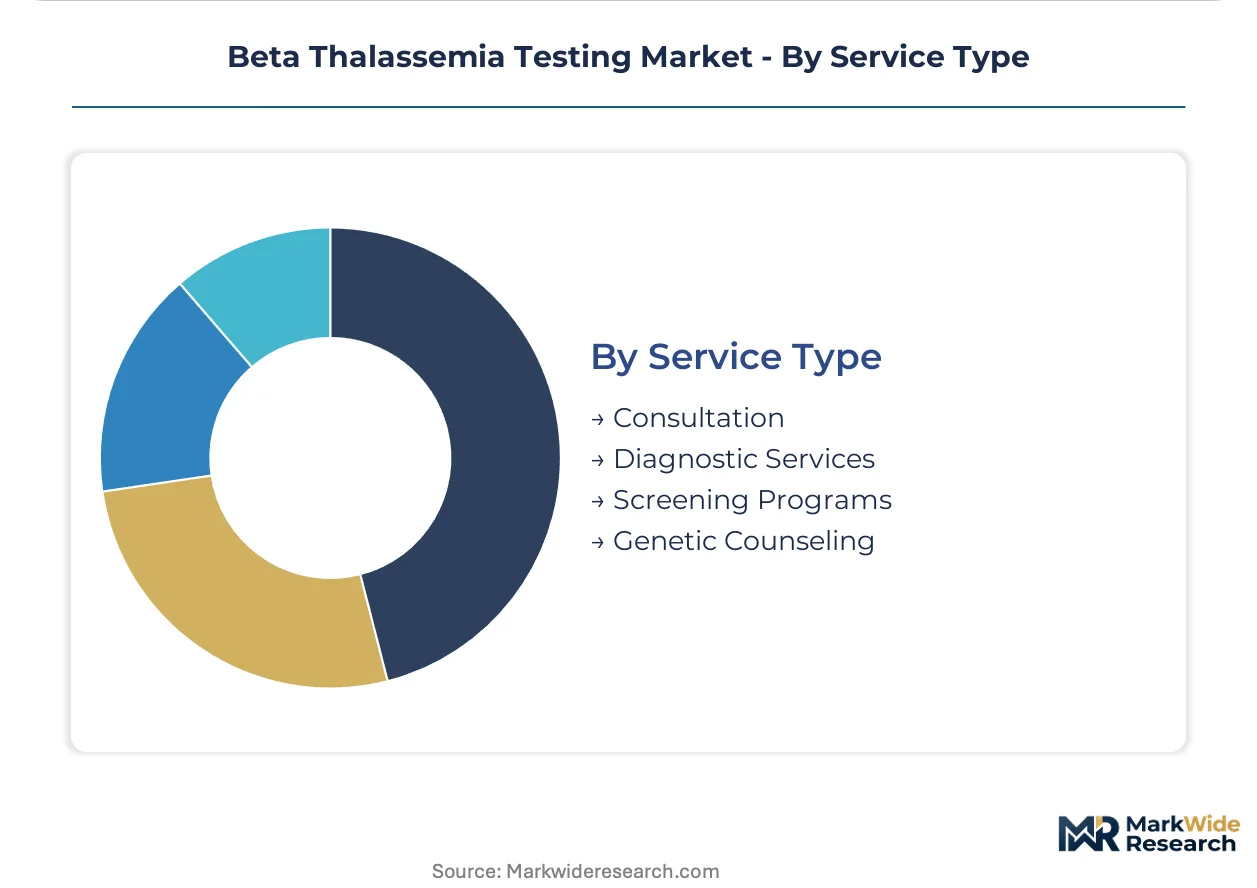
Service Type:
Customer type separates clinical diagnostic revenue from preventive public health expenditure.
- Diagnostic Services:Laboratory testing for symptomatic patients or confirmed carriers generates fee-for-service revenue. Private pathology groups in Germany operate dedicated hemoglobinopathy units.
- Screening Programs:Population-scale carrier detection operates through government-contracted networks. Cyprus and Iran maintain mandatory premarital screening with state-funded testing.
- Genetic Counseling:Pre-test and post-test consultation services interpret results for at-risk families. Specialized clinics in London and Paris integrate counseling with reproductive endocrinology.
- Consultation:Expert interpretation of complex or ambiguous molecular findings supports community pathologists. Telemedicine platforms extend specialist access to underserved regions.
Diagnostic Services generate the highest per-patient revenue; Screening Programs claim the largest aggregate test volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors European beta thalassemia testing demand through its concentration of academic medical centers operating high-throughput sequencing platforms for multi-hospital catchment areas across northern Italy.
Italy
Premarital screening mandates in Sicily and Sardinia sustain population-scale testing workflows, with the National Health Service funding comprehensive carrier detection programs. ISO 15189 accreditation standards shape procurement specifications for laboratories participating in regional prevention networks. Rome's tertiary obstetric centers concentrate demand for pre-implantation genetic diagnosis before in vitro fertilization procedures.
Greece
National mandates require hemoglobinopathy screening before marriage, institutionalizing diagnostic laboratory networks across Attica and Thessaloniki. EMA oversight of in vitro diagnostic devices ensures analytical validation for molecular assays used in carrier detection. Athens operates reference sequencing hubs serving hospital systems that have divested from capital-intensive infrastructure.
Cyprus
The island maintains the world's highest beta thalassemia carrier prevalence, driving state-funded premarital screening compliance rates exceeding ninety percent. WHO guidelines on hemoglobin disorders directly inform the Ministry of Health's procurement specifications for testing platforms. Nicosia's centralized reference laboratory absorbs complex genetic testing from district hospitals seeking to avoid sequencing capital outlays.
India
Maharashtra and Gujarat harbor substantial undiagnosed carrier populations where decentralized screening programs could replicate Mediterranean prevention models. The country's national pharmaceutical regulator oversees quality benchmarks for molecular assays deployed in public health programs. Mumbai's private pathology groups operate dedicated hemoglobinopathy units serving tertiary pediatric hematology centers.
United States
California and New York metropolitan markets concentrate demand as integrated delivery networks mandate single-source agreements for hemoglobinopathy testing across affiliated sites. FDA oversight now requires analytical validation studies for high-complexity molecular assays previously operating under enforcement discretion. Academic medical centers in Boston retrofit retrospective sample collections to satisfy premarket notification requirements for expanded carrier panels.
Beta Thalassemia Testing Market Competitive Environment
Premium-margin players sit above commodity-margin players across the technology-capital intensity spectrum. Thermo Fisher Scientific and Illumina anchor the high-complexity genetic testing tier, while mid-market laboratories balance throughput against capital constraints with established electrophoresis platforms. Three strategic archetypes dominate: sequencing technology licensors, automated workflow integrators, and regional reference service operators. Consolidated procurement by multi-hospital health systems compresses vendor margins, while technology licensing agreements enable geographic expansion without direct infrastructure investment.
Among US-based diversified life science conglomerates, Thermo Fisher Scientific Inc. and PerkinElmer Inc. occupy positions spanning reagent supply through analytical instrumentation. Swiss pharmaceutical-diagnostic hybrid Hoffmann-La Roche Ltd. exemplifies the integrated healthcare archetype with embedded molecular diagnostics divisions. Chinese genomic services specialist BGI Genomics Co. Ltd. represents cost-leadership positioning in population-scale screening workflows. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic moves.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| QIAGEN N.V. |
| PerkinElmer Inc. |
| Illumina Inc. |
| Hoffmann-La Roche Ltd. |
| Sysmex Corporation |
| BGI Genomics Co. Ltd. |
| MedGenome |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement by multi-hospital health systems and national screening programs concentrates buying power among fewer decision-makers, compressing vendor margins and institutionalizing contract-based long-term offtake agreements for mutation panel supplies across Mediterranean markets.
Pricing Analysis
Throughput-based pricing anchors the diagnostic platform tier, with automated next-generation sequencing workflows commanding subscription premiums tied to annual test volumes rather than per-unit reagent costs. Three-tier pricing structure across premium, standard, and economy levels separates CE-IVD certified instruments from research-use-only systems and refurbished electrophoresis units. Cost compression in the capillary electrophoresis segment is intensifying because district hospitals in Cyprus and Greece consolidate orders through centralized reference networks. Research institutes exhibit the lowest price sensitivity due to grant-funded procurement, while primary care clinics in resource-limited settings drive aggressive negotiation for point-of-care screening devices.
Supply Chain Analysis
Fluorescent dye and PCR master mix supply rests on specialty chemical producers concentrated in Germany, Switzerland, and the United States, creating single-source vulnerability for laboratories dependent on proprietary reagent formulations. Sequencing flow cells, thermal cycler components, and capillary arrays represent critical input categories with limited qualified suppliers. Tariff exposure on Chinese-manufactured consumables is elevating landed costs for European diagnostic laboratories. Distribution runs through authorized distributor networks serving hospital systems and direct procurement channels for national health service contracts in Italy and Greece.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
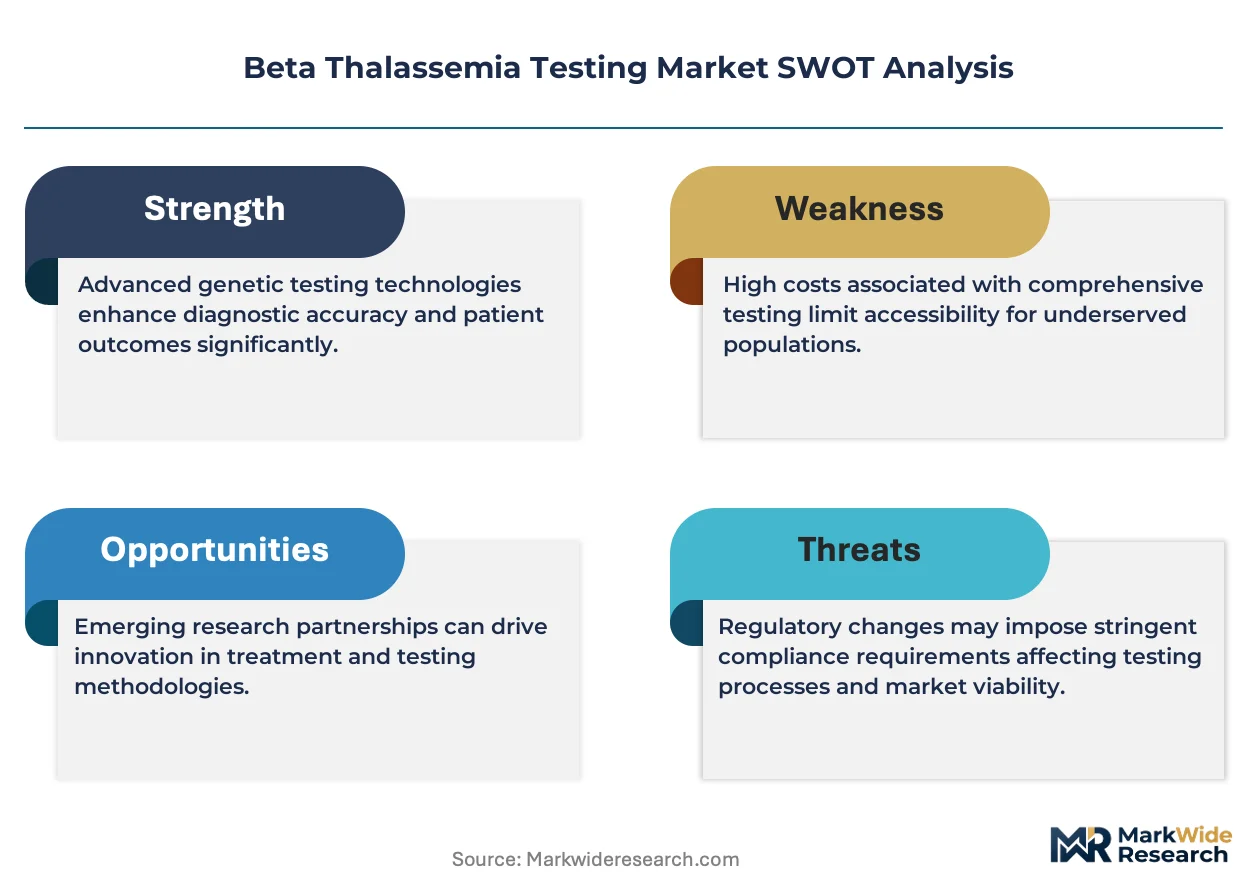
The beta thalassemia testing market is consolidating around sequencing technology licensors and automated workflow integrators, with IVDR certification timelines and capital intensity pressures forcing smaller regional reference service operators toward acquisition or exit.
For Market Incumbents: Deploy certification investment as the primary lever to defend installed base positions against emerging CRISPR-based diagnostic platforms. Pursue backward integration into reagent manufacturing to reduce exposure to specialty chemical supplier concentration. Secure exclusive service contracts with expanding diagnostic laboratory networks in India and Pakistan before local competitors achieve scale. For New Entrants and Emerging Players: Isothermal amplification at ambient temperatures offers a technology-first wedge into district hospital laboratories currently underserved by urban reference centers. Target premarital screening compliance gaps in Maharashtra and Gujarat where carrier detection rates lag Mediterranean benchmarks. Partner with telemedicine platforms to bundle remote genetic counseling with at-home saliva collection kits, bypassing clinical gatekeeper dependencies. For Investors and Strategic Acquirers: The window for entry favors automated workflow integrators with CE-IVD certified platforms and established notified body relationships. Mid-cap reference laboratories with ISO 15189 accreditation and captive screening program contracts represent viable acquisition targets. Watch FDA premarket notification requirements for laboratory-developed tests as the inflection indicator for US market access cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR compliance enables participation in Cyprus and Greece national screening tenders. |
| Hospital System Partnership | Exclusive agreements with Milan and Athens academic centers lock in sequencing volume commitments. |
| Software Companion Development | AI-powered variant interpretation tools address molecular geneticist workforce scarcity constraints. |
| Reimbursement Strategy | Medicaid coding alignment determines US market viability for expanded carrier panels. |
| Regulatory Approval Pathway | WHO prequalification accelerates procurement in thalassemia-endemic national health programs. |
Study Parameters
Multi-period observation of sequencing platform placements, screening program contract awards, and mutation panel reimbursement rates anchored the trend analysis, supplemented by interviews with laboratory directors at academic medical centers in Milan and Athens, procurement managers at Italian and Greek national health services, regulatory affairs specialists navigating IVDR transition, and biomedical engineers at centralized reference networks. Secondary validation drew from EMA notified body guidance documents, WHO hemoglobin disorder screening frameworks, ISO 15189 accreditation standards, and hospital procurement databases. Bottom-up test volume estimates triangulated against top-down national screening program expenditure data.
The input-output matrix framed projections across test type, technology platform, end-user channel, and regional regulatory cluster dimensions over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating technology substitution curves, screening mandate expansion timelines, and laboratory consolidation patterns. Forecast inputs included NGS platform installation forecasts, capillary electrophoresis replacement cycles, and point-of-care device adoption trajectories in primary care settings.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement discretion changes, supply disruptions from specialty chemical producer consolidation, and sudden shifts in national screening program funding. Forecasts reflect documented assumptions about technology adoption rates and reimbursement stability. A small set of named triggers warrants ongoing watch: FDA laboratory-developed test framework finalization, IVDR notified body capacity constraints, and CRISPR diagnostic platform clinical validation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Botulism Illness Market