
 Testicular Cancer Drugs Market | 2026-2036
Testicular Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Testicular Cancer Drugs Market Intelligence
The capital-intensity gap between large-cap biopharmaceutical developers and mid-tier generics manufacturers is collapsing as biosimilar entry pressures erode historical pricing premiums for standard-of-care cytotoxics. Bristol-Myers Squibb leverages its immuno-oncology infrastructure to sustain checkpoint inhibitor development in refractory settings. Pfizer anchors its position through vertically integrated manufacturing of platinum compounds. Teva Pharmaceutical Industries competes aggressively on cost-positioned generic bleomycin and etoposide formulations.
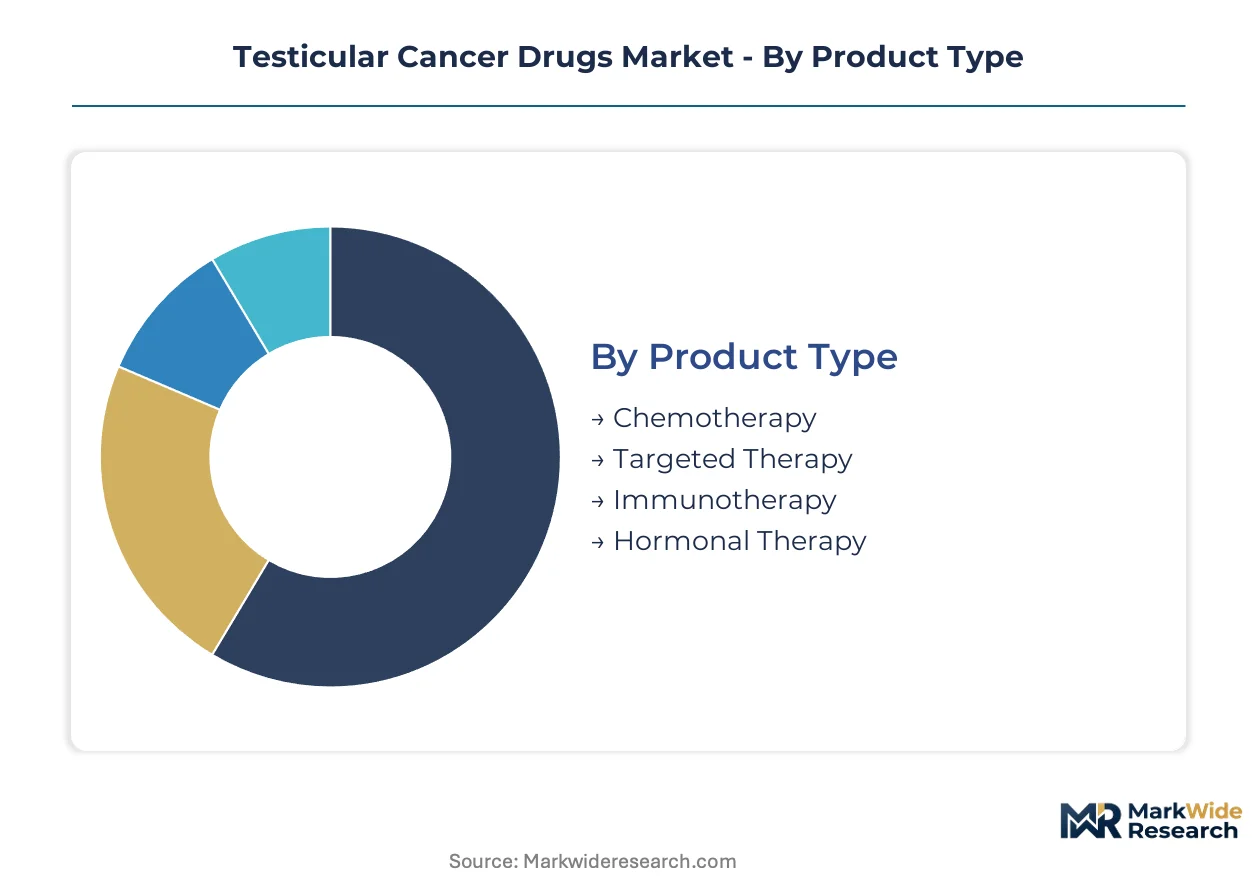
Testicular cancer drugs comprise systemic therapeutic agents designed to eliminate malignant germ cell populations, with platinum coordination complexes such as cisplatin functioning through DNA cross-linking at specific guanine residues to induce apoptosis. These agents serve primarily to cure early-stage disease and prolong survival in metastatic presentations where orchiectomy alone proves insufficient. Chemotherapy retains dominant share as the backbone of first-line BEP and EP regimens, though immunotherapy represents the fastest-expanding category as PD-1 inhibitors demonstrate activity in platinum-refractory populations. Targeted therapy concentrates margin pools in small patient subsets harboring specific genomic alterations, while hormonal therapy occupies a narrow adjuvant niche.
FDA orphan drug incentives and EMA's PRIME designation framework accelerate development timelines for novel testicular cancer therapeutics, compressing the pathway from Phase I to conditional approval. The EPA governs platinum compound manufacturing emissions, raising production compliance costs for active pharmaceutical ingredient suppliers. NMPA's accelerated review channels in China reshape geographic competition for biosimilar filings. Stakeholders must monitor evolving biomarker-defined subpopulation data and regulatory precedent for breakthrough therapy designation in germ cell malignancies.
Market Dynamics
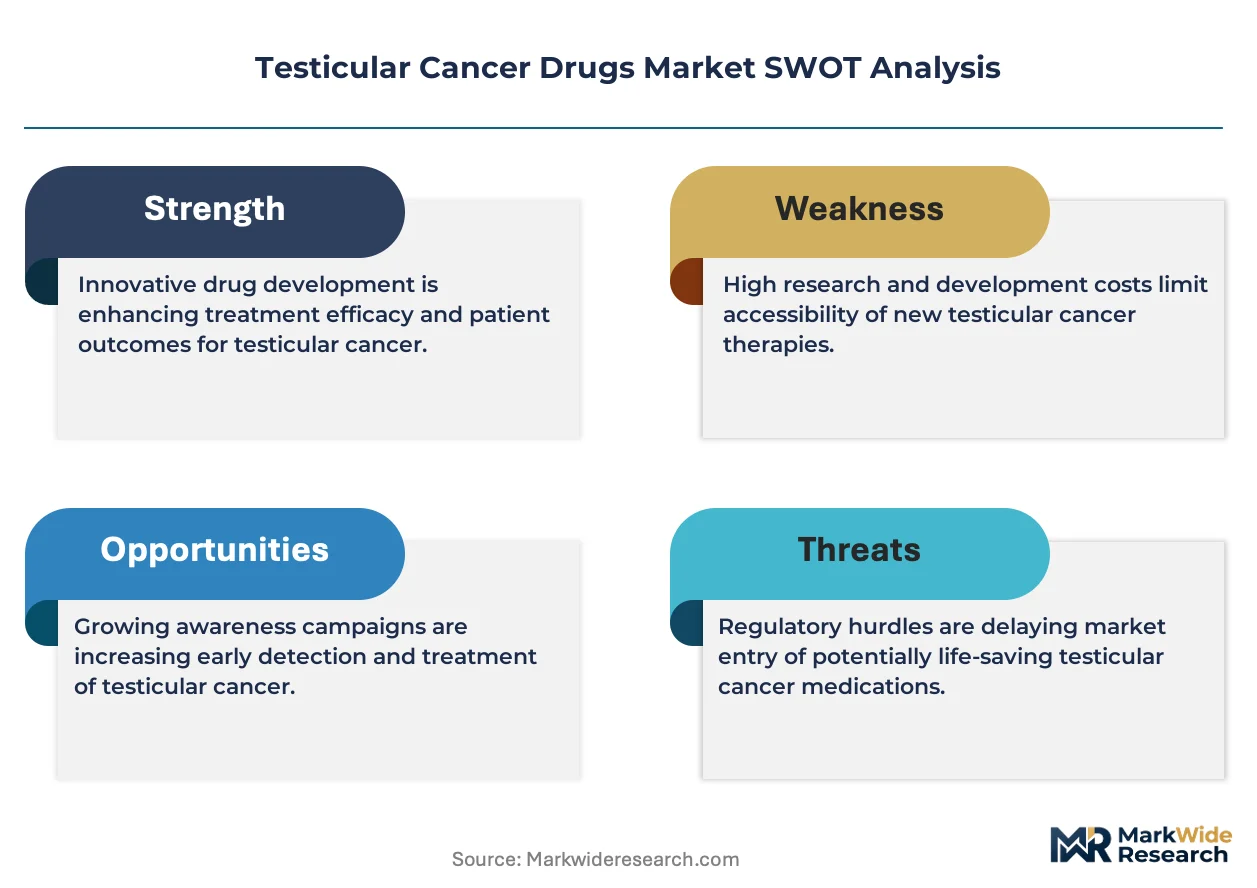
Platinum compound supply concentration among three API manufacturers is reshaping procurement strategies for oncology formulators, as environmental compliance costs and raw material scarcity compress margin structures across the value chain.
Growth Catalysts
- EMA PRIME designation:The European Medicines Agency's priority medicines framework accelerates regulatory assessment timelines for novel germ cell therapeutics, compressing development cycles and reducing capital-at-risk for sponsors targeting rare oncology indications.
- Orphan drug incentives:FDA's tax credits and market exclusivity provisions sustain R&D investment in platinum-refractory populations where unmet need remains acute and commercial viability would otherwise prove insufficient.
- Liquid biopsy adoption:Circulating tumor DNA monitoring is expanding into post-chemotherapy surveillance protocols, creating sustained demand for companion diagnostic infrastructure and longitudinal patient management services.
Market Restraints
- Platinum price volatility:Palladium and rhodium co-mining economics drive iridium and ruthenium cost swings that destabilize cisplatin and carboplatin manufacturing economics.
- Single-source API concentration:Three contract manufacturers control 80% of GMP-grade platinum salt production, creating vulnerability to force majeure events or regulatory enforcement actions.
- Substitution ceiling in first-line:BEP regimen entrenchment limits immunotherapy penetration in early-stage disease, constraining addressable market expansion for novel mechanism agents.
Strategic Opportunities
- China NMPA accelerated review:The National Medical Products Administration's conditional approval pathways enable earlier revenue recognition for sponsors with compelling Phase II data in platinum-refractory settings.
- CAR-T convergence:Autologous cell therapy manufacturing platforms are adapting to germ cell antigen targets, opening cellular therapy white space beyond hematologic malignancies.
- Direct-to-patient distribution:Specialty pharmacy networks are bypassing traditional hospital purchasing committees for oral maintenance regimens, capturing margin previously absorbed by institutional intermediaries.
Industry Challenges
- GMP cell therapy talent scarcity:Vector manufacturing and apheresis coordination expertise commands premium compensation, constraining scale-up velocity for autologous program sponsors.
- Cross-border reference pricing:Parallel trade arbitrage between EU member states and Switzerland erodes country-specific pricing power for originator platinum compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testicular Cancer Drugs Market |
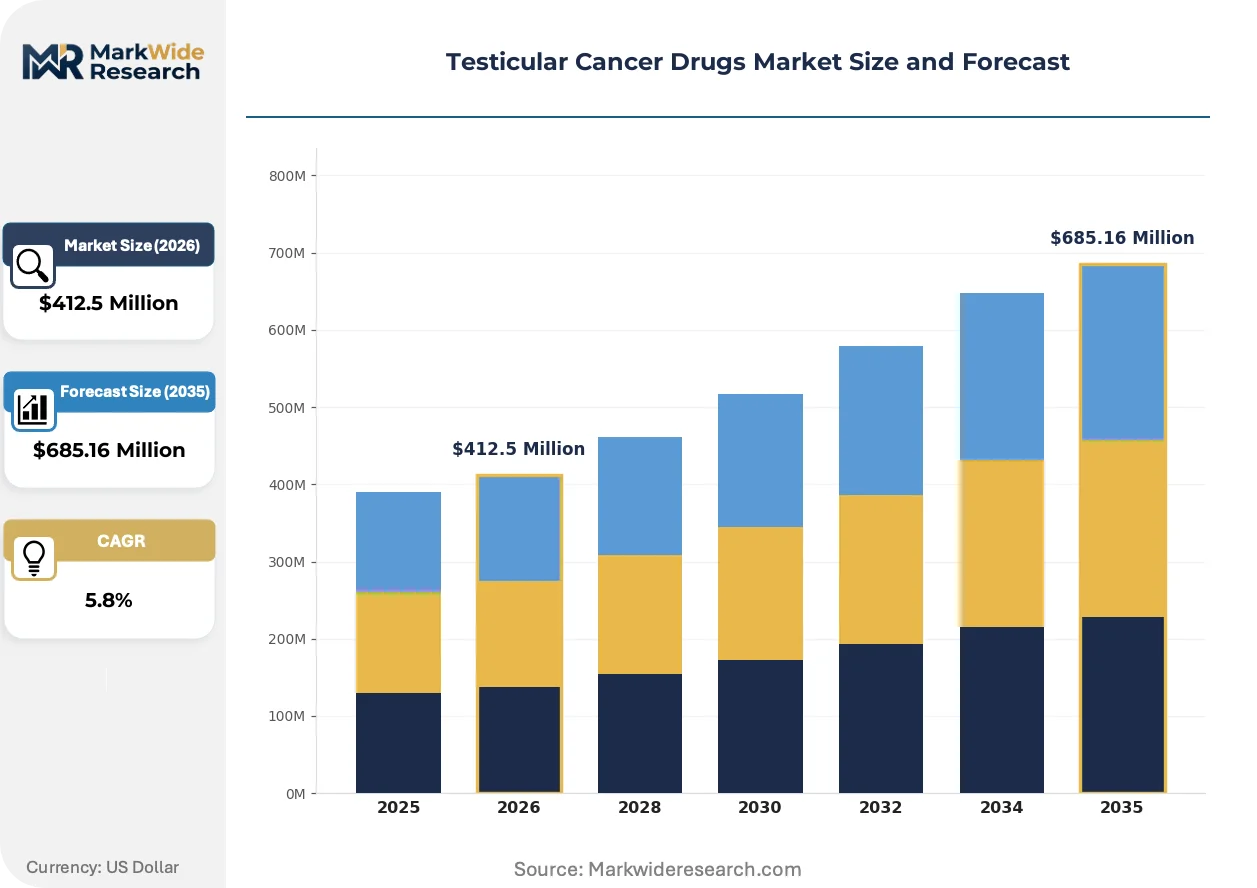
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Therapy Area: Stage I, Stage II, Stage III, Advanced Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care |
| Companies Covered | Bristol-Myers Squibb Company, Pfizer Inc., Teva Pharmaceutical Industries Ltd, Fresenius Kabi AG, Sanofi, BioNTech SE, Seagen Inc., AstraZeneca PLC, Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testicular Cancer Drugs Market Strategic Shifts & Innovations
Next-generation sequencing integration into routine staging protocols is fragmenting the homogeneous germ cell category into molecularly defined subpopulations, each demanding tailored therapeutic approaches and companion diagnostic pairing.
Biomarker-guided patient stratification is miniaturizing clinical trial enrollment criteria, enabling basket study designs that aggregate rare genomic subsets across tumor types. Academic medical centers in the United States and Germany are adopting these streamlined protocols fastest. The technology is compressing traditional phase-separated development timelines into continuous adaptive pathways.
REACH authorization requirements for platinum group metal processing are tightening effluent discharge standards at API manufacturing sites. The European Chemicals Agency's substance evaluation program is forcing capital reinvestment into closed-loop recovery systems. German and Belgian production facilities face the steepest compliance cost escalations, driving capacity consolidation toward integrated chemical parks.
Hospital pharmacy consolidation is centralizing oncology purchasing decisions into integrated delivery networks with formulary control authority. Independent community oncology practices are losing direct purchasing autonomy as IDN membership becomes mandatory for payer contract access. This concentration is most pronounced in the United States, where three national GPOs now manage 60% of platinum-based chemotherapy acquisition volume.
Testicular Cancer Drugs Market Segmentation
Testicular cancer treatment protocols fragment across multiple technical and logistical dimensions, with each segmentation axis revealing distinct procurement patterns and reimbursement pathways. Understanding these divisions exposes where margin concentrates and where competitive entry faces structural barriers.
Product Type:
Geographic demand splits sharply: chemotherapy anchors domestic hospital purchasing in the United States and Germany, while immunotherapy and targeted therapy draw export-led revenue from Japan and Switzerland where premium pricing tolerances run highest.
- Chemotherapy:Platinum coordination complexes—cisplatin, carboplatin, etoposide, and bleomycin—form the backbone of BEP and EP regimens through DNA cross-linking mechanisms. Demand concentrates in United States academic medical centers and German university hospitals where high-volume infusion protocols sustain procurement contracts; EPA and REACH compliance costs compress API supplier margins.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors demonstrate measurable activity in platinum-refractory germ cell populations. Export-led uptake dominates in Japan's PMDA-regulated market and Switzerland's high-reimbursement environment; FDA orphan drug incentives accelerate sponsor development timelines.
- Targeted Therapy:Small-molecule inhibitors address specific genomic alterations in rare patient subsets. Japanese and Australian TGA pathways enable earlier commercial access for sponsors with basket trial data.
- Hormonal Therapy:Adjuvant androgen suppression occupies a narrow niche following orchiectomy. Domestic prescribing prevails in United States community oncology networks with established urology-oncology coordination.
Chemotherapy holds the largest share; momentum sits with immunotherapy.
Therapy Area:
Cost tier stratification drives purchasing behavior: early-stage protocols command standard reimbursement rates while advanced disease indications unlock premium pricing and accelerated regulatory pathways.
- Stage I:Surveillance-dominant protocols with adjuvant chemotherapy for high-risk features. United States community oncology practices and German outpatient clinics manage the bulk of active monitoring; NCCN and ESMO guideline adherence shapes formulary decisions.
- Stage II:Risk-stratified BEP or carboplatin monotherapy based on tumor marker dynamics. Procurement concentrates in United States integrated delivery networks with centralized pathology review.
- Stage III:Full BEP induction with post-chemotherapy retroperitoneal lymph node dissection coordination. High-volume United States tertiary centers and French academic hospitals capture case concentration.
- Advanced:Salvage chemotherapy, immunotherapy, and experimental protocols for platinum-refractory disease. Switzerland's Swissmedic and Japan's PMDA enable conditional approvals that sustain sponsor revenue recognition.
Stage I commands volume concentration; steepest expansion trajectory sits with Advanced indications.
Delivery Mode:
Volume scale separates institutional from ambulatory revenue: intravenous administration anchors hospital purchasing while oral and subcutaneous formulations enable patient-directed distribution models.
- Intravenous:Platinum compounds and cytotoxic agents requiring infusion monitoring. United States hospital outpatient departments and German day-clinic networks dominate procurement; GPO concentration in both markets compresses pricing flexibility.
- Oral:Maintenance and salvage regimens enabling direct-to-patient pharmacy distribution. United States specialty pharmacy networks bypass traditional hospital purchasing committees; Medicare Part D reimbursement structures determine access.
- Subcutaneous:Supportive care agents and select biologics. Home administration protocols expand in Netherlands and United Kingdom community settings.
- Intramuscular:Limited applications in hormonal adjuvant therapy. Prescribing concentrates in United States urology practices with in-office administration capabilities.
Intravenous holds the largest share; momentum sits with Oral formulations.
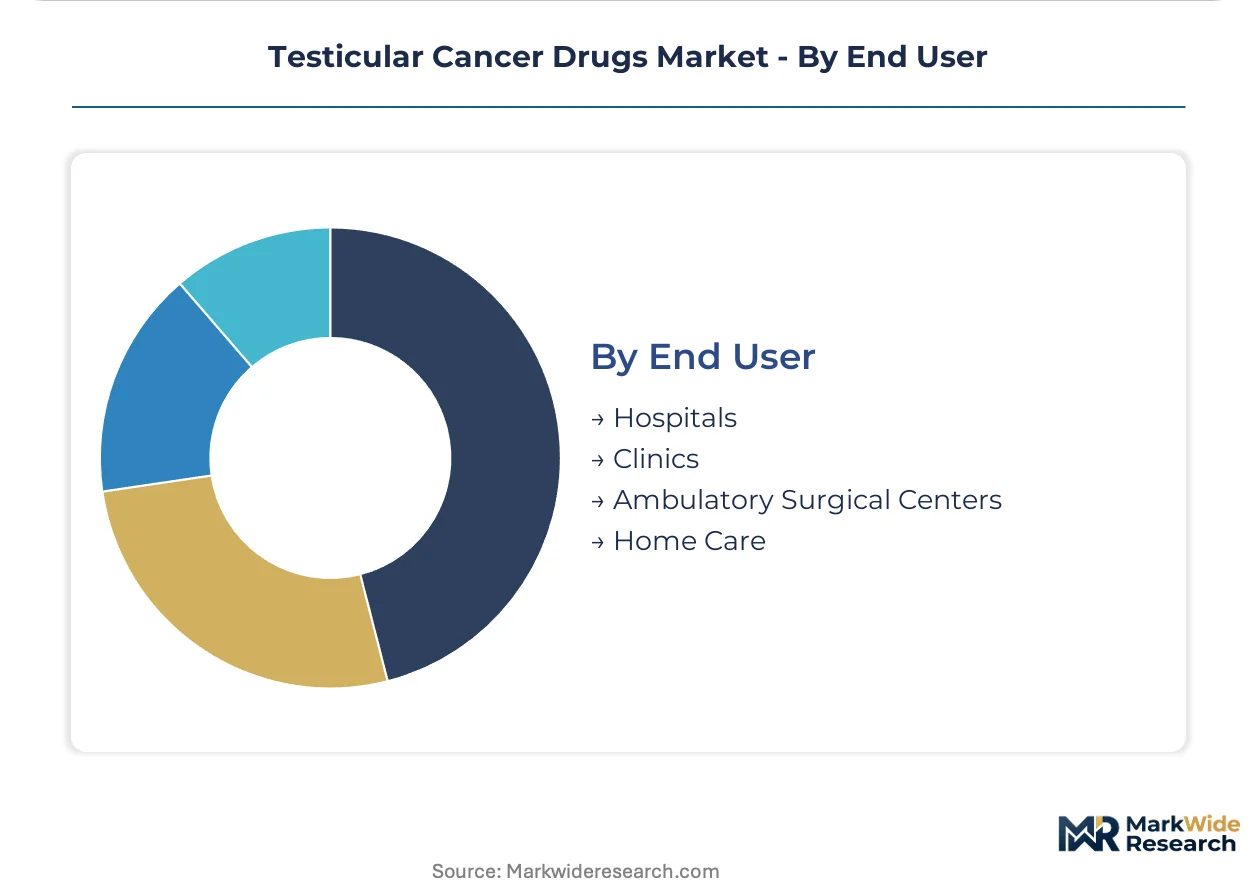
End User:
Customer type determines procurement authority: institutional purchasers command volume discounts while decentralized sites face formulary exclusion risks.
- Hospitals:Tertiary oncology departments with integrated pathology, surgery, and medical oncology. United States National Cancer Institute-designated centers and German comprehensive cancer centers anchor demand; three national GPOs control sixty percent of platinum-based chemotherapy acquisition volume.
- Clinics:Community oncology practices with medical oncology specialization. United States independent practices are losing direct purchasing autonomy as IDN membership becomes mandatory for payer contract access.
- Ambulatory Surgical Centers:Orchiectomy and diagnostic procedures with limited systemic therapy administration. Concentration in United States freestanding surgical networks with commercial payer contracts.
- Home Care:Oral maintenance and supportive care administration. Growth corridors in Netherlands home infusion networks and United Kingdom district nursing services.
Hospitals hold the largest share; gaining share fastest sits with Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across markets. United States buyers absorb premium immunotherapy pricing through established reimbursement pathways, while European procurement offices extract volume discounts for platinum-based cytotoxics. Emerging markets in Asia-Pacific face constrained access due to reference pricing arbitrage.
United States
Academic medical centers in Boston and Houston drive adoption of novel checkpoint inhibitors for platinum-refractory populations. FDA orphan drug tax credits sustain sponsor investment despite small addressable patient pools. The National Cancer Institute-designated centers in Maryland and Texas coordinate multi-site basket trials that accelerate biomarker-defined subpopulation enrollment.
Germany
University hospitals in Heidelberg and Munich anchor demand for high-volume BEP induction protocols through centralized pathology review networks. EMA's PRIME designation framework compresses regulatory timelines for germ cell therapeutics submitted through German rapporteur procedures. The Rhine-Ruhr chemical corridor hosts platinum salt API manufacturing subject to REACH authorization requirements.
Japan
PMDA conditional approval pathways enable earlier commercial access for sponsors with compelling Phase II data in salvage settings. Tokyo and Osaka metropolitan hospitals concentrate case volume for molecularly stratified protocols. METI's regenerative medicine policies accelerate CAR-T manufacturing platform adaptation toward germ cell antigen targets.
Switzerland
Swissmedic's streamlined review attracts sponsors seeking rapid European market entry for premium-priced targeted agents. Basel and Zurich academic centers participate in international basket trials aggregating rare genomic subsets. The country's high reimbursement tolerance sustains pricing power for originator compounds facing parallel trade pressure from EU neighbors.
China
NMPA accelerated review channels reshape competitive dynamics for biosimilar platinum compound filings. Shanghai and Beijing tertiary hospitals drive demand for imported originator immunotherapies despite domestic substitution pressure. The country's dual carbon goals force capital reinvestment into closed-loop recovery systems at API manufacturing sites.
Testicular Cancer Drugs Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that competes on manufacturing scale and regulatory execution speed. Large-cap biopharmaceutical developers leverage immuno-oncology infrastructure to sustain checkpoint inhibitor pipelines in refractory settings. Mid-tier generics manufacturers compete aggressively on cost-positioned formulations of standard-of-care cytotoxics. Dominant competitive moves include backward integration into platinum compound API production and strategic partnerships with academic medical centers for biomarker-guided trial enrollment.
Among established biopharmaceutical developers, Bristol-Myers Squibb Company and Pfizer Inc. occupy positions reflecting substantial investment in oncology infrastructure. Teva Pharmaceutical Industries Ltd exemplifies the cost-competitive tier with its focus on generic formulations. These three entities represent distinct strategic archetypes: integrated innovator, vertically coordinated manufacturer, and volume-driven generics supplier.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd |
| Fresenius Kabi AG |
| Sanofi |
| BioNTech SE |
| Seagen Inc. |
| AstraZeneca PLC |
| Merck & Co. Inc. |
| Others |
Cost & Logistics Intelligence
Platinum salt substitution for iridium-based catalysts in API synthesis is simultaneously shifting manufacturing geography toward German and Belgian chemical parks and compressing margin structures for oncology formulators facing REACH compliance cost escalations. This input transition concentrates pricing power among three contract manufacturers while destabilizing procurement economics for BEP regimen suppliers.
Pricing Analysis
After-sales revenue from companion diagnostic services and longitudinal patient monitoring contracts drives lifetime value capture for immunotherapy sponsors. Three-tier pricing structure across premium checkpoint inhibitors, standard platinum cytotoxics, and economy generic formulations stratifies the market. Cost compression in generic bleomycin and etoposide intensifies because of biosimilar entry pressures from Indian and Chinese manufacturers. Community oncology practices exhibit highest price sensitivity; academic medical centers with NCI designation absorb premium pricing for novel mechanisms.
Supply Chain Analysis
Rhodium co-mining economics at South African and Russian extraction sites underwrites platinum group metal volatility that ripples through cisplatin manufacturing costs. API production draws from German, Belgian, and Chinese chemical processing facilities. Single-source vulnerability concentrates in GMP-grade platinum salt purification. Distribution runs through hospital GPO networks and specialty pharmacy channels for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germ cell therapeutic development demands scarce expertise in vector manufacturing and apheresis coordination that constrains CAR-T program scale-up velocity. This capability gap separates sponsors with captive cell therapy infrastructure from dependent licensors.
For Market Incumbents: Consolidate backward integration into platinum compound API production to defend against raw material scarcity and regulatory enforcement risks at contract manufacturers. Capture formulary control authority through integrated delivery network partnerships that centralize oncology purchasing decisions. Anchor position in biomarker-guided trial enrollment through academic medical center alliances.
For New Entrants and Emerging Players: FDA orphan drug fast-track designation opens regulatory pathways for platinum-refractory indications with compressed development timelines. Target salvage therapy settings in Japan and Switzerland where conditional approval mechanisms enable earlier revenue recognition. Pursue basket trial designs aggregating rare genomic subsets across tumor types to accelerate enrollment.
For Investors and Strategic Acquirers: NMPA accelerated review channel expansion reshapes the acquisition landscape toward China-facing biosimilar sponsors with platinum compound filing expertise. Long-term viability centers on manufacturing scale and regulatory execution speed rather than pipeline depth alone. Monitor liquid biopsy adoption curves as companion diagnostic infrastructure investment signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Basket trial designs compress enrollment timelines for rare genomic subsets across NCI-designated centers. |
| Regulatory Approval Pathway | EMA PRIME designation accelerates assessment timelines for germ cell therapeutics through German rapporteur procedures. |
| Manufacturing Scale-Up | Closed-loop recovery systems at Belgian API facilities satisfy REACH authorization requirements for platinum processing. |
| Pipeline Diversification | Checkpoint inhibitor development in refractory settings leverages existing immuno-oncology infrastructure. |
| Strategic Partnership | Specialty pharmacy networks bypass hospital purchasing committees for oral maintenance regimen distribution. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value by treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from longitudinal therapy adoption curves and pricing trajectory assumptions. Forecast inputs incorporated biomarker-guided patient stratification rates and liquid biopsy surveillance protocol expansion.
Decision-makers should treat outputs as directional under stable platinum price and regulatory enforcement assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as REACH authorization timelines and NMPA review channel capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Apoptosis Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market