
 Global Metformin-Pioglitazone Market | 2026-2036
Global Metformin-Pioglitazone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metformin-Pioglitazone Market Foresight
Hospital formulary consolidation is recalibrating how combination antidiabetic therapies enter institutional procurement channels. Takeda Pharmaceutical Company Limited leverages its pioglitazone originator heritage to sustain brand loyalty among endocrinology specialists. Merck & Co., Inc. anchors its position through broad metformin manufacturing scale across multiple production sites. Sanofi competes by extending its diabetes portfolio depth beyond single-molecule offerings into fixed-dose combinations.
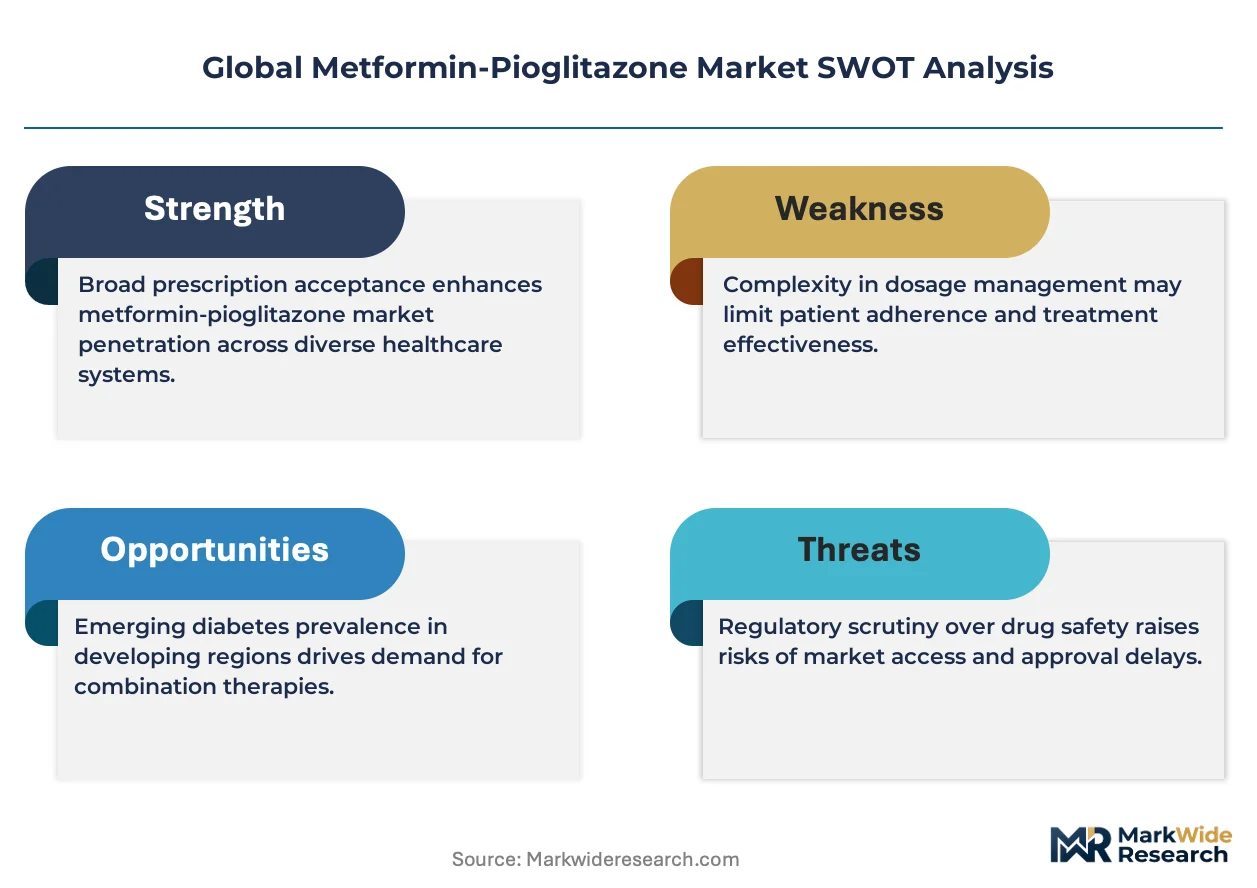
Metformin-pioglitazone combines a biguanide insulin sensitizer with a thiazolidinedione PPAR-gamma agonist in fixed-dose oral formulations, typically manufactured through wet granulation and direct compression processes to achieve dissolution profiles meeting USP monograph specifications. The therapy area dimension shows Type 2 Diabetes commanding the largest prescription volume while Polycystic Ovary Syndrome represents the fastest-expanding off-label utilization segment with distinct reimbursement dynamics. Product type segmentation reveals standard tablets occupying the dominant volume position, though Extended-Release Tablets capture disproportionate margin pools due to improved gastrointestinal tolerability profiles and patent-protected formulation technologies.
The FDA's New Drug Application pathway and EMA's centralized marketing authorization procedure govern combination therapy approvals, with both agencies requiring demonstration of bioequivalence and individual component contribution to glycemic efficacy. India's CDSCO mandates stability testing under accelerated and long-term conditions for fixed-dose combinations seeking manufacturing licenses. China's NMPA requires domestic clinical trial data for imported combination diabetes therapies. Stakeholders must monitor evolving pharmacovigilance requirements for thiazolidinedione class safety signals across multiple regulatory jurisdictions.
Market Dynamics
Hospital procurement of fixed-dose combination antidiabetic therapies is recalibrating purchasing criteria toward cost-per-HbA1c-reduction metrics, forcing manufacturers to demonstrate quantifiable clinical economic value beyond traditional efficacy endpoints.
Growth Catalysts
- Jan Aushadhi Generic Programs:India's government-subsidized pharmacy network expands fixed-dose combination access in tier-2 cities, creating volume pull-through for affordable metformin-pioglitazone formulations.
- FDA Cardiovascular Outcome Study Requirements:Tightened evidentiary standards for new diabetes drug approvals have elevated clinical evidence requirements for combination therapies, favoring established molecules with robust safety databases.
- Wet Granulation Process Optimization:Advanced manufacturing technologies reduce batch-to-batch dissolution variability, improving USP monograph compliance rates and reducing regulatory rejection risk.
Market Restraints
- Thiazolidinedione Class Safety Surveillance:Ongoing pharmacovigilance requirements for bladder cancer and cardiovascular signals impose post-market study burdens that elevate compliance costs across multiple regulatory jurisdictions.
- API Supply Concentration:Metformin active pharmaceutical ingredient production clusters in specific coastal manufacturing zones, creating geographic concentration risk for formulation-dependent supply chains.
- Sodium-Glucose Cotransporter-2 Inhibitor Substitution:SGLT2 inhibitors with demonstrated cardiovascular and renal protective outcomes are displacing pioglitazone-containing regimens in updated clinical practice guidelines.
Strategic Opportunities
- Polycystic Ovary Syndrome Off-Label Expansion:Insulin sensitization benefits in reproductive endocrinology create prescription volume growth outside traditional diabetes indications with distinct reimbursement pathways.
- Extended-Release Formulation Differentiation:Patent-protected gastrointestinal tolerability technologies command premium pricing pools as payers recognize adherence improvement value.
- China NMPA Domestic Clinical Trial Data Pathway:Localized efficacy studies for imported combination therapies unlock hospital formulary access in provincial procurement systems.
Industry Challenges
- Bioequivalence Study Execution:Demonstrating individual component contribution to glycemic efficacy requires complex factorial trial designs that extend development timelines and inflate clinical program budgets.
- Accelerated Stability Testing Infrastructure:CDSCO and EMA long-term condition requirements demand climate-controlled warehousing capacity that strains quality assurance resource allocation.
- Legacy Formulation Technology Integration:Direct compression equipment retrofits for extended-release tablet production create capital expenditure friction for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metformin-Pioglitazone Market |
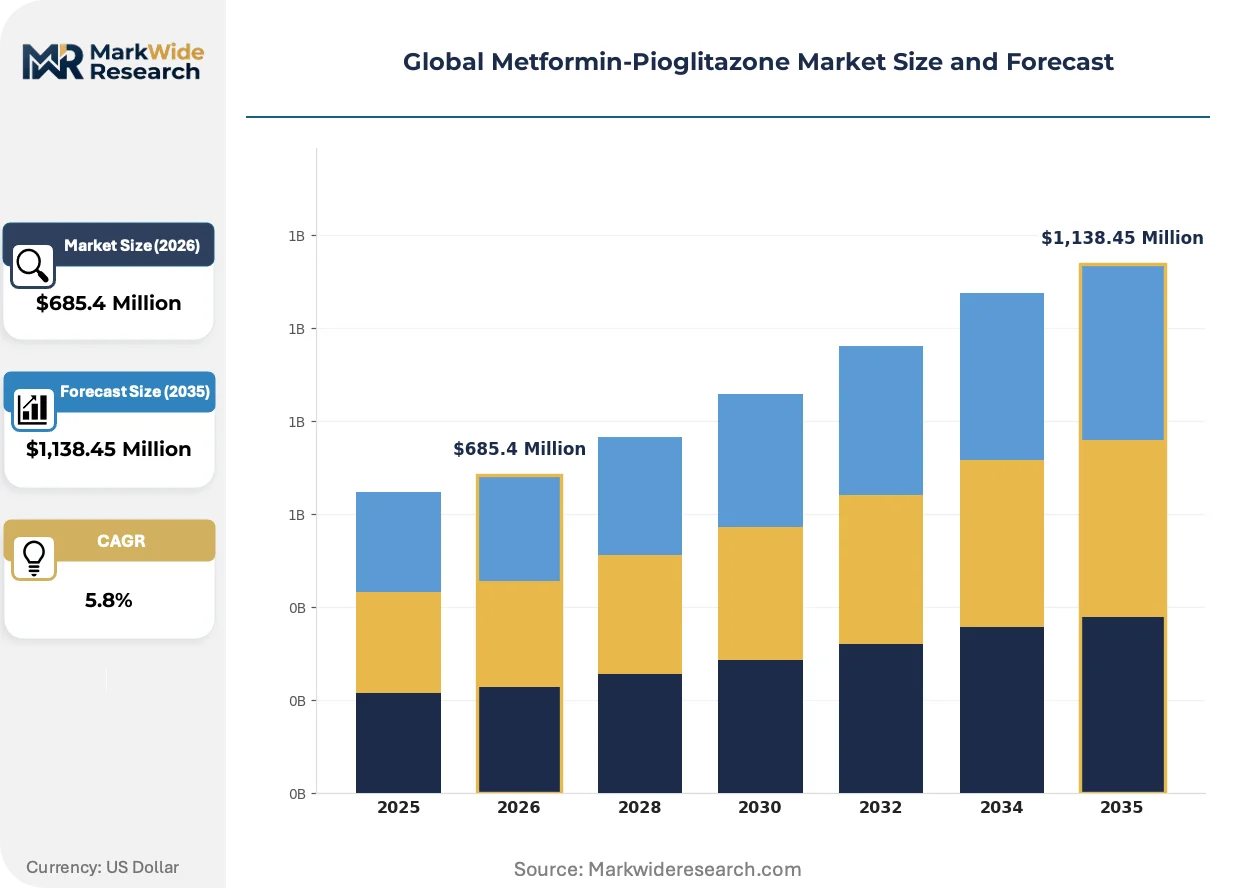
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Extended-Release Tablets, Oral Suspensions, Combination Pills Therapy Area: Type 2 Diabetes, Polycystic Ovary Syndrome, Insulin Resistance, Nonalcoholic Fatty Liver Disease End User: Diabetes Clinics, Specialty Pharmacies, General Practitioners, Academic Research Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Physician Supply |
| Companies Covered | Takeda Pharmaceutical Company Limited, Merck & Co., Inc., Bristol-Myers Squibb Company, Sanofi, Pfizer Inc., AstraZeneca plc, Eli Lilly and Company, Novartis AG, Boehringer Ingelheim GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metformin-Pioglitazone Market Shifts & Advancements
Fixed-dose combination manufacturing is advancing through process analytical technology integration and formulation science refinements that reshape competitive differentiation beyond molecule exclusivity.
Continuous manufacturing platforms for metformin-pioglitazone production are modularizing quality control into real-time release testing workflows. Contract development and manufacturing organizations in India and China adopt these systems to reduce batch cycle times from weeks to days. This technology is modularizing regulatory inspection preparedness by embedding compliance documentation into automated data capture architectures.
EMA's centralized marketing authorization procedure now mandates enhanced thiazolidinedione cardiovascular safety documentation for combination therapy renewals. Formulators must generate real-world evidence through patient registries to satisfy post-authorization commitment requirements. Extended-release tablet categories face disproportionate scrutiny due to complex pharmacokinetic profiles and higher therapeutic index sensitivity.
Hospital pharmacy committees now unbundle device and drug procurement decisions, creating separate vendor qualification tracks for formulation versus delivery technologies. Institutional buyers in Germany and France negotiate indication-specific rebates that reference HbA1c attainment thresholds rather than per-unit pricing. This behavioral shift concentrates purchasing power in integrated delivery networks that demand population health outcome guarantees from antidiabetic suppliers.
Global Metformin-Pioglitazone Market Segmentation
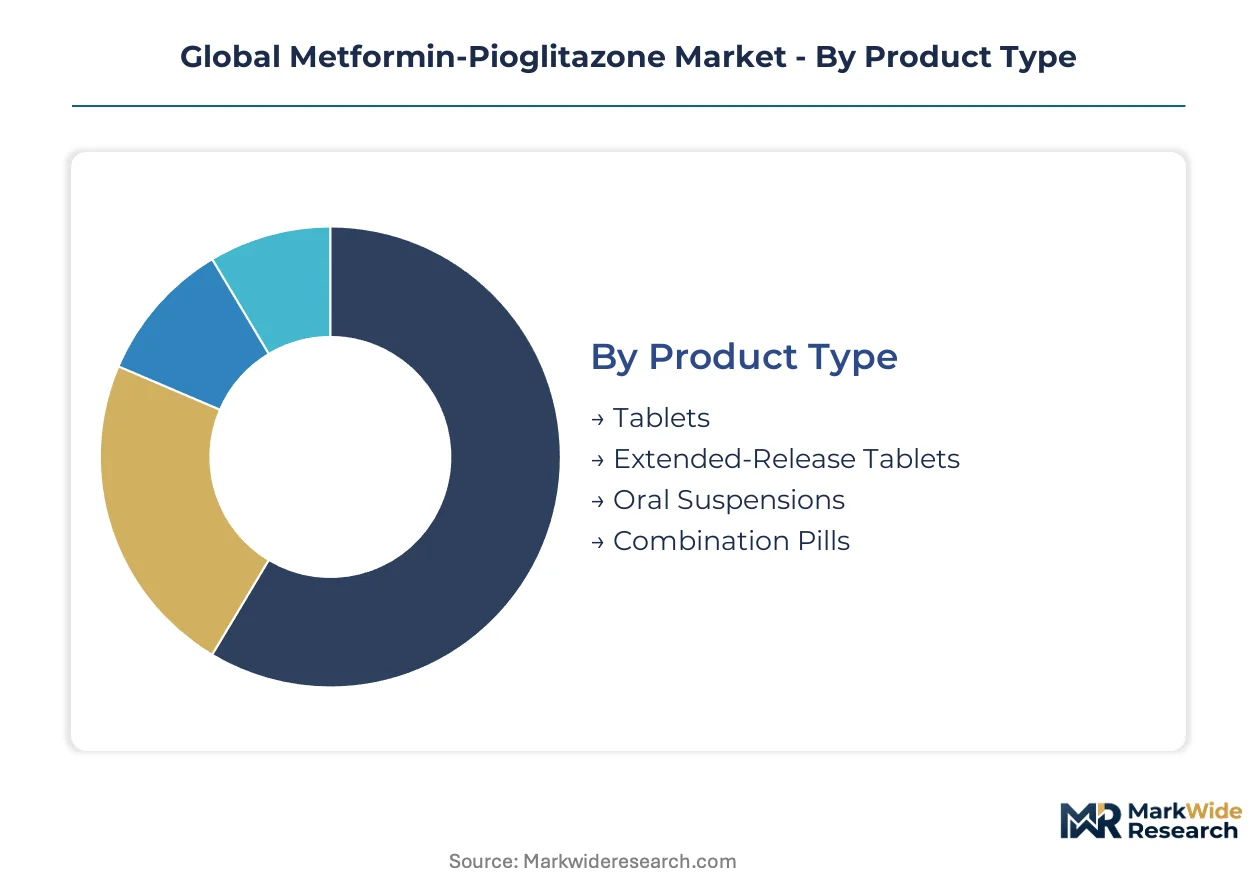
Fixed-dose combination antidiabetic therapies fragment across multiple commercial dimensions that determine pricing power, regulatory pathway complexity, and patient access dynamics. Manufacturers configure portfolio depth across these segments to balance volume scale against margin capture in institutional procurement environments.
Product Type:
Formulation technologies separate into immediate-release platforms for cost-sensitive markets versus modified-release systems that command adherence premiums through tolerability improvements.
- Tablets:Standard immediate-release formulations combine metformin and pioglitazone through wet granulation processes meeting USP dissolution specifications. Demand concentrates in India's Jan Aushadhi generic programs where government procurement tenders prioritize unit cost minimization over formulation sophistication.
- Extended-Release Tablets:Matrix-based or osmotic pump technologies modulate metformin release kinetics to reduce gastrointestinal adverse events. Hospital formularies in Germany and France negotiate indication-specific rebates for these formulations based on HbA1c attainment thresholds rather than per-unit acquisition cost.
- Oral Suspensions:Liquid dosage forms serve geriatric and dysphagia populations requiring dose titration flexibility.
- Combination Pills:Poly-pill configurations incorporating additional antidiabetic agents beyond the metformin-pioglitazone core.
Tablets lead volumes today; Extended-Release Tablets is gaining share fastest.
Therapy Area:
Clinical applications span established diabetes management through emerging metabolic syndrome indications with distinct evidentiary requirements and reimbursement codes.
- Type 2 Diabetes:The foundational indication requiring demonstration of bioequivalence and individual component contribution to glycemic efficacy under FDA and EMA guidelines. Prescription volumes concentrate in tier-2 Indian cities where fixed-dose combinations reduce pill burden for patients with limited healthcare access.
- Polycystic Ovary Syndrome:Off-label insulin sensitization applications in reproductive endocrinology create prescription growth outside traditional diabetes channels. Academic medical centers in the United States generate real-world evidence through patient registries to support reimbursement negotiations with commercial payers.
- Insulin Resistance:Prediabetes populations with elevated fasting glucose or impaired glucose tolerance.
- Nonalcoholic Fatty Liver Disease:Emerging metabolic indication with evolving clinical practice guidelines.
Type 2 Diabetes dominates current prescription flows; Polycystic Ovary Syndrome shows steepest expansion trajectory.
End User:
Provider types determine formulary access requirements, clinical evidence standards, and procurement contract structures across ambulatory and institutional settings.
- Diabetes Clinics:Specialized endocrinology practices with protocol-driven prescribing patterns and outcome measurement infrastructure. China's provincial hospital systems require domestic clinical trial data for imported combination therapies seeking formulary inclusion.
- Specialty Pharmacies:Distribution nodes with patient adherence monitoring capabilities and prior authorization management expertise. These channels concentrate in the United States where pharmacy benefit managers administer indication-specific prior authorization criteria.
- General Practitioners:Primary care gatekeepers managing initial Type 2 Diabetes diagnosis and therapy initiation.
- Academic Research Centers:Sites generating post-authorization safety data and real-world effectiveness evidence.
General Practitioners generate highest prescription volumes; Specialty Pharmacies capture fastest channel growth.
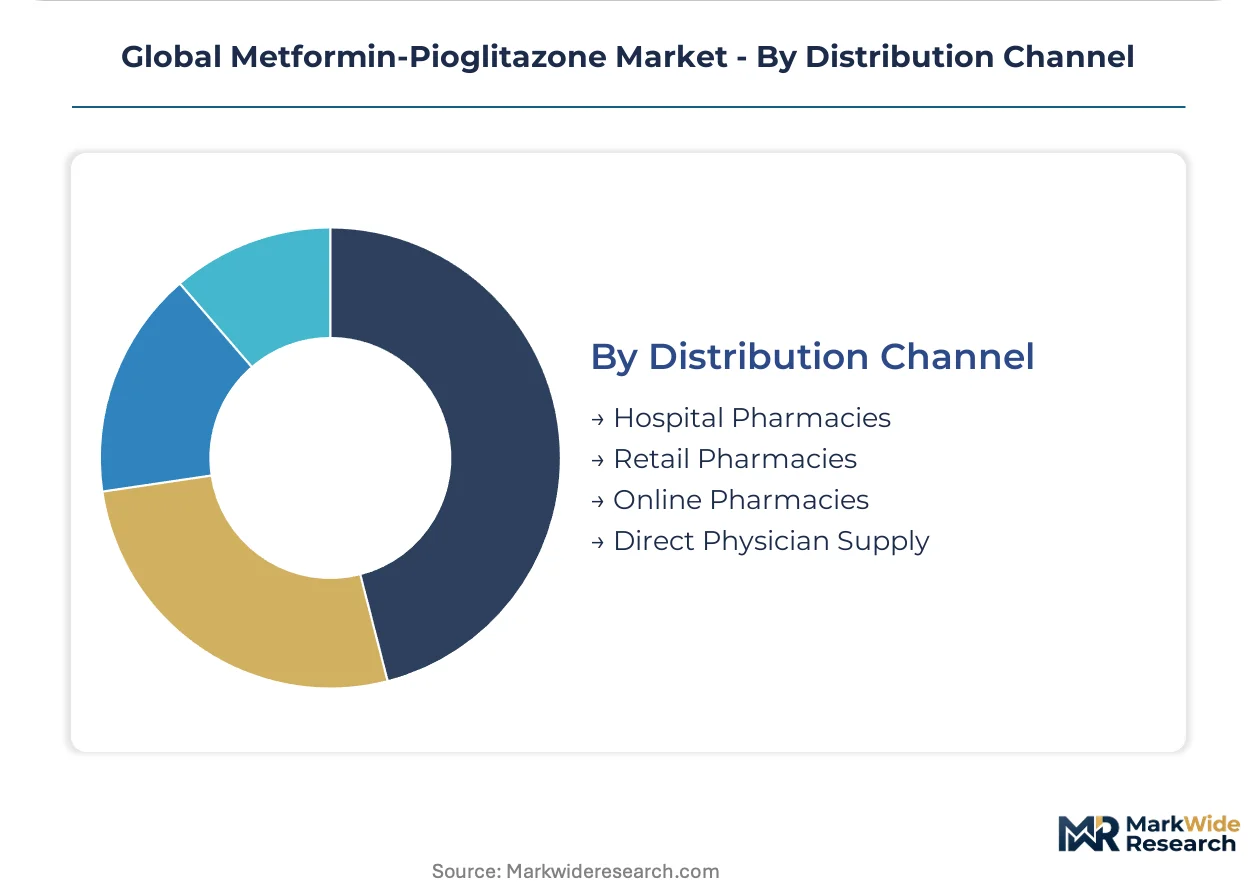
Distribution Channel:
Channel configuration reflects unbundling of drug procurement from device and delivery technology decisions in institutional purchasing environments.
- Hospital Pharmacies:Centralized procurement committees applying cost-per-HbA1c-reduction metrics rather than traditional efficacy endpoints. France's hospital federations negotiate population health outcome guarantees from antidiabetic suppliers through multi-year framework agreements.
- Retail Pharmacies:Community-based dispensing with direct patient counseling and generic substitution authority. India's retail channel fragments across branded generic and pure generic segments with divergent margin structures.
- Online Pharmacies:Digital platforms with automated prior authorization and home delivery logistics.
- Direct Physician Supply:In-office dispensing models bypassing traditional pharmacy intermediaries.
Retail Pharmacies maintain volume leadership; Online Pharmacies is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized endocrinology workforces concentrate in India's tier-2 cities and China's provincial hospital systems, anchoring prescription volume growth for fixed-dose combination therapies. Manufacturing chemists cluster in Gujarat's pharmaceutical corridors and along the Yangtze River Delta, sustaining API-to-formulation integration capabilities.
United States
Academic medical centers in Boston and Houston generate real-world evidence through patient registries to support reimbursement negotiations for off-label polycystic ovary syndrome applications. The FDA mandates enhanced cardiovascular safety documentation for thiazolidinedione combination renewals, elevating post-authorization study burdens. Formulation scientists in North Carolina's Research Triangle optimize extended-release matrix technologies to improve gastrointestinal tolerability profiles.
India
Government Jan Aushadhi generic programs expand fixed-dose combination access in tier-2 cities including Pune and Lucknow, creating volume pull-through for affordable metformin-pioglitazone formulations. The CDSCO mandates accelerated and long-term stability testing for manufacturing licenses, demanding climate-controlled warehousing capacity. API production clusters in Gujarat's Vapi and Ankleshwar industrial zones supply domestic formulation sites with metformin hydrochloride.
China
Provincial hospital procurement systems in Jiangsu and Guangdong provinces require domestic clinical trial data for imported combination therapies seeking formulary inclusion. The NMPA requires localized efficacy studies, extending development timelines for multinational manufacturers. Manufacturing scale concentrates in Taizhou's pharmaceutical industrial park, where wet granulation equipment supports batch production for regional distribution.
Germany
Hospital federations negotiate population health outcome guarantees through multi-year framework agreements referencing HbA1c attainment thresholds. The EMA's centralized marketing authorization procedure governs combination therapy approvals with bioequivalence demonstration requirements. Endocrinology specialists in Munich and Berlin sustain prescribing loyalty to established thiazolidinedione molecules with robust safety databases.
Brazil
ANVISA regulates fixed-dose combination imports through equivalence certification requirements that reference USP dissolution specifications. Retail pharmacy chains in São Paulo and Rio de Janeiro manage generic substitution authority for cost-sensitive patient populations. Distribution logistics concentrate in the São Paulo metropolitan hub, connecting import terminals to regional dispensing networks.
Global Metformin-Pioglitazone Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation technology tiers, creating a bifurcated structure where scale-driven manufacturers anchor volume positions while patent-protected extended-release specialists capture margin premiums. The vendor base separates into originator heritage holders, generic scale manufacturers, and formulation technology licensors. Consolidation pressure intensifies as hospital procurement committees unbundle device and drug decisions, favoring suppliers with integrated evidence-generation capabilities. Dominant competitive moves include strategic partnerships for real-world evidence collection and geographic expansion through localized clinical trial execution.
Within the diversified pharmaceutical conglomerate tier, Takeda Pharmaceutical Company Limited and Merck & Co., Inc. occupy positions reflecting distinct strategic anchors. Takeda exemplifies the originator heritage archetype, leveraging historical pioglitazone development experience to sustain specialist prescriber relationships. Merck represents the manufacturing scale archetype, with multiple production sites supporting broad metformin supply security. Sanofi sits within the portfolio depth category, competing through diabetes franchise extension rather than single-molecule dominance.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Sanofi |
| Pfizer Inc. |
| AstraZeneca plc |
| Eli Lilly and Company |
| Novartis AG |
| Boehringer Ingelheim GmbH |
| Others |
Supply & Pricing Matrix
Formulation-grade bifurcation between extended-release patent-protected platforms and immediate-release commodity tablets manifests divergent margin structures and sourcing configurations across the metformin-pioglitazone value chain. Premium matrix-technology formulations command adherence-linked rebates in German hospital federations while Jan Aushadhi procurement in India's tier-2 cities anchors volume at unit-cost floors, creating parallel supply chains with distinct API qualification standards and warehousing investments.
Pricing Analysis
Capacity additions in Gujarat's Vapi and Ankleshwar corridors are reshaping price floors for standard immediate-release tablets through metformin hydrochloride supply expansion. Three-tier pricing structure across premium extended-release, standard branded generic, and economy pure generic levels reflects formulation sophistication and bioequivalence certification investment. Cost compression in the economy tier intensifies as CDSCO manufacturing license requirements strain quality assurance budgets. Hospital procurement committees in France and Germany demonstrate lowest price sensitivity through outcome-based contracting, while India's retail pharmacy segments exhibit highest elasticity to per-unit acquisition cost.
Supply Chain Analysis
China's NMPA domestic clinical trial data mandates are reshaping sourcing patterns for multinational manufacturers seeking provincial hospital formulary inclusion. Metformin API production clusters in India's Gujarat coastal zones and China's Yangtze River Delta, with pioglitazone intermediate supply anchored in Taizhou's pharmaceutical industrial park. Active pharmaceutical ingredient dependence on coastal manufacturing zones creates geographic concentration risk from climate disruption and regulatory inspection backlogs. Distribution runs through hospital pharmacy committees in Germany and France, retail pharmacy chains in Brazil, and government-subsidized Jan Aushadhi networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metformin-pioglitazone market functions as a regulatory compounder where FDA cardiovascular outcome study requirements for new diabetes approvals have elevated evidentiary barriers that favor established molecules with robust safety databases.
For Market Incumbents: To counter SGLT2 inhibitor substitution in updated clinical practice guidelines, incumbents must deepen real-world evidence generation through patient registries supporting off-label polycystic ovary syndrome reimbursement negotiations. Backward integration into extended-release matrix technology capabilities protects margin pools as hospital formularies unbundle device and drug procurement decisions. CDSCO stability testing infrastructure investments in climate-controlled warehousing defend manufacturing license positions against quality assurance resource constraints. For New Entrants and Emerging Players: Contract development and manufacturing organizations in India's tier-2 cities represent the most penetrable channel partner type for volume entry through Jan Aushadhi generic program participation. White-space targets concentrate in China's provincial hospital systems where NMPA domestic clinical trial data requirements extend multinational development timelines, creating local execution partnerships as the critical go-to-market angle. Polycystic ovary syndrome off-label expansion offers distinct reimbursement pathways outside traditional diabetes indication saturation. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital procurement committees demand integrated evidence-generation capabilities alongside formulation supply security. Long-term viability over the projection horizon favors acquisition targets possessing extended-release patent-protected technologies with demonstrated gastrointestinal tolerability profiles. The signal to monitor is EMA thiazolidinedione cardiovascular safety documentation escalation for combination therapy renewals, which will accelerate post-authorization study burden differentiation between scaled and mid-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Matrix technology patents command premium pricing in German hospital outcome-based contracts. |
| Real-World Evidence Registry Establishment | Patient data platforms satisfy FDA post-authorization commitments for thiazolidinedione safety signals. |
| CDSCO Manufacturing License Expansion | Accelerated stability testing capacity unlocks Jan Aushadhi volume in India's tier-2 cities. |
| NMPA Domestic Clinical Trial Execution | Localized efficacy studies enable provincial hospital formulary inclusion in Jiangsu and Guangdong. |
| Continuous Manufacturing Platform Adoption | Process analytical technology integration reduces batch cycle times from weeks to days for CDMO competitiveness. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads at multinational manufacturers, hospital procurement managers in Germany and France, and payer access specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA New Drug Application filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and Indian CDSCO manufacturing license databases. Bottom-up prescription volume modeling across formulation types and therapy areas triangulated against top-down market value estimates from customs and trade flow analysis.
Bottom-up demand modeling segmented the market by product type, therapy area, end user archetype, and distribution channel across the analysis window. CAGRs derived from polynomial trend fitting to historical prescription volume trajectories, adjusted for regulatory event impacts including FDA cardiovascular outcome study requirement implementation. Forecast inputs incorporated wet granulation process yield improvements, extended-release formulation adoption curves, and Jan Aushadhi program expansion rates in Indian tier-2 cities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SGLT2 inhibitor guideline displacement, thiazolidinedione class safety signal emergence, and API supply concentration disruption. Forecasts reflect documented assumptions regarding regulatory pathway stability and hospital procurement metric persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Neurotrophins Market