
 Muscular Dystrophy Drugs Market | 2026-2036
Muscular Dystrophy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Muscular Dystrophy Drugs Market Foresight
Aftermarket service revenue from patient monitoring and long-term efficacy tracking is tilting toward gene therapy developers. Sarepta Therapeutics, Inc. leverages its antisense oligonucleotide platform to sustain leadership in Duchenne muscular dystrophy. PTC Therapeutics, Inc. anchors its position through oral small-molecule development for nonsense mutation patients. FibroGen, Inc. competes with connective tissue modulation approaches that differentiate its pipeline from genetic intervention rivals.
Muscular dystrophy drugs comprise pharmacological agents designed to modify disease progression, restore protein function, or compensate for genetic deficits in skeletal muscle integrity; these formulations range from corticosteroid anti-inflammatories to viral-vector gene deliveries requiring cold-chain handling and specialized infusion protocols. Their primary purpose centers on delaying ambulatory loss, preserving respiratory function, and reducing cardiomyopathy risk in progressive neuromuscular degeneration. Corticosteroids retain the largest installed base due to decades of clinical familiarity and generic availability, while antisense oligonucleotides command premium positioning through mutation-specific targeting. Gene therapy represents the fastest-expanding development frontier, though manufacturing complexity and durable expression questions concentrate margin pools in contract development organizations rather than finished dose producers alone.
The FDA's accelerated approval framework and orphan drug exclusivity provisions shape investment prioritization and trial design for developers seeking U.S. market access. EMA's Committee for Orphan Medicinal Products and the EU's pharmaceutical legislation revision exert parallel influence on European commercialization pathways and pricing negotiations. Stakeholders must monitor evolving payer evidence requirements for one-time gene therapies versus chronic administration models, as reimbursement mechanics will determine which therapeutic modalities achieve scalable adoption without access restrictions.
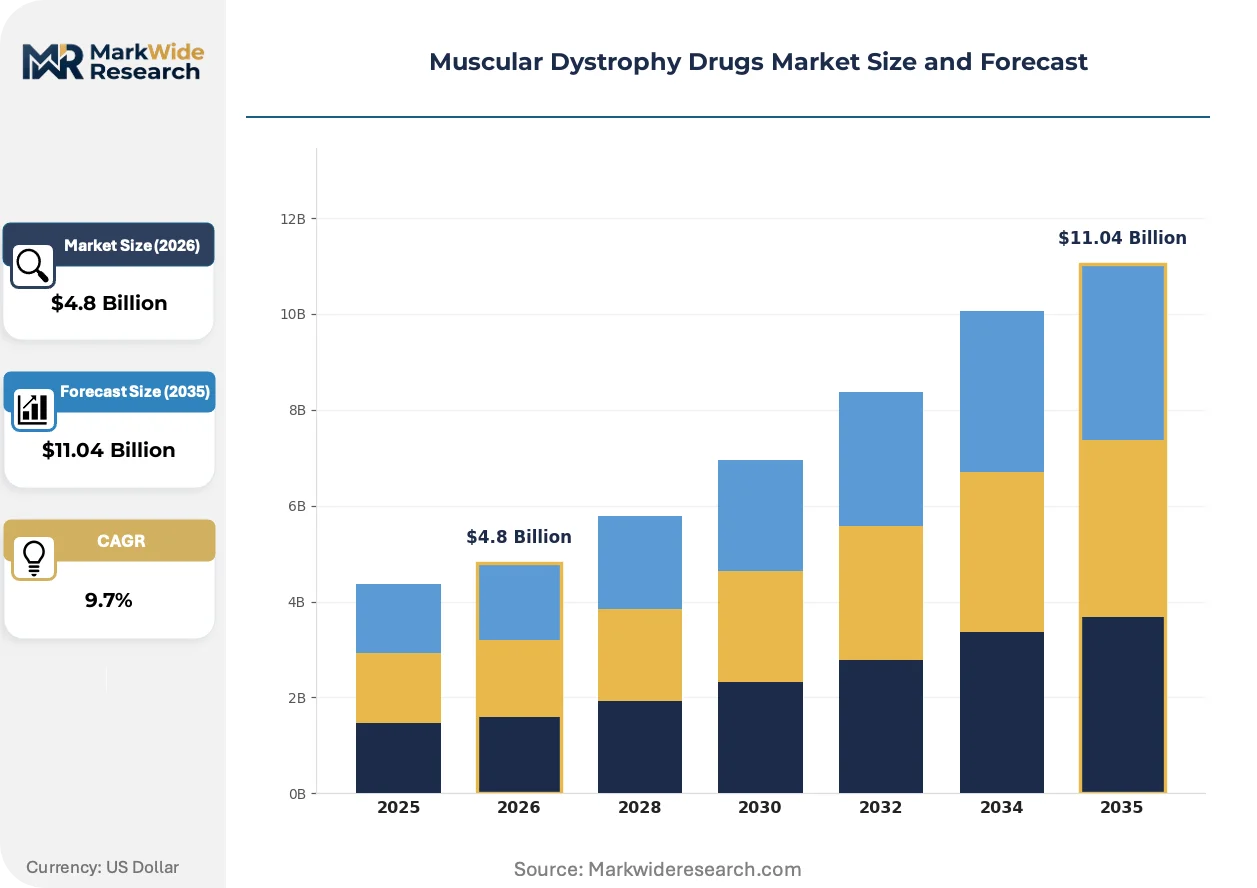
Market Dynamics
Gene therapy manufacturing bottlenecks are compressing commercial timelines as developers race to secure viral vector capacity ahead of regulatory submissions. Cold-chain infrastructure scarcity and specialized infusion center density now determine which patient populations gain access to one-time treatments.
Growth Catalysts
- FDA Accelerated Approval Pathway:Orphan drug designation combined with surrogate endpoint acceptance compresses Phase II-to-approval timelines for mutation-specific therapies. Developers leverage this framework to reach Duchenne and Becker subpopulations faster than conventional neurology indications permit.
- Antisense Oligonucleotide Platform Maturation:Chemistry modifications enabling subcutaneous administration expand prescriber adoption beyond academic medical centers into community neurology practices.
- Pediatric Treatment Center Concentration:The United States hosts over forty specialized neuromuscular clinics with dedicated gene therapy infusion suites, creating concentrated demand pools that justify manufacturing scale-up investments.
Market Restraints
- Viral Vector Supply Concentration:AAV manufacturing capacity concentrates among three contract development organizations in the United States and Europe, creating multi-year waitlists that delay trial initiations.
- Reimbursement Uncertainty for One-Time Therapies:CMS and commercial payers lack established frameworks for amortizing multi-million dollar gene therapy costs across patient lifetimes, triggering access restrictions.
- Corticosteroid Generic Substitution:Prednisone and deflazacort commoditization displaces branded chronic therapy revenue pools, compressing funding available for novel mechanism development.
Strategic Opportunities
- India's Emerging Regulatory Framework:CDSCO orphan drug provisions under revision create first-mover positioning for developers establishing local clinical trial infrastructure ahead of formal pathway finalization.
- Cardiomyopathy Indication Expansion:Skeletal muscle-focused developers pivot toward heart failure prevention endpoints, accessing cardiology reimbursement codes with broader coverage than neurology carve-outs.
- Real-World Evidence Collection Infrastructure:Patient registries maintained by European reference networks satisfy EMA post-authorization requirements while generating differentiation data for HTA submissions.
Industry Challenges
- Gene Therapy Manufacturing Workforce Scarcity:Viral vector production requires GMP bioprocessing specialists with cell culture and downstream purification expertise that outstrips current training program output.
- Long-Term Expression Monitoring Complexity:Durable protein restoration claims require decade-long patient follow-up that strains clinical operations budgets and informed consent frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muscular Dystrophy Drugs Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Antisense Oligonucleotides, Gene Therapy, Enzyme Replacement Therapy Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Homecare Settings, Research Institutions Therapy Area: Duchenne Muscular Dystrophy, Becker Muscular Dystrophy, Limb-Girdle Muscular Dystrophy, Congenital Muscular Dystrophy |
| Companies Covered | Sarepta Therapeutics, Inc., PTC Therapeutics, Inc., Santhera Pharmaceuticals, NS Pharma, Inc., Italfarmaco S.p.A., FibroGen, Inc., Capricor Therapeutics, Inc., Catalyst Pharmaceuticals, Inc., Solid Biosciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muscular Dystrophy Drugs Market Shifts & Advancements
Digital biomarker integration and decentralized trial models are compressing evidence generation timelines while reshaping how developers demonstrate functional preservation. These shifts alter competitive positioning beyond molecule differentiation alone.
Micro-dystrophin gene delivery via recombinant AAV9 vectors is virtualizing the traditional clinical endpoint framework. Pediatric neurology clinics in the United States are adopting wearable accelerometry and video-based movement analysis to supplement six-minute walk tests. This virtualization compresses placebo-controlled trial durations while enabling continuous efficacy monitoring that supports accelerated approval submissions.
EMA's revision of pharmaceutical legislation introduces adaptive pathways and post-authorization evidence generation requirements that reshape European commercialization timelines. Developers must now pre-negotiate registry participation and real-world data collection protocols prior to CHMP opinion. Duchenne-focused gene therapy sponsors face heightened evidentiary burdens as HTA bodies demand direct comparative effectiveness data against established exon-skipping standards.
Patient advocacy organizations are consolidating procurement influence through centralized referral network certification. Parent-led foundations in the United States now maintain approved treatment center directories that steer families toward sites with gene therapy administration capability. This concentration shifts prescribing authority from individual neurologists toward institution-level contracts that bundle infusion services with long-term monitoring commitments.
Muscular Dystrophy Drugs Market Segmentation
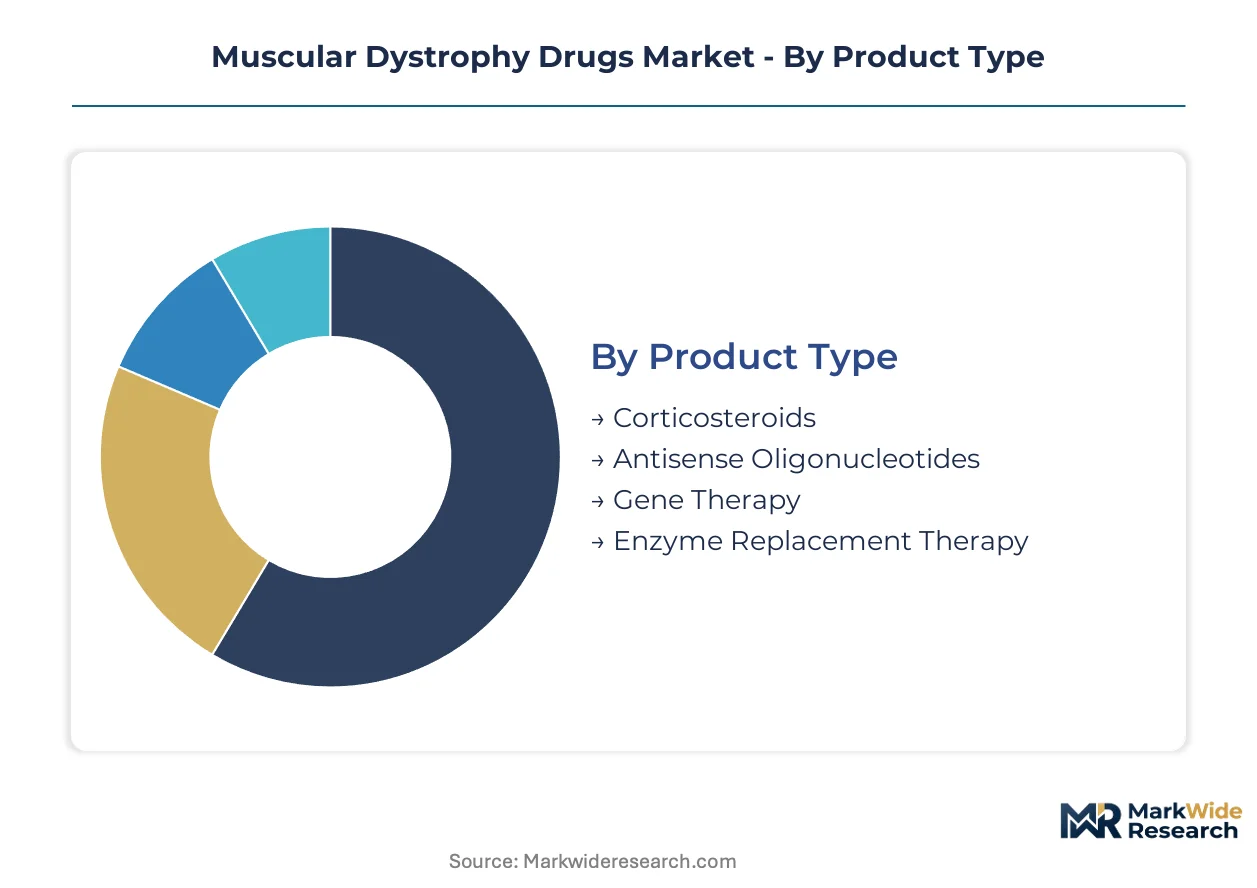
Muscular dystrophy drug segmentation reveals divergent margin structures across therapeutic modalities. Corticosteroid commoditization contrasts sharply with gene therapy premium positioning, while delivery infrastructure constraints reshape end-user channel economics.
Product Type:
Cost tier stratification separates chronic administration generics from one-time curative interventions with million-dollar price points.
- Corticosteroids:Prednisone and deflazacort formulations constitute the foundational anti-inflammatory standard with decades of clinical familiarity. Demand concentrates in Medicaid and commercial insurance plans prioritizing cost containment over mechanism novelty, though generic substitution compresses branded revenue pools.
- Antisense Oligonucleotides:Splice-switching chemistry enables exon-skipping for mutation-specific subpopulations, delivered via subcutaneous or intrathecal routes. United States academic medical centers drive adoption, with FDA accelerated approval pathways supporting premium positioning against corticosteroid baselines.
- Gene Therapy:AAV-vector micro-dystrophin delivery targets one-time functional correction. Manufacturing bottlenecks and cold-chain complexity restrict access to specialized infusion centers.
- Enzyme Replacement Therapy:Intravenous enzyme supplementation addresses metabolic deficiencies in select congenital subtypes. Limited patient populations constrain commercial scale.
Corticosteroids hold installed capacity. Gene therapy is rotating up the share rankings.
Delivery Mode:
Application setting determines reimbursement coding and patient compliance trajectories across neuromuscular care pathways.
- Oral:Corticosteroid tablets dominate pediatric adherence profiles with home-based administration eliminating infusion center dependency. Community neurology practices in the United States prescribe oral regimens as first-line maintenance, though chronic steroid exposure drives bone density and weight gain monitoring requirements.
- Injectable:Subcutaneous antisense oligonucleotide administration expands prescriber base beyond academic centers into regional neurology clinics. Parent-led advocacy networks prioritize home injection training to reduce treatment burden, creating demand for nursing support services.
- Intravenous:Gene therapy and enzyme replacement require hospital-based infusion suites with cardiac monitoring capability. Site certification programs concentrate eligible patients at United States pediatric neuromuscular centers.
- Transdermal:Patch-based delivery remains developmental for corticosteroid alternatives, targeting adolescent compliance improvement through reduced dosing frequency.
Oral formulations hold installed capacity. Injectable administration is rotating up the share rankings.
End User:
Customer type segmentation maps to reimbursement complexity and monitoring infrastructure requirements.
- Hospitals:Tertiary academic centers host gene therapy infusion suites and multidisciplinary neuromuscular teams. United States children's hospitals anchor regional referral networks with cardiac MRI and pulmonary function testing co-located.
- Clinics:Community neurology practices manage corticosteroid maintenance and antisense injection protocols. Medicare Part B billing codes shape site-of-service economics for injectable therapies.
- Homecare Settings:Nursing-supported subcutaneous administration reduces family travel burden for exon-skipping regimens. Home health reimbursement varies across United States state Medicaid programs.
- Research Institutions:Clinical trial sites generate natural history data supporting regulatory submissions. European reference networks maintain patient registries satisfying EMA post-authorization requirements.
Hospitals hold installed capacity. Homecare settings are rotating up the share rankings.
Therapy Area:
Geography of genetic prevalence and mutation spectrum concentration shapes developer pipeline prioritization.
- Duchenne Muscular Dystrophy:X-linked recessive deletion mutations affecting dystrophin production represent the largest addressable population. United States and European treatment centers concentrate clinical trial infrastructure, with FDA and EMA orphan designations accelerating development timelines.
- Becker Muscular Dystrophy:Milder dystrophin-deficient phenotype with later onset preserves ambulation longer. Cardiomyopathy endpoints attract cardiology reimbursement codes distinct from neurology carve-outs.
- Limb-Girdle Muscular Dystrophy:Heterogeneous autosomal recessive and dominant subtypes fragment clinical trial design. European neuromuscular reference networks aggregate rare subtype populations for registry-based evidence generation.
- Congenital Muscular Dystrophy:Early-onset collagen VI and laminin deficiencies require respiratory support prioritization. Ultra-rare prevalence limits commercial incentive for targeted therapy development.
Duchenne muscular dystrophy holds installed capacity. Limb-girdle muscular dystrophy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for muscular dystrophy therapies varies sharply across markets. United States buyers demonstrate limited price sensitivity due to orphan drug reimbursement carve-outs, while European purchasers enforce rigid cost-effectiveness thresholds that compress gene therapy adoption timelines.
United States
Specialized pediatric neuromuscular clinics in Boston, Philadelphia, and Cincinnati anchor domestic demand concentration. FDA accelerated approval pathways compress Phase II-to-launch timelines for mutation-specific therapies. The National Institutes of Health funds natural history studies at forty-plus academic medical centers, generating regulatory-grade evidence for surrogate endpoint validation.
Germany
European reference networks aggregate rare disease populations across federal states, enabling registry-based post-authorization studies. The Federal Joint Committee applies early benefit assessment frameworks that demand direct comparative effectiveness data against corticosteroid baselines. Munich and Heidelberg host GMP viral vector manufacturing facilities serving EMA-submission-bound developers.
United Kingdom
NHS England's specialized commissioning frameworks concentrate gene therapy access at designated treatment centers in London, Manchester, and Newcastle. The National Institute for Health and Care Excellence evaluates one-time therapies through modified cost-per-QALY thresholds acknowledging lifetime horizon benefits. Patient advocacy organizations maintain referral network directories steering families toward certified infusion sites.
Japan
PMDA's Sakigake designation system grants priority review to Duchenne-focused gene therapies, compressing regulatory timelines relative to standard neurology indications. Tokyo and Osaka academic hospitals host multicenter registry infrastructure satisfying post-marketing surveillance requirements. The Ministry of Health, Labour and Welfare's rare disease reimbursement lists provide predictable access pathways for antisense oligonucleotide maintenance therapies.
India
CDSCO orphan drug provisions under revision create regulatory uncertainty that delays multinational trial initiations. Hyderabad and Bengaluru contract research organizations build natural history cohorts for limb-girdle subtypes prevalent in South Asian populations. State-level rare disease policies in Karnataka and Tamil Nadu pilot cashless treatment schemes for corticosteroid-dependent patients.
Muscular Dystrophy Drugs Market Competitive Landscape
Capability concentration sits with gene therapy developers commanding viral vector manufacturing partnerships; scale advantage sits with corticosteroid incumbents distributing through generic channels. The market structures around three tiers: antisense platform specialists, AAV-vector gene therapy sponsors, and connective tissue modulation researchers. Dominant competitive moves include strategic partnerships securing CDMO capacity and portfolio diversification into cardiomyopathy indications.
Within the antisense platform tier, Sarepta Therapeutics, Inc. and NS Pharma, Inc. occupy positions defined by exon-skipping chemistry maturation. PTC Therapeutics, Inc. anchors the oral small-molecule segment addressing nonsense mutation subpopulations. FibroGen, Inc. represents connective tissue modulation approaches that differentiate from genetic intervention rivals. These three archetypes illustrate how mechanism diversity fragments competitive dynamics beyond simple molecule rivalry.
| Leading Market Players |
|---|
| Sarepta Therapeutics, Inc. |
| PTC Therapeutics, Inc. |
| Santhera Pharmaceuticals |
| NS Pharma, Inc. |
| Italfarmaco S.p.A. |
| FibroGen, Inc. |
| Capricor Therapeutics, Inc. |
| Catalyst Pharmaceuticals, Inc. |
| Solid Biosciences Inc. |
| Others |
Supply & Pricing Matrix
Trans-Atlantic cold-chain freight corridors connecting viral vector manufacturing sites in Germany and Massachusetts to infusion centers in Pennsylvania and Ohio impose per-dose logistics costs that stratify patient access. These transportation economics concentrate gene therapy pricing power among developers with captive CDMO relationships while forcing corticosteroid producers toward commodity margin structures.
Pricing Analysis
Aftermarket service revenue from patient monitoring contracts and long-term efficacy registries now drives lifetime value for gene therapy developers. Three-tier pricing structure across premium mutation-specific interventions, mid-tier exon-skipping maintenance, and economy corticosteroid baselines reflects divergent value demonstration requirements. Pricing pressure stems from Medicaid formulary restrictions on one-time therapies exceeding traditional cost-effectiveness thresholds. Community neurology practices exhibit highest price sensitivity due to fixed reimbursement codes, while academic medical centers with dedicated infusion suites demonstrate lowest sensitivity due to bundled service contracts.
Supply Chain Analysis
Upstream plasmid DNA and cell culture media production concentrates in the United States, Germany, and South Korea, with viral vector finishing capacity tethered to GMP-certified facilities near major regulatory submission clusters. AAV capsid components, specialized bioreactor systems, and cold-chain packaging materials constitute critical input dependencies. Single-source vulnerability pervades AAV manufacturing due to three-dominant-CDMO concentration. Distribution runs through hospital-based specialty pharmacy channels with site-of-care billing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Muscular dystrophy therapeutics fragmentation creates positioning openings as mutation-specific demand splinters across exon-skipping, gene replacement, and cardiomyopathy prevention niches.
For Market Incumbents: Harden antisense platform moats through subcutaneous formulation patents that delay biosimilar entry. Secure multi-year viral vector manufacturing reservations at CDMOs in Massachusetts and North Carolina to outflank pipeline-stage competitors facing capacity waitlists. Corticosteroid incumbents must backward integrate into active pharmaceutical ingredient production to defend against Indian and Chinese generic substitution. For New Entrants and Emerging Players: Build out Becker muscular dystrophy cardiomyopathy indications to access cardiology reimbursement codes with broader coverage than neurology carve-outs. Limb-girdle subtypes in South Asian populations offer penetrable trial populations through Hyderabad and Bengaluru clinical research organization partnerships. Homecare injection training services provide differentiated go-to-market positioning against hospital-dependent gene therapy rivals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors antisense platform specialists with validated exon-skipping chemistry over pre-clinical gene therapy sponsors facing manufacturing scale-up uncertainty. Long-term viability hinges on durable expression data across decade-long horizons. Watch FDA advisory committee outcomes for micro-dystrophin therapies as inflection indicators for gene therapy capital allocation confidence.| Strategic Initiative | Industry Significance |
|---|---|
| CDMO Capacity Reservation | Multi-year viral vector manufacturing contracts at Massachusetts facilities secure launch timelines ahead of regulatory submission. |
| Cardiomyopathy Endpoint Expansion | Heart failure prevention trials unlock cardiology reimbursement codes with broader payer coverage than neurology indications. |
| Subcutaneous Formulation Development | Injection route migration from intravenous expands prescriber base into community neurology practices beyond academic centers. |
| Real-World Evidence Registry Participation | European reference network data collection satisfies EMA post-authorization requirements while generating HTA differentiation. |
| Patient Advocacy Network Certification | Foundation-approved treatment center directories steer family referrals toward sites with gene therapy administration capability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA CHMP opinions, ClinicalTrials.gov protocols, and CMS national coverage determinations. Drug development executives, regulatory affairs leads at gene therapy sponsors, formulary directors at national payers, and hospital procurement managers at pediatric neuromuscular centers contributed qualitative inputs. Bottom-up patient population sizing triangulates against top-down pharmaceutical revenue estimates across therapeutic modality segments.
Forecast inputs include regulatory approval probability assessments, manufacturing capacity expansion timelines, and payer access restriction scenarios across the projection horizon. Segmentation dimensions encompass treatment line, administration route, mutation specificity, and regional regulatory cluster. CAGRs derive from patient population epidemiology, pricing trajectory assumptions, and therapy penetration curves. Viral vector production yield improvements and corticosteroid generic substitution rates constitute industry-specific forecast variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-positioned gene therapy sponsors to acquire CDMO capacity would shift outcomes. Gene therapy durability failures, FDA advisory committee negative votes, or CMS national non-coverage determinations for one-time therapies constitute primary revision risks. Cross-checking against IQVIA prescription data and Symphony Health patient flow analytics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
CMO and CDMO Biotechnology Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
AI in Pharma and Biotech Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Testicular Cancer Drugs Market