
 Alport Syndrome Market | 2026-2036
Alport Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Alport Syndrome Market Analysis
Rare disease venture philanthropy and milestone-based partnership financing is reshaping how biotech firms fund Alport Syndrome programs through clinical development. Reata Pharmaceuticals leverages its oxidative stress modulation platform to sustain a differentiated position in progressive kidney disease. Novartis anchors broad nephrology capabilities that extend across multiple genetic renal indications. Calliditas Therapeutics competes through specialty commercial infrastructure in orphan and rare disease markets.
Alport Syndrome constitutes a hereditary glomerulonephritis driven by mutations in type IV collagen genes (COL4A3, COL4A4, COL4A5), producing progressive basement membrane defects that advance from microscopic hematuria to end-stage renal disease. Therapeutics development concentrates on anti-inflammatory and anti-fibrotic mechanisms targeting the underlying collagenopathy pathology. Genetic Testing using next-generation sequencing occupies the highest-margin segment as definitive diagnosis replaces presumptive clinical criteria. Diagnostic Tests through biomarker panels represent the fastest-growing category as proteinuria quantification and renal function staging demand precision tools for trial enrollment and treatment monitoring.
FDA orphan drug designations and EMA rare disease incentives shape development economics by granting market exclusivity and protocol assistance for Alport Syndrome candidates. ISO 15189 accreditation requirements for genetic testing laboratories influence quality standards across diagnostic service providers in Europe and North America. Stakeholders must weigh gene therapy platform investments against small-molecule progression risks as clinical data matures across competing mechanistic approaches.
Market Dynamics
Gene therapy platforms targeting COL4A3, COL4A4, and COL4A5 mutations are compressing development timelines and forcing established anti-fibrotic programs to demonstrate superior renal function preservation endpoints.
Growth Catalysts
- Orphan drug incentives:FDA's seven-year market exclusivity and EMA's protocol assistance programs accelerate Alport Syndrome therapeutic candidates through clinical phases.
- Next-generation sequencing adoption:Nephrology clinics in the United States, Germany, and Japan deploy comprehensive genetic panels to replace presumptive diagnostic criteria.
- Specialist renal care networks:Concentrated referral pathways in mature healthcare systems enable rapid enrollment for interventional trials and post-market surveillance.
Market Restraints
- Gene therapy manufacturing complexity:AAV vector production bottlenecks and cold-chain distribution requirements constrain supply scalability.
- Reimbursement uncertainty:Payers in Germany and Japan apply stringent cost-effectiveness thresholds to one-time curative interventions.
- Diagnostic access inequality:Genetic testing penetration remains limited outside the United States, Germany, and Japan due to fragmented laboratory infrastructure.
Strategic Opportunities
- Biomarker-driven trial enrollment:Proteinuria quantification and renal function staging tools enable precision patient selection for mechanistic studies.
- Patient monitoring applications:Digital health platforms for early intervention protocols create recurring revenue streams alongside acute therapeutics.
- EMA rare disease incentives:European centralized marketing authorization and pediatric investigation plans reduce regulatory duplication costs.
Industry Challenges
- Gene therapy talent scarcity:Clinical development teams with rare disease and nephrology expertise command premium compensation.
- ISO 15189 compliance timelines:Genetic testing laboratories face extended accreditation processes affecting service launch schedules.
- Platform investment allocation:Biotech firms must balance gene therapy capital deployment against small-molecule progression risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alport Syndrome Market |
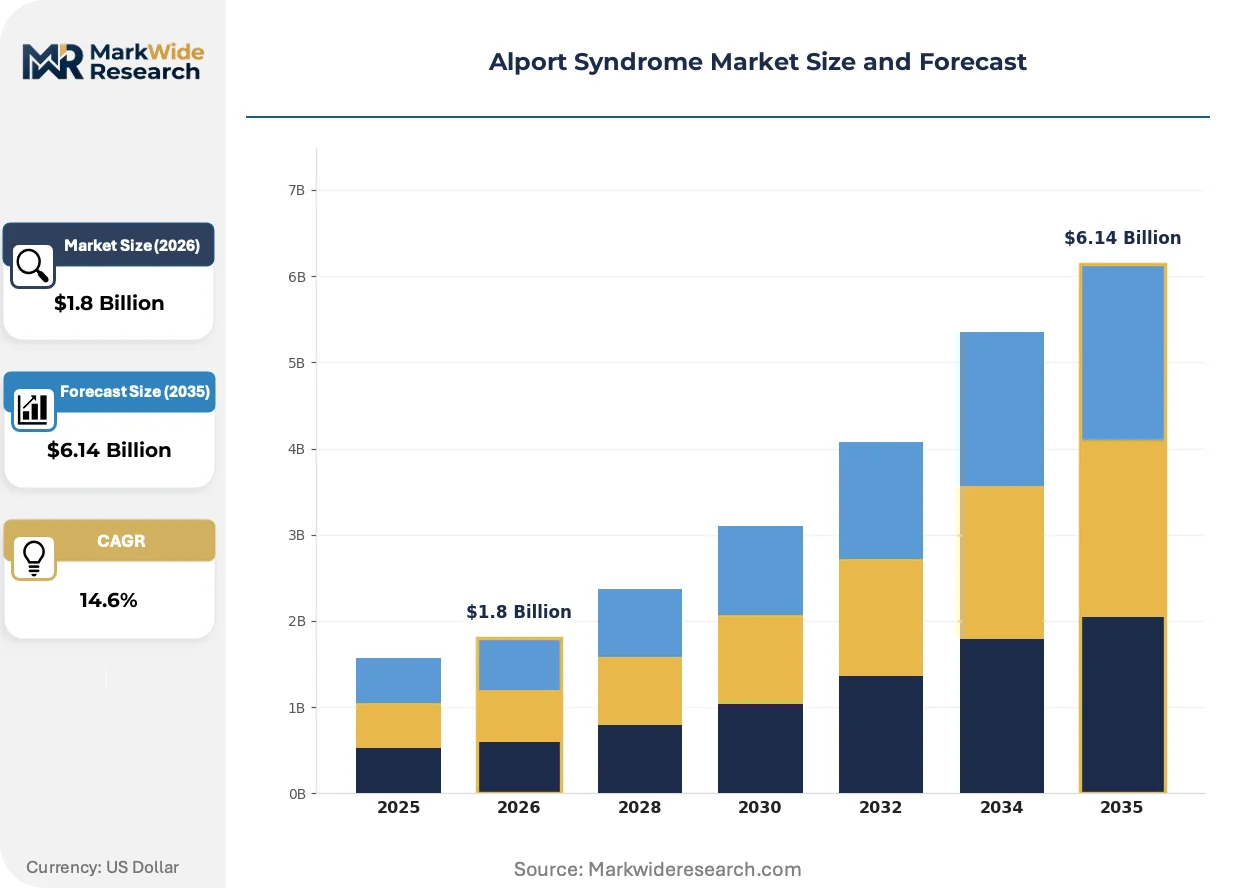
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutics, Genetic Testing, Biomarkers Application: Clinical Research, Patient Monitoring, Early Detection, Treatment Management End User: Hospitals, Research Laboratories, Diagnostic Centers, Clinics Technology: Next-Generation Sequencing, CRISPR, ELISA, Mass Spectrometry |
| Companies Covered | Reata Pharmaceuticals, Calliditas Therapeutics, Eloxx Pharmaceuticals, Novartis, River 3 Renal Corp, Chinook Therapeutics, Bayer, Fresenius Medical Care, Travere Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alport Syndrome Market Emerging Trajectories
Mechanistic convergence between anti-inflammatory small molecules and genetic interventions is redefining competitive positioning in progressive kidney disease therapeutics.
AAV-mediated gene delivery to renal podocytes is rendering obsolete chronic immunosuppression protocols for COL4A5 mutation carriers. Pediatric nephrology centers in the United States and Germany are prioritizing these candidates for early-phase enrollment. The shift is compressing development timelines for anti-fibrotic small molecules lacking disease-modifying claims.
EMA's rare disease incentives and FDA's orphan drug designation pathways are harmonizing protocol standards across transatlantic trials. Sponsors now design single global studies satisfying both regulators' evidentiary requirements. Small-cap biotech firms lacking European regulatory expertise are partnering with established nephrology players to navigate EMA scientific advice procedures.
Nephrology clinics are consolidating procurement around integrated diagnostic-therapeutic platforms rather than discrete testing services. Academic medical centers in Japan and Germany now contract for longitudinal patient monitoring bundled with genetic counseling. This unbundling of traditional reference laboratory relationships favors vendors with captive therapeutic pipelines.
Alport Syndrome Market Segmentation
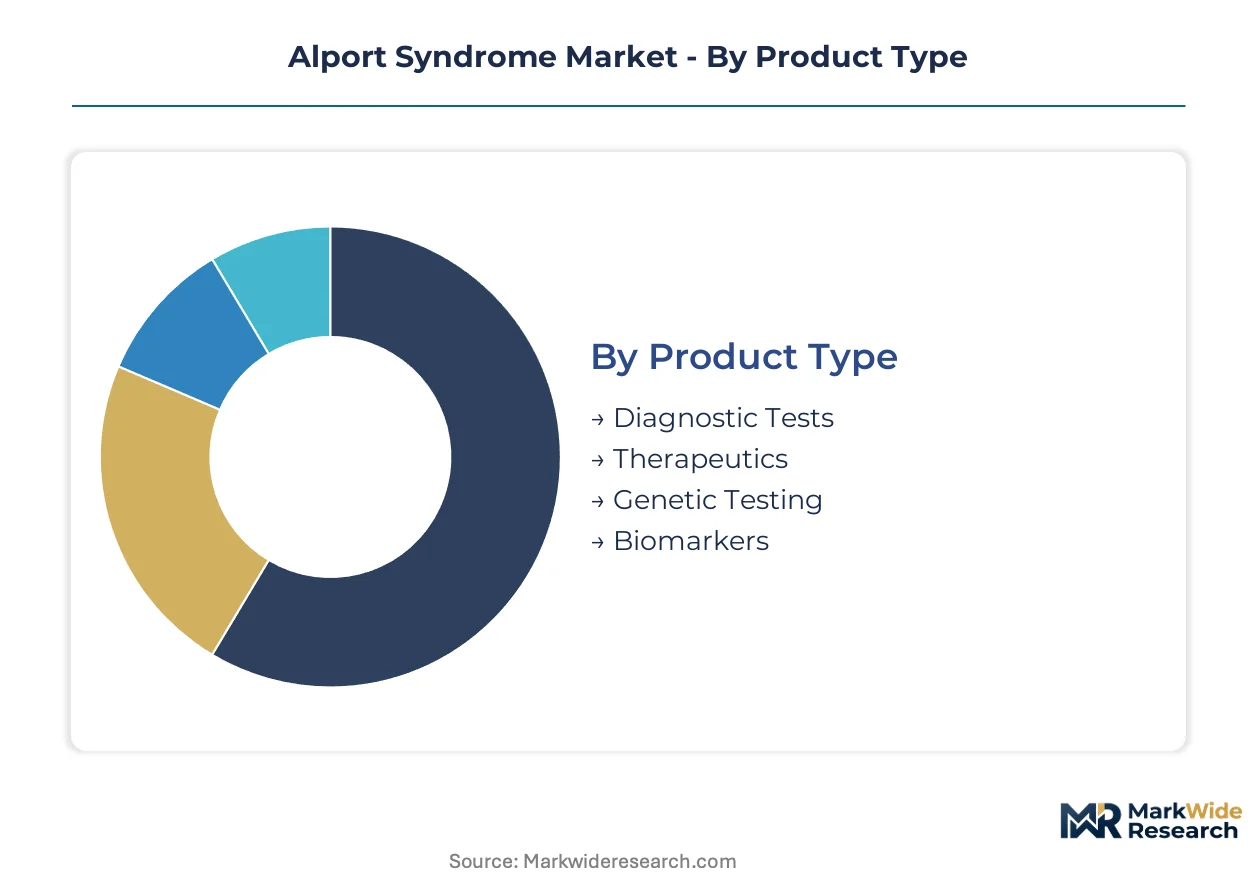
Segmentation in Alport Syndrome markets reflects divergent commercial rhythms across diagnostic, therapeutic, and monitoring modalities. Product categories with extended regulatory pathways contrast sharply with monitoring applications that generate recurring revenue through shorter deployment cycles.
Product Type:
Genetic Testing commands the longest validation timelines due to ISO 15189 laboratory accreditation requirements, while Biomarkers iterate rapidly through assay refinement cycles.
- Genetic Testing:Next-generation sequencing panels targeting COL4A3, COL4A4, and COL4A5 mutations deliver definitive diagnosis replacing presumptive clinical criteria. United States nephrology clinics and German academic medical centers concentrate procurement around integrated diagnostic-therapeutic platforms bundling longitudinal monitoring with genetic counseling.
- Diagnostic Tests:Biomarker panels quantifying proteinuria and staging renal function serve precision trial enrollment and treatment monitoring protocols. Japanese specialist renal networks deploy these tools most aggressively for early intervention patient selection.
- Therapeutics:Anti-inflammatory and anti-fibrotic mechanisms target underlying collagenopathy pathology in progressive kidney disease.
- Biomarkers:Proteinuria quantification and renal function staging tools enable mechanistic study patient selection.
Diagnostic Tests anchors the volume base while Genetic Testing gains share at the steepest rate.
Application:
Revenue concentration clusters around applications with captive patient populations and recurring touchpoints rather than episodic interventions.
- Patient Monitoring:Digital health platforms for early intervention protocols create recurring revenue streams alongside acute therapeutics. Nephrology clinics in Germany and Japan consolidate procurement around longitudinal monitoring bundled with genetic counseling services.
- Clinical Research:Mechanistic studies and interventional trials demand precision enrollment tools and biomarker-driven stratification. United States academic medical centers anchor global trial enrollment through concentrated referral pathways.
- Early Detection:Screening protocols identify microscopic hematuria progression before basement membrane defects advance.
- Treatment Management:Protocols coordinate anti-fibrotic therapy timing with renal function preservation endpoints.
Clinical Research absorbs the largest absolute spending while Patient Monitoring expands most quickly through subscription-based platform economics.
End User:
Procurement authority concentrates in institutions with integrated rare disease infrastructure and captive therapeutic pipelines.
- Hospitals:Academic medical centers with specialist renal care networks control trial enrollment and post-market surveillance pathways. Pediatric nephrology centers in the United States and Germany prioritize gene therapy candidates for early-phase enrollment.
- Research Laboratories:Genetic testing facilities face extended ISO 15189 accreditation processes affecting service launch schedules. European laboratories navigate EMA scientific advice procedures through partnership with established nephrology players.
- Diagnostic Centers:Reference laboratories compete for bundled diagnostic-therapeutic platform contracts.
- Clinics:Community nephrology practices access genetic testing through fragmented laboratory infrastructure outside core markets.
Hospitals dominate procurement value while Research Laboratories climb the fastest through gene therapy manufacturing partnerships.
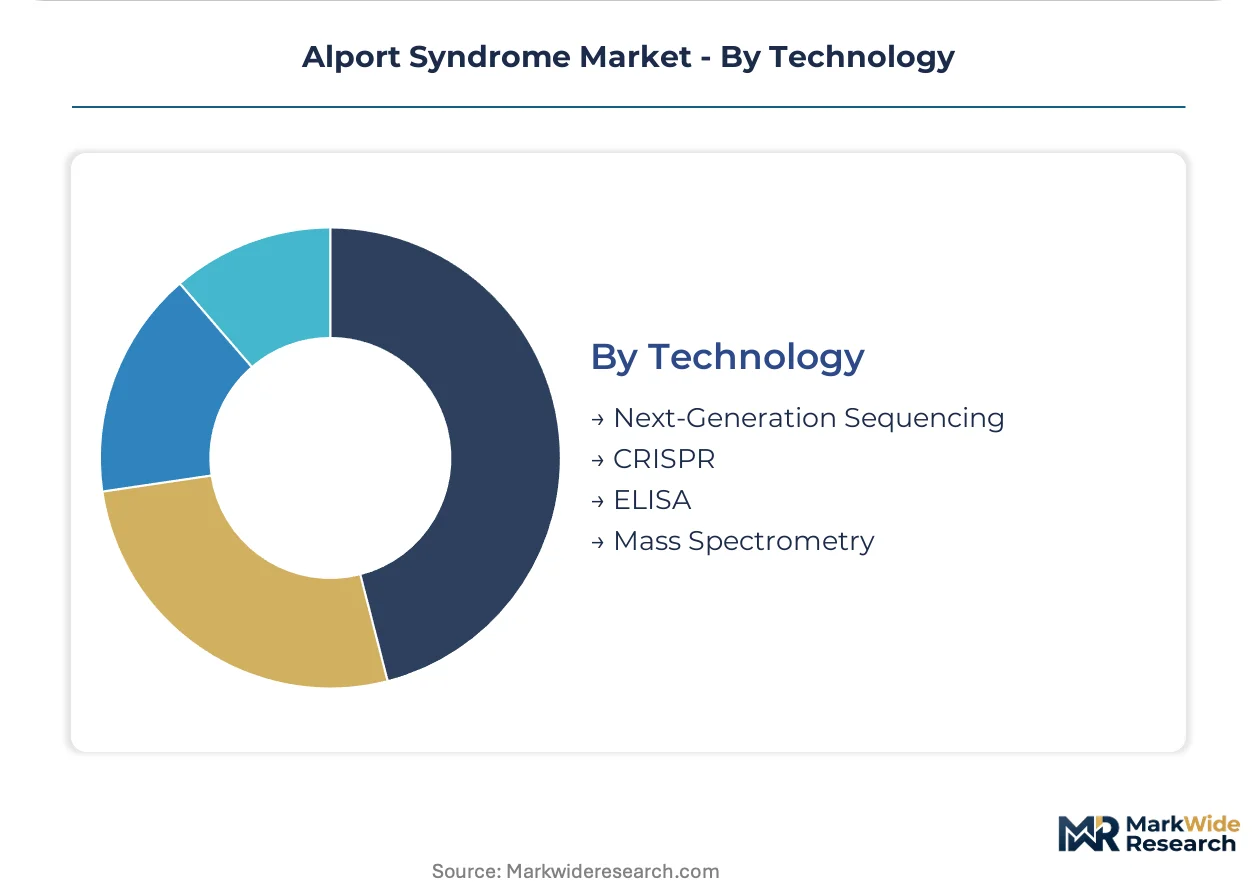
Technology:
Platform investments differentiate between capital-intensive vector production and scalable assay methodologies.
- Next-Generation Sequencing:Comprehensive genetic panels replace presumptive diagnostic criteria across United States, German, and Japanese nephrology clinics. Deployment concentrates where reimbursement frameworks for rare diseases are most developed.
- CRISPR:Gene editing platforms targeting COL4A3, COL4A4, and COL4A5 mutations compress development timelines for disease-modifying interventions. Manufacturing complexity and cold-chain distribution requirements constrain supply scalability.
- ELISA:Protein quantification assays support biomarker-driven trial enrollment at accessible cost points.
- Mass Spectrometry:High-resolution analytical platforms enable precise proteinuria characterization for mechanistic studies.
Next-Generation Sequencing underpins diagnostic volume while CRISPR attracts the steepest investment trajectory through curative potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and EMA rare disease programs have concentrated Alport Syndrome therapeutic development in jurisdictions with mature reimbursement frameworks for genetic renal diseases. Specialist renal care networks in these markets enable rapid clinical trial enrollment and post-market surveillance.
United States
Pediatric nephrology centers in Boston and New York anchor global gene therapy trial enrollment for COL4A3, COL4A4, and COL4A5 mutations. FDA protocol assistance programs accelerate investigational new drug applications through streamlined rare disease pathways. Academic medical centers in the Research Triangle and San Francisco Bay Area consolidate procurement around integrated diagnostic-therapeutic platforms bundling longitudinal monitoring with genetic counseling services.
Germany
ISO 15189-accredited genetic testing laboratories in Munich and Heidelberg deliver definitive diagnosis replacing presumptive clinical criteria for Alport Syndrome. EMA centralized marketing authorization and pediatric investigation plans reduce regulatory duplication costs for sponsors designing transatlantic studies. The country's statutory health insurance applies stringent cost-effectiveness thresholds to one-time curative interventions, creating reimbursement uncertainty for gene therapy candidates.
Japan
PMDA orphan drug designation and Sakigake fast-track pathways compress review timelines for Alport Syndrome therapeutic candidates targeting progressive kidney disease. Specialist renal networks in Tokyo and Osaka deploy biomarker panels most aggressively for early intervention patient selection. METI funding for rare disease research infrastructure supports nephrology clinics consolidating procurement around bundled diagnostic-therapeutic contracts.
United Kingdom
NHS England's specialized commissioning frameworks for rare renal diseases concentrate Alport Syndrome patient referrals to designated supraregional centers in London and Manchester. MHRA recognition of EMA scientific advice procedures enables parallel regulatory submissions with European counterparts. Genomics England's 100,000 Genomes Project has established variant interpretation pipelines that accelerate definitive diagnosis for collagenopathy mutations.
Switzerland
Swissmedic's expedited access pathway for medicines addresses unmet medical needs in hereditary nephropathies with accelerated assessment timelines. Basel and Zurich host concentrated pharmaceutical R&D infrastructure supporting mechanistic studies for anti-fibrotic and gene therapy platforms. The country's compulsory health insurance system provides more predictable reimbursement for innovative therapeutics compared to neighboring EU markets.
Alport Syndrome Market Vendor Landscape
Channel-controlling players compete with product-specialist players across Alport Syndrome markets, with consolidation around nephrology-focused biotech firms possessing rare disease development expertise. The competitive structure reflects tiered positioning between gene therapy platform developers, anti-fibrotic small-molecule specialists, and integrated diagnostic-therapeutic service providers. Strategic archetypes include oxidative stress modulators, specialty commercial infrastructure operators, and broad nephrology capability holders. Dominant competitive moves encompass milestone-based partnership financing and gene therapy manufacturing partnerships securing vector production capacity.
Among United States-based developers, Reata Pharmaceuticals and Novartis occupy distinct archetype positions within the competitive landscape. Reata exemplifies the oxidative stress modulation specialist targeting progressive kidney disease mechanisms, while Novartis anchors broad nephrology capabilities extending across multiple genetic renal indications. Calliditas Therapeutics, with its Swedish corporate structure, represents the specialty commercial infrastructure archetype competing through orphan and rare disease market access expertise.
| Leading Market Players |
|---|
| Reata Pharmaceuticals |
| Calliditas Therapeutics |
| Eloxx Pharmaceuticals |
| Novartis |
| River 3 Renal Corp |
| Chinook Therapeutics |
| Bayer |
| Fresenius Medical Care |
| Travere Therapeutics |
| Others |
Supply Flow & Price Mechanics
Boston's gene therapy manufacturing cluster dictates downstream pricing power through AAV vector production bottlenecks that constrain supply scalability. Cold-chain distribution requirements and ISO 15189 accreditation timelines for genetic testing laboratories create cost pass-through mechanisms that favor integrated diagnostic-therapeutic platform vendors over discrete service providers.
Pricing Analysis
Certification level (ISO 15189/FDA-grade) creates the primary spread between premium genetic testing services and standard biomarker panels. Three-tier pricing structure across premium, standard, and economy levels reflects laboratory accreditation status, with ISO 15189-accredited facilities in Germany and the United States commanding substantial premiums. Cost compression in standard-tier biomarker assays is intensifying because of automated ELISA platform proliferation. Academic medical centers with captive therapeutic pipelines exhibit lowest price sensitivity, while community nephrology clinics in fragmented laboratory markets face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized AAV vector producers in the United States, Switzerland, and Germany that serve gene therapy developers. Raw material dependencies include plasmid DNA, cell culture media, and chromatography resins. Single-source vulnerability pervades GMP-grade AAV production capacity, where qualified facilities number fewer than twenty globally. Distribution runs through specialist cold-chain logistics providers with validated cryogenic handling capabilities for cellular and genetic materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy platforms threaten to displace chronic anti-fibrotic small molecules entirely, forcing incumbents to defend revenue streams against curative substitution. Incumbents must navigate this substitution threat through strategic repositioning around patient monitoring and diagnostic platform integration.
For Market Incumbents: Harden market position through backward integration into genetic testing laboratory networks, securing ISO 15189-accredited capacity in Germany and Japan. Prioritize longitudinal patient monitoring platform development to create recurring revenue streams that offset therapeutic substitution risk. Lock in exclusive contracts with pediatric nephrology centers in Boston and New York to control gene therapy trial enrollment pathways. For New Entrants and Emerging Players: Build out biomarker-driven trial enrollment services targeting Japanese specialist renal networks, where early intervention protocol demand runs highest. Penetrate the diagnostic access inequality gap outside core United States, German, and Japanese markets through portable NGS platform deployment. Pursue EMA rare disease incentive navigation partnerships to reduce regulatory duplication costs for sponsors lacking European expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated diagnostic-therapeutic platform operators bundling longitudinal monitoring with genetic counseling services. Long-term viability hinges on gene therapy manufacturing partnerships securing vector production capacity, with platform economics favoring firms with captive laboratory infrastructure. Watch for FDA breakthrough therapy designation signals as inflection indicators for gene therapy candidate valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Partnership | AAV vector capacity scarcity makes manufacturing alliances critical for clinical supply security. |
| ISO 15189 Laboratory Accreditation | Accreditation unlocks premium pricing tiers in United States and European genetic testing markets. |
| Patient Monitoring Platform Development | Digital health subscriptions create defensive recurring revenue against therapeutic substitution. |
| EMA Rare Disease Incentive Navigation | Centralized marketing authorization reduces regulatory costs for transatlantic trial sponsors. |
| Pediatric Nephrology Center Partnership | Boston and New York centers anchor global gene therapy enrollment and surveillance pathways. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with nephrology clinic directors, genetic testing laboratory managers, regulatory affairs specialists, and rare disease venture capitalists; and secondary validation through FDA orphan drug designation filings, EMA scientific advice procedures, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up patient population estimates triangulated against top-down therapeutic market projections.
Forecast inputs considered gene therapy platform maturation curves, anti-fibrotic small molecule progression risks, and biomarker adoption rates across nephrology clinic networks. Segmentation dimensions spanned product type, application, end user, and technology platform. CAGRs derived from slope-intercept modeling of historical orphan drug market penetration patterns, adjusted for Alport Syndrome-specific regulatory acceleration factors and reimbursement framework development.
Stress conditions across gene therapy manufacturing scale-up timelines, payer cost-effectiveness threshold tightening in Germany, and diagnostic laboratory infrastructure buildout in emerging markets were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway harmonization and specialist renal care network consolidation. Quarterly review of FDA breakthrough therapy designations and EMA pediatric investigation plan approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Muscular Dystrophy Drugs Market