
 Point-Of-Care Genetic Testing Market | 2026-2036
Point-Of-Care Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Point-Of-Care Genetic Testing Market Outlook
CLIA-waiver certification under the Clinical Laboratory Improvement Amendments is reorganizing competitive access to the point-of-care genetic testing market, elevating manufacturers with proven quality management systems while filtering out smaller entrants. Danaher Corporation leverages its integrated diagnostics platform to sustain instrument placement cycles across acute care networks. Abbott Laboratories anchors its position through handheld molecular system specialization in infectious disease settings.
Point-of-care genetic testing encompasses nucleic acid amplification and detection systems designed for deployment outside centralized laboratories, typically delivering results within 15–60 minutes through cartridge-based or strip-based chemistries with minimal operator training. The technology serves clinical decision-making at the site of patient care, enabling therapeutic selection or isolation protocols without sample transport delays. Polymerase chain reaction dominates current installed bases due to its established analytical sensitivity, though LAMP technology is gaining fastest expansion in resource-limited settings where thermal cycler infrastructure remains scarce. Test kits capture the largest revenue pool through recurring consumable pull, while analyzers represent concentrated capital expenditure decisions with multi-year placement contracts.
FDA oversight through premarket notification and CLIA complexity categorization shapes product development roadmaps and commercial launch sequencing for US market participants. The EMA's In Vitro Diagnostic Regulation in Europe imposes parallel conformity requirements that extend certification timelines and documentation burdens for multinational manufacturers. Stakeholders must monitor evolving payer coverage determinations for pharmacogenomic testing as these reimbursement policies will determine which instrument platforms achieve sustainable utilization rates in outpatient settings.
Market Dynamics
The CLIA-waiver pathway is compressing commercialization timelines for molecular diagnostic platforms, forcing manufacturers to restructure quality management systems around near-patient testing requirements rather than centralized laboratory workflows.
Growth Catalysts
- Hospital laboratory consolidation:Integrated delivery networks in the United States are standardizing pharmacogenomic panels across multi-site systems, creating pull for cartridge-based platforms with 15-minute turnaround.
- LAMP chemistry expansion:Loop-mediated isothermal amplification is penetrating resource-limited clinical settings where thermal cycler infrastructure remains unavailable, opening addressable test volumes outside traditional PCR strongholds.
- FDA complexity reclassification:The agency's streamlined premarket notification for moderate-complexity molecular devices is accelerating instrument placement cycles in acute care networks.
Market Restraints
- Reagent supply concentration:Polymerase and fluorescent probe manufacturing clusters in Germany and Japan create vulnerability to regional logistics disruptions.
- Capital intensity barriers:Cartridge molding equipment and cleanroom assembly lines require eight-figure facility investments that filter mid-scale entrants.
- EMA documentation burdens:Europe's In Vitro Diagnostic Regulation extends conformity assessment timelines, delaying synchronous US-EU product launches.
Strategic Opportunities
- Pharmacogenomic reimbursement expansion:Medicare coverage determinations for CYP2C19 and SLCO1B1 testing in cardiology and psychiatry outpatient settings are creating new placement opportunities outside hospital walls.
- CRISPR-Cas detection convergence:Guide RNA-programmable nucleic acid recognition is integrating with existing cartridge architectures, enabling single-instrument multiplexing across infectious disease and oncology panels.
- Retail clinic channel development:MinuteClinic and similar urgent care formats are piloting rapid genetic testing for anticoagulant selection, establishing precedent for pharmacy-based molecular diagnostics.
Industry Challenges
- Bioinformatics integration complexity:Interpretation software for pharmacogenomic reports must interface with hospital electronic health record systems, requiring HL7 FHIR compliance that stretches development timelines.
- CLIA personnel certification gaps:Waived molecular testing still demands personnel with moderate-complexity training, creating hiring friction in rural and community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-Of-Care Genetic Testing Market |
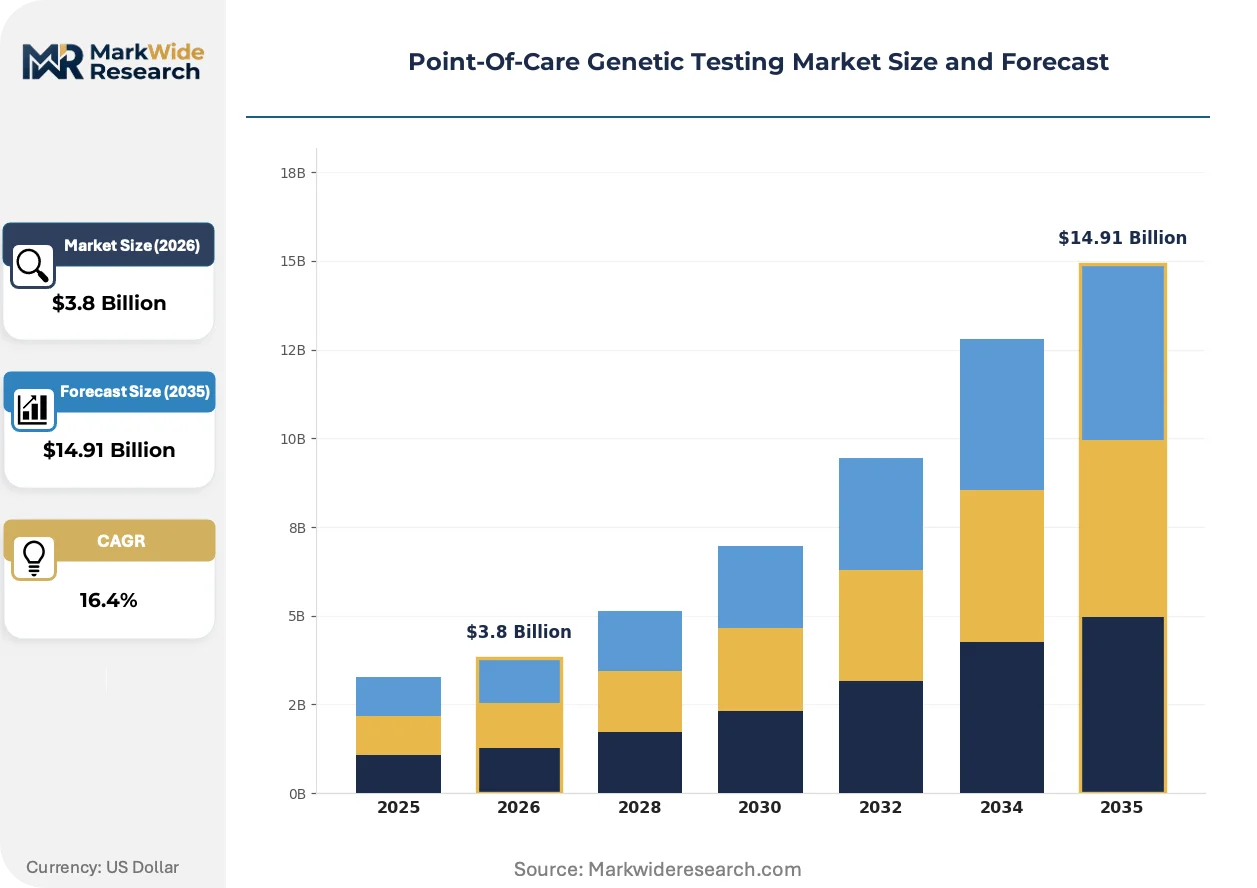
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Analyzers, Reagents, Software End User: Clinics, Hospitals, Laboratories, Pharmacies Technology: Polymerase Chain Reaction, Microarrays, Sequencing, LAMP Application: Infectious Disease, Oncology, Cardiovascular, Pharmacogenomics |
| Companies Covered | Danaher Corporation, F. Hoffmann-La Roche Ltd., Abbott Laboratories, QIAGEN N.V., bioMérieux, Illumina Inc., Bio-Rad Laboratories Inc., DiaSorin S.p.A., Cepheid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-Of-Care Genetic Testing Market Strategic Shifts
Competitive pressure is fragmenting product architectures into two distinct pathways: high-throughput cartridge systems for integrated networks versus ultra-portable strip-based formats for decentralized deployment.
Digital microfluidics is bifurcating instrument design philosophies. Electrowetting-on-dielectric platforms from academic spinouts are enabling programmable reaction chambers without moving parts. Large diagnostics manufacturers are licensing these architectures for next-generation pharmacogenomic panels. The technology is compressing assay development cycles from 18 months to under 8 months.
Europe's Medical Device Regulation is tightening clinical evidence requirements for molecular diagnostic software. Manufacturers must now submit prospective validation studies for algorithm-driven variant interpretation tools. Small-to-midscale IVD developers are responding by partnering with academic medical centers for real-world evidence generation.
Integrated delivery networks are consolidating procurement decisions at the system level rather than individual hospital laboratories. Centralized value analysis committees now evaluate total cost-of-ownership across instrument platforms, consumable contracts, and service agreements. This concentration is most pronounced in the United States, where three national IDNs control placement decisions for over 40 percent of acute care beds.
Point-Of-Care Genetic Testing Market Segmentation
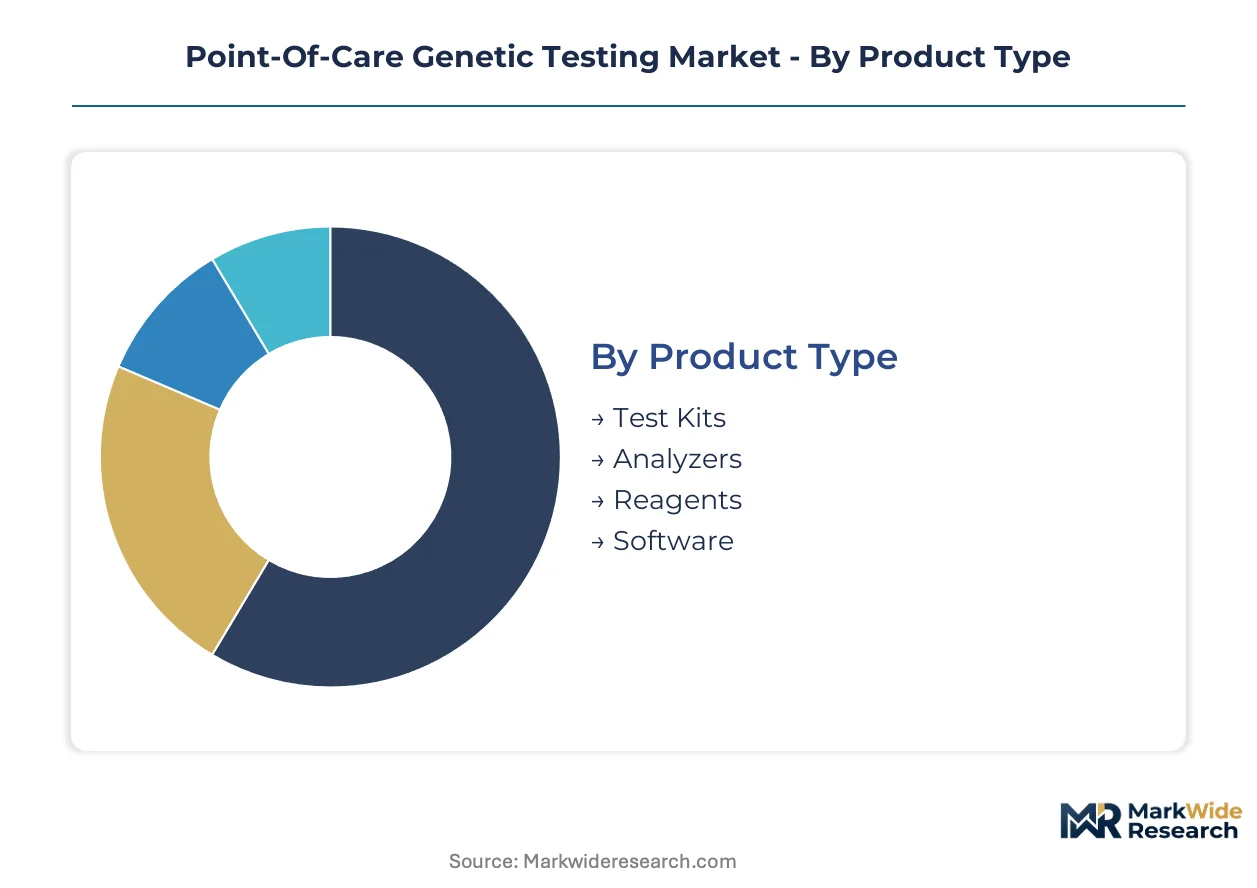
Segmentation in point-of-care genetic testing reveals where purchasing power concentrates across consumable pull-through versus capital placement decisions. Understanding these divides clarifies which technology platforms command sustainable revenue streams in decentralized clinical environments.
Product Type:
Recurring consumable margins dominate manufacturer profitability, while analyzer placements lock in multi-year purchasing commitments.
- Test Kits:Cartridge-based and strip-based chemistries deliver nucleic acid amplification in pre-configured reaction chambers. Hospital laboratories in the United States generate concentrated demand through pharmacogenomic panel standardization across integrated delivery networks.
- Analyzers:Benchtop and handheld instruments process cartridges with thermal cycling or isothermal protocols. Capital procurement committees evaluate total cost-of-ownership metrics that stretch replacement cycles to five-to-seven years.
- Reagents:Polymerase and fluorescent probe formulations with defined shelf-life constraints. Supply concentration in German and Japanese manufacturing clusters creates logistics vulnerability.
- Software:Bioinformatics platforms for variant interpretation and EHR integration. HL7 FHIR compliance requirements stretch development timelines for report generation modules.
Test kits hold installed capacity. Software is rotating up the share rankings.
End User:
Purchasing authority concentrates at the system level for hospital networks, while pharmacies represent emerging channel development with distinct reimbursement hurdles.
- Clinics:Outpatient facilities deploy rapid-turnaround testing for anticoagulant selection and infectious disease screening. Retail clinic pilots at MinuteClinic formats are establishing precedent for pharmacy-based molecular diagnostics.
- Hospitals:Acute care networks standardize pharmacogenomic panels across multi-site systems. Value analysis committees now consolidate procurement decisions controlling placement for over 40 percent of United States acute care beds.
- Laboratories:Hospital-affiliated and independent reference labs maintain moderate-complexity certification infrastructure. CLIA personnel requirements create hiring friction in rural and community settings.
- Pharmacies:Chain drugstore operators pilot point-of-care genetic testing for medication therapy management. Medicare coverage determinations for outpatient pharmacogenomic testing will determine sustainable utilization rates.
Hospitals anchor current revenue. Pharmacies are climbing the fastest.
Technology:
Established thermal cycling platforms defend installed base positions while isothermal chemistries penetrate infrastructure-constrained settings.
- Polymerase Chain Reaction:Thermal cycling amplification with established analytical sensitivity metrics. Dominates current installed bases in United States hospital laboratories with CLIA-waiver pathway acceleration.
- LAMP:Loop-mediated isothermal amplification operates without thermal cycler infrastructure. Resource-limited clinical settings in lower-income countries drive fastest expansion where electricity and equipment availability remain constrained.
- Microarrays:Solid-phase nucleic acid hybridization for multiplexed variant detection. Pharmacogenomic panel applications benefit from parallel SNP interrogation.
- Sequencing:Miniaturized next-generation platforms for targeted gene panels. Oncology applications leverage single-instrument multiplexing across mutation profiles.
Polymerase Chain Reaction commands placement volume. LAMP is gaining share fastest.
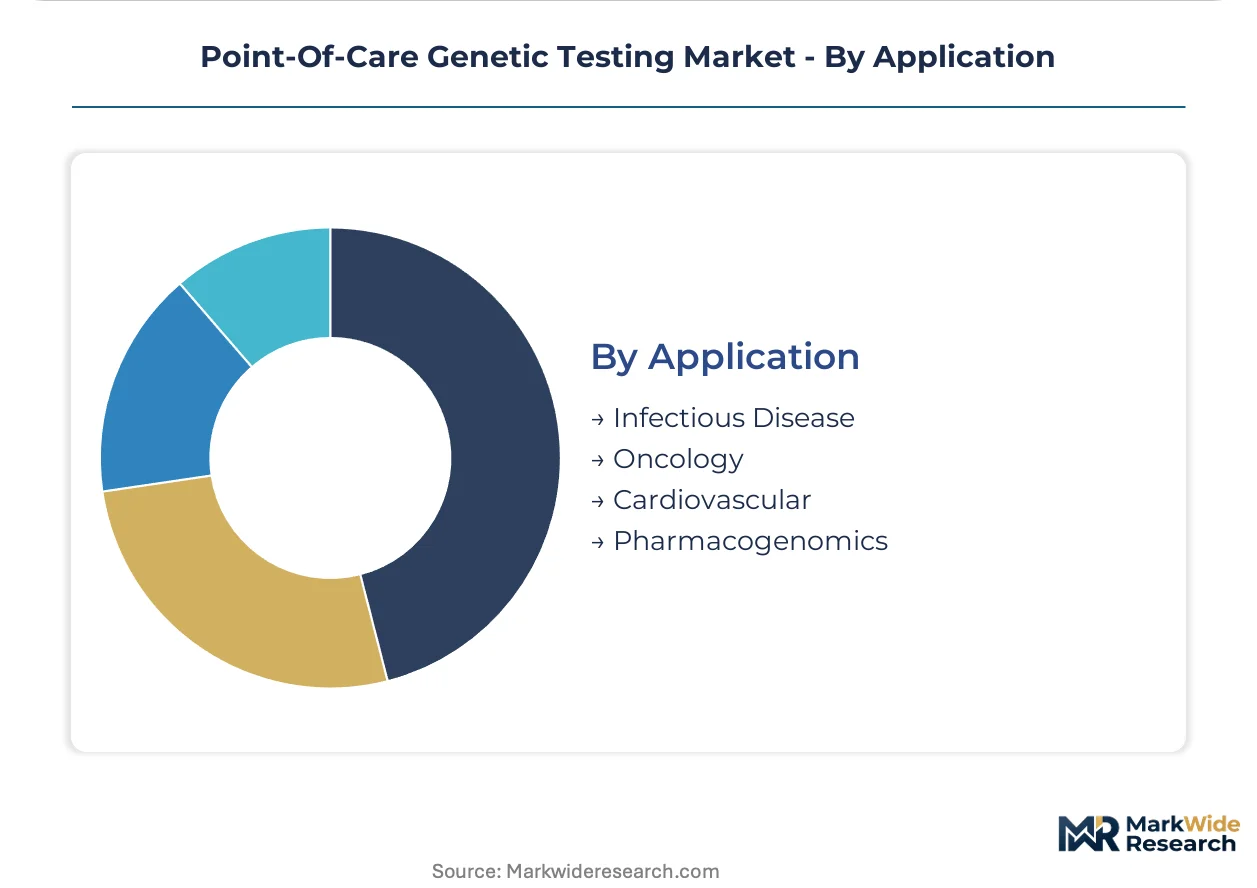
Application:
Reimbursement policy divergence across therapeutic areas determines which test menus achieve sustainable utilization outside hospital walls.
- Pharmacogenomics:CYP2C19 and SLCO1B1 testing for cardiology and psychiatry medication selection. Medicare coverage expansion for outpatient settings is creating new placement opportunities beyond acute care networks.
- Infectious Disease:Rapid pathogen identification for isolation protocol decisions and antimicrobial stewardship. Handheld molecular system specialization concentrates in emergency department and urgent care deployments.
- Oncology:Tumor mutation profiling for targeted therapy selection. CRISPR-Cas detection convergence enables programmable nucleic acid recognition within existing cartridge architectures.
- Cardiovascular:Genetic risk stratification for anticoagulant and antiplatelet selection. Retail clinic channel pilots focus on warfarin and clopidogrel pharmacogenomic testing.
Infectious Disease holds test volume leadership. Pharmacogenomics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's CLIA-waiver pathway accelerates commercialization timelines for molecular diagnostic manufacturers targeting the United States. Germany's EMA enforces parallel conformity requirements through the In Vitro Diagnostic Regulation. Japan's PMDA maintains stringent quality management standards for near-patient testing platforms.
United States
Integrated delivery networks consolidate procurement decisions for over 40 percent of acute care beds, standardizing pharmacogenomic panels across multi-site hospital systems. Medicare coverage determinations for CYP2C19 and SLCO1B1 testing in outpatient cardiology and psychiatry settings expand addressable test volumes beyond hospital walls. The Boston-Cambridge biotechnology corridor anchors CRISPR-Cas detection convergence research for programmable nucleic acid recognition systems.
Germany
Polymerase and fluorescent probe manufacturing clusters in German industrial centers create supply concentration vulnerability for global reagent supply chains. The EMA's In Vitro Diagnostic Regulation extends conformity assessment timelines, delaying synchronous product launches with US markets. The Rhine-Ruhr metropolitan region hosts precision molding equipment manufacturers serving cartridge-based platform producers.
Japan
PMDA oversight of moderate-complexity molecular devices maintains rigorous quality management system requirements for market entry. METI industrial policy supports miniaturized next-generation sequencing platform development for oncology applications. The Kanto region around Tokyo concentrates diagnostic instrument engineering talent and precision manufacturing capabilities.
China
NMPA regulatory pathways for molecular diagnostics are streamlining premarket notification procedures for domestic and multinational manufacturers. Dual carbon goals pressure cleanroom assembly line operators to adopt energy-efficient cartridge molding processes. The Yangtze River Delta region, particularly Shanghai and Suzhou, hosts expanding IVD manufacturing parks serving domestic hospital procurement networks.
India
CDSCO regulatory harmonization efforts align with international standards for point-of-care genetic testing platform certification. PLI scheme incentives attract diagnostic instrument assembly investments targeting resource-limited clinical settings. Karnataka's Bangalore-Tumkur industrial corridor concentrates biotech manufacturing operations for LAMP chemistry expansion in infrastructure-constrained markets.
Point-Of-Care Genetic Testing Market Competitive Environment
Player mix skews toward diversified diagnostics conglomerates with integrated platform capabilities and specialized molecular testing firms with focused application expertise. Market structure exhibits tiered consolidation, with capital-intensive instrument manufacturers commanding multi-year placement contracts against consumable-focused test kit suppliers. Strategic archetypes include platform-integrated systems providers, handheld molecular specialists, and reagent supply pure-plays. Dominant competitive moves center on CLIA-waiver pathway navigation for accelerated FDA clearance and strategic partnerships for bioinformatics software integration with hospital electronic health record systems.
Within the platform-integrated tier, Danaher Corporation and Abbott Laboratories exemplify divergent specialization strategies. Danaher leverages its diagnostics conglomerate structure to sustain instrument placement cycles across acute care networks through recurring consumable pull-through economics. Abbott anchors positioning through handheld molecular system development for infectious disease and pharmacogenomic applications. F. Hoffmann-La Roche Ltd. occupies a position bridging centralized laboratory and near-patient testing domains through its molecular diagnostics division structure. These three entities represent contrasting responses to the FDA's complexity reclassification trajectory and Medicare reimbursement expansion for outpatient pharmacogenomic testing.
| Leading Market Players |
|---|
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| Abbott Laboratories |
| QIAGEN N.V. |
| bioMérieux |
| Illumina Inc. |
| Bio-Rad Laboratories Inc. |
| DiaSorin S.p.A. |
| Cepheid |
| Others |
Value Chain & Pricing Dynamics
Multi-year consumable supply contracts lock in cartridge pricing visibility for integrated delivery networks while tethering manufacturers to polymerase sourcing commitments from German and Japanese production clusters. These arrangements compress margin flexibility for test kit producers facing CLIA-waiver certification costs.
Pricing Analysis
Certification level (FDA-grade, CE-IVD, ISO 13485) creates the primary spread across instrument and consumable tiers. Three-tier pricing structure across premium, standard, and economy levels segments by quality management maturity and EHR integration depth. Cost compression in economy-tier reagents is intensifying because Indian and Chinese manufacturers are scaling LAMP chemistry production. Hospital value analysis committees exhibit lowest price sensitivity for FDA-waived platforms with proven bioinformatics integration, while retail clinic pilots show highest sensitivity to per-test consumable costs.
Supply Chain Analysis
Rhine-Ruhr industrial corridor precision molding capacity underwrites cartridge housing supply for European and North American instrument manufacturers. Polymerase enzymes, fluorescent probe chemistries, and electrowetting-on-dielectric substrates draw from concentrated German, Japanese, and Chinese production bases. Single-source vulnerability in Taq polymerase fermentation capacity creates exposure to regional logistics disruptions. Distribution runs through diagnostics distributors with cold-chain capabilities to hospital laboratories and direct-to-IDN contracts for system-wide instrument placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care genetic testing sits at an inflection where FDA CLIA-waiver pathway acceleration converges with Medicare reimbursement expansion for outpatient pharmacogenomic testing, compressing commercialization timelines and enlarging addressable test volumes beyond acute care networks.
For Market Incumbents: Secure instrument placement cycles through multi-year consumable pull-through contracts with integrated delivery networks controlling over 40 percent of United States acute care beds. Deepen backward integration into polymerase manufacturing to mitigate supply concentration risk from German and Japanese clusters. Prioritize HL7 FHIR-compliant bioinformatics development to defend against software-focused entrants threatening EHR integration moats. For New Entrants and Emerging Players: Differentiate on LAMP chemistry miniaturization for resource-limited clinical settings where thermal cycler infrastructure remains unavailable. Target retail clinic and pharmacy channels piloting rapid genetic testing for anticoagulant selection, as Medicare coverage determinations for outpatient pharmacogenomic testing will determine sustainable utilization rates. Pursue strategic licensing of electrowetting-on-dielectric architectures from academic spinouts to compress assay development cycles. For Investors and Strategic Acquirers: Capital is best deployed toward consumable-focused test kit suppliers with proven CLIA-waiver quality management systems and established GPO contracts. Long-term viability hinges on sustainable reimbursement policy evolution rather than instrument hardware differentiation alone. Monitor FDA premarket notification timelines for CRISPR-Cas detection platforms as the signal indicating convergence velocity between programmable nucleic acid recognition and existing cartridge architectures.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waiver Certification Investment | Accelerates FDA clearance timelines for moderate-complexity molecular devices targeting acute care networks. |
| Pharmacogenomic Reimbursement Strategy | Positions test menus for Medicare coverage expansion in outpatient cardiology and psychiatry settings. |
| Hospital System Partnership | Secures multi-year instrument placement contracts through value analysis committee negotiations. |
| Software Companion Development | Enables HL7 FHIR-compliant variant interpretation integration with hospital electronic health record systems. |
| Backward Integration into Reagents | Reduces exposure to polymerase supply concentration in German and Japanese manufacturing clusters. |
Study Parameters
A spread of perspectives from hospital laboratory directors, CLIA compliance officers, GPO contracts managers, and diagnostic instrument procurement leads converged on the working assumptions underlying this analysis. Primary field engagement with integrated delivery network value analysis committees and FDA regulatory consultants combined with secondary validation from FDA 510(k) premarket notification databases, CMS Medicare coverage determination records, and hospital procurement databases. Bottom-up test volume modeling and top-down market sizing triangulated across technology platform installed bases and consumable pull-through economics.
Segmentation dimensions modeled span product type (test kits, analyzers, reagents, software), end user (hospitals, clinics, laboratories, pharmacies), technology (PCR, LAMP, microarrays, sequencing), and application (pharmacogenomics, infectious disease, oncology, cardiovascular) across the analysis window. CAGRs were derived from instrument placement cycle analysis and consumable revenue per installed base unit trajectories. Forecast inputs incorporated CLIA-waiver pathway approval velocity and pharmacogenomic reimbursement policy evolution.
Material uncertainties — regulatory reclassification of moderate-complexity devices, polymerase supply chain disruptions, and Medicare coverage determination delays — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as FDA complexity categorization and EMA In Vitro Diagnostic Regulation implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Cytogenetic Systems Market
Genomics
North America DNA Sequencing Products Market
Genomics
Nutrigenomics Testing Market
Genomics
Next Generation Molecular Assay Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
DNA Microarray Market
Genomics
Next Generation Sequencing Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Genomic Biomarkers Market
Genomics
Global Genomics Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Global Molecular Cytogenetics Market
Genomics
DNA Gene Chip Market