
 Fetal Macrosomia Market | 2026-2036
Fetal Macrosomia Market Size, Share, and Industry Trends Forecast 2026-2036
Fetal Macrosomia Market Foresight
Aftermarket service revenue for ultrasound platforms is reshaping margin distribution across the prenatal diagnostic landscape. GE Healthcare leverages its installed base of Voluson systems to sustain recurring service contracts in tertiary maternity centers. Siemens Healthineers anchors its position through AI-enhanced fetal biometry software integrated across imaging modalities. Philips Healthcare competes by extending remote monitoring capabilities that connect hospital networks with outpatient obstetric clinics.
Fetal macrosomia denotes a condition where a fetus exceeds standard weight thresholds, typically assessed through biparietal diameter, abdominal circumference, and femur length measurements obtained via ultrasound imaging, with clinical purpose centered on predicting delivery complications and guiding labor management decisions. Ultrasound equipment commands the dominant product segment due to its non-invasive real-time imaging utility, while glucose tolerance testing represents the fastest-expanding diagnostic category as gestational diabetes screening intensifies. Hospital end users concentrate procurement budgets on integrated fetal monitoring systems that combine cardiotocography with biometric analysis, whereas obstetrician practices increasingly favor portable point-of-care ultrasound for in-office risk stratification.
The FDA regulates prenatal diagnostic devices through 510(k) and De Novo pathways that govern ultrasound output limits and image quality benchmarks, while the EMA's Medical Device Regulation imposes clinical evidence requirements on fetal monitoring equipment marketed across European Union member states. Reimbursement coding under CMS and parallel national health systems directly shapes hospital capital allocation toward advanced prenatal screening technologies. Stakeholders must monitor evolving AI diagnostic algorithms and their regulatory classification status to anticipate shifts in competitive positioning and capital deployment priorities.
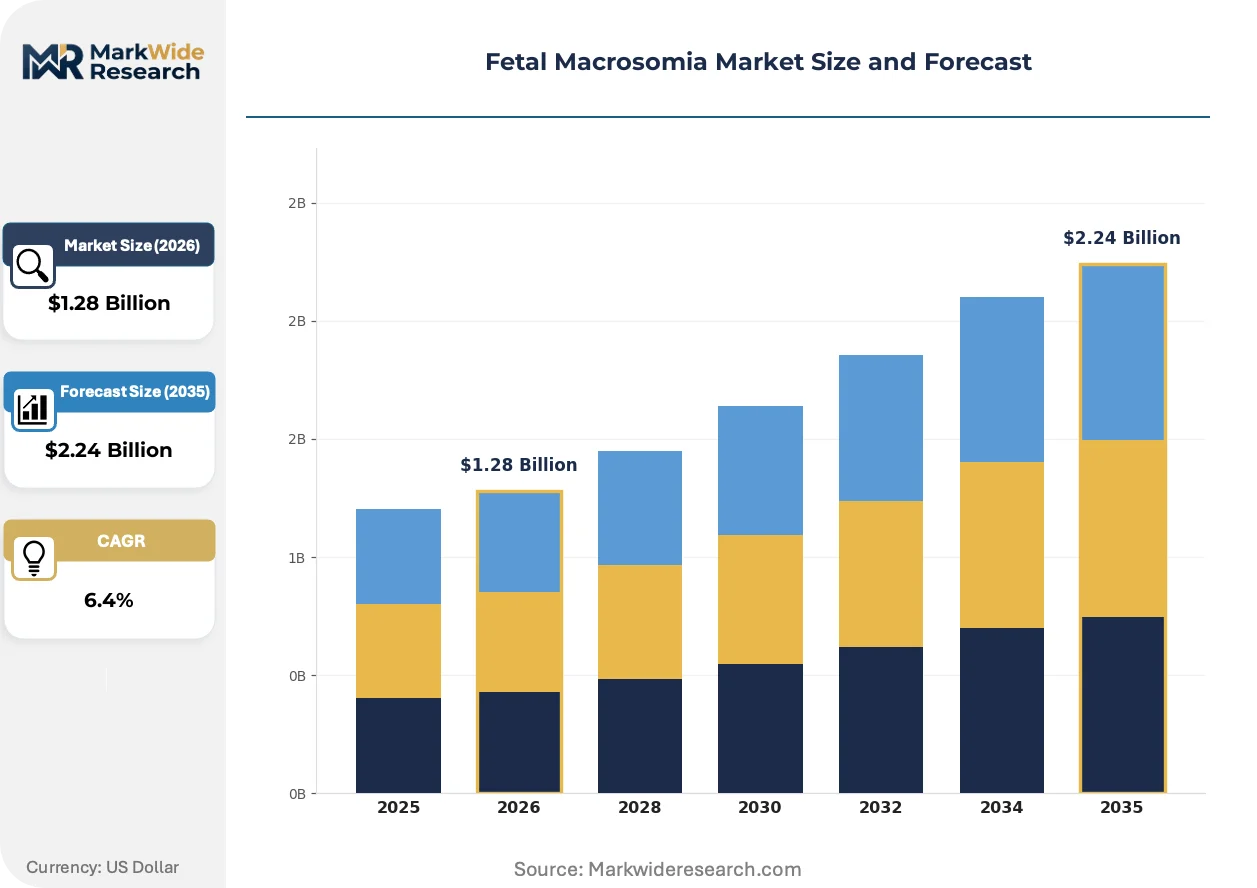
Market Dynamics
The FDA's streamlined 510(k) clearance pathway for AI-enhanced prenatal diagnostics is compressing technology adoption cycles, while hospital consolidation into regional maternity networks concentrates procurement authority among fewer decision-makers.
Growth Catalysts
- Gestational diabetes screening mandates:CMS reimbursement codes for universal glucose tolerance testing expand diagnostic volumes in obstetric practices. The protocol drives demand for integrated fetal biometry systems.
- AI-powered fetal weight estimation:Machine learning algorithms processing biparietal diameter and abdominal circumference measurements improve prediction accuracy for delivery complications. Tertiary care centers deploy these tools to reduce shoulder dystocia incidence.
- Rural clinic connectivity investments:Federal broadband infrastructure programs enable remote ultrasound interpretation services. Outpatient obstetric clinics in underserved counties access specialist-level diagnostic capabilities.
Market Restraints
- Capital equipment replacement cycles:Hospital capital budgets prioritize emergency department imaging over maternity ward ultrasound upgrades. Mid-tier systems face extended depreciation schedules.
- Transducer supply concentration:Piezoelectric crystal manufacturing for high-frequency obstetric probes concentrates in East Asian component suppliers. Single-source dependencies create procurement vulnerability.
- Operator skill variability:Fetal biometric measurement accuracy depends on sonographer training levels. Inconsistent technique across community hospitals limits clinical utility of screening protocols.
Strategic Opportunities
- Home-based glucose monitoring integration:Continuous glucose monitoring devices link to provider dashboards for real-time gestational diabetes management. Remote patient monitoring reimbursement codes support this channel expansion.
- Portable point-of-care ultrasound:Handheld devices with automated biometric calculation enable in-office risk stratification by obstetrician practices. The form factor addresses workflow constraints in high-volume clinics.
- EMA MDR clinical evidence pathways:Harmonized European regulatory requirements for fetal monitoring equipment create streamlined market access. Manufacturers leveraging this framework gain competitive positioning across EU member states.
Industry Challenges
- AI algorithm validation timelines:FDA pre-submission processes for machine learning-based diagnostic tools require extensive clinical performance datasets. Development costs escalate during evidentiary collection phases.
- Legacy CTG system integration:Hospital IT infrastructure for cardiotocography equipment lacks interoperability standards with newer biometric analysis platforms. Replacement decisions stall on integration complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fetal Macrosomia Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Blood Test, Glucose Tolerance Test, Fetal Monitoring Delivery Mode: Home Birth, Hospital Delivery, C-Section, Natural Birth End User: Obstetricians, Midwives, Hospitals, Clinics Application: Risk Assessment, Monitoring, Diagnosis, Treatment Management |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Fujifilm, Hologic, Samsung Medison, Canon Medical Systems, Mindray Medical International, Hitachi Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fetal Macrosomia Market Shifts & Advancements
Computational advances in fetal imaging and shifting reimbursement incentives are restructuring how prenatal diagnostics deploy across care settings. Three developments warrant particular attention.
Deep learning algorithms for automated fetal biometry are rendering obsolete manual measurement protocols that require specialized sonographer expertise. Community hospitals with limited maternal-fetal medicine staffing adopt these tools to standardize screening quality. The technology compresses the performance gap between tertiary centers and regional facilities.
REACH regulation amendments governing medical device material safety are imposing new substance disclosure requirements on ultrasound transducer manufacturers. European distributors now demand complete supply chain documentation for piezoelectric components. Manufacturers with captive material sourcing gain compliance advantages in EU member state tenders.
Obstetric group purchasing organizations are consolidating diagnostic equipment contracts across multi-hospital systems. Independent physician practices lose negotiating leverage as procurement authority centralizes. The concentration is most visible in United States metropolitan markets where health system mergers have accelerated.
Fetal Macrosomia Market Segmentation
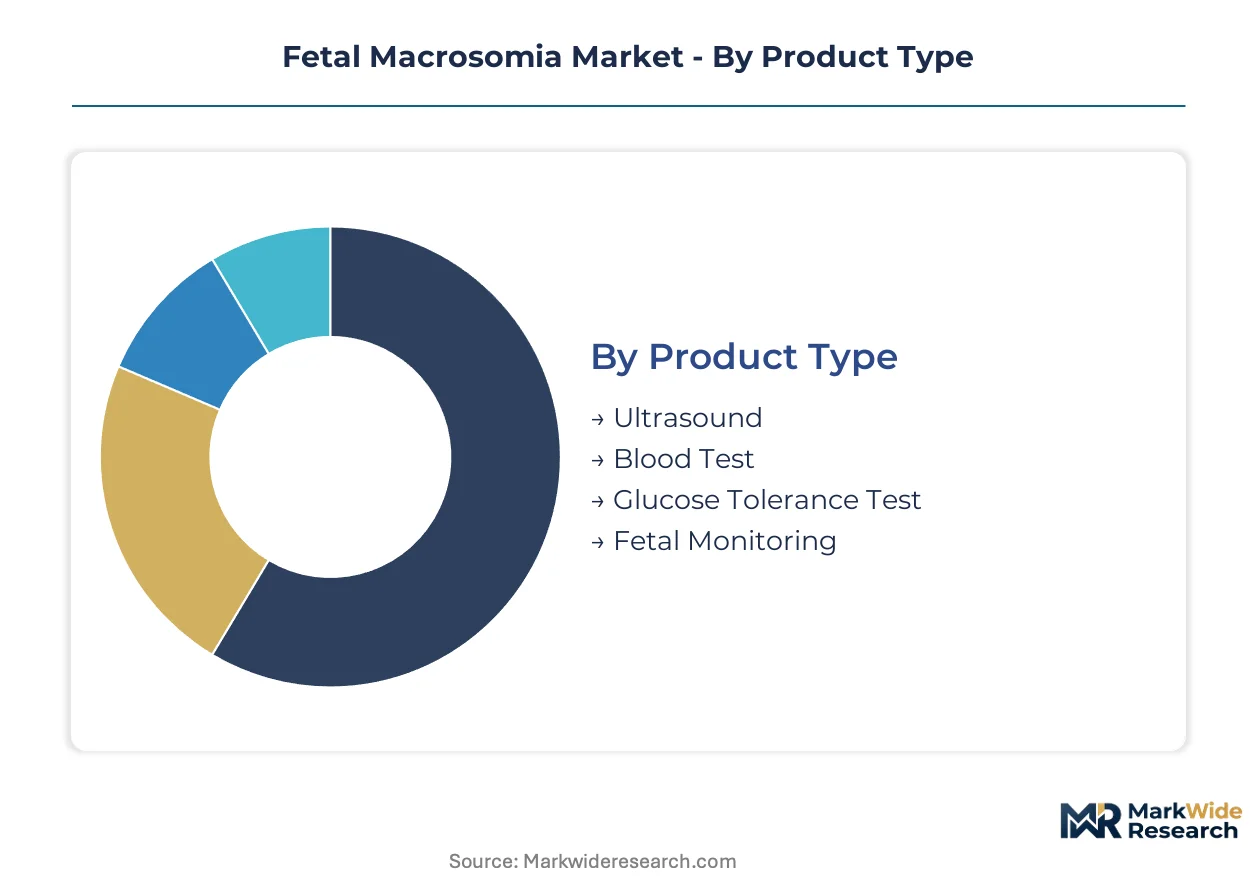
Product differentiation in fetal macrosomia diagnostics creates distinct service revenue streams and capital deployment patterns across the prenatal care continuum. Equipment manufacturers calibrate aftermarket strategies to the replacement cycles and connectivity requirements of each segment category.
Product Type:
After-sales service intensity varies sharply across diagnostic modalities, with imaging platforms generating recurring maintenance contracts while consumable-based tests rely on volume-driven reagent supply agreements.
- Ultrasound:Non-invasive real-time imaging systems process biparietal diameter, abdominal circumference, and femur length measurements for fetal weight estimation. Tertiary maternity centers in the United States concentrate procurement of integrated Voluson-class platforms with AI-enhanced biometry software, driven by hospital consolidation into regional perinatal networks.
- Glucose Tolerance Test:Standardized oral glucose challenge protocols screen for gestational diabetes as a primary macrosomia risk factor. Obstetric practices in high-diabetes-prevalence counties expand diagnostic volumes under CMS reimbursement codes, accelerating demand for integrated fetal biometry systems that combine metabolic screening with ultrasonic monitoring.
- Blood Test:Maternal serum biomarker panels assess metabolic and genetic risk indicators.
- Fetal Monitoring:Cardiotocography systems track fetal heart rate and uterine contraction patterns.
Ultrasound holds the largest share; momentum sits with glucose tolerance testing.
Delivery Mode:
Clinical workflow requirements and liability exposure shape diagnostic equipment placement across birth settings, with institutional deliveries commanding integrated monitoring suites.
- Hospital Delivery:Institutional births deploy comprehensive fetal surveillance infrastructure combining ultrasound biometry with continuous cardiotocography. United States health systems prioritize capital allocation toward integrated monitoring suites that reduce shoulder dystocia litigation exposure through predictive delivery complication protocols.
- C-Section:Surgical delivery protocols demand preoperative fetal weight verification to optimize incision planning and neonatal resuscitation readiness. Academic medical centers invest in AI-enhanced estimation tools to refine elective cesarean scheduling decisions.
- Natural Birth:Vaginal delivery pathways require intermittent ultrasonic assessment.
- Home Birth:Out-of-hospital deliveries rely on portable diagnostic equipment and telemedicine linkages.
Hospital delivery dominates equipment procurement; C-section protocols drive the steepest expansion trajectory for predictive analytics.
End User:
Customer concentration patterns determine sales channel economics, with consolidated health systems extracting volume discounts while fragmented practices sustain premium pricing for portable form factors.
- Hospitals:Integrated delivery networks consolidate procurement authority for multi-modal fetal surveillance systems. United States metropolitan health systems negotiate enterprise contracts spanning ultrasound platforms, glucose testing infrastructure, and electronic health record connectivity.
- Obstetricians:Physician practices in high-volume clinics favor handheld point-of-care ultrasound with automated biometric calculation for in-office risk stratification. The form factor addresses workflow constraints where specialist referral delays threaten patient retention.
- Clinics:Outpatient facilities serve as screening gatekeepers with limited intervention capability.
- Midwives:Independent birth attendants utilize portable monitoring devices with remote interpretation services.
Hospitals anchor capital equipment demand; obstetrician practices are gaining share fastest for portable diagnostics.
Application:
Clinical utility varies across the care pathway, with screening applications commanding higher test volumes while intervention guidance justifies premium equipment specifications.
- Risk Assessment:Population-level screening protocols identify pregnancies requiring enhanced surveillance based on maternal diabetes status, prior macrosomia history, and biometric percentile trajectories. United States prenatal care guidelines mandate universal glucose tolerance screening, institutionalizing risk stratification as a standard-of-care component.
- Diagnosis:Definitive macrosomia confirmation integrates ultrasonic biometry with clinical gestational age verification. Tertiary referral centers deploy machine learning algorithms to standardize measurement interpretation across sonographers with variable training backgrounds.
- Monitoring:Serial assessment tracks fetal growth velocity and maternal metabolic control.
- Treatment Management:Therapeutic intervention guidance spans delivery timing and mode selection.
Risk assessment captures the highest test volumes; diagnosis commands premium equipment specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical protocols for fetal macrosomia screening diverge sharply across healthcare systems, with the United States emphasizing universal gestational diabetes surveillance while European markets prioritize ultrasound standardization under harmonized device regulations.
United States
Hospital consolidation into regional perinatal networks concentrates procurement authority for integrated Voluson-class ultrasound platforms. The FDA's 510(k) clearance pathway for AI-enhanced fetal biometry accelerates technology adoption cycles. Tertiary maternity centers in metropolitan health systems deploy predictive delivery complication protocols to reduce shoulder dystocia litigation exposure.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor demand for AI-enhanced fetal weight estimation tools in elective cesarean scheduling. The EMA's Medical Device Regulation imposes clinical evidence requirements on fetal monitoring equipment marketed across EU member states. Siemens Healthineers leverages its domestic installed base to sustain recurring service contracts in university hospitals.
China
Rising gestational diabetes prevalence in urban maternal populations drives glucose tolerance testing volumes in provincial hospital networks. The NMPA regulates prenatal diagnostic devices through streamlined registration pathways for ultrasound platforms. Manufacturing clusters in Guangdong and Jiangsu provinces concentrate piezoelectric transducer component supply for domestic equipment assembly.
Japan
Aging obstetrician demographics and rural hospital closures intensify demand for remote ultrasound interpretation services. The PMDA governs fetal monitoring equipment through premarket approval processes emphasizing safety benchmarks. Tokyo and Osaka metropolitan medical centers pioneer machine learning integration for standardized biometric measurement across variable sonographer training levels.
United Kingdom
NHS England's maternity transformation program mandates enhanced screening for high-risk pregnancies in integrated care systems. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards for device market access. London and Southeast England academic centers concentrate AI diagnostic algorithm validation partnerships with imaging equipment manufacturers.
Fetal Macrosomia Market Competitive Landscape
Capability concentration sits with diversified imaging conglomerates; scale advantage sits with specialized maternal-fetal medicine equipment providers. The vendor base stratifies across three tiers: integrated healthcare technology conglomerates with multi-modal portfolios, mid-scale ultrasound specialists with obstetric software integration, and regional device assemblers serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships for AI algorithm licensing and backward integration into piezoelectric transducer manufacturing.
Within the diversified imaging tier, Siemens Healthineers, GE Healthcare, and Philips Healthcare exemplify contrasting geographic anchoring strategies. Siemens Healthineers occupies a position emphasizing European regulatory harmonization advantages. GE Healthcare represents scale-driven aftermarket service monetization through installed base leverage. Philips Healthcare exemplifies connectivity-focused positioning linking hospital networks with outpatient obstetric infrastructure. These three conglomerates anchor competitive dynamics through divergent emphases on software integration, service contract retention, and distributed care network architecture.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Fujifilm |
| Hologic |
| Samsung Medison |
| Canon Medical Systems |
| Mindray Medical International |
| Hitachi Medical Corporation |
| Others |
Supply & Pricing Matrix
Piezoelectric crystal supply concentration in East Asian component manufacturers creates procurement vulnerability that widens pricing spreads between premium AI-integrated ultrasound platforms and mid-tier systems while forcing hospital buyers toward long-term service contracts that lock in transducer replacement schedules.
Pricing Analysis
Long-term service contracts dominate equipment procurement, with tertiary maternity centers negotiating multi-year agreements bundling AI-enhanced biometry software licenses with predictive maintenance coverage. Price differentiation hinges on FDA 510(k) clearance tier and embedded machine learning capability, with premium Voluson-class systems commanding substantial markups over portable point-of-care alternatives. Cost compression in the mid-tier segment intensifies as hospital consolidation extracts volume discounts from regional perinatal networks. Obstetrician practices in high-volume clinics exhibit highest price sensitivity, prioritizing handheld form factors over integrated monitoring suites.
Supply Chain Analysis
Extended payment terms from East Asian piezoelectric crystal suppliers now stretch to 120 days for high-frequency obstetric probe components, straining working capital for ultrasound equipment assemblers. Manufacturing draws from China, Japan, and South Korea for transducer substrates, with additional dependencies on German precision optics and United States semiconductor controllers. Single-source vulnerability concentrates in Jiangsu province ceramic foundries serving multiple OEMs. Distribution runs through health system GPOs and specialized medical device distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across rural clinic connectivity and home-based glucose monitoring creates niche entry points for specialized players as federal broadband infrastructure programs and remote patient monitoring reimbursement codes reshape demand patterns.
For Market Incumbents: Build installed base moats through captive aftermarket service networks that preempt third-party transducer refurbishment. Siemens Healthineers and GE Healthcare should deepen AI algorithm licensing partnerships with academic medical centers to standardize biometric measurement protocols across variable sonographer training levels. Consolidation of obstetric group purchasing organization contracts demands proactive enterprise pricing to defend margin position against mid-tier ultrasound specialists. For New Entrants and Emerging Players: Underserved counties in United States rural health networks offer the most penetrable geography, where federal broadband infrastructure programs enable remote ultrasound interpretation services without capital-intensive platform deployment. Portable point-of-care ultrasound with automated biometric calculation addresses workflow constraints in high-volume obstetrician practices losing patients to referral delays. A software-first go-to-market angle licensing AI fetal weight estimation algorithms to existing installed bases minimizes hardware manufacturing barriers. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors AI diagnostic algorithm developers with FDA pre-submission progress over pure hardware manufacturers. Long-term viability over the next decade hinges on regulatory capture of machine learning-based diagnostic classifications and reimbursement code expansion for remote patient monitoring. Acquisition targets should demonstrate clinical validation partnerships with tertiary maternity centers. The signal to watch is FDA De Novo pathway decisions for novel AI biometry tools that would reset competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing Partnership | Siemens Healthineers leverages domestic German academic networks to validate fetal weight estimation tools. |
| CE Marking Pathway Investment | Harmonized EMA MDR clinical evidence requirements streamline market access across EU member states. |
| Hospital System Partnership | United States metropolitan health systems negotiate enterprise contracts spanning ultrasound platforms and EHR connectivity. |
| Software Companion Development | Continuous glucose monitoring device integration with provider dashboards enables real-time gestational diabetes management. |
| Reimbursement Strategy | CMS remote patient monitoring codes support channel expansion into home-based glucose monitoring integration. |
Research Methodology
Initial hypotheses were tested against primary input from maternal-fetal medicine specialists, hospital purchasing committee directors, biomedical engineers, and obstetrician practice administrators and refined through secondary validation against FDA 510(k) clearance databases, CMS reimbursement code filings, hospital procurement records, and EMA Medical Device Regulation guidance documents. Bottom-up demand modeling across ultrasound equipment installations, glucose tolerance testing volumes, and AI diagnostic algorithm deployments triangulated against top-down healthcare capital expenditure forecasts.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling across product type, delivery mode, end user, and application dimensions plus regional regulatory cluster differentiation. CAGRs were derived from equipment replacement cycle analysis, gestational diabetes screening protocol expansion rates, and hospital consolidation patterns. Forecast inputs incorporated AI diagnostic algorithm validation timelines and piezoelectric transducer supply concentration metrics.
Practitioners should monitor FDA pre-submission outcomes for machine learning-based diagnostic tools and REACH regulation amendments governing medical device material safety for early signals of competitive repositioning. Forecasts reflect assumptions regarding sustained CMS reimbursement for remote patient monitoring and continued hospital consolidation into regional perinatal networks. Macroeconomic deviation in healthcare capital expenditure, regulatory reclassification of AI diagnostic algorithms, or supply disruption in East Asian piezoelectric component manufacturing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Insulinoma Market