
 Alpha Mannosidosis Market | 2026-2036
Alpha Mannosidosis Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha Mannosidosis Market Analysis
Pediatric metabolic specialists is collapsing as the dominant buyer archetype as adult transition clinics and homecare infusion providers capture growing patient volumes. Chiesi Farmaceutici S.p.A. leverages its European rare disease infrastructure to sustain commercial reach across specialized treatment centers. Ultragenyx Pharmaceutical Inc anchors its position through deep manufacturing partnerships for biologic supply security. Amicus Therapeutics differentiates via platform technologies that compete across multiple lysosomal storage disorders.
Alpha mannosidosis is a rare autosomal recessive lysosomal storage disorder caused by deficient alpha-mannosidase enzyme activity, resulting in accumulation of undegraded mannose-rich oligosaccharides in tissues and progressive multisystem dysfunction; the condition requires lifelong therapeutic intervention to manage neurological, skeletal, and immunological manifestations. Enzyme Replacement Therapy dominates current revenue as the only approved mechanistic approach, while Gene Therapy represents the fastest-expanding development category with multiple clinical programs advancing toward regulatory submission. Substrate Reduction Therapy occupies a narrower position aimed at symptomatic biochemical modulation rather than definitive disease correction.
The FDA's Rare Pediatric Disease designation and EMA's orphan drug framework shape clinical trial incentives and extended exclusivity timelines for developers targeting this ultra-rare indication. ISO 15189 accreditation requirements for biochemical and genetic testing laboratories influence diagnostic access and newborn screening program expansion. Stakeholders must monitor regulatory pathway convergence between gene therapy and enzyme replacement platforms to anticipate reimbursement and manufacturing investment priorities.
Market Dynamics
The transition from pediatric-only treatment to adult maintenance protocols is compressing site-of-care economics and forcing reimbursement redesign across managed care organizations.
Growth Catalysts
- Newborn screening expansion:State-level mandates in the United States and pilot programs in Germany are shortening diagnostic delays and expanding addressable patient pools.
- EMA orphan drug framework:Extended market exclusivity and protocol assistance incentives accelerate clinical development timelines for ultra-rare enzyme therapies.
- Home infusion capabilities:Specialized nursing networks and cold-chain logistics providers are enabling treatment migration from hospital outpatient departments to residential settings.
Market Restraints
- Bioreactor capacity concentration:Mammalian cell culture manufacturing for recombinant enzymes depends on a limited network of contract development and manufacturing organizations in Switzerland and the United States.
- Reimbursement fragmentation:Payer heterogeneity across Medicaid, commercial, and pharmacy benefit managers creates prior authorization friction and treatment initiation delays.
- Gene therapy substitution timeline:Potentially curative lentiviral and AAV approaches threaten long-term enzyme replacement revenue durability as clinical data matures.
Strategic Opportunities
- Adult transition clinic networks:Underserved patient cohorts aging out of pediatric metabolic centers in the United States represent untapped lifetime value capture.
- Companion diagnostic integration:Biochemical and next-generation sequencing test bundling with therapeutic protocols creates stickiness with treatment-naïve patients.
- Substrate reduction therapy positioning:Small-molecule adjuncts targeting glycoprotein biosynthesis offer pipeline optionality for milder phenotypes and combination regimens.
Industry Challenges
- Genetic counselor workforce scarcity:Pre-test counseling and variant interpretation bottlenecks limit diagnostic throughput in community hospital settings.
- Long-term follow-up infrastructure:Natural history study enrollment and post-marketing surveillance obligations strain registry maintenance capabilities across dispersed patient populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha Mannosidosis Market |
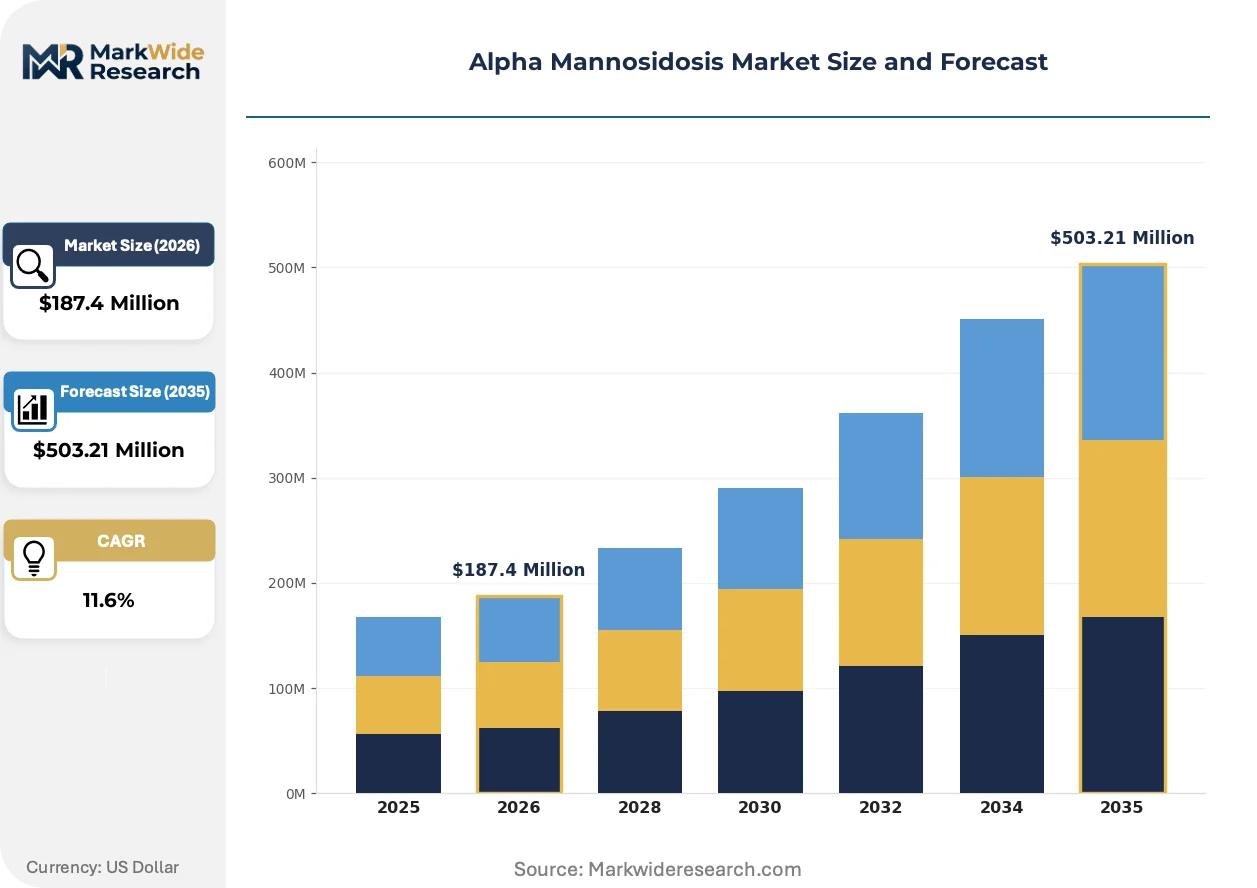
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Gene Therapy, Supportive Care Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Clinics, Homecare, Research Institutions Test Type: Genetic Testing, Biochemical Testing, Prenatal Testing, Newborn Screening |
| Companies Covered | Orchard Therapeutics, PTC Therapeutics, Chiesi Farmaceutici S.p.A., Takeda Pharmaceutical Company Limited, Sobi, Ultragenyx Pharmaceutical Inc, Zymenex A/S, Amicus Therapeutics, BioMarin Pharmaceutical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha Mannosidosis Market Emerging Trajectories
Mechanistic diversification beyond enzyme replacement is reshaping competitive positioning, with gene therapy and substrate modulation approaches advancing through parallel clinical pathways.
Lentiviral hematopoietic stem cell gene therapy is decomposing the assumption that lifelong intravenous enzyme infusions represent the definitive treatment paradigm. Adult metabolic specialists and transition clinic coordinators are evaluating early-phase data to anticipate protocol shifts. The technology is decomposing revenue concentration in infusion-dependent care models and redirecting capital toward curative intent manufacturing infrastructure.
FDA Rare Pediatric Disease Priority Review Voucher awards are compressing commercialization timelines for developers achieving pivotal endpoints. The industrial consequence is front-loaded investment in natural history data collection and biomarker qualification to support accelerated approval pathways. Ultra-rare disease sponsors with voucher-eligible programs are prioritizing United States regulatory submission sequencing over European Medicines Agency filing.
Site-of-care migration toward home-based infusion administration is fragmenting traditional hospital outpatient department capture. Specialized home nursing agencies and regional infusion pharmacies are displacing academic medical center volume in stable maintenance patients. This pattern is most visible in United States metropolitan markets with established rare disease hub-and-spoke distribution networks.
Alpha Mannosidosis Market Segmentation
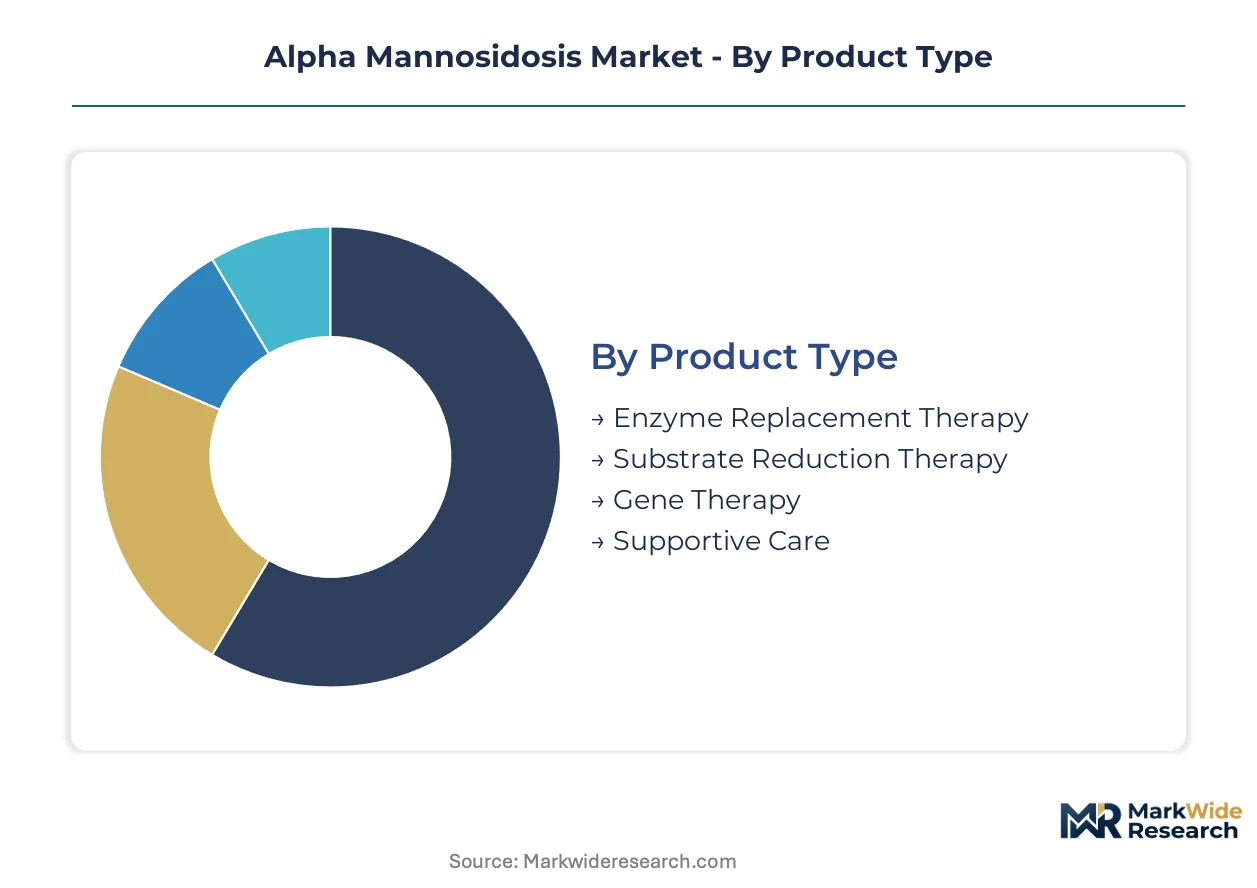
Treatment modality segmentation in alpha mannosidosis reveals divergent investment profiles across curative versus chronic care platforms. Mechanistic categories carry distinct regulatory pathways, manufacturing requirements, and reimbursement architectures that reshape competitive boundaries.
Product Type:
Domestic market absorption concentrates in chronic maintenance therapies, while export-led demand clusters around one-time curative modalities requiring specialized manufacturing infrastructure.
- Enzyme Replacement Therapy:Recombinant alpha-mannosidase administered via regular intravenous infusions addresses the underlying enzyme deficiency. United States pediatric metabolic centers and adult transition clinics in Boston, Philadelphia, and San Francisco anchor demand concentration, driven by FDA Rare Pediatric Disease Priority Review Voucher incentives and established infusion infrastructure.
- Gene Therapy:Lentiviral and AAV vectors targeting hematopoietic stem cells or direct CNS delivery aim at functional cure through persistent enzyme expression. Clinical program momentum in Basel, Switzerland and Cambridge, Massachusetts positions this segment for regulatory submission sequencing, with manufacturing partnerships determining geographic rollout priority.
- Substrate Reduction Therapy:Small-molecule glycoprotein biosynthesis inhibitors offer biochemical modulation for milder phenotypes.
- Supportive Care:Symptomatic management of skeletal, immunological, and neurological manifestations through orthopedic, infectious disease, and rehabilitation protocols.
Enzyme Replacement Therapy holds the largest share; momentum sits with Gene Therapy.
Delivery Mode:
Route selection drives site-of-care economics and patient adherence profiles, with cost tiers separating hospital-dependent from self-administered modalities.
- Intravenous:Infusion-dependent administration requiring specialized nursing and cold-chain logistics, concentrated in academic medical center outpatient departments.
- Subcutaneous:Home-based delivery systems reducing treatment burden for maintenance patients with established vascular access.
- Oral:Small-molecule substrate reduction agents enabling patient self-management without clinical infrastructure dependency.
- Inhalation:Pulmonary delivery platforms under investigation for CNS penetration through olfactory neural pathways.
Intravenous dominates current volume; Subcutaneous is climbing the fastest as home nursing networks expand.
End User:
Customer type fragmentation reflects the transition from pediatric-only diagnosis toward lifelong disease management across institutional and residential settings.
- Hospitals:Academic medical centers with lysosomal storage disorder programs manage acute complications, surgical interventions, and initial therapy initiation in New York, Houston, and Los Angeles.
- Clinics:Specialized metabolic and genetics clinics in Chicago, Seattle, and Denver coordinate multidisciplinary care and transition protocols.
- Homecare:Regional infusion pharmacies and nursing agencies in metropolitan markets enable treatment migration from institutional to residential settings.
- Research Institutions:Natural history study sites and gene therapy trial centers in Bethesda, Maryland and Research Triangle Park, North Carolina drive clinical development enrollment.
Hospitals retain the largest patient volume; Homecare shows the steepest expansion trajectory as reimbursement redesign follows site-of-care migration.
Test Type:
Diagnostic modality segmentation tracks the shift from symptomatic confirmation toward presymptomatic detection through population screening infrastructure.
- Genetic Testing:Next-generation sequencing of MAN2B1 variants confirms diagnosis and enables carrier detection in family screening protocols.
- Biochemical Testing:Alpha-mannosidase enzyme activity assays and urinary oligosaccharide profiling provide functional confirmation in ISO 15189-accredited laboratories.
- Prenatal Testing:Chorionic villus sampling and amniocentesis with enzymatic or molecular analysis for at-risk pregnancies.
- Newborn Screening:Dried blood spot enzyme activity testing with tandem mass spectrometry detection, expanding through state-level mandates in California, New York, and Texas.
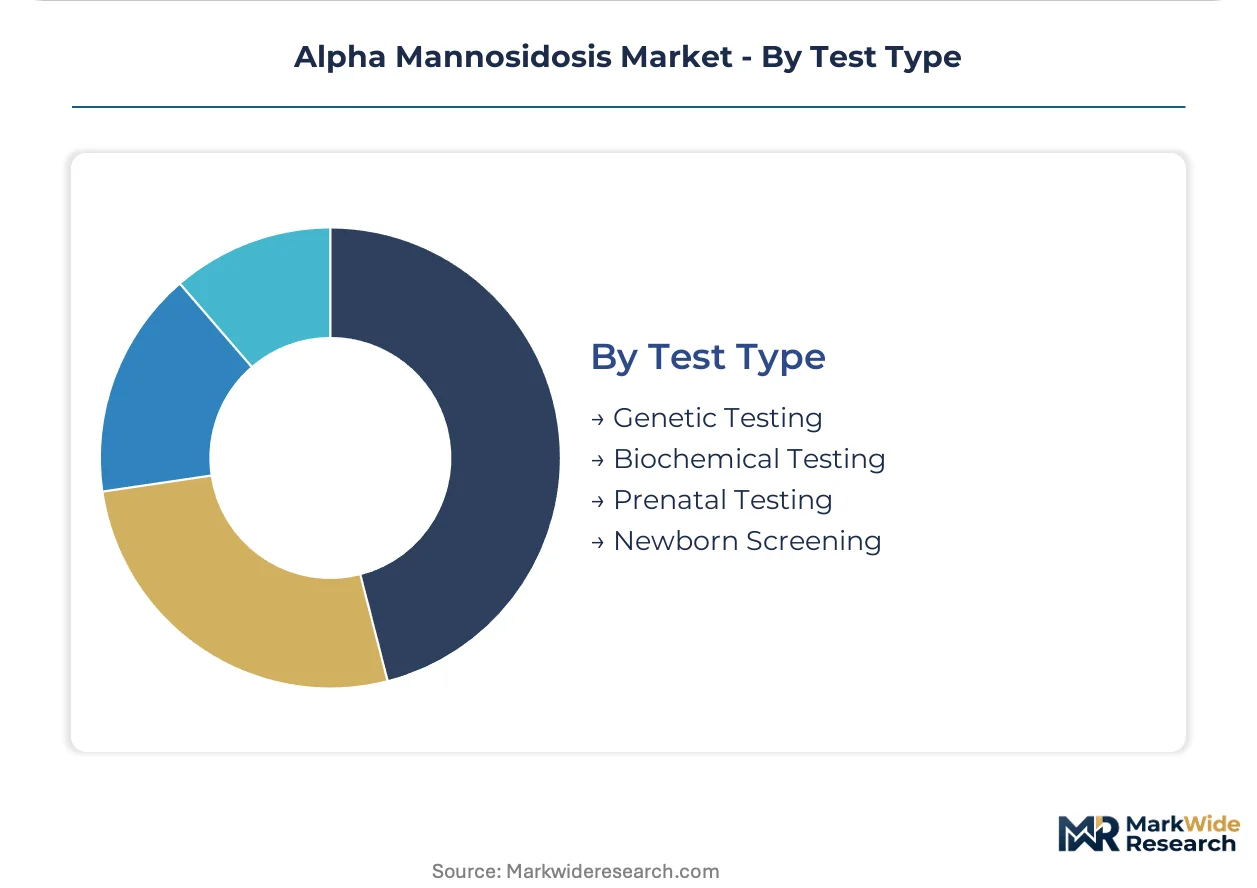
Genetic Testing captures the largest diagnostic volume; Newborn Screening is gaining share fastest through state mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Treatment flows from Swiss and United States manufacturing clusters toward specialized metabolic centers in Germany, Japan, and the United Kingdom, with newborn screening infrastructure determining patient identification velocity in each market.
United States
FDA Rare Pediatric Disease Priority Review Vouchers compress commercialization timelines for developers achieving pivotal endpoints. State-level newborn screening mandates in California, New York, and Texas expand addressable patient pools through dried blood spot enzyme activity testing. Boston, Philadelphia, and San Francisco anchor demand concentration through pediatric metabolic centers and adult transition clinics managing lifelong therapy.
Germany
Pilot newborn screening programs in Bavaria and North Rhine-Westphalia shorten diagnostic delays for ultra-rare lysosomal storage disorders. EMA orphan drug framework provides extended market exclusivity and protocol assistance incentives for enzyme therapy developers. Heidelberg and Munich host specialized treatment centers coordinating multidisciplinary care across pediatric and adult patient cohorts.
Switzerland
Contract development and manufacturing organizations in Basel concentrate mammalian cell culture capacity for recombinant enzyme production. Swissmedic regulates advanced therapy medicinal products including lentiviral vector manufacturing for gene therapy programs. The Basel biotech cluster anchors European clinical development for hematopoietic stem cell gene therapy approaches.
Japan
PMDA Sakigake designation accelerates regulatory review for innovative therapies targeting unmet medical needs in ultra-rare diseases. Tokyo and Osaka metropolitan areas concentrate specialized metabolic centers with lysosomal storage disorder expertise. Domestic pharmaceutical partners facilitate market access for imported enzyme replacement therapies through local distribution agreements.
United Kingdom
NHS England's Highly Specialised Services framework commissions ultra-orphan treatments through national centers of excellence. Genomics England integrates rare disease sequencing into diagnostic pathways for metabolic disorders. London, Manchester, and Birmingham anchor specialized treatment networks managing transition from pediatric to adult metabolic services.
Alpha Mannosidosis Market Vendor Landscape
Listed leaders compete with private specialists across enzyme manufacturing and gene therapy platform development, creating a tiered structure where scale-driven pharmaceutical companies face precision-focused biotechnology firms. The vendor base separates into three archetypes: integrated rare disease platforms with global commercial infrastructure, gene therapy specialists advancing curative modalities, and regional enzyme manufacturers serving established infusion markets. Consolidation pressure intensifies as gene therapy data matures, prompting partnership strategies between large-cap developers and vector manufacturing specialists.
Within the integrated rare disease platform tier, Chiesi Farmaceutici S.p.A. and Ultragenyx Pharmaceutical Inc exemplify archetypes leveraging European and North American commercial infrastructure respectively. Amicus Therapeutics occupies a position representing platform technology competitors addressing multiple lysosomal storage disorders through shared manufacturing and regulatory capabilities. Takeda Pharmaceutical Company Limited anchors the large-cap pharmaceutical vector with rare disease portfolio diversification strategies.
| Leading Market Players |
|---|
| Orchard Therapeutics |
| PTC Therapeutics |
| Chiesi Farmaceutici S.p.A. |
| Takeda Pharmaceutical Company Limited |
| Sobi |
| Ultragenyx Pharmaceutical Inc |
| Zymenex A/S |
| Amicus Therapeutics |
| BioMarin Pharmaceutical Inc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between recombinant enzyme manufacturers and specialized infusion networks lock in both supply access and price visibility across the United States and Swiss markets. These arrangements tether treatment costs to bioreactor capacity reservations while insulating pediatric metabolic centers from spot-market volatility in mammalian cell culture inputs.
Pricing Analysis
Next-generation gene therapy pricing is diverging sharply from chronic enzyme replacement benchmarks as curative intent modalities command premium positioning against maintenance-dependent alternatives. Three-tier pricing structure across premium, standard, and economy levels separates lentiviral hematopoietic stem cell programs from established intravenous enzyme protocols and investigational substrate reduction small molecules. Cost compression in standard-tier enzyme replacement is intensifying because site-of-care migration toward home infusion fragments hospital outpatient capture and forces reimbursement redesign. Medicaid programs and commercial pharmacy benefit managers exhibit the highest price sensitivity, while academic medical center bundled payment arrangements demonstrate greater tolerance for premium-tier curative modalities.
Supply Chain Analysis
Extended cold-chain lead times for temperature-sensitive biologics strain inventory positioning across dispersed rare disease treatment networks. Mammalian cell culture capacity concentrates in Switzerland, the United States, and Germany, with contract development and manufacturing organizations in Basel and Boston anchoring recombinant enzyme production. Supply rests on porcine trypsin, chemically defined cell culture media, and single-use bioreactor consumables as critical inputs. Single-source vulnerability in viral vector manufacturing for gene therapy programs threatens rollout timelines as lentiviral platform competition intensifies. Distribution runs through hub-and-spoke rare disease networks linking centralized manufacturing to regional infusion pharmacies and home nursing agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alpha mannosidosis market rewards developers commanding scarce capabilities in lentiviral vector manufacturing and pediatric-to-adult transition clinic infrastructure. Mastery of these assets determines competitive endurance as mechanistic paradigms shift from chronic maintenance toward curative intent.
For Market Incumbents: Secure exclusive bioreactor capacity reservations in Swiss and United States contract manufacturing organizations before gene therapy substitution accelerates. Lock in long-term home nursing network partnerships to defend patient volume as site-of-care migration fragments traditional hospital capture. Vertical integration into vector manufacturing capabilities offers the strongest defensive lever against emerging gene therapy specialists threatening enzyme replacement revenue durability. For New Entrants and Emerging Players: Adult transition clinic coordination services represent the most penetrable white-space target as aging patient cohorts outgrow pediatric metabolic centers in the United States metropolitan markets. Substrate reduction therapy positioning for milder phenotypes offers secondary entry point with lower manufacturing capital requirements than biologic platforms. A go-to-market angle bundling biochemical testing with therapeutic protocols creates diagnostic stickiness among treatment-naïve patients identified through newborn screening expansion. For Investors and Strategic Acquirers: Capital is best deployed toward gene therapy platform developers with demonstrated hematopoietic stem cell transduction efficiency and existing FDA Rare Pediatric Disease Priority Review Voucher eligibility. Long-term viability in this market hinges on curative intent data packages that can command premium reimbursement against chronic maintenance alternatives. The signal to watch is pivotal trial readouts for lentiviral programs, which will determine whether manufacturing investment shifts decisively from enzyme replacement toward vector production infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Regulatory Submission | FDA Rare Pediatric Disease Priority Review Voucher eligibility compresses commercialization timelines for curative modalities. |
| Manufacturing Scale-Up Partnership | CDMO alliances in Basel and Boston determine geographic rollout priority for lentiviral vector supply. |
| Adult Transition Clinic Network | Underserved patient cohorts aging out of pediatric centers in Philadelphia and San Francisco represent untapped lifetime value. |
| Companion Diagnostic Integration | Biochemical and next-generation sequencing test bundling creates stickiness with treatment-naïve patients. |
| Home Infusion Infrastructure | Regional nursing agencies and cold-chain logistics providers enable site-of-care migration from hospitals to residential settings. |
Methodological Framework
A spread of perspectives from pediatric metabolic specialists, gene therapy development executives, payer access specialists, and home infusion network operators converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders were cross-validated against secondary sources including FDA orphan drug designations, EMA protocol assistance records, ClinicalTrials.gov enrollment data, and state-level newborn screening mandate documentation. Bottom-up patient flow modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Segmentation dimensions modeled encompass treatment modality, delivery route, end-user setting, and diagnostic test type alongside regional regulatory cluster differentiation. CAGRs were derived from natural history study enrollment trajectories, therapy penetration curves in screened versus unscreened birth cohorts, and gene therapy substitution elasticity assumptions. Forecast inputs incorporated bioreactor capacity expansion timelines, home nursing network growth rates, and newborn screening mandate adoption patterns across state jurisdictions.
Forecasts assume regulatory continuity in FDA Rare Pediatric Disease and EMA orphan drug frameworks; material policy shifts would require re-modeling of commercial timeline assumptions and exclusivity value capture. Revision becomes warranted when gene therapy pivotal trial data crosses efficacy thresholds that trigger accelerated prescriber adoption away from enzyme replacement protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
AI in Pharma and Biotech Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market