
 Asia-Pacific Cell and Gene Therapy Thawing Equipment Market | 2026-2036
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market Outlook
China's biomanufacturing corridor from Shanghai to Suzhou is rewriting regional supply dynamics for precision thawing systems. Cytiva leverages its chromatography and bioprocessing heritage to extend into controlled-rate thawing workflows for cell therapy manufacturers. Thermo Fisher Scientific anchors its position through integrated cold-chain instrumentation spanning cryogenic storage to endpoint thawing. Sartorius competes with single-use technologies that reduce cross-contamination risk in multi-product facilities.
Cell and gene therapy thawing equipment encompasses automated, manual, hybrid, and water bath systems designed to restore cryopreserved cellular products to viable temperatures with precise thermal uniformity, typically maintaining ramp rates within manufacturer-specified ranges to preserve membrane integrity and therapeutic potency. These systems serve research laboratories, biotechnology firms, pharmaceutical companies, and hospitals where deviation from validated thawing protocols can compromise cell viability and regulatory batch release. Automated systems dominate capital expenditure among commercial-stage cell therapy producers due to protocol reproducibility requirements and audit trail documentation. Manual and water bath configurations retain share in early-stage research settings where throughput demands remain modest and budget constraints favor simpler instrumentation.
Japan's PMDA enforces stringent validation protocols for regenerative medicine manufacturing equipment, while Australia's TGA aligns with PIC/S guidance on cell therapy product handling. China's NMPA has issued draft technical standards for cell preparation facility equipment that encompass thawing system qualification. South Korea's MFDS requires documented temperature mapping for critical processing steps in advanced therapy medicinal product facilities. Stakeholders must monitor harmonization between national pharmacopeial standards and ISO 20399 guidance on ancillary materials to anticipate equipment qualification burden shifts.
Market Dynamics
Japan's PMDA validation protocols for regenerative medicine equipment are forcing commercial-stage cell therapy manufacturers to replace manual thawing workflows with automated systems that generate auditable temperature ramp documentation.
Growth Catalysts
- China's NMPA Draft Technical Standards:The regulator's equipment qualification requirements for cell preparation facilities are accelerating GMP-compliant thawing infrastructure deployment across Shanghai and Suzhou biotech clusters.
- Single-use technology adoption:Multi-product cell therapy facilities are prioritizing disposable thawing chamber liners to eliminate cross-contamination risk between patient-specific batches.
- South Korea's MFDS temperature mapping mandates:Documented thermal validation for critical processing steps is driving replacement of water bath systems in advanced therapy medicinal product facilities.
Market Restraints
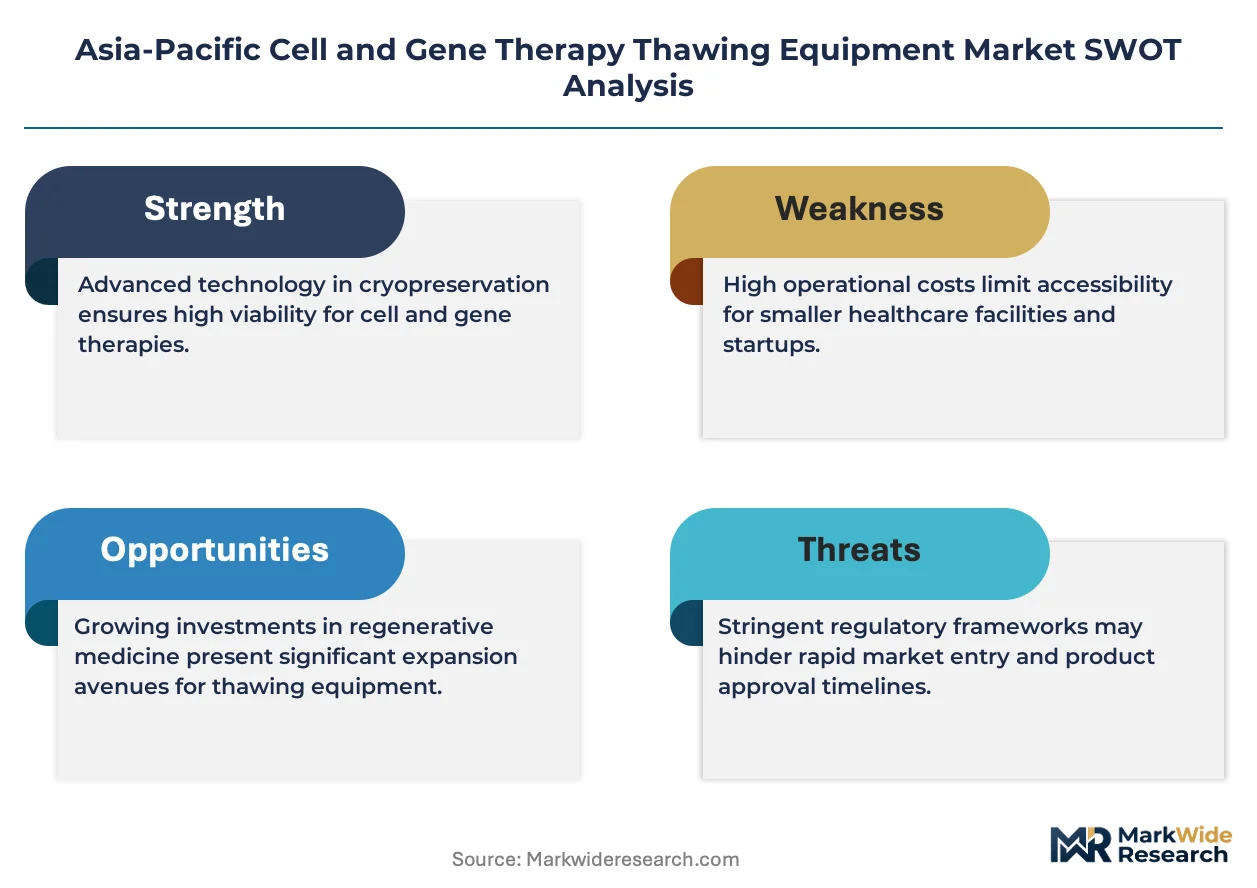
- Stainless steel supply concentration:Precision-grade 316L chambers for controlled-rate thawing systems face input cost volatility from concentrated Asian metal suppliers.
- Liquid nitrogen infrastructure gaps:Cryogenic warming protocols require reliable LN2 supply chains that remain underdeveloped in secondary Australian and Southeast Asian cities.
- PMDA-TGA harmonization friction:Divergent equipment validation timelines between Japan's PMDA and Australia's TGA create dual-qualification burdens for regional manufacturers.
Strategic Opportunities
- India's CDSCO pathway expansion:The regulator's emerging framework for cell therapy manufacturing equipment presents first-mover positioning for thawing system vendors ahead of formalized standards.
- Integrated cold-chain instrumentation:Convergence of cryogenic storage monitoring with endpoint thawing data logging enables single-vendor workflow contracts.
- Contract manufacturing organization channel:Asia-Pacific CDMOs building cell therapy capacity represent a concentrated procurement channel bypassing direct pharmaceutical sales cycles.
Industry Challenges
- Cryobiology technician scarcity:Validated thawing protocol execution requires specialized personnel that outpace regional training program output.
- ISO 20399 harmonization delays:Ancillary materials guidance remains inconsistently interpreted across national pharmacopeial standards, complicating multi-country equipment qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cell and Gene Therapy Thawing Equipment Market |
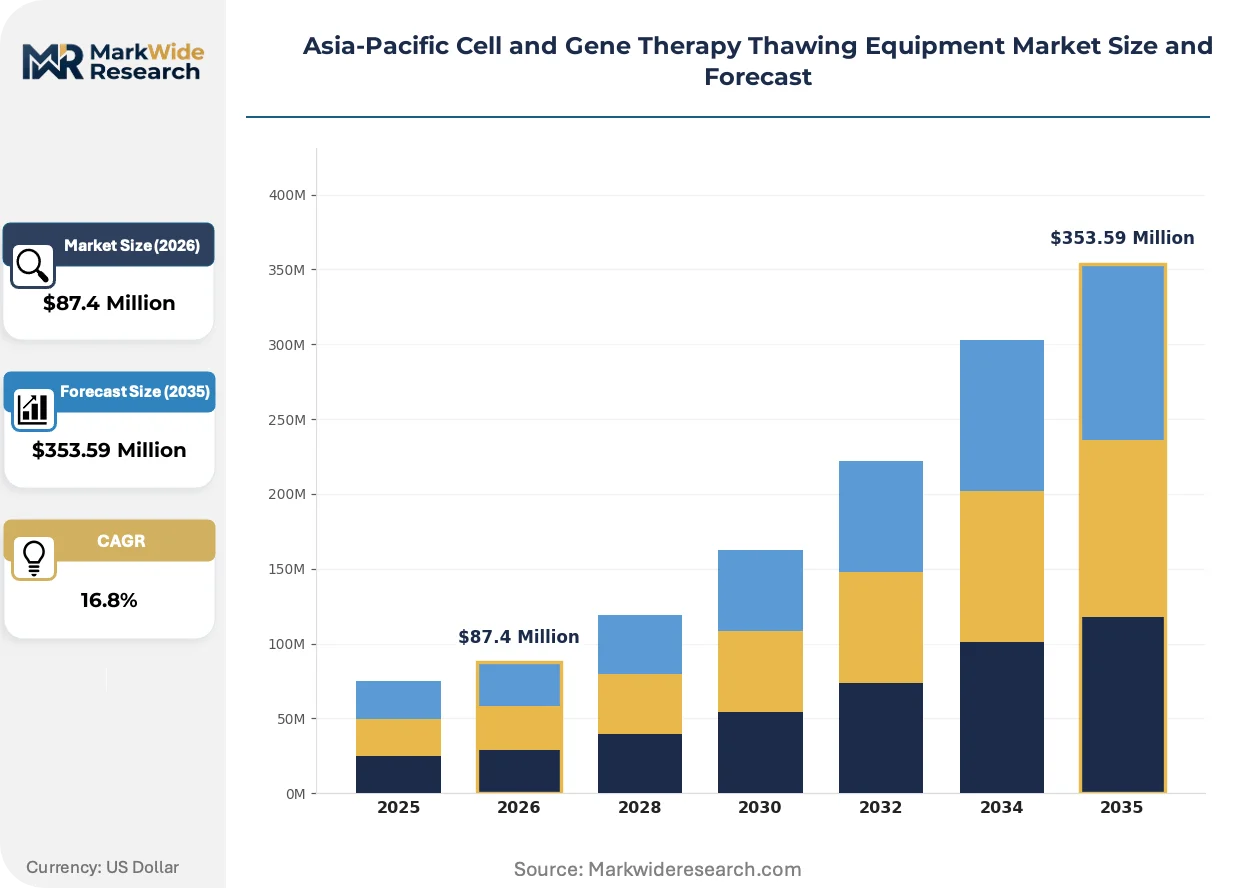
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $353.59 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Hybrid Systems, Water Bath End User: Research Laboratories, Biotechnology Firms, Pharmaceutical Companies, Hospitals Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Installation: Tabletop, Benchtop, Floor-mounted, Custom-built |
| Companies Covered | Cytiva, BioLife Solutions, Thermo Fisher Scientific, Helmer Scientific, Sartorius, Barkey, BioCision, GE HealthCare, PHC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market Strategic Shifts
Digital thermal profiling and remote monitoring capabilities are compressing the validation burden for distributed cell therapy manufacturing networks across the Asia-Pacific region.
Programmable ramp-rate thawing chambers with embedded sensors are virtualizing the documentation workflow that previously required manual temperature logging and paper batch records. Commercial-stage cell therapy producers in Japan and South Korea are adopting these systems at replacement cycle intervals of 18-24 months. The technology is virtualizing compliance labor, reducing headcount requirements for quality assurance functions while accelerating regulatory submission timelines.
Australia's TGA alignment with PIC/S guidance on cell therapy product handling is tightening temperature excursion documentation requirements for imported cellular products. The policy shift forces thawing equipment vendors to embed redundant data logging that satisfies both TGA and originating jurisdiction standards. CDMOs serving multiple Asia-Pacific markets are responding by specifying dual-compliant systems in procurement tenders.
After-sales service unbundling is fragmenting the traditional capital equipment sales model. Cell therapy developers in China's biotech corridors are separating hardware acquisition from validation support contracts, pressuring vendors to price training and protocol development as standalone services. This pattern is most visible among mid-stage biotechnology firms in Suzhou Industrial Park that lack internal cryopreservation expertise.
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market Segmentation
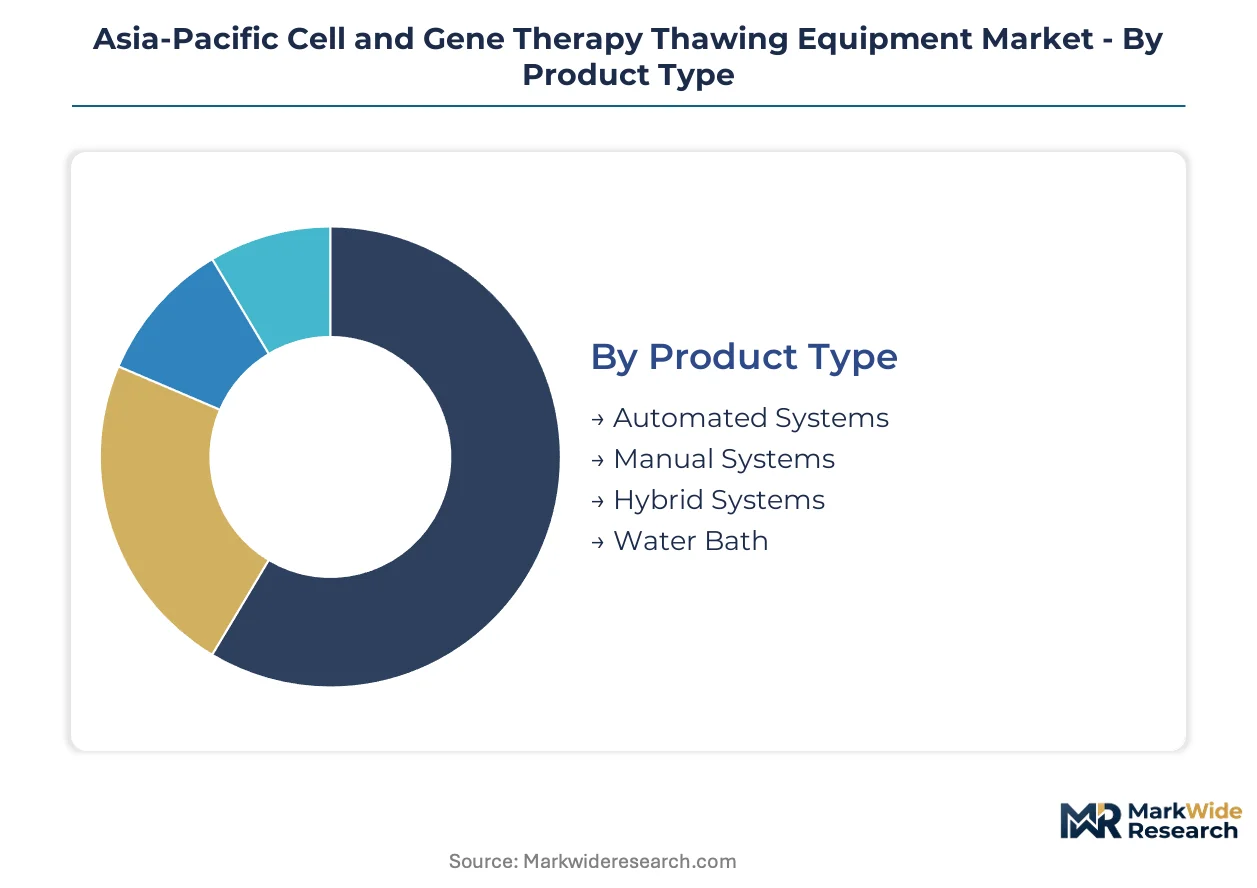
Segmentation in this market reflects divergent capital deployment strategies across clinical development stages. Equipment specifications vary sharply between research-scale flexibility requirements and commercial manufacturing's protocol rigidity demands.
Product Type:
Cost tier determines procurement patterns, with capital intensity separating commercial-stage adopters from research-grade purchasers.
- Automated Systems:Programmable ramp-rate chambers with embedded thermal sensors generate auditable batch records for regulatory submission. Japan's PMDA validation mandates are concentrating demand among commercial cell therapy producers replacing manual workflows in Osaka and Kobe manufacturing clusters.
- Manual Systems:Operator-dependent thawing apparatus with basic temperature monitoring serves early-phase research where protocol flexibility outweighs documentation burden. China's Suzhou biotech corridor shows persistent manual system procurement among pre-clinical stage firms prioritizing capital conservation.
- Hybrid Systems:Semi-automated configurations blending manual oversight with digital logging bridge validation gaps for mid-stage developers.
- Water Bath:Immersion-based thawing retains share in academic settings across Australia where throughput demands remain modest.
Automated systems hold installed capacity. Hybrid systems are rotating up the share rankings.
End User:
Application context shapes specification requirements, with therapeutic intent driving compliance intensity.
- Biotechnology Firms:Venture-backed cell therapy developers in Shanghai and Suzhou are scaling GMP-compliant thawing infrastructure ahead of IND submissions, prioritizing systems with dual NMPA-PMDA qualification pathways.
- Pharmaceutical Companies:Multinational manufacturers integrate thawing stations into closed-system manufacturing trains, demanding vendor validation support for multi-jurisdiction filings.
- Research Laboratories:Academic and institutional settings across South Korea maintain mixed fleets of manual and automated units for protocol development work.
- Hospitals:Point-of-care thawing for autologous therapies drives compact footprint requirements in Japan's designated regenerative medicine hospitals.
Biotechnology firms command procurement volume. Pharmaceutical companies are climbing the fastest in specification intensity.
Capacity:
Volume tier aligns with manufacturing scale, with batch size requirements dictating chamber geometry and thermal uniformity specifications.
- High Capacity:Multi-vessel chambers processing 10+ liters of cryopreserved product support allogeneic therapy commercialization. South Korea's MFDS temperature mapping mandates are accelerating replacement of lower-capacity units in advanced therapy medicinal product facilities.
- Ultra High Capacity:Industrial-scale systems for centralized manufacturing serve regional supply hub strategies, particularly in China's planned cell therapy industrial parks.
- Medium Capacity:Standard commercial batch sizes dominate current installed base across Asia-Pacific CDMOs.
- Low Capacity:Single-vessel configurations serve early clinical trials and autologous patient-specific production.
High capacity dominates capital expenditure. Ultra high capacity is gaining share fastest in greenfield facility planning.
Installation:
Physical configuration responds to facility constraints, with floor space economics and cleanroom classification driving form factor selection.
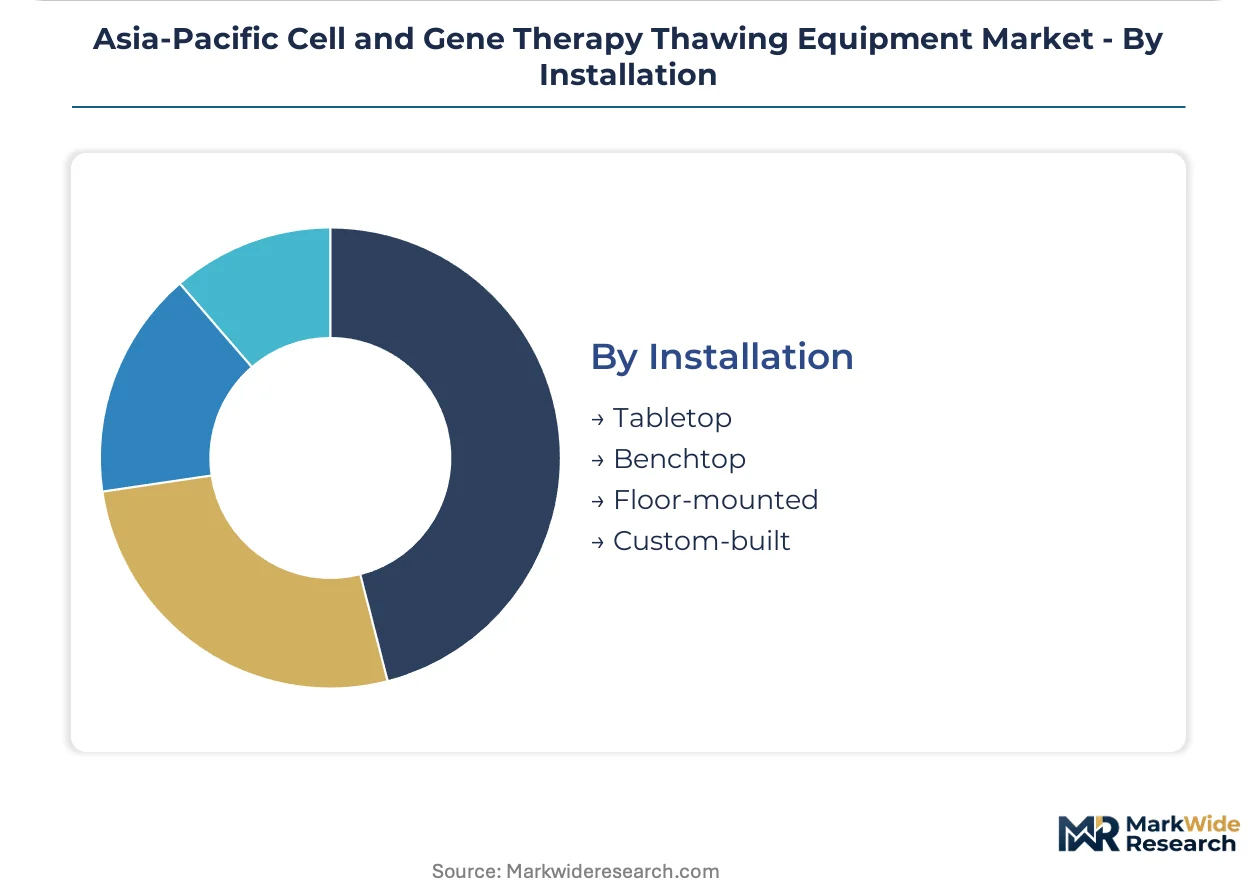
- Floor-mounted:Fixed-position systems with integrated LN2 supply connections anchor commercial manufacturing suites. Australia's TGA alignment with PIC/S guidance is tightening specifications for permanent installation validation documentation.
- Benchtop:Compact units with flexible utility connections serve multi-product facilities requiring rapid reconfiguration between campaigns.
- Tabletop:Portable configurations support distributed manufacturing models and hospital-based therapy preparation.
- Custom-built:Engineered solutions for integrated manufacturing trains address specific cleanroom layouts and workflow sequencing.
Floor-mounted systems anchor commercial capacity. Benchtop configurations are expanding most quickly in CDMO facility buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision-grade 316L chamber fabrication concentrates among Japanese and South Korean metal suppliers, creating input cost exposure for thawing system manufacturers across the region.
China
Shanghai and Suzhou biotech clusters are scaling GMP-compliant thawing infrastructure ahead of IND submissions. NMPA draft technical standards for cell preparation facility equipment are accelerating qualification timelines. Suzhou Industrial Park hosts mid-stage biotechnology firms separating hardware acquisition from validation support contracts.
Japan
Osaka and Kobe manufacturing clusters are replacing manual thawing workflows with automated systems. PMDA validation protocols for regenerative medicine equipment mandate auditable temperature ramp documentation. Designated regenerative medicine hospitals drive compact footprint requirements for point-of-care thawing.
South Korea
Advanced therapy medicinal product facilities are replacing water bath systems under MFDS temperature mapping mandates. Seoul-based CDMOs building cell therapy capacity represent concentrated procurement channels. Documented thermal validation for critical processing steps is accelerating replacement cycles to 18-24 months.
Australia
TGA alignment with PIC/S guidance is tightening temperature excursion documentation for imported cellular products. Sydney and Melbourne CDMOs are specifying dual-compliant systems in procurement tenders. Permanent installation validation documentation requirements are reshaping commercial manufacturing suite specifications.
India
CDSCO's emerging framework for cell therapy manufacturing equipment presents first-mover positioning opportunities. Bangalore and Hyderabad biotech corridors are building cryopreservation workflows ahead of formalized standards. Venture-backed cell therapy developers are prioritizing systems with dual qualification pathways for future NMPA-PMDA submissions.
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the precision chamber and sensor supply chain. The vendor base spans multinational life science conglomerates with chromatography and bioprocessing heritage, mid-scale cold-chain instrumentation specialists, and regional fabricators serving price-sensitive research settings. Three archetypes dominate: integrated workflow providers bundling storage-to-thawing data logging, single-use technology specialists reducing cross-contamination risk, and precision thermal engineering firms optimizing ramp-rate uniformity. Capacity expansion and strategic partnerships represent the dominant competitive moves, with vendors securing validation support contracts separate from hardware sales.
Among the integrated platform tier, Cytiva leverages its bioprocessing heritage into controlled-rate thawing workflows, while Thermo Fisher Scientific anchors its position through cold-chain instrumentation spanning cryogenic storage to endpoint thawing. Sartorius occupies a position within the single-use technology tier, competing with disposable thawing chamber configurations for multi-product facilities. These three exemplify the strategic divergence between workflow integration and modular flexibility that defines competitive positioning in Asia-Pacific cell therapy manufacturing infrastructure.
| Leading Market Players |
|---|
| Cytiva |
| BioLife Solutions |
| Thermo Fisher Scientific |
| Helmer Scientific |
| Sartorius |
| Barkey |
| BioCision |
| GE HealthCare |
| PHC Corporation |
| Others |
Value Chain & Pricing Dynamics
Japanese and South Korean precision-grade 316L stainless steel suppliers anchor upstream chamber fabrication, concentrating margin capture in the metals tier while thawing system assemblers compete on validation service bundling downstream.
Pricing Analysis
PMDA validation protocols dictate the pricing tier structure across the Asia-Pacific region, separating premium automated systems with full audit trail documentation from standard manual configurations and economy water bath units. Price differentiation rests on certification grade for multi-jurisdiction qualification and after-sales service bundling for protocol development support. Cost compression in the standard tier is intensifying because mid-stage biotechnology firms in Suzhou Industrial Park are unbundling hardware acquisition from validation contracts. Early-stage research laboratories exhibit the highest price sensitivity, while commercial-stage cell therapy producers prioritize qualification pathway breadth over unit cost.
Supply Chain Analysis
Contract manufacturing capacity for precision thermal chambers concentrates among Japanese metal fabricators and South Korean sensor integrators, with final system assembly distributed across regional hubs. Geographic supply concentration centers on Japan, South Korea, and China for precision-grade 316L chambers, embedded thermal sensors, and LN2 handling components. Single-source vulnerability runs through concentrated stainless steel suppliers facing input cost volatility. Distribution feeds from direct vendor relationships with biotechnology firms and concentrated procurement channels through Asia-Pacific CDMOs building cell therapy capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific cell and gene therapy thawing equipment market represents a high-growth disruption driven by PMDA validation mandates forcing automated system replacement cycles and NMPA draft standards accelerating GMP infrastructure deployment.
For Market Incumbents: Build switching-cost moats through integrated cold-chain data logging that spans cryogenic storage to endpoint thawing, locking in multi-year service contracts. Deepen captive supply of precision-grade 316L chambers to defend margin position against input cost volatility from Japanese and South Korean metal suppliers. Expand validation support capacity in Shanghai and Suzhou to capture unbundled service demand from mid-stage biotechnology firms lacking internal cryopreservation expertise. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO pathway ahead of formalized cell therapy manufacturing equipment standards, positioning for first-mover advantage in Bangalore and Hyderabad biotech corridors. Target hybrid system configurations for mid-stage developers bridging manual flexibility and digital compliance documentation. Pursue channel partnerships with Asia-Pacific CDMOs as a concentrated procurement pathway bypassing direct pharmaceutical sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cold-chain instrumentation specialists seeking platform expansion into cell therapy workflows. Five-to-ten year viability hinges on regulatory harmonization momentum across PMDA, NMPA, and MFDS jurisdictions. Monitor NMPA finalization of cell preparation facility equipment standards as the critical inflection signal for infrastructure deployment acceleration in China's biotech clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Support Unbundling | Suzhou biotechnology firms now separate hardware purchase from protocol development contracts, reshaping vendor revenue models. |
| Dual-Jurisdiction Qualification Investment | Systems certified for both PMDA and NMPA pathways command procurement preference among multinational cell therapy developers. |
| Single-Use Technology Expansion | Disposable thawing chamber liners eliminate cross-contamination risk in multi-product facilities across South Korean CDMOs. |
| Integrated Data Logging Development | Convergence of cryogenic storage monitoring with endpoint thawing documentation enables single-vendor workflow contracts. |
| Regional Service Capacity Buildout | After-sales validation support centers in Shanghai and Osaka reduce compliance labor for quality assurance functions. |
Study Parameters
Initial hypotheses were tested against primary input from cell therapy manufacturing executives, regulatory affairs specialists at PMDA and NMPA, CDMO procurement directors, and cryobiology laboratory managers, then refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and ISO 20399 guidance documents. Bottom-up equipment procurement data from Shanghai, Suzhou, Osaka, and Seoul biotech clusters was triangulated with top-down market sizing across automated, manual, hybrid, and water bath system categories.
Demand-supply balance modeling anchored the analytical framework, with segmentation across product type, end user, capacity tier, and installation configuration throughout the projection horizon. CAGRs were derived from replacement cycle analysis, greenfield facility planning pipelines, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated PMDA validation protocol enforcement rates and NMPA draft standard finalization trajectories.
Macroeconomic conditions sit as an overlay; deviation in biotechnology venture funding availability, stainless steel commodity pricing, or cross-border equipment tariff structures would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization momentum and CDMO capacity expansion cadence. Quarterly review of NMPA standard finalization, PMDA inspection enforcement data, and regional LN2 infrastructure development indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market