
 Cell Therapy Market | 2026-2036
Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Market Intelligence
The development of allogeneic, or 'off-the-shelf', cell therapies is redrawing the competitive landscape from its autologous-centric model. This shift promises to reduce manufacturing complexity and treatment costs. Novartis AG sustains its market position through its pioneering work in CAR-T cell therapies. Gilead Sciences, Inc. competes by expanding its oncology and cell therapy pipeline. Bristol-Myers Squibb Company differentiates itself with a broad portfolio of approved cell therapy products for various indications.
Cell therapy is a medical treatment that involves introducing new, healthy cells into a patient's body to treat or cure a disease. This process often involves the ex vivo genetic modification of cells, such as T-cells or stem cells, before reinfusion to target specific pathological conditions. The Oncology segment commands the largest share within therapy areas, driven by breakthroughs in cancer treatment. Among product types, CAR-T Cell Therapy shows significant momentum, particularly for hematological malignancies.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) is critical for market entry. Their specific pathways for advanced therapies, such as the FDA's RMAT designation and the EMA's PRIME scheme, influence clinical trial design and approval timelines. Navigating the complex manufacturing and logistical challenges to ensure patient access remains a central focus for all stakeholders.
Market Dynamics
The structural shift from bespoke autologous therapies to scalable allogeneic platforms is the central force shaping the cell therapy market. This transition redefines manufacturing logistics, cost structures, and the competitive requirements for market participants, favoring industrial-scale production capabilities.
Growth Catalysts
- Accelerated Regulatory Pathways:Frameworks such as the FDA's RMAT designation and the EMA's PRIME scheme shorten development and review timelines for qualifying therapies, incentivizing investment in innovative treatments for serious conditions.
- Genetic Engineering Advances:The maturation of gene-editing tools like CRISPR-Cas9 enables more precise and efficient modification of cells. This enhances the safety and efficacy of next-generation therapies, particularly for complex diseases like cancer.
- Concentrated Research Investment:High levels of public and private funding in biotechnology hubs within the United States and Europe create dense ecosystems for advanced cell therapy research, clinical trials, and commercialization.
Market Restraints
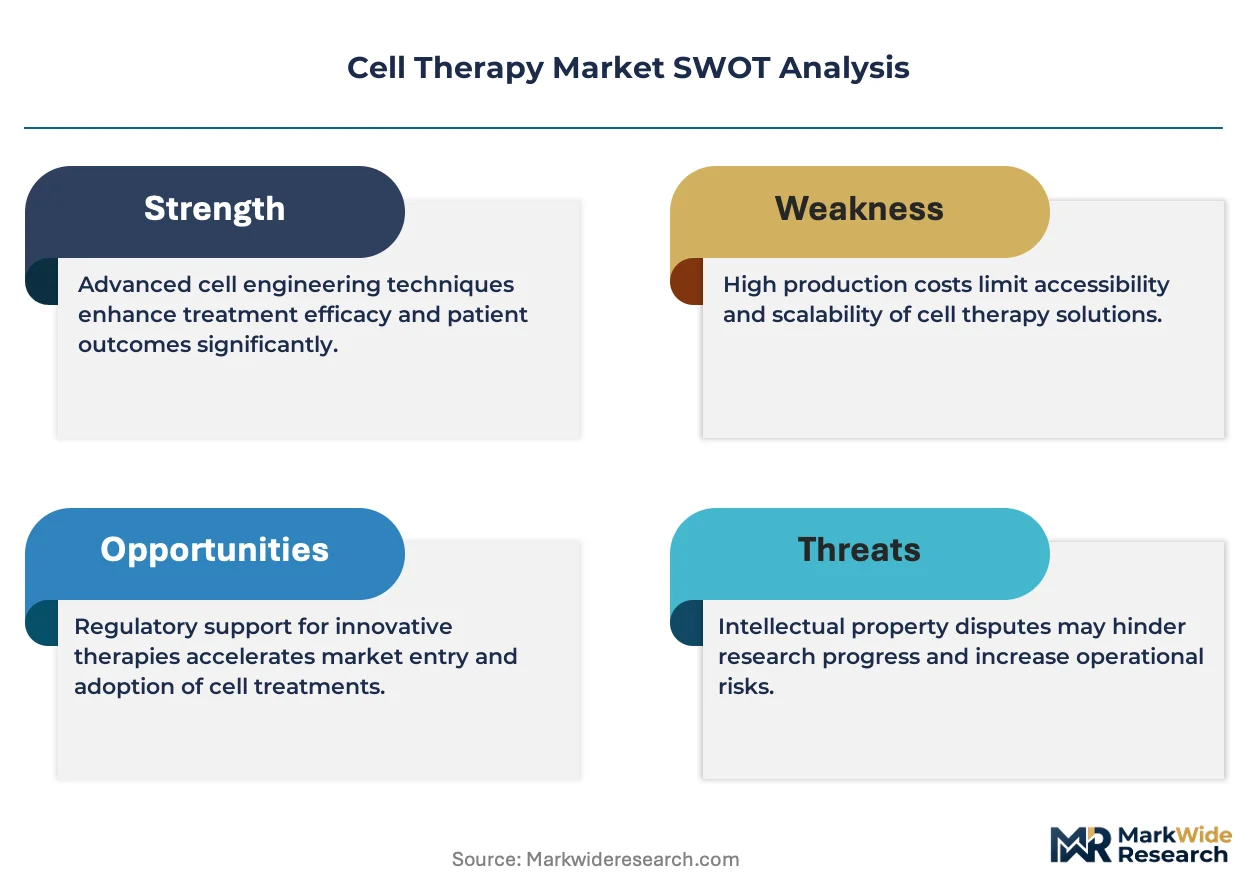
- Prohibitive Treatment Costs:The high price of autologous cell therapies, driven by personalized manufacturing and complex logistics, limits patient access and creates significant reimbursement challenges for healthcare systems globally.
- Complex Cold-Chain Logistics:Ensuring the viability of living cellular products from manufacturing site to patient requires a stringent, cryopreserved supply chain. This creates logistical bottlenecks and increases the risk of product failure.
- Immunogenicity Risks:Allogeneic, or 'off-the-shelf', therapies face the significant technical barrier of potential immune rejection by the patient's body, which can limit their durability and safety profile.
Strategic Opportunities
- Expansion into Autoimmune Diseases:While oncology currently dominates, applying cell therapy principles to treat autoimmune disorders like lupus or multiple sclerosis represents a substantial, largely untapped clinical and commercial opportunity.
- Integration with Artificial Intelligence:Leveraging AI and machine learning to analyze patient data can optimize patient selection for specific therapies and predict treatment outcomes, enhancing efficacy and personalizing care.
- Penetration of Asian Markets:Developing therapies tailored to prevalent cancers in Asia-Pacific and navigating the evolving regulatory landscapes of countries like China and Japan offers access to large patient populations.
Industry Challenges
- Specialized Talent Shortages:A critical gap exists for personnel with expertise in Good Manufacturing Practice (GMP) for cell therapies, process development, and quality control analytics, constraining industry-wide production capacity.
- Lack of Manufacturing Standardization:The absence of universally accepted standards for cell processing, characterization, and potency assays complicates regulatory comparisons and hinders the ability to scale production reliably across different sites.
- Complex Intellectual Property Landscape:Overlapping patents related to gene-editing tools, vector technologies, and CAR constructs create significant licensing hurdles and increase the risk of litigation for therapy developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Market |
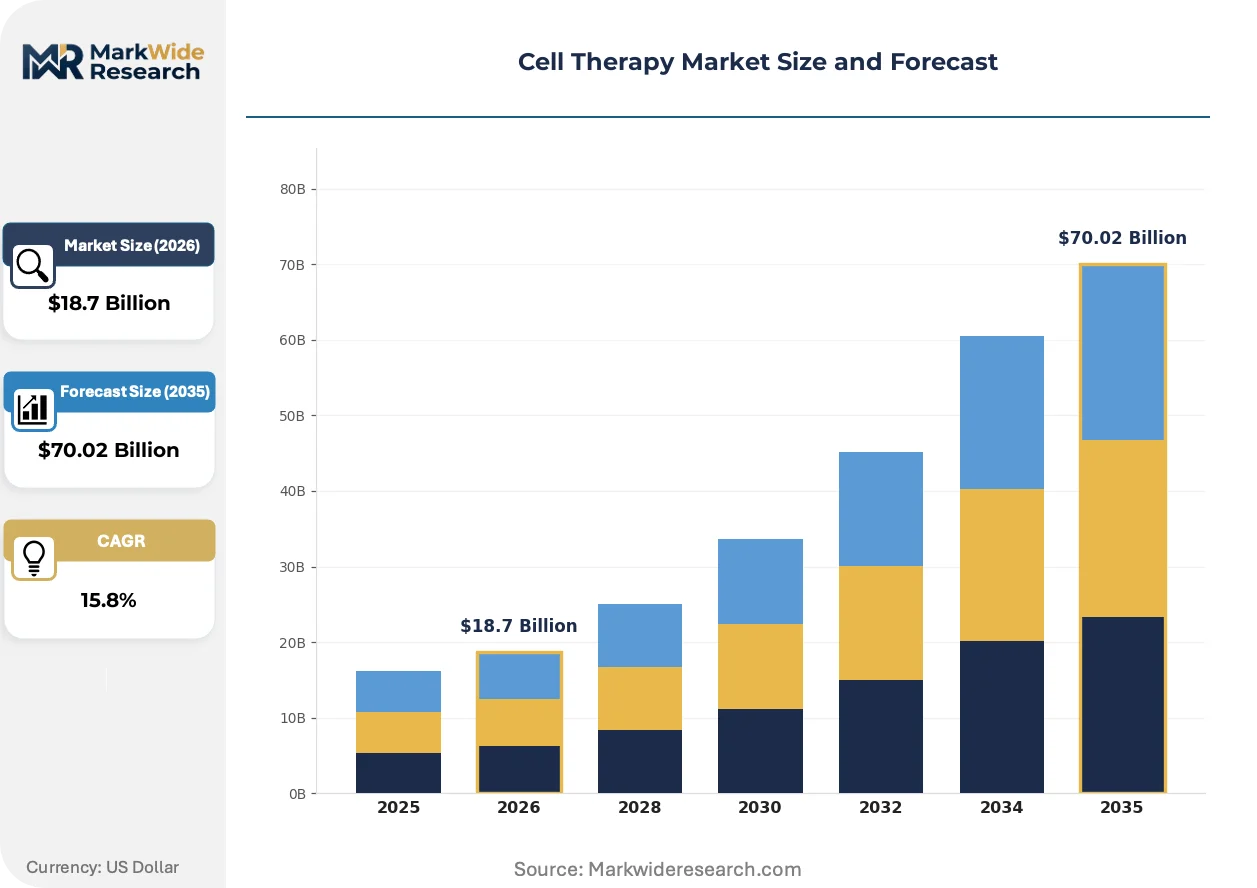
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $70.02 Billion |
| CAGR (2026 – 2036) | 15.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Cell Therapy, Stem Cell Therapy, Dendritic Cell Therapy, Natural Killer Cell Therapy, CAR-T Cell Therapy Therapy Area: Oncology, Autoimmune Disorders, Neurological Diseases, Cardiovascular Diseases, Genetic Disorders End User: Specialty Clinics, Research Institutions, Biotechnology Companies, Academic Hospitals, Contract Research Organizations Delivery Technology: Injection, Infusion, Implantation, Electroporation, Microfluidic Devices |
| Companies Covered | Novartis AG, Gilead Sciences, Inc., Bristol-Myers Squibb Company, Johnson & Johnson Services, Inc., Thermo Fisher Scientific Inc., Merck KGaA, Fate Therapeutics, Bluebird Bio Inc., Adaptimmune Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Market Strategic Shifts & Innovations
The industrialization of cell therapy is defining the current market trajectory. This evolution moves treatment development from a highly customized, academic process toward a more standardized, scalable, and commercially viable model, impacting everything from product design to clinical delivery.
Advanced gene-editing platforms enable the creation of modular cell therapy constructs. These systems are being adopted by biopharmaceutical companies to develop next-generation treatments targeting solid tumors and other complex indications. This modular approach is decomposing the monolithic design of early-generation CAR-T cells into a toolkit of swappable components, which accelerates the design-build-test cycle for new therapeutic candidates.
Regulatory frameworks are adapting to the unique nature of these advanced medicines. The European Medicines Agency's (EMA) PRIME scheme offers early and enhanced dialogue to developers of promising therapies, streamlining their path to market. This initiative particularly benefits smaller biotechnology firms in Europe focused on rare diseases, providing them with crucial guidance to navigate the complex authorization process for advanced therapy medicinal products.
A notable shift in operational strategy involves moving toward decentralized manufacturing models. This trend challenges the established paradigm of large, central production sites by establishing smaller, automated manufacturing units at or near major treatment centers. This model is gaining visibility in the United States, where academic medical centers are implementing point-of-care production to reduce turnaround times and logistical complexity.
Cell Therapy Market Segmentation
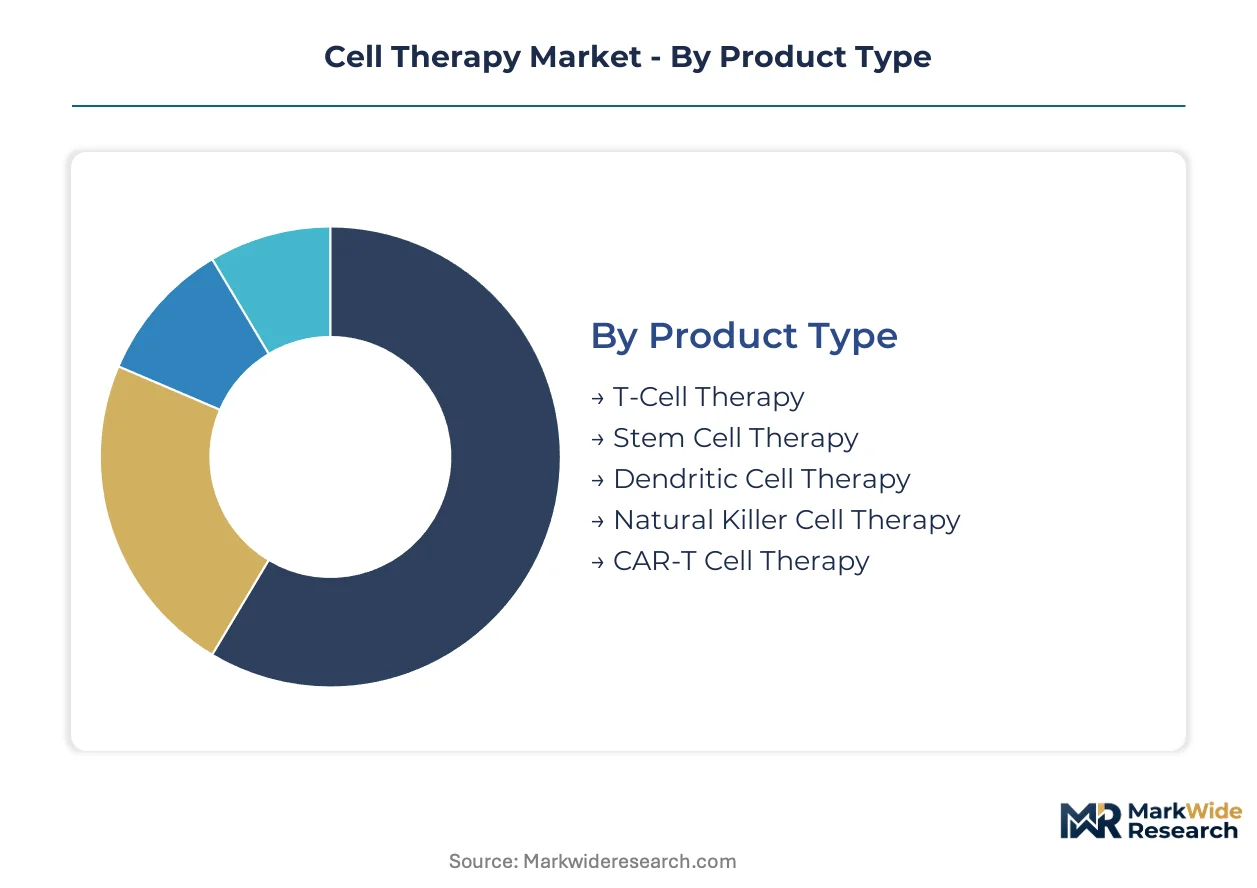
Segmentation within the cell therapy market clarifies the diverse technological approaches and therapeutic applications driving innovation. Understanding these distinct segments is crucial for stakeholders to identify areas of concentrated investment and evolving patient needs.
Product Type:
Margin pools within product type concentrate around proprietary CAR-T cell constructs and advanced stem cell therapies.
- CAR-T Cell Therapy:This therapy involves genetically engineering a patient's T-cells to express chimeric antigen receptors, enabling them to target specific cancer antigens. Demand concentrates in the United States due to high investment in oncology research and advanced treatment infrastructure.
- Stem Cell Therapy:This segment utilizes undifferentiated cells capable of self-renewal and differentiation into various specialized cell types, often applied in regenerative medicine. Demand concentrates in Europe for treating neurological diseases, driven by ongoing clinical trials and regulatory support.
- T-Cell Therapy:This category modifies T-lymphocytes to enhance their ability to recognize and destroy diseased cells, particularly in cancer immunotherapy.
- Natural Killer Cell Therapy:This approach harnesses innate immune cells for direct tumor killing and immune modulation, offering an allogeneic treatment option.
- Dendritic Cell Therapy:This therapy employs immune cells to present tumor antigens, stimulating an anti-tumor immune response in patients.
CAR-T Cell Therapy holds installed capacity. Stem Cell Therapy is rotating up the share rankings.
Therapy Area:
Cost tiers within therapy areas vary significantly, with oncology treatments often commanding premium pricing due to their complex development and personalized nature.
- Oncology:This area focuses on treating various cancers through immune cell modification or targeted cell delivery, addressing solid tumors and hematological malignancies. Demand concentrates in the United States, driven by the high prevalence of cancer and significant research and development investment.
- Autoimmune Disorders:This segment aims to modulate or reset the immune system using regulatory T-cells or mesenchymal stem cells, treating conditions like lupus and multiple sclerosis. Demand concentrates in Europe, spurred by increasing clinical trials exploring cell therapies for chronic inflammatory conditions.
- Neurological Diseases:This area targets neurodegenerative conditions and acute injuries using neural stem cells or other regenerative cell types.
- Cardiovascular Diseases:This segment utilizes stem cells to repair damaged heart tissue or improve cardiac function after ischemic events.
- Genetic Disorders:This involves gene-corrected cells or stem cells to replace defective cells, addressing inherited conditions.
Oncology treatments command the largest application volume. Autoimmune Disorders are gaining share fastest.
End User:
Application diversity among end users reflects their specific roles in the cell therapy ecosystem, from research to patient administration.
- Biotechnology Companies:These entities develop, manufacture, and commercialize novel cell therapies, often focusing on advanced genetic engineering platforms. Demand concentrates in the United States, propelled by a robust venture capital ecosystem and skilled scientific workforce.
- Academic Hospitals:These institutions integrate patient care with clinical research, often serving as sites for early-phase clinical trials and specialized cell therapy administration. Demand concentrates in Germany, supported by strong public health infrastructure and research funding.
- Research Institutions:These organizations conduct fundamental and translational research into cell biology, disease mechanisms, and therapeutic applications.
- Specialty Clinics:These facilities provide focused patient care for specific conditions, often administering approved cell therapies under expert supervision.
- Contract Research Organizations:These firms offer outsourced services for clinical trials, regulatory affairs, and manufacturing support to therapy developers.
Biotechnology Companies lead in product development. Academic Hospitals are expanding their clinical trial footprint.
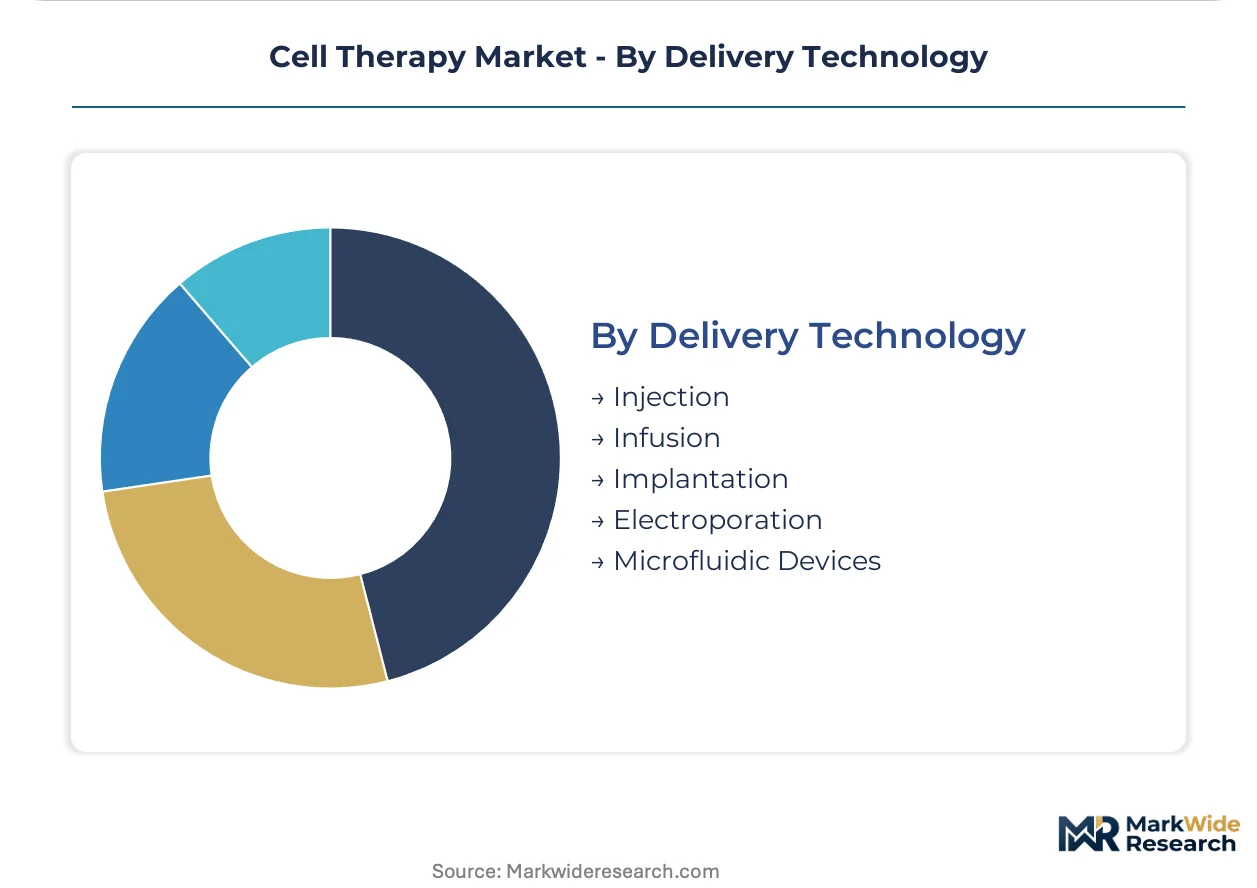
Delivery Technology:
Supply concentration for delivery technologies often aligns with the complexity and invasiveness required for cell administration.
- Infusion:This technology involves the intravenous administration of cell products, commonly used for CAR-T and hematopoietic stem cell transplantation. Demand concentrates in the United States, driven by established clinical protocols and widespread hospital infrastructure.
- Injection:This method facilitates the direct delivery of cell therapies into specific tissues or organs, such as intratumoral or intra-articular injections. Demand concentrates in Japan, where regenerative medicine approaches for localized treatments are gaining traction.
- Implantation:This involves the surgical placement of cell-containing scaffolds or devices into the body for sustained therapeutic effect.
- Electroporation:This technique uses electrical pulses to transiently permeabilize cell membranes, facilitating genetic modification of cells ex vivo.
- Microfluidic Devices:These devices enable precise handling, sorting, and encapsulation of cells for research or therapeutic applications at a small scale.
Infusion techniques remain the most established. Microfluidic Devices are showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy pricing remains high, limiting broad patient access in some regions due to cost constraints. Conversely, areas with strong healthcare budgets and advanced research infrastructure exhibit lower price sensitivity. This creates distinct demand patterns across major global markets, influencing where new therapies are launched and adopted.
United States
Demand for CAR-T cell therapies concentrates in the United States due to high cancer prevalence and significant R&D investment. The US FDA's RMAT designation accelerates approval for promising treatments, incentivizing innovation and market entry. Boston and the San Francisco Bay Area serve as major biotechnology hubs, attracting substantial venture capital for cell therapy development.
Germany
Europe's demand for stem cell therapies, particularly for neurological diseases, is strong in Germany. The EMA's PRIME scheme and national regulatory bodies like the Paul-Ehrlich-Institut guide advanced therapy developers. Munich and Berlin possess dense ecosystems of academic hospitals and research institutions conducting clinical trials for cell therapies.
Japan
Regenerative medicine approaches for localized treatments, especially injection-based cell therapies, are gaining traction in Japan. The PMDA offers expedited review pathways for regenerative medical products, fostering rapid development. Tokyo and Kyoto host specialized clinics and research centers focusing on stem cell applications and tissue engineering.
China
The market in China is driven by a large patient population with prevalent cancers and increasing healthcare investment. The NMPA is streamlining approval processes for innovative cell and gene therapies, encouraging domestic development. Shanghai and Shenzhen are emerging as key hubs for biotechnology companies and contract research organizations in cell therapy.
Switzerland
Switzerland exhibits strong demand for advanced cell therapies, supported by a robust pharmaceutical and biotech industry. Swissmedic provides a clear regulatory framework for advanced therapy medicinal products, facilitating market entry. Basel and Zurich are home to numerous global pharmaceutical companies and specialized research institutions focused on cell therapy innovation.
Cell Therapy Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the cell therapy market. The competitive landscape is tiered, with established pharmaceutical giants operating alongside specialized biotechnology firms and academic spin-offs. Strategic archetypes include integrated developers focusing on end-to-end solutions, platform technology providers offering tools and services, and contract manufacturing organizations scaling production. Dominant competitive moves involve significant R&D investment in novel gene-editing constructs and strategic partnerships for clinical trial execution and market access.
On the integrated developer vector, Novartis AG represents a pharmaceutical company with a pioneering position in CAR-T cell therapies, leveraging its early market entry. Gilead Sciences, Inc. exemplifies a major biopharmaceutical player expanding its oncology and cell therapy pipeline through strategic acquisitions and internal development efforts. Bristol-Myers Squibb Company occupies a position with a broad portfolio of approved cell therapy products across various indications, reflecting significant ongoing investment in advanced therapeutic modalities. These entities anchor the high-value segment of the market, focusing on complex therapeutic solutions.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences, Inc. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson Services, Inc. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Fate Therapeutics |
| Bluebird Bio Inc. |
| Adaptimmune Limited |
Cost & Logistics Intelligence
US FDA's RMAT designation and EMA's PRIME scheme gate both supply qualification and price differentiation simultaneously for advanced cell therapies. These regulatory pathways establish a high bar for product quality and efficacy, influencing market entry and the premium pricing strategies for novel treatments.
Pricing Analysis
After-sales service and ongoing patient monitoring represent significant revenue streams complementing the initial high cost of cell therapies. Value-based pricing models dominate, reflecting the substantial clinical benefits and personalized nature of these treatments. Price differentiation stems from the complexity of genetic engineering and stringent GMP certification levels required for manufacturing. Payer pressure from healthcare systems globally intensifies due to the high cost of autologous therapies, driving demand for more affordable allogeneic options. Academic hospitals and research institutions are generally less price-sensitive for early-stage trials, prioritizing innovative access.
Supply Chain Analysis
Complex cold-chain logistics for cryopreserved cell products underwrites significant supply chain challenges for cell therapies. Geographic supply concentrates in the United States, Germany, and Japan, reflecting advanced research infrastructure and regulatory support. Raw material dependencies include specialized viral vectors for gene delivery and proprietary cell culture media. Single-source vulnerability for these critical reagents poses a structural risk to production continuity. Distribution runs through highly specialized hospital pharmacies and treatment centers equipped to handle living cellular products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell therapy market is defined by a critical scarcity of specialized talent, particularly in GMP manufacturing and process development. This capability gap constrains industrial-scale production and broader patient access.
For Market Incumbents: Consolidate smaller, innovative biotech firms to acquire novel gene-editing platforms and allogeneic therapy candidates. Invest heavily in process automation and closed-system manufacturing to mitigate specialized talent shortages and reduce manufacturing costs. Diversify pipelines beyond oncology into autoimmune disorders to address unmet needs and secure new revenue streams, defending against reimbursement challenges. Strengthen vertical integration into critical raw material production, such as viral vectors, to ensure supply chain resilience.
For New Entrants and Emerging Players: Lead with differentiated technology in niche indications, particularly orphan diseases with high unmet medical need. Target specific Asian markets like Japan, leveraging expedited regulatory pathways for regenerative medicine. Focus on developing modular cell therapy constructs that can be rapidly adapted for various targets, offering a scalable go-to-market angle. Prioritize partnerships with academic research institutions to access early-stage clinical data and specialized expertise, accelerating development timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting in an upward direction across advanced therapy manufacturing, driven by automation and scale-up requirements. Evaluate specialized biotech firms with validated allogeneic platforms or next-generation gene-editing tools as prime acquisition targets. Long-term viability over the next decade depends on successful clinical translation into non-oncology indications and cost-effective manufacturing solutions. The signal to watch is the successful commercialization of 'off-the-shelf' therapies for solid tumors.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Enhances production capacity and reduces per-unit cost for broader market penetration. |
| Regulatory Approval Pathway | Accelerates market entry for innovative therapies through RMAT and PRIME designations. |
| Pipeline Diversification | Expands therapeutic reach beyond oncology into autoimmune and neurological diseases. |
| Strategic Partnership | Leverages complementary expertise for clinical trials and market access in new regions. |
| Acquisition of Specialist Firm | Integrates novel gene-editing technologies and allogeneic platforms into existing portfolios. |
Research Approach
Initial hypotheses were tested against primary input from cell therapy developers, regulatory affairs specialists, clinical oncologists, and hospital administrators, and refined through iterative analysis. This approach combined qualitative insights from in-depth interviews with quantitative validation from secondary sources. Secondary data included FDA and EMA guidance documents, ClinicalTrials.gov, academic publications, and company investor reports, ensuring robust bottom-up and top-down triangulation.
The analytical framework utilized a variance-decomposition approach to project market trajectories across the analysis window. Segmentation dimensions modeled included product type, therapy area, end user, delivery technology, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, projected market drivers, and specific industry inputs like clinical trial success rates and regulatory approval timelines.
Forecasts assume regulatory continuity in the US FDA and EMA regimes; material policy shifts would require re-modeling. The analysis reflects assumptions regarding technological advancements and healthcare expenditure patterns. Practitioners should keep alternative scenarios live as unforeseen clinical trial failures or changes in reimbursement policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market