
 Myeloproliferative Disorders Drugs Market | 2026-2036
Myeloproliferative Disorders Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Myeloproliferative Disorders Drugs Market Analytics
Specialty pharmacy networks is realigning how myeloproliferative disorder therapies reach patients, shifting volume away from traditional hospital dispensing. Novartis AG leverages its oncology infrastructure to sustain leadership in interferon-based polycythemia vera management. Bristol Myers Squibb Company anchors its position through deep hematology expertise and broad institutional access across major treatment centers.
Myeloproliferative disorders drugs comprise pharmaceutical agents targeting clonal hematopoietic stem cell malignancies, with JAK inhibitors such as ruxolitinib functioning as ATP-competitive kinase blockers that modulate dysregulated JAK-STAT signaling pathways implicated in disease pathophysiology. These therapeutics serve to reduce splenomegaly, alleviate constitutional symptoms, and modify disease trajectory in progressive myelofibrosis. JAK Inhibitors command the dominant revenue position due to established efficacy in myelofibrosis and expanding label opportunities, while Interferons retain structural importance in younger polycythemia vera patients seeking cytoreductive options without mutagenic risk. Oral delivery mode captures the majority of prescriptions, though intravenous administration persists for certain hospital-based induction protocols where bioavailability monitoring proves critical.
FDA, EMA, and the EU AI Act collectively shape market access through divergent evidentiary standards for accelerated approval and post-market surveillance requirements. FDA's Project Optimus is pressuring dose-optimization studies that extend development timelines but promise improved long-term safety profiles. EMA's evolving oncology guidelines demand robust quality-of-life endpoints alongside traditional progression metrics. Stakeholders must monitor how regulatory divergence between these frameworks influences trial design and geographic launch sequencing.
Market Dynamics
FDA's Project Optimus is forcing dose-optimization studies that extend development timelines but yield improved long-term safety profiles for JAK inhibitor therapies. This regulatory pressure is reshaping how sponsors design Phase II trials and prioritize pharmacokinetic endpoints over speed-to-market metrics.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy designation compresses regulatory review timelines for novel myelofibrosis treatments. Hematology-oncology departments at academic medical centers fast-track protocol adoption for eligible candidates.
- Specialty Pharmacy Networks:These channels expand patient access beyond traditional hospital dispensing. Oral JAK inhibitors reach previously underserved populations through direct-to-patient distribution models.
- JAK-STAT Biology Advances:Deeper mechanistic understanding of signaling pathway dysregulation enables precision patient stratification. Biomarker-driven enrollment improves response rates in clinical trials.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for kinase inhibitors clusters in China and India. Geopolitical friction or quality enforcement actions disrupt downstream formulation capacity.
- Reimbursement Complexity:Medicare Part D and commercial payers impose step-therapy requirements that delay access to second-line JAK inhibitors. Prior authorization burdens fall on already-constrained clinic staff.
- Long-Term Safety Surveillance:Post-marketing commitments for accelerated approvals demand expensive real-world evidence collection. Sponsors face 10-year follow-up obligations that strain pharmacovigilance infrastructure.
Strategic Opportunities
- Combination Regimen Development:Pairing JAK inhibitors with BET inhibitors or PI3K pathway modulators addresses resistance mechanisms. Early-phase trials in relapsed myelofibrosis show synergistic activity.
- Home Administration Models:Subcutaneous interferon formulations and oral kinase inhibitors shift care from infusion centers to patient residences. This reduces healthcare utilization costs and expands rural access.
- Pediatric Indication Expansion:Juvenile myelomonocytic leukemia and other rare childhood myeloproliferative neoplasms lack approved targeted therapies. Orphan drug incentives support development in this white space.
Industry Challenges
- Hematopathology Talent Scarcity:Accurate diagnosis of myeloproliferative neoplasms requires specialized morphologic expertise. Fellowship-trained pathologists concentrate at tertiary referral centers, creating diagnostic bottlenecks.
- Companion Diagnostic Integration:CALR and JAK2 mutation testing must align with therapy selection workflows. Laboratory information system interoperability gaps delay treatment initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myeloproliferative Disorders Drugs Market |
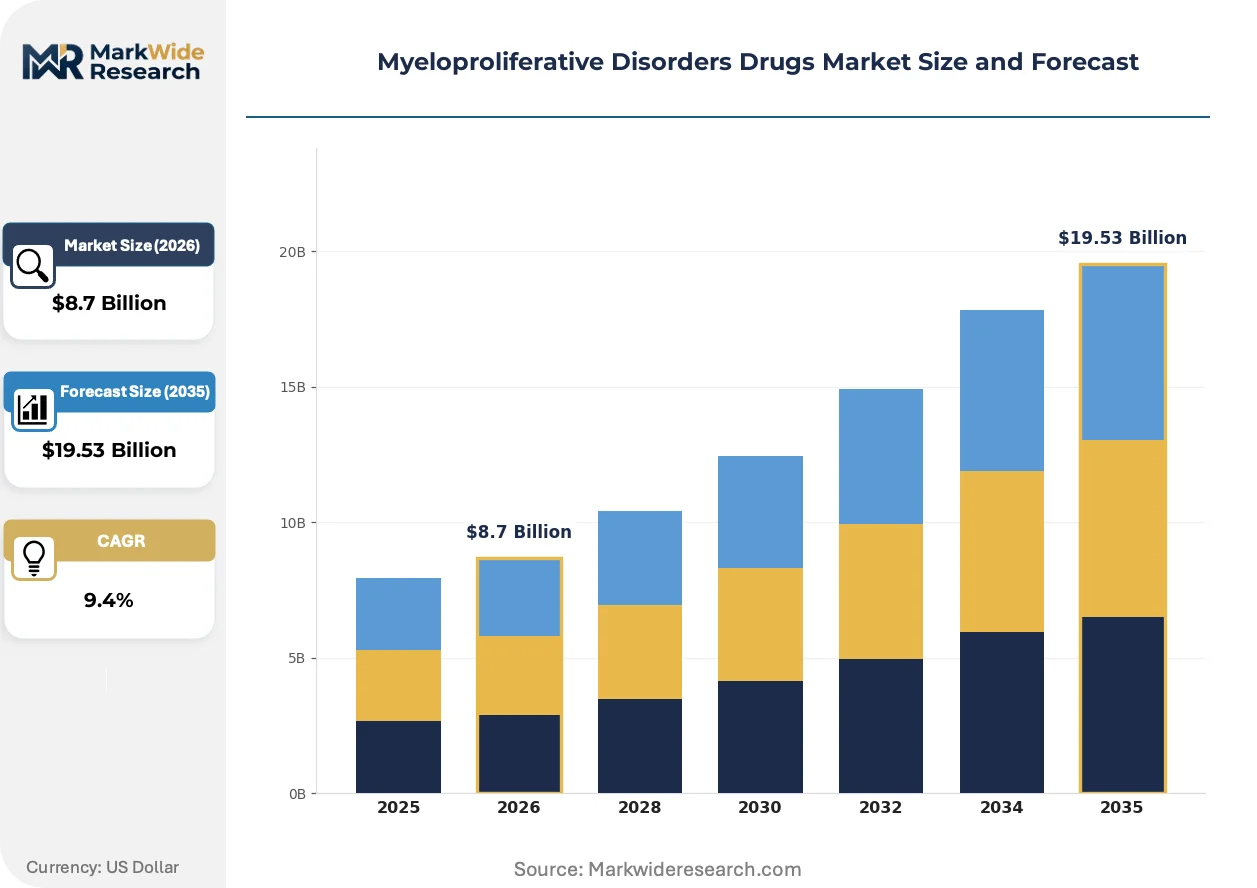
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxyurea, JAK Inhibitors, Interferons, Thalidomide Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Indication: Polycythemia Vera, Essential Thrombocythemia, Myelofibrosis, Atypical Myeloproliferative Disorders |
| Companies Covered | Novartis AG, Bristol Myers Squibb Company, Incyte Corporation, Pfizer Inc, Takeda Pharmaceutical Company Limited, AbbVie Inc, Teva Pharmaceutical Industries Ltd, GSK Plc, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myeloproliferative Disorders Drugs Market Evolving Landscape
Next-generation JAK inhibitors with improved selectivity profiles are displacing first-generation compounds in development pipelines. These molecules promise reduced hematologic toxicity while maintaining efficacy against splenomegaly and constitutional symptoms.
Second-generation JAK2-selective inhibitors such as fedratinib and pacritinib are consolidating position in myelofibrosis treatment algorithms. Academic medical centers in the United States and Germany prioritize these agents for patients with baseline cytopenias who cannot tolerate ruxolitinib. The technology is consolidating market share among transplant-ineligible populations by offering differentiated safety profiles that preserve platelet counts.
EMA's evolving oncology guidelines now mandate quality-of-life endpoints alongside traditional progression-free survival metrics. This regulatory shift extends trial duration and increases patient-reported outcome collection costs. European sponsors are responding by embedding digital health technologies for remote symptom capture in Phase III protocols.
Hospital-based hematology-oncology departments are unbundling drug procurement from care delivery. Specialty pharmacy networks now manage prior authorization, patient assistance enrollment, and adherence monitoring. This channel transformation is most advanced in the United States, where pharmacy benefit manager consolidation creates preferred network arrangements that bypass traditional hospital outpatient pharmacies.
Myeloproliferative Disorders Drugs Market Segmentation
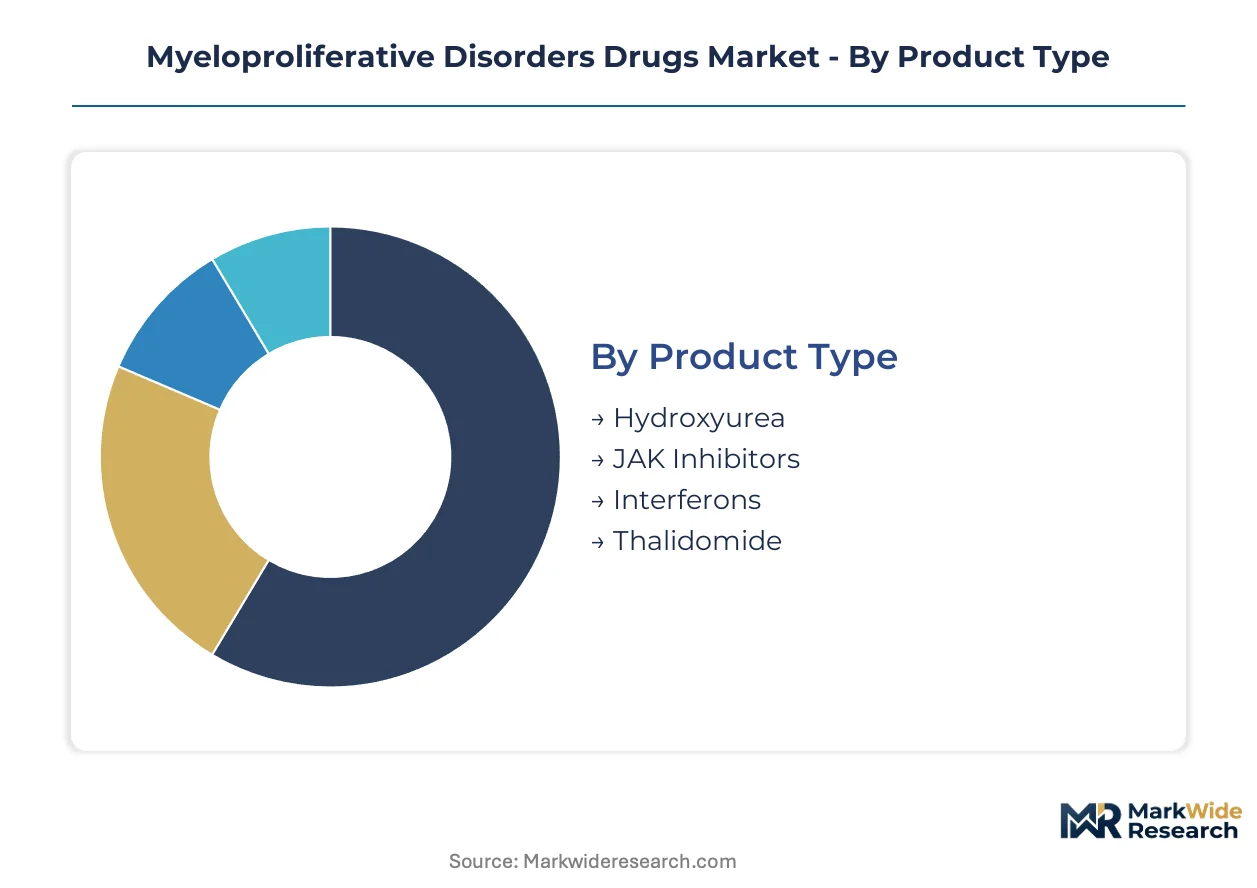
Myeloproliferative disorder therapies fragment across four distinct dimensions that shape prescribing patterns and channel economics. Product type stratification reflects the ongoing displacement of cytotoxic agents by targeted kinase inhibitors. Delivery mode and end-user segmentation capture the migration from hospital-based infusion to home administration models.
Product Type:
Upgrade cycles from conventional cytoreduction to pathway-directed therapy are compressing as biomarker testing standardizes treatment selection across academic centers.
- JAK Inhibitors:ATP-competitive small molecules block dysregulated JAK-STAT signaling in myelofibrosis and polycythemia vera. Demand concentrates at academic medical centers in the United States and Germany where ruxolitinib and second-generation compounds displace hydroxyurea for splenomegaly management. The upgrade trajectory accelerates as platelet-sparing formulations expand addressable populations.
- Interferons:Recombinant alpha-interferons provide non-mutagenic cytoreduction for younger polycythemia vera patients pursuing long-term disease control. European hematology departments in France and Switzerland retain structural preference for pegylated formulations where pregnancy considerations or thrombotic risk profiles favor interferon over JAK inhibition.
- Hydroxyurea:Oral ribonucleotide reductase inhibitor remains first-line for essential thrombocythemia and resource-constrained settings where kinase inhibitor access is limited.
- Thalidomide:Immunomodulatory agent with anti-angiogenic properties sees niche application in atypical myeloproliferative presentations with concurrent myelodysplastic features.
Volume placements concentrate in JAK Inhibitors; the faster expansion belongs to Interferons as next-generation pegylated formulations reduce injection burden.
Delivery Mode:
Cost tier stratification separates premium oral kinase inhibitors from hospital-administered parenteral therapies with higher logistics overhead.
- Oral:Small-molecule kinase inhibitors and hydroxyurea tablets enable patient self-administration with pharmacy benefit manager reimbursement. Specialty pharmacy networks in the United States capture dispensing margin through direct-to-patient distribution models that bypass hospital outpatient pharmacies.
- Subcutaneous:Pegylated interferon formulations shift administration from infusion centers to patient residences, reducing healthcare utilization costs while preserving therapeutic exposure.
- Intravenous:Hospital-based induction protocols require bioavailability monitoring for certain investigational JAK inhibitors where first-pass metabolism variability demands controlled administration.
- Injectable:Intramuscular and depot formulations persist for interferon therapies in markets where cold-chain infrastructure for subcutaneous delivery remains underdeveloped.
Prescription volume tilts toward Oral delivery; Subcutaneous routes are climbing the fastest as home administration models gain payer preference.
End User:
Customer type fragmentation reflects unbundling of drug procurement from clinical care across United States healthcare delivery systems.
- Specialty Pharmacies:Limited-distribution networks manage prior authorization, patient assistance enrollment, and adherence monitoring for oral JAK inhibitors. These channels expand fastest in the United States where pharmacy benefit manager consolidation creates preferred network arrangements.
- Hospitals:Academic medical centers retain dominance for intravenous induction protocols and complex myelofibrosis cases requiring multidisciplinary transplant evaluation.
- Home Care:Nursing services support subcutaneous interferon administration for patients with mobility limitations or rural geographic isolation.
- Clinics:Community hematology-oncology practices serve as prescribing gatekeepers where laboratory infrastructure for CALR and JAK2 mutation testing is available.
Patient volume concentrates in Hospitals; Specialty Pharmacies are gaining share fastest as channel transformation accelerates.
Indication:
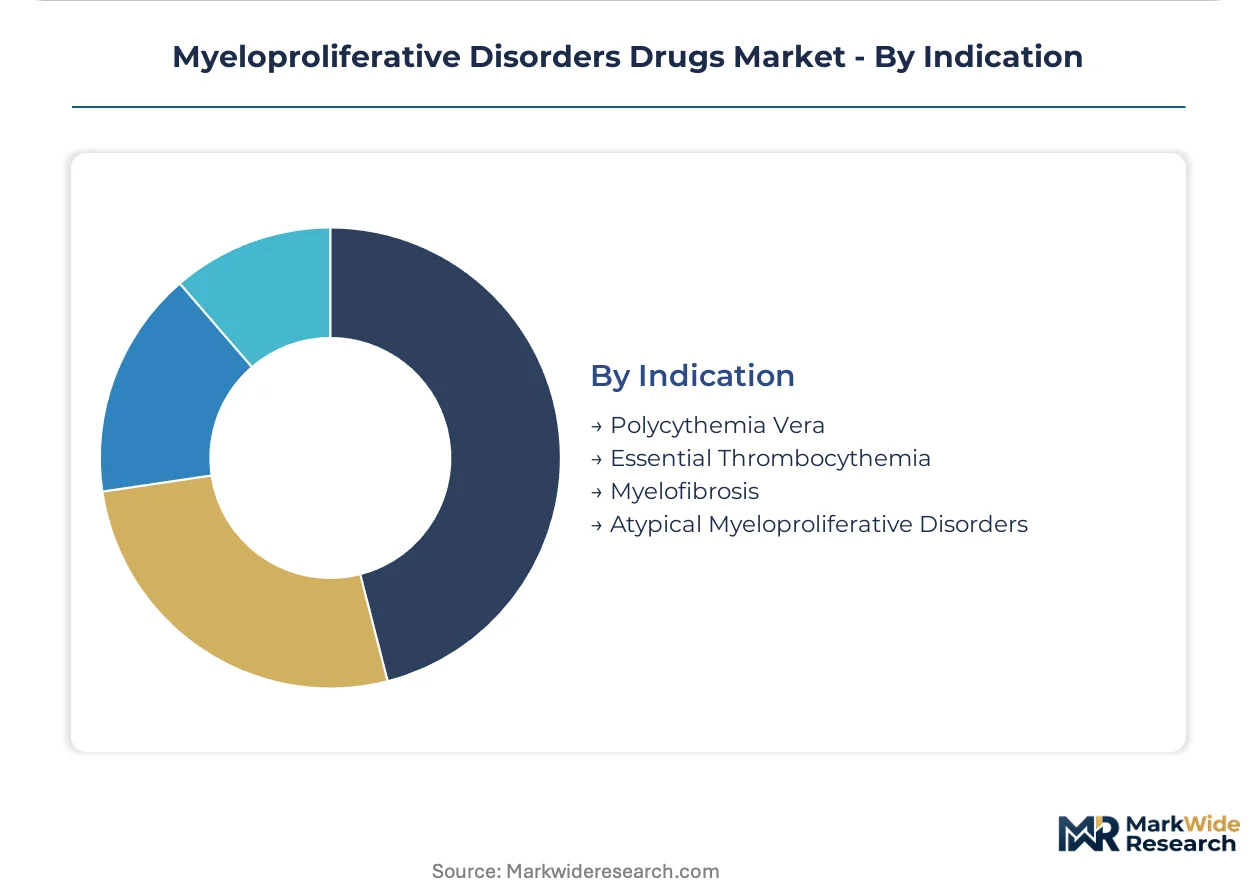
Maturity differentiation separates well-established myelofibrosis and polycythemia vera markets from emerging atypical indications with unmet therapeutic need.
- Myelofibrosis:Primary and secondary forms drive JAK inhibitor revenue through splenomegaly reduction and constitutional symptom control. United States transplant centers prioritize ruxolitinib bridging therapy for allogeneic stem cell transplant candidates.
- Polycythemia Vera:JAK2V617F-mutant disease represents the largest addressable population for interferon and hydroxyurea therapy, with second-line JAK inhibitor uptake accelerating among intolerant or resistant cases.
- Essential Thrombocythemia:Low-risk patients receive aspirin and observation; high-risk cohorts require cytoreductive intervention where hydroxyurea retains dominant position.
- Atypical Myeloproliferative Disorders:Overlap syndromes and unclassifiable neoplasms lack approved targeted therapies, creating orphan drug development opportunity with FDA and EMA incentives.
Therapeutic focus concentrates in Myelofibrosis; Atypical Myeloproliferative Disorders show the steepest expansion trajectory as molecular classification improves diagnostic precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmaceutical zones in the United States and biotech clusters in Switzerland concentrate myeloproliferative disorder drug development. These tax-advantaged jurisdictions attract kinase inhibitor research through R&D credits and accelerated regulatory pathways.
United States
FDA breakthrough therapy designations compress review timelines for novel JAK inhibitors. Medicare Part D reimbursement policies shape prescribing patterns across academic medical centers. The Greater Boston corridor hosts clinical trial networks for next-generation myelofibrosis therapies.
Germany
EMA conditional marketing authorizations enable early patient access to interferon formulations. The country's statutory health insurance system negotiates reference pricing for oral kinase inhibitors. Heidelberg and Munich anchor hematology research clusters with integrated diagnostic pathology services.
Switzerland
Swissmedic's streamlined oncology approval pathways attract multinational headquarters operations. The Basel biotech corridor concentrates interferon manufacturing and pegylated formulation expertise. Cantonal tax incentives support rare disease drug development infrastructure.
Japan
PMDA's sakigake designation system accelerates myeloproliferative neoplasm therapy reviews. The national health insurance price listing process determines market access timelines. The Kanto region's academic hospitals drive adoption of platelet-sparing JAK2 inhibitors.
United Kingdom
NICE technology appraisals mandate cost-effectiveness thresholds for ruxolitinib access. The NHS Cancer Drugs Fund provides interim reimbursement for promising myelofibrosis treatments. London's tertiary referral centers concentrate CALR mutation testing capacity.
Myeloproliferative Disorders Drugs Market Competitive Landscape
Top-tier vendors anchor the JAK inhibitor segment, while mid-cap specialists concentrate on interferon formulations and biosimilar development. The competitive structure stratifies across three distinct tiers: integrated pharmaceutical conglomerates with hematology franchises, biotechnology firms with kinase platform expertise, and generic manufacturers serving cost-sensitive markets. Two dominant competitive moves define current positioning: strategic partnerships to combine JAK inhibitors with complementary pathway modulators, and geographic expansion into Asia-Pacific markets with rising diagnosis rates.
Within the integrated pharmaceutical tier, Novartis AG and Bristol Myers Squibb Company represent established anchors with deep institutional access across major treatment centers. Incyte Corporation occupies a position exemplifying kinase platform specialization. These three entities collectively illustrate how market presence stratifies between broad oncology infrastructure and targeted signaling pathway expertise.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol Myers Squibb Company |
| Incyte Corporation |
| Pfizer Inc |
| Takeda Pharmaceutical Company Limited |
| AbbVie Inc |
| Teva Pharmaceutical Industries Ltd |
| GSK Plc |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Network & Pricing Analysis
Next-generation JAK2-selective manufacturing processes are compressing production costs while concentrating API synthesis expertise in fewer qualified facilities. This technological transition simultaneously enables premium pricing for platelet-sparing formulations and creates supply vulnerability where multi-product kinase inhibitor plants face capacity constraints.
Pricing Analysis
Short-lead-time premiums for investigational JAK inhibitors command substantial markups over standard commercial formulations in clinical trial supply agreements. Three-tier pricing structure across innovator, authorized generic, and compounding pharmacy levels reflects patent exclusivity windows and bioequivalence certification requirements. Cost compression in the hydroxyurea segment intensifies as Indian and Chinese API producers expand generic formulation capacity. Community hematology clinics exhibit highest price sensitivity due to Medicare Part D reimbursement lag, while academic medical centers absorb premium pricing through research grant offsets.
Supply Chain Analysis
Dual-sourcing mandates from FDA and EMA quality guidelines require sponsors to qualify at least two API manufacturers for each kinase inhibitor program. Active pharmaceutical ingredient production for JAK inhibitors concentrates in China, India, and Switzerland, drawing from specialized intermediate suppliers in Italy and Germany. Supply chain vulnerability centers on single-source chiral synthesis steps for JAK2-selective molecules. Cold-chain distribution for interferon formulations runs through specialty pharmacy networks that manage temperature-controlled logistics to patient residences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as sponsors pursue captive API manufacturing to secure supply continuity and margin control against geopolitical friction.
For Market Incumbents: Deepen backward integration into JAK inhibitor intermediate production to reduce exposure to Chinese API concentration. Secure dedicated fermentation capacity for interferon manufacturing through long-term offtake agreements with European biotechnology contractors. This defensive posture counters emerging biosimilar threats from Indian manufacturers and protects against EMA quality enforcement actions that disrupt multi-product facilities.
For New Entrants and Emerging Players: Rural community hematology practices represent an underserved buyer archetype with limited access to specialty pharmacy networks and clinical trial enrollment. Develop subcutaneous interferon formulations with simplified cold-chain requirements to penetrate this white space through direct physician distribution models. Target pediatric myeloproliferative neoplasm indications where orphan drug incentives reduce competitive density and accelerate regulatory timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with kinase platform specialists given FDA's Project Optimus creating extended development timelines that favor established pharmacokinetic expertise. Long-term viability over the next decade hinges on combination regimen pipelines pairing JAK inhibitors with BET or PI3K modulators. Monitor CALR mutation testing penetration rates as the inflection indicator for precision medicine adoption and biomarker-driven therapy selection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II dose-optimization studies satisfy FDA Project Optimus requirements for JAK inhibitor approval pathways. |
| Regulatory Approval Pathway | EMA conditional marketing authorizations accelerate European access to interferon formulations before full trial completion. |
| Manufacturing Scale-Up | Dedicated API plants in Switzerland and Germany reduce geopolitical risk from concentrated Asian supply. |
| Pipeline Diversification | BET inhibitor combinations address JAK inhibitor resistance mechanisms in relapsed myelofibrosis populations. |
| Reimbursement Strategy | Medicare Part D prior authorization navigation services improve patient access and reduce prescription abandonment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated market sizing assumptions. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases provided structured secondary validation. Bottom-up patient population estimates and top-down revenue triangulation converged on segment-level projections.
Granularity-level modeling disaggregated the analysis window by product type, delivery mode, end-user channel, and indication severity. Treatment line stratification captured first-line versus second-line JAK inhibitor adoption curves. Regional regulatory clusters grouped countries by FDA, EMA, PMDA, and Swissmedic approval pathway similarities. CAGRs were derived from patient volume forecasts and pricing trajectory assumptions across the projection horizon. JAK2 and CALR mutation prevalence rates informed addressable population calculations.
Revisions become necessary when regulatory divergence between FDA and EMA intensifies, API supply disruptions materialize, or biosimilar entry accelerates beyond current assumptions. Deviation in accelerated approval conversion rates or post-marketing commitment fulfillment timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Balantidiasis Market