
 Cancer Monoclonal Antibodies Market | 2026-2036
Cancer Monoclonal Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Monoclonal Antibodies Market Intelligence
Biologics manufacturing capacity across North America and Western Europe is broadening as contract development organizations expand single-use bioreactor footprints to meet antibody output targets. F. Hoffmann-La Roche Ltd. leverages its Basel-based production network to sustain supply continuity for blockbuster oncology portfolios. Bristol Myers Squibb Co. anchors its competitive stance through deep immuno-oncology specialization across multiple solid tumor indications. Merck & Co., Inc competes aggressively in the PD-1 pathway segment with manufacturing scale that supports broad global distribution.
Cancer monoclonal antibodies constitute recombinant protein therapeutics engineered through hybridoma technology or phage display to bind specific tumor-associated antigens with nanomolar affinity, typically administered via intravenous infusion in doses ranging from 2 to 15 milligrams per kilogram. These agents function primarily to block growth factor signaling, recruit immune effector cells, or deliver cytotoxic payloads directly to malignant tissue. Fully human antibodies command expanding share as immunogenicity concerns limit murine and chimeric platform uptake in maintenance therapy settings. Lung cancer applications represent the fastest-growing therapy area as checkpoint inhibitors displace chemotherapy in first-line non-small cell protocols. Intravenous delivery dominates current revenue pools, though subcutaneous formulations are gaining structural importance through reduced infusion center burden and improved patient compliance metrics.
FDA breakthrough therapy designation and EMA PRIME eligibility frameworks compress clinical development timelines while raising evidence standards for confirmatory trials. The EU MDR and FDA's updated biologics guidance jointly enforce escalating purity requirements and post-market surveillance obligations that shape manufacturer quality investments. Stakeholders must monitor evolving biosimilar interchangeability standards and CMS reimbursement mechanisms for infused oncology products as these decisions will determine competitive dynamics between originator and follow-on antibody developers.
Market Dynamics
FDA breakthrough therapy designation and EMA PRIME eligibility frameworks compress clinical development timelines while reshaping competitive entry patterns for novel antibody candidates.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy designation and EMA's PRIME framework compress Phase II-to-approval timelines, enabling earlier patient access for novel checkpoint inhibitors.
- Outpatient Administration Shift:Oncology clinics are capturing infusion volume as payers favor ambulatory settings over hospital-based delivery for maintenance antibody regimens.
- Subcutaneous Formulation Advances:Reduced infusion center burden and improved patient compliance metrics are driving formulation investment across PD-1 and HER2-directed portfolios.
Market Restraints
- Bioreactor Capacity Constraints:Stainless steel facility shortages in mammalian cell culture create bottlenecks for blockbuster antibody scale-up.
- Confirmatory Trial Evidence Standards:FDA's accelerated approval confirmatory requirements impose costly post-market obligations that strain development budgets.
- Reimbursement Compression:CMS national coverage determinations for infused oncology products create pricing pressure on originator therapies facing biosimilar entry.
Strategic Opportunities
- EU MDR Transition Window:Stricter purity and post-market surveillance obligations under the EU Medical Device Regulation favor manufacturers with advanced quality systems.
- Combination Regimen Expansion:Pairing checkpoint inhibitors with antibody-drug conjugates opens new indication spaces beyond monotherapy-responsive tumors.
- Home Administration Models:Subcutaneous delivery platforms enable self-administration programs that reduce healthcare system utilization costs.
Industry Challenges
- Cell Line Development Expertise Gap:Shortages of mammalian cell culture scientists delay clone selection timelines for high-titer production strains.
- Biosimilar Interchangeability Uncertainty:Evolving FDA standards for automatic substitution create commercial planning complexity for follow-on developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Monoclonal Antibodies Market |
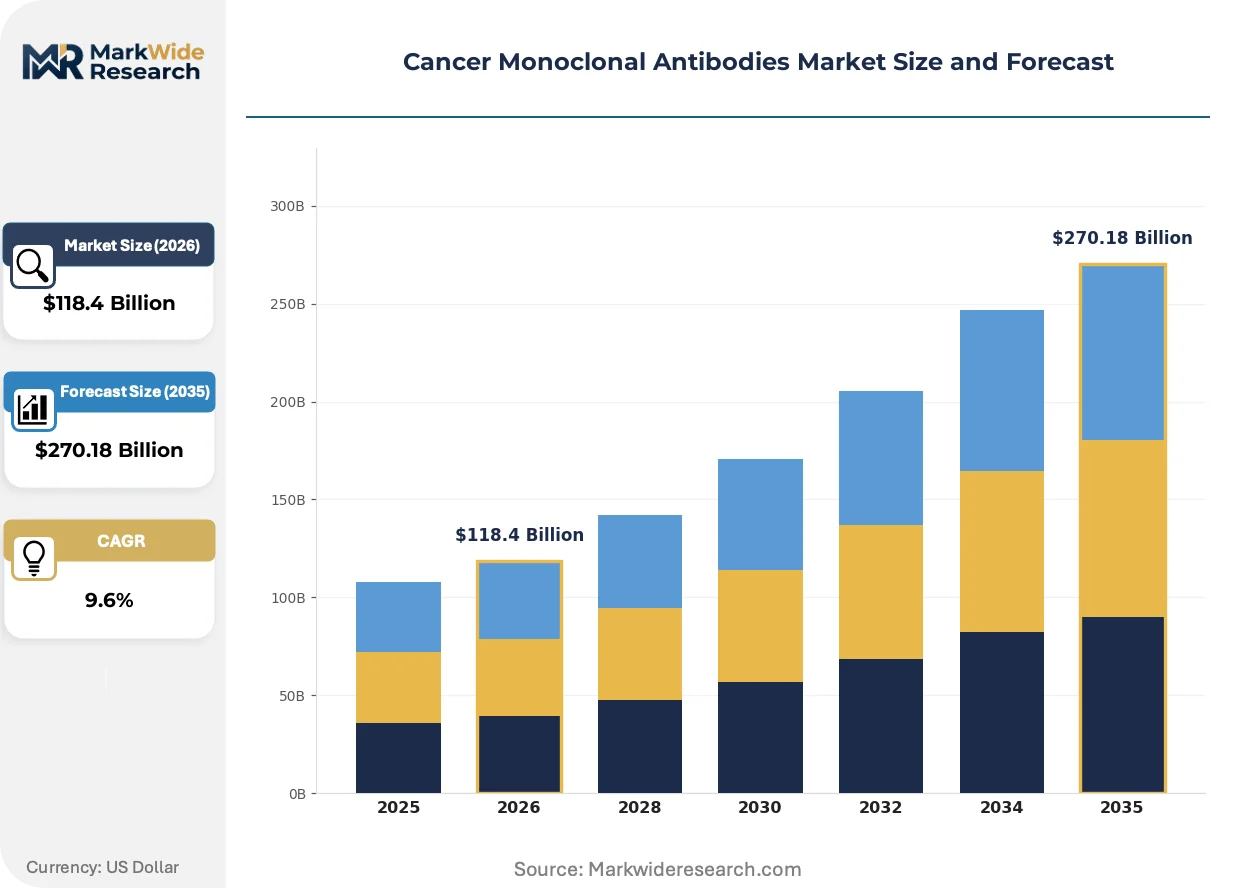
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $270.18 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Murine Antibodies, Chimeric Antibodies, Humanized Antibodies, Fully Human Antibodies Therapy Area: Breast Cancer, Colorectal Cancer, Lymphoma, Lung Cancer Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Research Laboratories, Oncology Clinics, Homecare |
| Companies Covered | F. Hoffmann-La Roche Ltd., Bristol Myers Squibb Co., Merck & Co., Inc, Amgen Inc, Novartis AG, AstraZeneca plc, Eli Lilly and Company, Johnson & Johnson, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Monoclonal Antibodies Market Strategic Shifts & Innovations
Antibody engineering platforms are converging with payload delivery systems to expand therapeutic index beyond what unconjugated or naked antibodies achieve.
Bispecific T-cell engagers are integrating dual antigen recognition architectures to redirect cytotoxic lymphocytes against hematologic malignancies. Academic medical centers and specialized oncology networks are adopting these constructs for relapsed refractory indications. The technology is integrating into earlier lines of therapy as manufacturing consistency improves and cytokine release syndrome management protocols mature.
EMA's updated biologics guidance enforces escalating purity requirements for host cell protein clearance and aggregate control. Manufacturers must demonstrate extended stability data and enhanced pharmacovigilance systems. European contract development organizations are responding with dedicated single-use train investments to meet these specifications.
Hospital procurement committees are consolidating antibody purchasing through centralized formulary management and therapeutic interchange protocols. Community oncology practices are losing direct contracting leverage as integrated delivery networks capture infusion volume. This concentration is most visible in United States metropolitan markets where Medicare Advantage penetration exceeds fifty percent.
Cancer Monoclonal Antibodies Market Segmentation
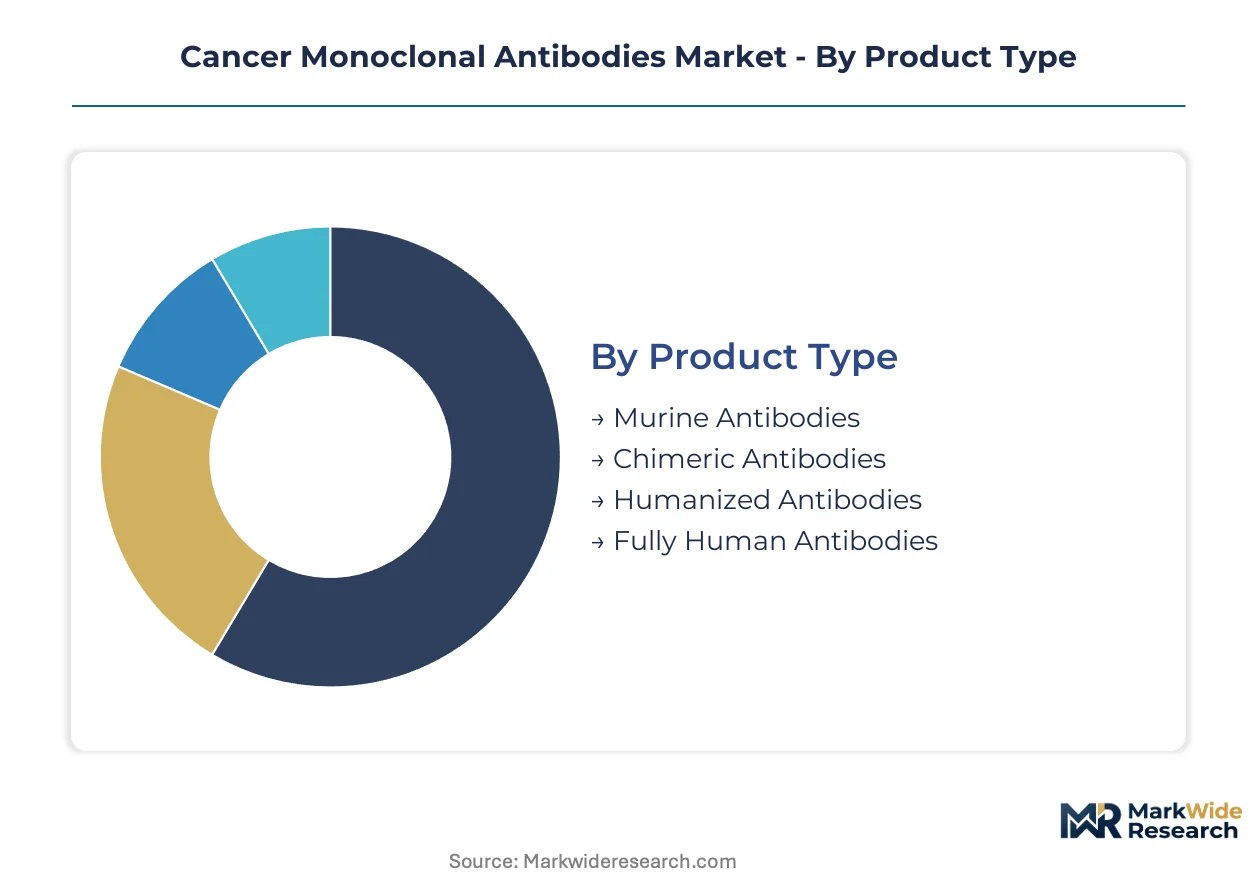
Antibody platform selection determines manufacturing complexity and immunogenicity risk profiles. Therapy area concentration shapes clinical trial investment priorities. Delivery mode and end-user channel choices directly influence reimbursement pathways and patient access economics.
Product Type:
Fully human and humanized platforms command the highest upstream investment in transgenic animal facilities and phage display libraries.
- Fully Human Antibodies:Engineered through transgenic mouse platforms or phage display to eliminate murine sequences entirely. Demand concentrates in maintenance therapy settings within United States oncology clinics where immunogenicity concerns drive formulary preference.
- Humanized Antibodies:Retain 5-10% murine-derived complementarity-determining regions grafted onto human frameworks. Investment flows heavily into CDR optimization programs at Basel-based production networks seeking to reduce anti-drug antibody incidence.
- Chimeric Antibodies:Approximately 33% murine variable regions fused to human constant domains. Rituximab-class legacy products sustain volume in lymphoma protocols.
- Murine Antibodies:Unmodified rodent-derived sequences with high immunogenicity liability. Relegated to diagnostic imaging applications and limited therapeutic niches.
Most installed capacity flows through fully human platforms. Expansion is steepest in humanized antibody segments where biosimilar developers target established oncology franchises.
Therapy Area:
Clinical development spending correlates directly with addressable patient populations and regulatory pathway maturity.
- Lung Cancer:Checkpoint inhibitors displace chemotherapy in first-line non-small cell protocols. United States Medicare reimbursement policies sustain premium pricing for PD-1/PD-L1 combinations in metropolitan markets with concentrated specialist networks.
- Breast Cancer:HER2-directed antibodies anchor adjuvant and metastatic treatment paradigms. Demand concentrates in academic medical centers with integrated pathology and infusion capabilities.
- Lymphoma:CD20-targeted antibodies maintain durable revenue pools despite biosimilar entry. Rituximab biosimilars capture share in European markets with centralized procurement.
- Colorectal Cancer:EGFR and VEGF pathway antibodies compete in later-line settings. Bevacizumab biosimilars compress pricing in United States community oncology practices.
Lung cancer applications absorb the largest share of Phase III investment. Steepest expansion trajectory appears in breast cancer as antibody-drug conjugates penetrate earlier treatment lines.
Delivery Mode:
Formulation technology requirements scale with route complexity and stability demands.
- Intravenous:Dominates current revenue through established infusion center infrastructure. United States hospital outpatient departments and oncology clinics capture volume as administration shifts from inpatient settings.
- Subcutaneous:High-concentration formulations require sophisticated viscosity management and injection device engineering. Home administration programs reduce healthcare system utilization costs.
- Intramuscular:Limited to specific adjuvant antibody applications and certain bispecific constructs with acceptable local tolerability profiles.
- Oral:Antibody bioavailability barriers restrict this route to experimental mucosal delivery platforms and gastrointestinal targeting technologies.
Intravenous delivery retains the largest installed manufacturing footprint. Subcutaneous capacity is expanding most quickly as Bristol Myers Squibb and Merck invest in patient-compliant formulation platforms.
End User:
Channel economics diverge sharply between institutional purchasers and distributed care settings.
- Oncology Clinics:Ambulatory infusion centers capture maintenance therapy volume as United States payers favor outpatient reimbursement rates. Medicare Advantage penetration above fifty percent in metropolitan markets accelerates this shift.
- Hospitals:Academic medical centers retain complex induction regimens and combination protocols requiring inpatient monitoring. Centralized formulary management concentrates purchasing leverage.
- Homecare:Subcutaneous self-administration programs emerge through specialty pharmacy distribution networks. Patient compliance metrics improve with reduced travel burden.
- Research Laboratories:Preclinical and biomarker discovery applications sustain demand for specialized antibody reagents and conjugation services.
Hospital channels retain the largest absolute antibody consumption. Oncology clinics are gaining share fastest as site-of-care policies reshape United States reimbursement flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with streamlined biologics approval frameworks and favorable reimbursement environments. Cost-of-compliance gaps between mature and emerging markets are accelerating facility placement decisions for antibody production networks.
United States
Medicare reimbursement policies sustain premium pricing for novel antibody therapies in metropolitan markets with concentrated specialist networks. FDA breakthrough therapy designation compresses Phase II-to-approval timelines for checkpoint inhibitors. The Greater Boston and San Francisco Bay Area clusters anchor clinical development infrastructure for immuno-oncology portfolios.
Germany
EMA PRIME eligibility frameworks enable accelerated patient access for hematologic malignancy antibodies. The country's national pharmaceutical regulator enforces escalating purity requirements under EU MDR transition protocols. The Rhine-Main and Munich regions concentrate single-use bioreactor investments from contract development organizations.
Switzerland
Basel-based production networks leverage cross-border regulatory harmonization to sustain supply continuity for blockbuster oncology franchises. Swissmedic maintains alignment with EMA standards while offering specialized pathways for advanced therapy medicinal products. The Basel metropolitan area hosts concentrated antibody manufacturing infrastructure serving European distribution.
Japan
PMDA's sakigake designation system accelerates review timelines for oncology antibodies addressing unmet medical needs. METI industrial policy supports domestic biologics manufacturing capacity expansion through targeted subsidies. The Kanto region around Tokyo concentrates clinical trial infrastructure and specialist oncology networks.
India
CDSCO accelerated approval pathways for biosimilar antibodies are attracting follow-on developer investment. The country's national pharmaceutical regulator harmonizes with ICH guidelines to facilitate export-oriented production. Hyderabad and Bangalore clusters are expanding mammalian cell culture capacity for contract manufacturing services.
Cancer Monoclonal Antibodies Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biosimilar and next-generation format opportunities through differentiated platform technologies. The market structure concentrates around integrated pharmaceutical conglomerates with captive manufacturing infrastructure and specialized biotechnology firms with novel modality expertise. Two dominant strategic archetypes prevail: diversified oncology incumbents leveraging broad immunotherapy portfolios, and focused biotechnology specialists advancing bispecific and antibody-drug conjugate platforms. Competitive dynamics center on manufacturing scale expansion and accelerated regulatory pathway navigation.
Within the diversified oncology tier, F. Hoffmann-La Roche Ltd. and Bristol Myers Squibb Co. exemplify archetypes of integrated development and commercialization capability. Merck & Co., Inc occupies a position representing manufacturing scale advantages in the PD-1 pathway segment. These entities anchor competitive positioning through deep specialization across multiple solid tumor indications and global distribution infrastructure.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Bristol Myers Squibb Co. |
| Merck & Co., Inc |
| Amgen Inc |
| Novartis AG |
| AstraZeneca plc |
| Eli Lilly and Company |
| Johnson & Johnson |
| AbbVie |
| Others |
Cost & Logistics Intelligence
Originator-biosimilar bifurcation separates premium checkpoint inhibitors from commoditized CD20-directed antibodies, concentrating pricing power with FDA breakthrough-designated portfolios while supply chains anchor in Basel-based production networks and Indian contract manufacturing clusters. This divergence channels investment toward single-use bioreactor capacity in Switzerland and Germany while biosimilar developers exploit cost-of-compliance gaps in South Asian mammalian cell culture facilities.
Pricing Analysis
Distributor margins for infused oncology products compress as integrated delivery networks consolidate formulary leverage across United States metropolitan markets. Three-tier pricing structure across premium, standard, and economy levels reflects FDA approval pathway differentiation, with breakthrough-designated antibodies commanding formulary preference against interchangeable biosimilars. Cost compression in the CD20 and VEGF pathway segments intensifies as European centralized procurement captures rituximab and bevacizumab biosimilar volume. Community oncology practices exhibit highest price sensitivity, while academic medical centers with dedicated pharmacy budgets absorb premium pricing for first-line lung cancer combinations.
Supply Chain Analysis
Workforce availability for mammalian cell culture scientists constrains clone selection timelines most acutely in Basel, Boston, and San Francisco Bay Area clusters. Supply concentrates in Switzerland, Germany, and the United States for originator antibody production, while India and South Korea expand contract manufacturing capacity for biosimilar output. Raw material dependencies span recombinant protein A resin, chemically defined cell culture media, and single-use bioreactor bags. Single-source vulnerability in protein A resin supply creates bottleneck exposure for high-titer production strains. Distribution runs through specialty pharmacy networks for subcutaneous formulations and hospital outpatient departments for intravenous infusion products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathway expansion compounds regulatory-driven demand for confirmatory trial infrastructure, positioning quality-system investments as the decisive competitive filter. EMA PRIME eligibility and EU MDR transition obligations jointly elevate the cost of market participation.
For Market Incumbents: Deepen captive bioreactor capacity in Basel and Boston corridors to secure supply continuity for blockbuster PD-1 portfolios facing biosimilar entry threats. Anchor formulary position through vertical integration into subcutaneous formulation platforms that reduce infusion center burden. Invest in extended pharmacovigilance systems to satisfy EMA post-market surveillance obligations under escalating purity standards. For New Entrants and Emerging Players: Bispecific T-cell engager technology offers a technology-first wedge into relapsed refractory lymphoma indications where manufacturing consistency gaps still impede incumbent dominance. Target United States oncology clinic channels for subcutaneous delivery platforms that bypass hospital formulary consolidation. Pursue CDSCO accelerated approval pathways in India to establish export-oriented production before EU MDR compliance costs escalate. For Investors and Strategic Acquirers: Consolidation pressure builds where biosimilar developers lack the quality systems to satisfy EU MDR transition requirements. Long-term viability favors platforms with demonstrated CMC consistency across multiple antibody formats. Acquisition target archetypes include specialized biotechnology firms with validated high-titer cell lines and established EMA rapporteur relationships. Monitor FDA confirmatory trial completion rates as the inflection indicator for accelerated approval withdrawal risk.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III investment in lung cancer checkpoint inhibitor combinations anchors United States reimbursement positioning. |
| Manufacturing Scale-Up | Single-use bioreactor expansion in Rhine-Main clusters addresses stainless steel capacity constraints for blockbuster scale. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines while raising confirmatory evidence standards. |
| Pipeline Diversification | Antibody-drug conjugate portfolios in breast cancer penetrate earlier treatment lines beyond monotherapy-responsive tumors. |
| Licensing Agreement | Cross-border technology transfers enable Indian CMOs to access validated high-titer cell line platforms for export markets. |
Research Approach
Bottom-up oncology clinic volume modeling reconciled against top-down bioreactor capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers generated demand-side intelligence. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Cross-referencing manufacturer production disclosures against infusion center administration data enabled supply-demand reconciliation across the analysis window.
Input-output matrices linked patient population projections to antibody dose requirements, treatment line penetration curves, and regional regulatory approval timelines. Segmentation dimensions encompassed antibody platform type, therapy area concentration, delivery mode, and end-user channel economics. CAGRs derived from fitted growth curves applied to base-year volume estimates, with sensitivity testing around biosimilar entry timing and CMS national coverage determination scenarios. Forecast inputs included specialist network concentration metrics and Medicare Advantage penetration rates by metropolitan market.
The model holds under stable FDA accelerated approval frameworks and EMA PRIME eligibility continuity; deviation in confirmatory trial failure rates or EU MDR enforcement intensity would shift volume trajectories. Forecasts embed assumptions regarding biosimilar interchangeability standards and outpatient administration reimbursement stability. Practitioners should monitor FDA advisory committee outcomes for accelerated approval withdrawals and CMS national coverage determinations for infused oncology products as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Cellular Epigenetics Market