
 CMO and CDMO Biotechnology Market | 2026-2036
CMO and CDMO Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
CMO and CDMO Biotechnology Market Insights
Biologics process engineering talent is rotating from traditional small-molecule facilities into mammalian cell culture and viral vector suites, tightening labor pools in advanced therapy manufacturing. Samsung Biologics leverages its Songdo campus to dominate mammalian production at multi-liter scale. Lonza Group sustains leadership in cell and gene therapy through dedicated viral vector capacity in Switzerland and the United States. Boehringer Ingelheim International GmbH anchors European demand with integrated development-to-commercial antibody services from its Biberach and Vienna sites.
Contract manufacturing and development organizations for biotechnology execute cell line development, upstream bioprocessing, purification, fill-finish, and regulatory filing support under GMP conditions for sponsors lacking internal capacity. Monoclonal antibodies occupy the largest product type share due to established platform processes and blockbuster originator portfolios approaching biosimilar expiry. Gene therapy represents the fastest-growing segment as AAV and lentiviral vector demand outstrips available CDMO capacity, compressing lead times and elevating pricing power for qualified suppliers. Process development services capture disproportionate margin pools where early-phase engagement converts to long-term manufacturing contracts.
FDA enforces strict comparability protocols for biologics manufacturing changes, while EMA's ATMP framework imposes additional certification burdens on gene and cell therapy CDMOs. ISO 13485 and ICH Q5D guidelines further shape facility qualification standards that determine market access for cross-border sponsors. Stakeholders must monitor regulatory divergence between FDA's risk-based CMC reviews and EMA's centralized ATMP classification, as this friction dictates where sponsors locate pivotal clinical supply and commercial launch capacity.
Market Dynamics
Gene therapy manufacturing capacity scarcity is compressing sponsor timelines and forcing biotech firms into multi-year CDMO commitments before clinical proof-of-concept, fundamentally restructuring risk allocation across development pipelines.
Growth Catalysts
- EMA's ATMP Certification:The framework accelerates qualified CDMO qualification for European commercial launches, pulling gene therapy sponsors toward certified facilities in Ireland and Switzerland.
- Continuous Bioprocessing:Perfusion cell culture technologies reduce facility footprint requirements while maintaining volumetric productivity, enabling modular capacity expansion in high-cost labor markets.
- South Korean Cluster Density:Incheon's free economic zone concentrates mammalian cell culture expertise, attracting US and European sponsors seeking dual-source supply strategies for antibody programs.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector production depends on qualified plasmid suppliers concentrated in North America, creating single-source vulnerability for AAV and lentiviral programs.
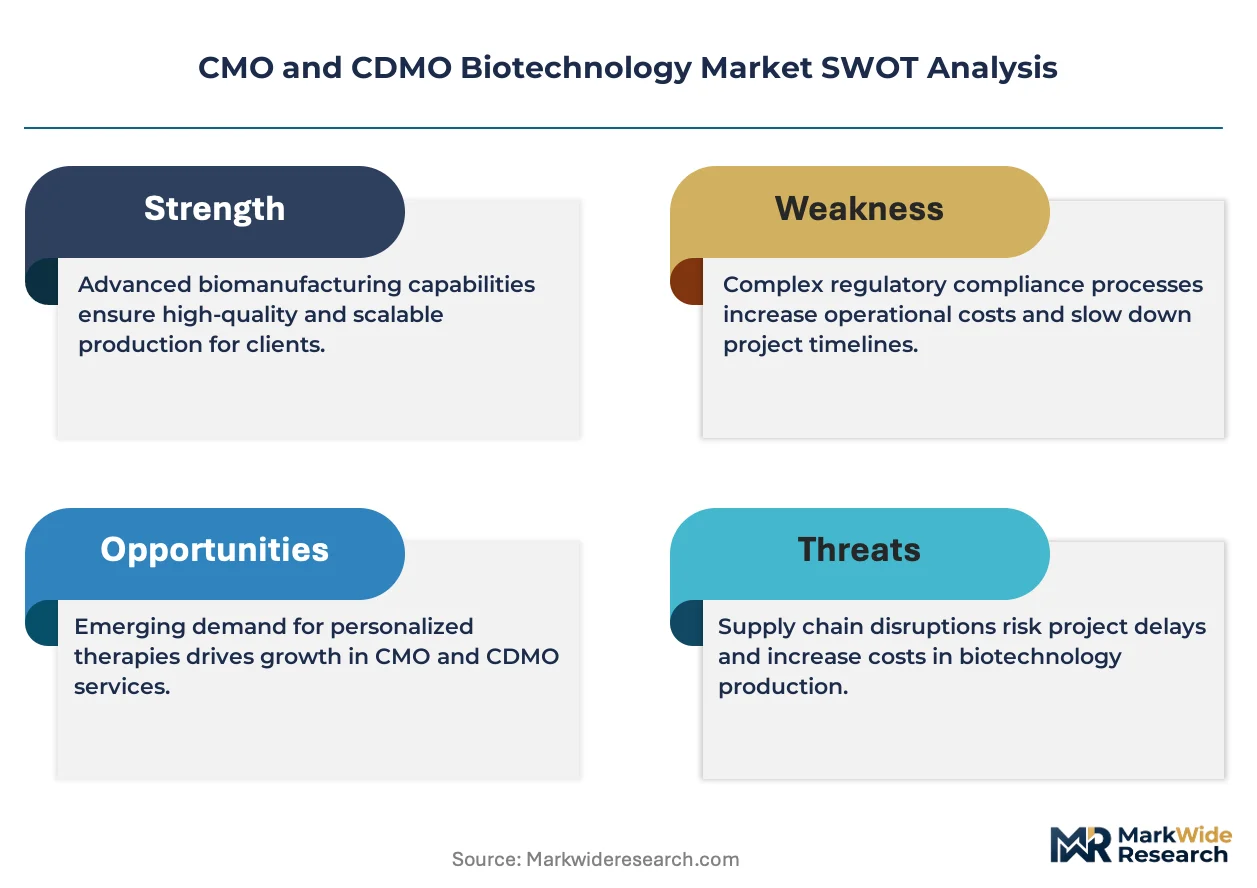
- FDA Comparability Protocol Burden:Manufacturing changes for biologics require extensive analytical bridging studies, freezing process improvements and extending development timelines by 12-18 months.
- Stainless Steel Facility Obsolescence:Legacy small-molecule infrastructure cannot retrofit to single-use bioprocessing standards without complete rebuilds, stranding capital in traditional pharma hubs.
Strategic Opportunities
- India's Emerging CDMO Ecosystem:CDSCO's streamlined biosimilar approval pathways and domestic cost structures position Indian facilities for late-stage clinical and commercial antibody manufacturing.
- AI-Driven Process Development:Machine learning convergence with high-throughput screening compresses cell line development timelines, enabling CDMOs to capture earlier-phase sponsor relationships.
- Japan's Regenerative Medicine Push:METI's industrial policy incentives and PMDA's conditional approval framework accelerate demand for cell therapy manufacturing infrastructure in Kobe and Osaka bioclusters.
Industry Challenges
- Viral Vector Production Talent Scarcity:Transient transfection expertise and biosafety level 2+ operational experience remain concentrated among senior staff at a handful of specialized facilities.
- GMP Facility Qualification Timelines:ISO 13485 and ICH Q5D compliance for advanced therapy suites requires 18-24 months from construction completion to first validated batch release.
- Multi-Product Facility Segregation:Gene therapy CDMOs face complex campaign changeover protocols to prevent cross-contamination between AAV serotypes, constraining effective capacity utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMO and CDMO Biotechnology Market |
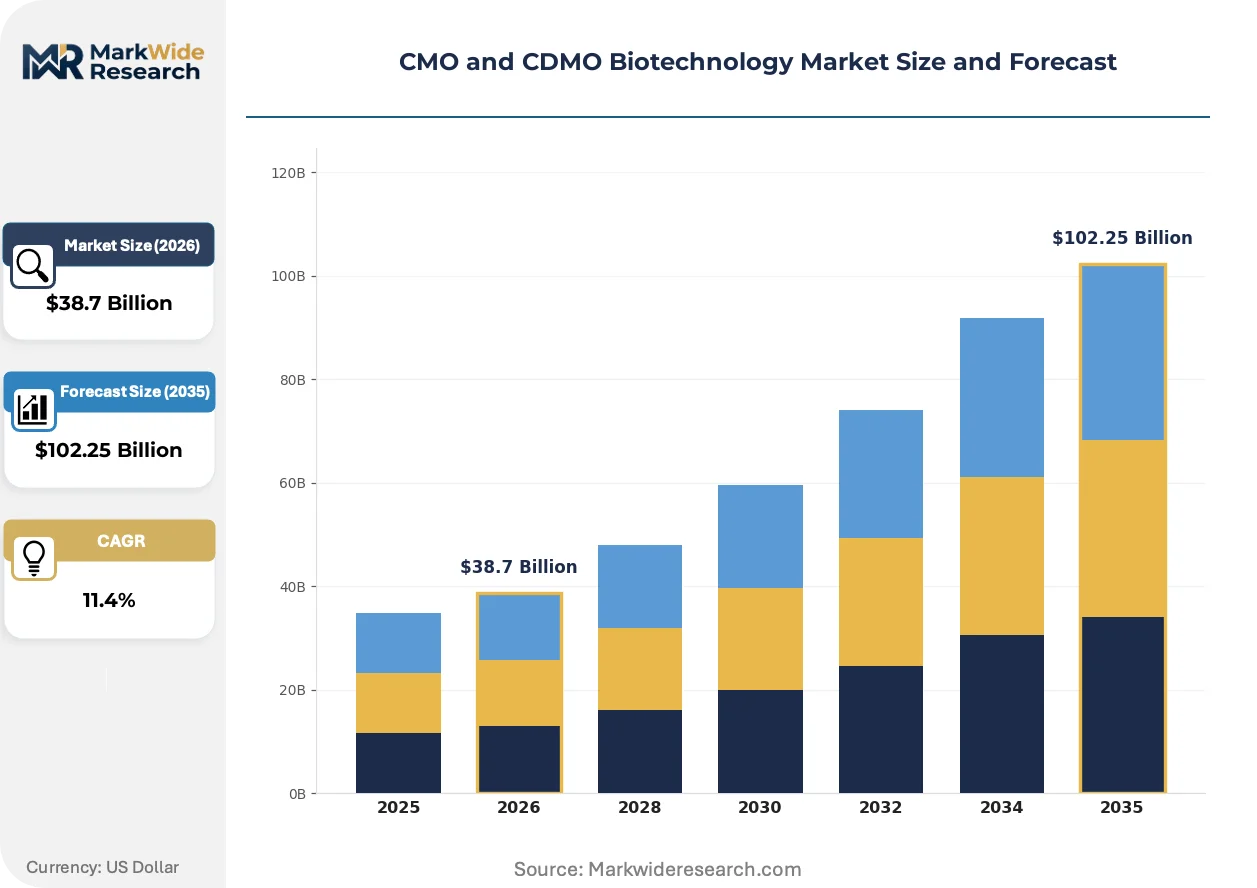
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Manufacturing, Quality Control, Regulatory Affairs Therapy Area: Oncology, Immunology, Neurology, Cardiovascular Product Type: Monoclonal Antibodies, Vaccines, Gene Therapy, Biosimilars Client Type: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Startups |
| Companies Covered | Samsung Biologics, Boehringer Ingelheim International GmbH, Thermo Fisher Scientific, AGC Biologics, Fujifilm Biotechnologies, Lonza Group, WuXi Biologics, Recipharm, Catalent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMO and CDMO Biotechnology Market Trends and Innovations
Bioprocessing hardware and analytical platforms are fragmenting into modular, portable configurations that displace centralized mega-facilities, while regulatory science struggles to keep pace with vector engineering advances.
Single-use bioreactor technology is bifurcating the manufacturing landscape. Biotech sponsors now deploy 2,000-liter disposable systems for Phase III commercial supply, avoiding stainless steel capital commitments. This shift compresses facility construction timelines from 36 months to 18 months. CDMOs with standardized single-use platforms capture sponsor preference over integrated legacy operators.
REACH and RoHS compliance requirements are tightening material traceability for European bioprocessing supply chains. Suppliers must document polymer and additive compositions in single-use bags, tubing, and connectors. Gene therapy CDMOs serving EMA-regulated products face the steepest compliance burden, driving qualification of regional European component manufacturers.
Sponsor technical diligence patterns are shortening vendor selection cycles. Large pharma procurement teams now compress CDMO qualification from 12 months to 6 months through pre-audited supplier databases and standardized quality agreements. This acceleration is most visible in antibody programs where platform processes reduce technical risk assessment complexity.
CMO and CDMO Biotechnology Market Segmentation
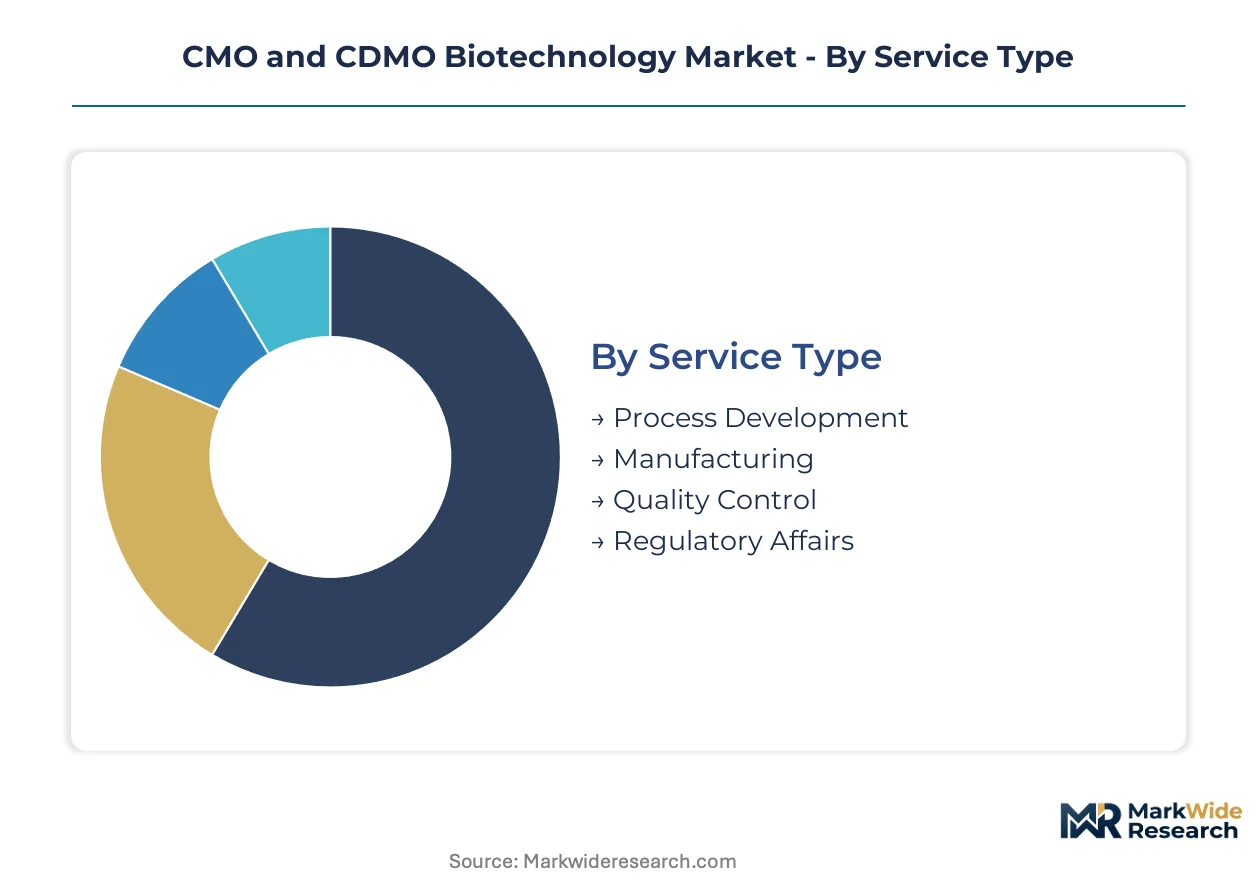
CDMO procurement patterns fragment sharply across service depth and sponsor maturity. Contract manufacturers must calibrate capability portfolios to capture process development margins while defending commoditized manufacturing volumes.
Service Type:
Process development services face acute substitution pressure from in-house bioprocess engineering teams at well-capitalized pharma sponsors, compressing pricing power for standardized platform offerings.
- Process Development:Cell line engineering, upstream optimization, and purification design for novel biologics. Demand concentrates with Boston and San Francisco biotech clusters seeking early-phase engagement that converts to long-term manufacturing commitments.
- Manufacturing:GMP production at clinical and commercial scale using mammalian cell culture or microbial systems. Capacity scarcity in viral vector suites pulls sponsor investment toward dedicated multi-year supply agreements before proof-of-concept data.
- Quality Control:Analytical method development, release testing, and stability studies under ICH guidelines. Biosimilar sponsors in India leverage domestic QC infrastructure to compress approval timelines.
- Regulatory Affairs:CMC documentation, agency correspondence, and compliance strategy for FDA and EMA submissions. Gene therapy sponsors prioritize CDMOs with prior ATMP certification experience.
Manufacturing anchors the volume base while process development gains share at the steepest rate.
Therapy Area:
Oncology commands the highest manufacturing premiums due to personalized medicine complexity and orphan drug economics that tolerate elevated COGS.
- Oncology:Antibody-drug conjugates, bispecific antibodies, and CAR-T cell therapies requiring specialized containment and handling protocols. South Korean CDMOs capture substantial checkpoint inhibitor manufacturing from US sponsors.
- Immunology:Autoimmune and inflammatory disease biologics with established platform processes and large patient populations. Biosimilar competition intensifies cost pressure on originator manufacturing partnerships.
- Neurology:Blood-brain barrier delivery challenges and CNS-targeted gene therapies. AAV vector engineering for neurological indications strains available CDMO capacity.
- Cardiovascular:Recombinant proteins and gene therapies for heart failure and rare cardiac conditions. Clinical trial manufacturing demand remains concentrated in North American and European facilities.
Oncology dominates current revenue contribution while neurology climbs fastest on gene therapy pipeline expansion.
Product Type:
Monoclonal antibodies face biosimilar substitution dynamics that fragment manufacturing demand between originator defense and follow-on biologic launches.
- Monoclonal Antibodies:Established platform processes with standardized cell lines and purification trains. Irish manufacturing clusters attract blockbuster originator volume seeking dual-source supply security.
- Gene Therapy:AAV and lentiviral vector production with transient transfection and adherent or suspension cell platforms. Viral vector capacity scarcity compresses sponsor timelines and elevates pricing for qualified suppliers.
- Vaccines:Viral, bacterial, and recombinant protein vaccines requiring dedicated containment infrastructure. Pandemic preparedness investments expanded mRNA manufacturing capacity at specialized CDMOs.
- Biosimilars:Follow-on biologics demanding analytical similarity and immunogenicity assessment. CDSCO's streamlined Indian approval pathways position domestic facilities for late-stage clinical and commercial supply.
Monoclonal antibodies sustain volume leadership while gene therapy posts the steepest expansion trajectory.
Client Type:
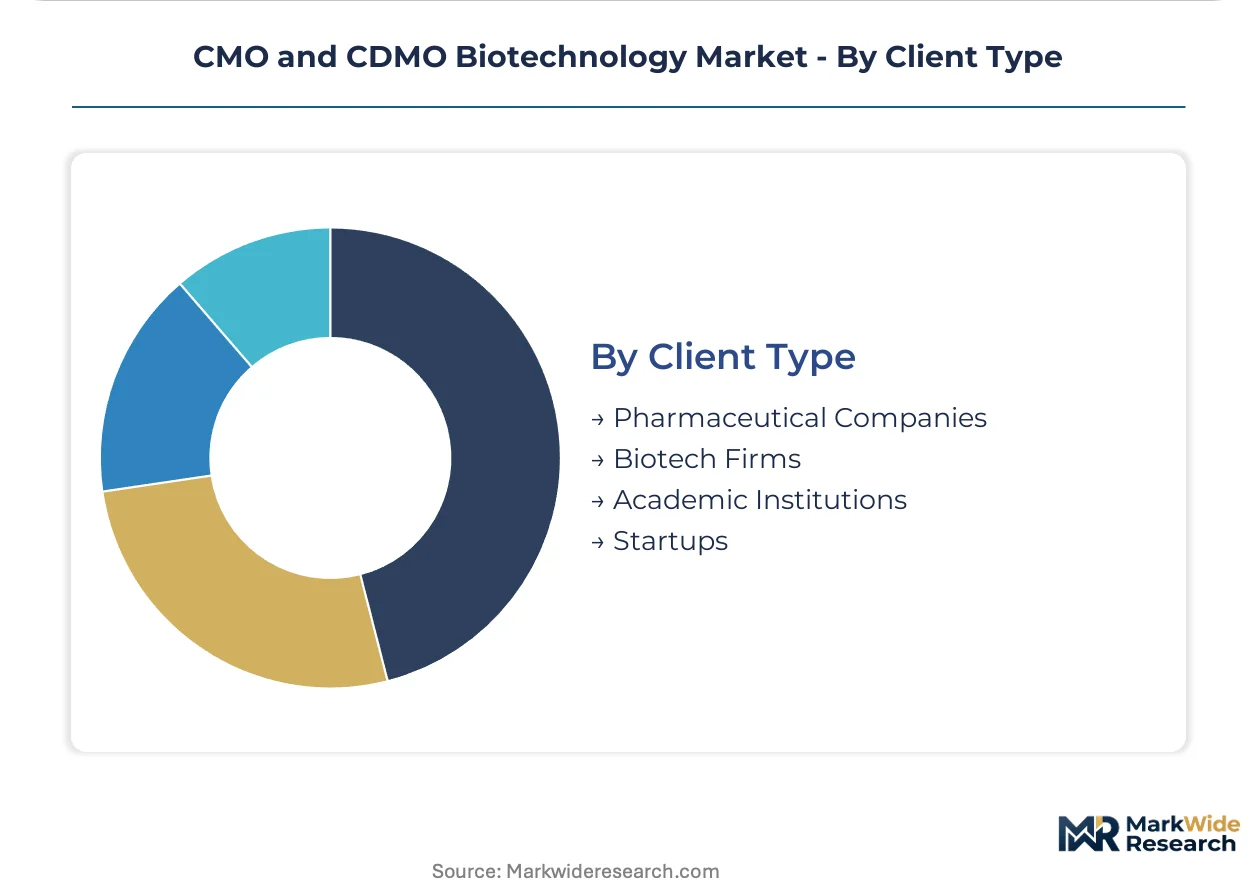
Pharmaceutical companies exercise procurement leverage through multi-program master service agreements that compress unit economics for CDMOs.
- Pharmaceutical Companies:Large sponsors outsourcing capacity-constrained modalities or geographic expansion. Swiss and German pharma anchor European demand for integrated development-to-commercial antibody services.
- Biotech Firms:Venture-backed developers lacking internal GMP infrastructure. Early-phase engagement patterns favor CDMOs with standardized single-use platforms and rapid scale-up capabilities.
- Academic Institutions:Translational research programs requiring GLP tox batch and early clinical supply. University spinouts in Kobe and Osaka bioclusters leverage Japan's regenerative medicine incentives.
- Startups:Preclinical-stage companies seeking flexible, low-minimum engagement structures. AI-driven process development tools enable CDMOs to capture relationships before traditional technical diligence cycles.
Pharmaceutical companies anchor contract value while biotech firms drive engagement volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's risk-based CMC reviews anchor the United States as the dominant geography for biologics contract manufacturing, though sponsor facility location decisions increasingly weigh EMA's ATMP certification burdens and Asian cluster density.
United States
Gene therapy sponsors concentrate viral vector manufacturing in Massachusetts and North Carolina to maintain proximity to FDA's Center for Biologics Evaluation and Research. The agency's comparability protocol requirements for manufacturing changes compress sponsor timelines and elevate demand for qualified CDMOs with prior BLA submission experience. Boston-Cambridge bioclusters anchor early-phase engagement patterns that convert to commercial supply agreements.
Switzerland
Lonza Group's Visp facility and dedicated viral vector capacity attract European gene therapy sponsors seeking EMA ATMP certification. Swissmedic's alignment with centralized EMA procedures streamlines multi-national trial supply. Basel-Zurich corridor concentrates cell and gene therapy process development talent pools that rotate between pharmaceutical sponsors and contract partners.
South Korea
Samsung Biologics' Songdo campus dominates mammalian cell culture at multi-liter scale, capturing US checkpoint inhibitor manufacturing through Incheon's free economic zone incentives. MFDS streamlined biosimilar approval pathways compress development timelines for sponsors seeking dual-source supply security. Seoul-Incheon cluster density concentrates transient transfection expertise for late-stage clinical programs.
Ireland
Dublin and Cork manufacturing parks attract blockbuster antibody originators seeking dual-source supply security alongside European commercial launch capacity. EMA's centralized ATMP classification pulls gene therapy sponsors toward Irish facilities with prior certification experience. Shannon-Freeport zone tax structures anchor Boehringer Ingelheim's integrated development-to-commercial antibody services.
India
CDSCO's streamlined biosimilar approval pathways position Hyderabad and Bengaluru facilities for late-stage clinical and commercial antibody manufacturing. Domestic cost structures compress COGS for sponsors defending against biosimilar competition. Pune-Mumbai corridor concentrates analytical method development capacity that supports accelerated stability study protocols.
CMO and CDMO Biotechnology Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium-positioned CDMOs command manufacturing premiums through viral vector specialization. The vendor base separates into three strategic groupings: integrated pharmaceutical conglomerates with captive biologics divisions, pure-play biologics specialists with platform standardization, and emerging low-cost operators capturing late-stage biosimilar volume. M&A activity concentrates among mid-cap specialists seeking viral vector capacity, while greenfield facility investments cluster in South Korean and Irish free economic zones.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Fujifilm Biotechnics exemplify diversified life sciences operators leveraging analytical instrumentation synergies with bioprocess services. Lonza Group occupies a position among pure-play specialists with dedicated viral vector capacity in Switzerland. Samsung Biologics anchors the scale-driven segment through its Songdo campus concentration of mammalian production expertise. WuXi Biologics represents the emerging low-cost archetype with Chinese domestic cost structures and expanding US and European regulatory filing experience.
| Leading Market Players |
|---|
| Samsung Biologics |
| Boehringer Ingelheim International GmbH |
| Thermo Fisher Scientific |
| AGC Biologics |
| Fujifilm Biotechnologies |
| Lonza Group |
| WuXi Biologics |
| Recipharm |
| Catalent |
| Others |
Pricing and Supply Chain Analysis
Multi-year capacity reservation agreements lock in viral vector supply access for gene therapy sponsors while freezing unit pricing visibility across clinical development stages. FDA comparability protocols and EMA ATMP certification requirements embed regulatory compliance costs into contracted rates, compressing margin flexibility for CDMOs serving cross-border sponsors.
Pricing Analysis
Gene therapy manufacturing commands 40-60% premiums over antibody production in Switzerland and Ireland versus South Korean mammalian cell culture rates. Three-tier pricing structure across ATMP-certified premium, standard GMP, and emerging-economy economy levels segments buyer access by regulatory risk tolerance. Cost compression in antibody manufacturing intensifies as biosimilar sponsors in India leverage CDSCO streamlined pathways to undercut originator COGS. Biotech startups with pre-revenue pipelines exhibit highest price sensitivity, while large pharma multi-program agreements secure volume discounts through master service contracts.
Supply Chain Analysis
North America and Europe anchor plasmid DNA production for viral vector transient transfection, while South Korea concentrates mammalian cell culture expertise at scale. Single-use bioreactor assemblies draw from specialized polymer suppliers in Germany and Japan, with cell culture media formulations resting on serum and recombinant protein inputs. Single-source vulnerability in qualified plasmid suppliers creates chokepoint exposure for AAV and lentiviral programs. Distribution runs through sponsor-directed logistics chains with temperature-controlled custody transfer to clinical sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics outsourcing demand is recovering from pipeline funding constraints as venture deployment into cell and gene therapy reaccelerates. CDMO procurement cycles shorten as sponsors prioritize speed-to-clinic over exhaustive technical diligence.
For Market Incumbents: Compound viral vector capacity advantages through dedicated suite investments in Switzerland and Ireland before EMA ATMP certification backlogs widen. Defend mammalian cell culture margins by backward integration into cell line development platforms that convert early-phase engagements into locked manufacturing contracts. Neutralize emerging Indian biosimilar specialists by co-locating analytical method development with European sponsor clusters.
For New Entrants and Emerging Players: Lead with AI-driven process development tools that compress cell line engineering timelines for Boston and San Francisco biotech clusters. Target Japan's regenerative medicine infrastructure gap in Kobe and Osaka bioclusters where METI incentives outpace qualified CDMO supply. Secure initial revenue through flexible, low-minimum engagement structures for preclinical-stage startups before scaling to commercial supply.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap CDMOs with viral vector specialization and prior BLA submission experience rather than undifferentiated mammalian cell culture assets. Long-term viability hinges on ATMP certification depth and single-use platform standardization that accelerates sponsor onboarding. Watch for inflection when gene therapy sponsor procurement shifts from capacity-scarcity panic to normalized vendor selection cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| ATMP Certification Investment | EMA qualification in Ireland and Switzerland accelerates European commercial launch access for gene therapy sponsors. |
| Single-Use Platform Standardization | Disposable bioreactor deployment reduces facility construction timelines from 36 months to 18 months for rapid scale-up. |
| Viral Vector Capacity Expansion | Dedicated AAV and lentiviral suites capture multi-year sponsor commitments before clinical proof-of-concept data. |
| AI-Driven Process Development | Machine learning convergence with high-throughput screening compresses cell line engineering timelines for early-phase engagement. |
| Dual-Source Supply Structuring | Geographic diversification across South Korean and Irish manufacturing clusters mitigates regulatory divergence risk. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, CDMO procurement managers, and cell therapy manufacturing heads and refined through secondary validation. FDA BLA filings, EMA ATMP certification records, ClinicalTrials.gov entries, and MFDS biosimilar approval databases anchored quantitative segmentation. Bottom-up capacity utilization models and top-down sponsor outsourcing spend estimates were triangulated to cross-check volume assumptions.
Variance-decomposition framing separated volume growth from pricing mix effects across the projection horizon. Segmentation dimensions modeled include service depth, therapy area, product type, client maturity, and regional regulatory cluster. CAGRs were derived from sponsor pipeline progression rates and capacity expansion announcements. Viral vector demand-supply imbalances and continuous bioprocessing adoption curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained venture funding into gene therapy or accelerated EMA ATMP certification timelines would require recalibration. Forecasts reflect documented assumptions about sponsor outsourcing penetration and regulatory harmonization progress. Recalibration cycles align with material shifts in FDA comparability protocol enforcement and plasmid DNA supplier qualification standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Myoglobin Market