
 Anti-Cathepsin B Market | 2026-2036
Anti-Cathepsin B Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Cathepsin B Market Outlook
Subscription-based access to recombinant antibody libraries is hardening the commercial model for research-grade inhibitors. Merck KGaA leverages its European manufacturing footprint to supply GMP-compliant reagents for early-phase drug discovery. Bio-Techne sustains dominance in the hybridoma-derived segment through controlled distribution to North American academic consortia. Thermo Fisher Scientific anchors its position with integrated procurement platforms that bundle anti-cathepsin B products with workflow automation.
Anti-cathepsin B reagents comprise immunoglobulin and synthetic small-molecule compounds that selectively bind or inhibit the cysteine protease cathepsin B, a lysosomal enzyme implicated in extracellular matrix degradation and cancer metastasis; these reagents function as critical tools for elucidating disease mechanisms and validating therapeutic targets in preclinical models. Monoclonal antibodies command the largest share of product-type revenue due to their established validation in immunohistochemistry protocols, while phage display technology is displacing older hybridoma methods for rapid epitope mapping in neurological disorder research. Pharmaceutical companies represent the most concentrated end-user segment, as internal target-validation teams outsource fewer steps and consolidate vendor relationships around certified suppliers.
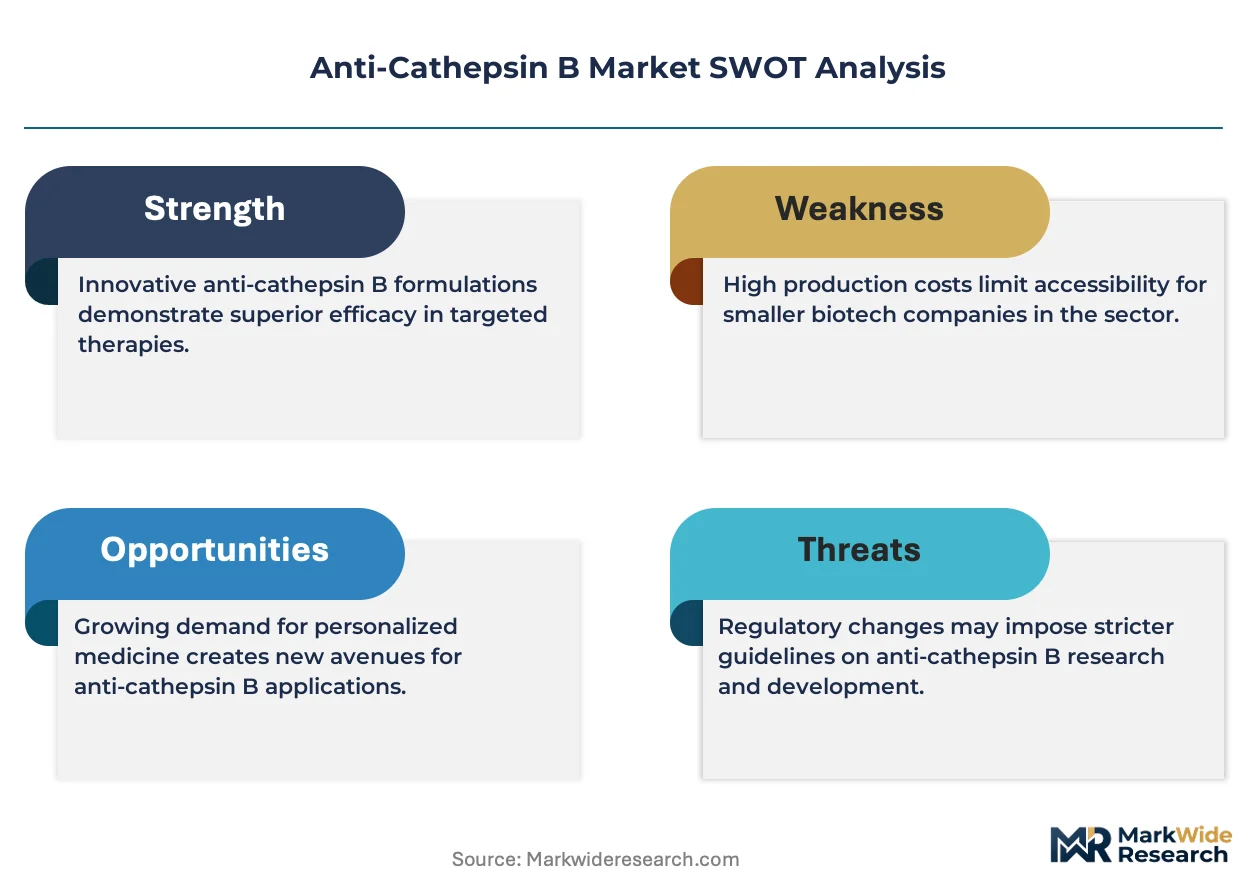
The FDA maintains stringent lot-release requirements for research antibodies used in IND-enabling studies, while the EMA's MDR framework extends quality documentation obligations to diagnostic-grade reagents imported into Europe. Japan's PMDA imposes additional stability-testing standards on temperature-sensitive biologicals, compelling exporters to maintain dual validation protocols. Stakeholders must monitor evolving pharmacopeial harmonization between ICH member states, as divergence in impurity thresholds threatens to fragment supplier qualification requirements and inflate compliance overhead.
Market Dynamics
Oncology drug developers are consolidating vendor relationships around certified antibody suppliers as IND-enabling studies demand GMP-compliant reagents with full lot-release documentation. This supplier concentration is compressing procurement timelines while elevating qualification barriers for smaller reagent producers.
Growth Catalysts
- FDA Accelerated Approval:The FDA's streamlined pathways for targeted cancer therapies compress clinical trial design timelines, pulling forward demand for validated cathepsin B inhibitors in tumor microenvironment modulation studies.
- Phage Display Technology:Phage display methods are displacing hybridoma approaches for rapid epitope mapping in neurological disorder research, expanding the addressable application base for research-grade reagents.
- Boston and San Francisco Clusters:Preclinical sourcing concentrates in these biopharma R&D hubs, creating dense demand pools that sustain premium pricing for certified suppliers.
Market Restraints
- Dual Validation Overhead:Japan's PMDA imposes additional stability-testing standards on temperature-sensitive biologicals, compelling exporters to maintain parallel protocols that inflate compliance costs.
- Hybridoma Method Lock-in:Academic consortia retain entrenched workflows with established hybridoma-derived antibodies, slowing adoption of newer recombinant platforms despite superior performance.
- ICH Harmonization Gaps:Divergence in impurity thresholds between ICH member states fragments supplier qualification requirements and threatens to bifurcate manufacturing runs.
Strategic Opportunities
- Integrated Procurement Platforms:Workflow automation bundling creates stickier customer relationships and captures share from standalone reagent distributors.
- EMA MDR Framework:Europe's extended quality documentation obligations for diagnostic-grade reimports favor suppliers with established European manufacturing footprints.
- Neurological Disorder Research:Emerging applications in neurodegeneration models represent underpenetrated therapeutic areas with less mature competitive dynamics than oncology.
Industry Challenges
- GMP Certification Timelines:Lot-release documentation for IND-enabling studies extends production cycles and strains capacity planning for multi-product facilities.
- Epitope Mapping Skill Gaps:Phage display expertise remains concentrated in specialized contract research organizations, limiting in-house adoption at mid-tier pharmaceutical companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Cathepsin B Market |
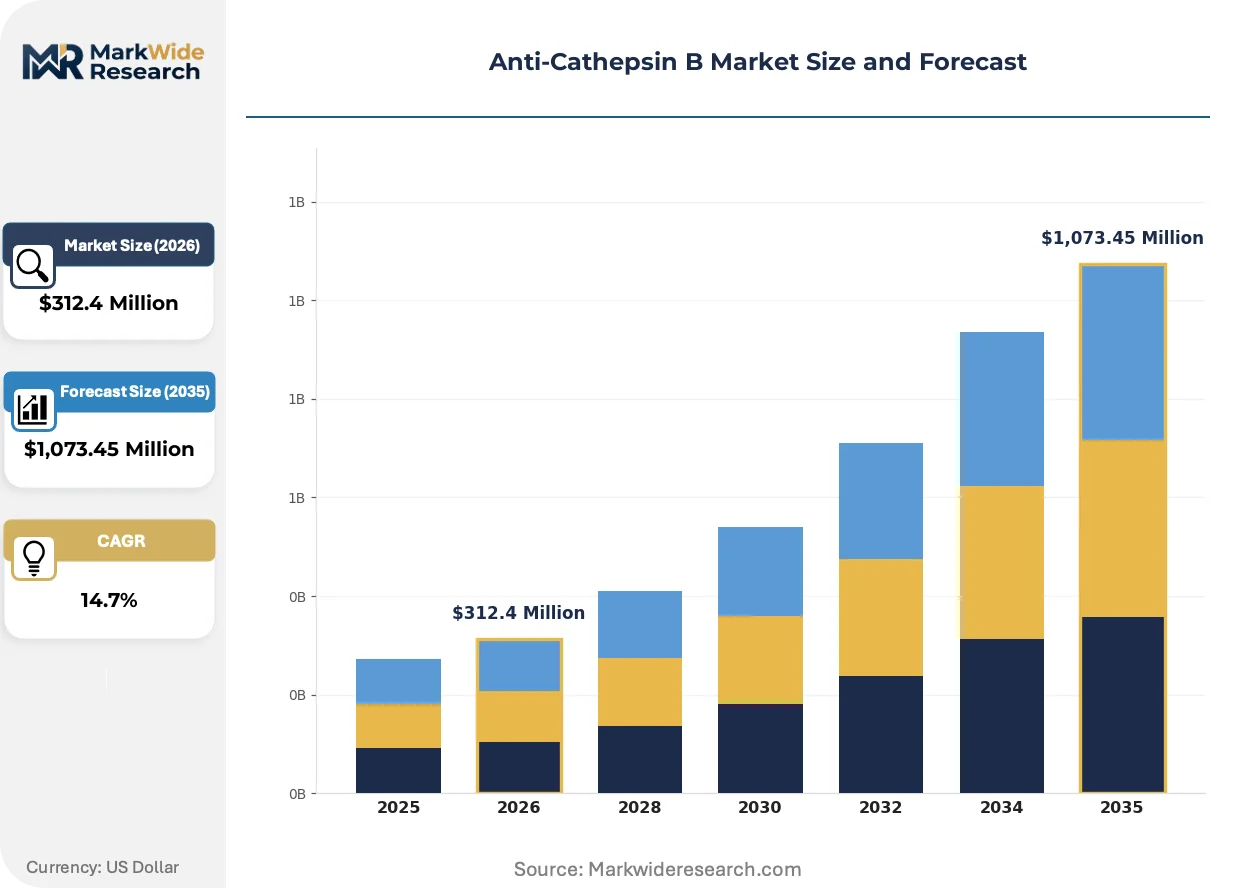
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Peptides, Inhibitors Technology: Recombinant Technology, Chemical Synthesis, Hybridoma Technology, Phage Display Application: Oncology, Autoimmune Disorders, Cardiovascular Diseases, Neurological Disorders End User: Research Laboratories, Pharmaceutical Companies, Clinical Research Organizations, Academic Institutions |
| Companies Covered | Merck KGaA, Bio-Techne, Abcam Plc, Santa Cruz Biotechnology, Inc, Thermo Fisher Scientific, BioVision Inc., Cayman Chemical, Selleck Chemicals, MedChemExpress, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Cathepsin B Market Strategic Shifts
Research antibody production is bifurcating between legacy hybridoma methods and recombinant platforms, with vendor business models hardening around subscription-based access rather than perpetual licensing.
Recombinant antibody libraries are converging with automated high-throughput screening systems to compress target-validation timelines. Pharmaceutical internal teams are adopting these integrated workflows at accelerating pace. The technology convergence is enabling real-time epitope optimization that previously required months of iterative hybridoma refinement.
REACH regulatory extensions in Europe are tightening substance registration requirements for synthetic small-molecule inhibitors used in preclinical models. Industrial consequence includes mandatory safety dossier updates that elevate documentation burdens for importers. Diagnostic-grade reagents face the steepest compliance adjustments, with suppliers restructuring European distribution to maintain MDR-aligned quality chains.
Buyer concentration around certified suppliers is shortening switching cycles and unbundling after-sales technical support. Standalone reagent vendors are losing share to integrated platform providers that bundle antibodies with automation hardware and cloud-based data management. The behavioral shift is most visible in United States academic medical centers, where procurement committees now mandate vendor ISO 13485 certification for orders exceeding threshold volumes.
Anti-Cathepsin B Market Segmentation
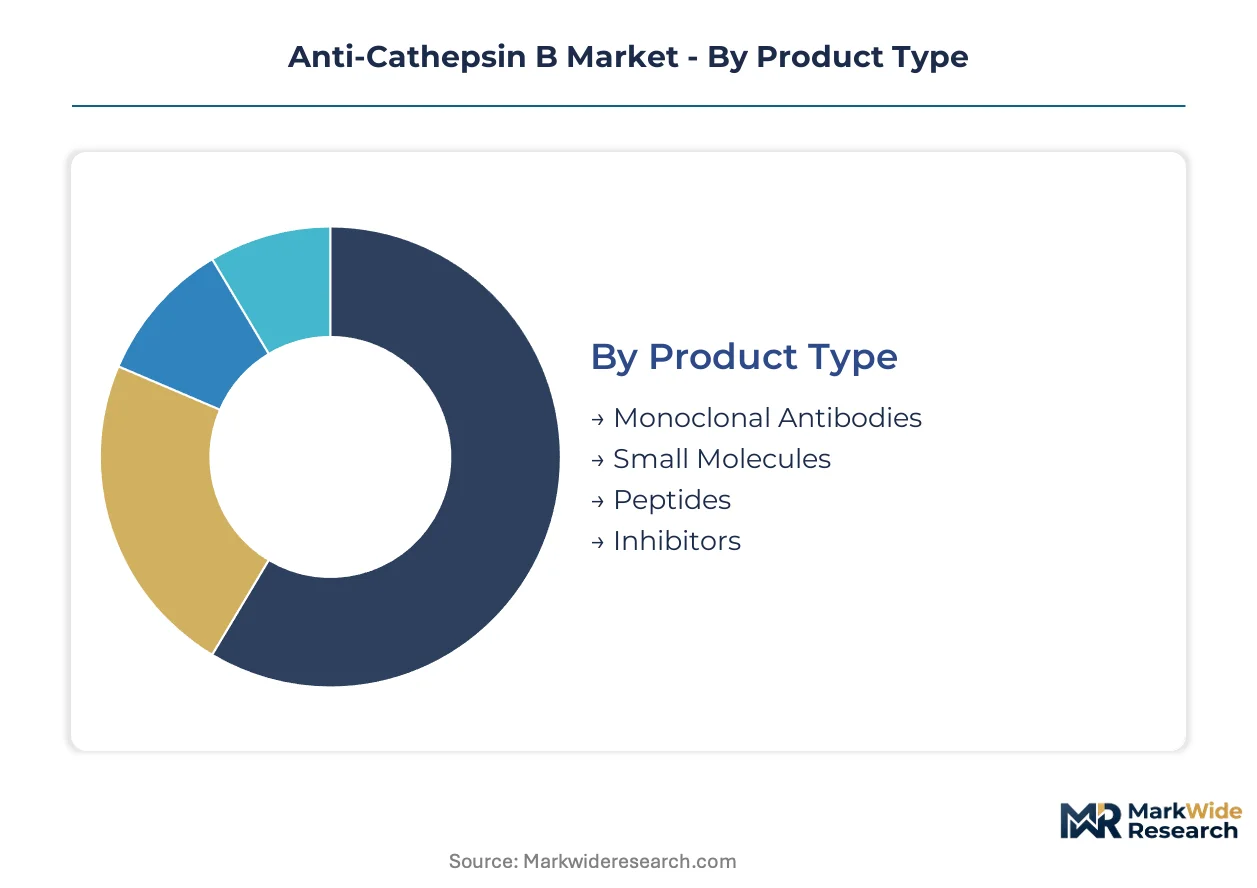
Segmentation in the anti-cathepsin B market reveals divergent capital requirements and validation burdens across reagent categories. Procurement committees weight GMP certification, lot-release documentation, and regional regulatory alignment differently depending on end-use criticality.
Product Type:
Capital intensity varies sharply across molecular formats, with biological production demanding substantially higher upfront facility investment than synthetic chemistry.
- Monoclonal Antibodies:Immunoglobulin-based reagents produced via mammalian cell culture or hybridoma systems require dedicated bioreactor suites and extensive lot-release testing. Pharmaceutical companies in the United States consolidate procurement around certified suppliers for IND-enabling oncology studies, compressing vendor shortlists.
- Small Molecules:Synthetic organic compounds manufactured through multi-step chemical synthesis offer lower per-batch production costs but face tightening REACH substance registration requirements in Europe. Academic institutions favor these for high-throughput screening campaigns where antibody specificity is less critical.
- Peptides:Short amino acid chains synthesized via solid-phase methods bridge biological and chemical production modalities.
- Inhibitors:Functional compounds designed for enzymatic blockade span both small-molecule and peptide architectures.
Monoclonal antibodies absorb the bulk of installed capacity; small molecules are expanding most quickly in European preclinical sourcing.
Technology:
Platform selection determines speed-to-clone, epitope precision, and intellectual property freedom—factors that reshape competitive positioning in contract research markets.
- Recombinant Technology:DNA-encoded antibody libraries expressed in bacterial or yeast systems enable rapid sequence optimization and humanization. Boston-area biopharma clusters drive adoption for tumor microenvironment target validation where iterative refinement accelerates candidate selection.
- Phage Display:Bacteriophage-linked peptide libraries facilitate epitope mapping at throughput rates exceeding hybridoma methods. Neurological disorder research programs favor this platform for blood-brain barrier penetration studies.
- Chemical Synthesis:Traditional organic chemistry approaches dominate small-molecule inhibitor production with established scale-up pathways.
- Hybridoma Technology:Murine-derived monoclonal production retains entrenched workflows in academic consortia despite longer development timelines.
Recombinant platforms command the steepest R&D investment; phage display is climbing the fastest as neurological applications mature.
Application:
Therapeutic area focus dictates regulatory pathway complexity and reagent performance specifications, with oncology imposing the most stringent validation standards.
- Oncology:Tumor microenvironment modulation studies demand antibodies with demonstrated specificity in immunohistochemistry protocols and validated lot-to-lot consistency. FDA accelerated approval pathways compress clinical timelines, pulling forward demand for GMP-compliant reagents in United States drug development pipelines.
- Neurological Disorders:Blood-brain barrier penetration and neuroinflammation models require specialized epitope mapping for tissue-specific targeting. Phage display methods are displacing older platforms in this segment as researchers prioritize rapid candidate generation.
- Autoimmune Disorders:Lysosomal enzyme dysregulation studies in rheumatoid arthritis and lupus models drive steady reagent consumption.
- Cardiovascular Diseases:Atherosclerotic plaque degradation research represents a smaller but growing application area.
Oncology absorbs the bulk of validated reagent capacity; neurological disorders are gaining share fastest as platform technology improves.
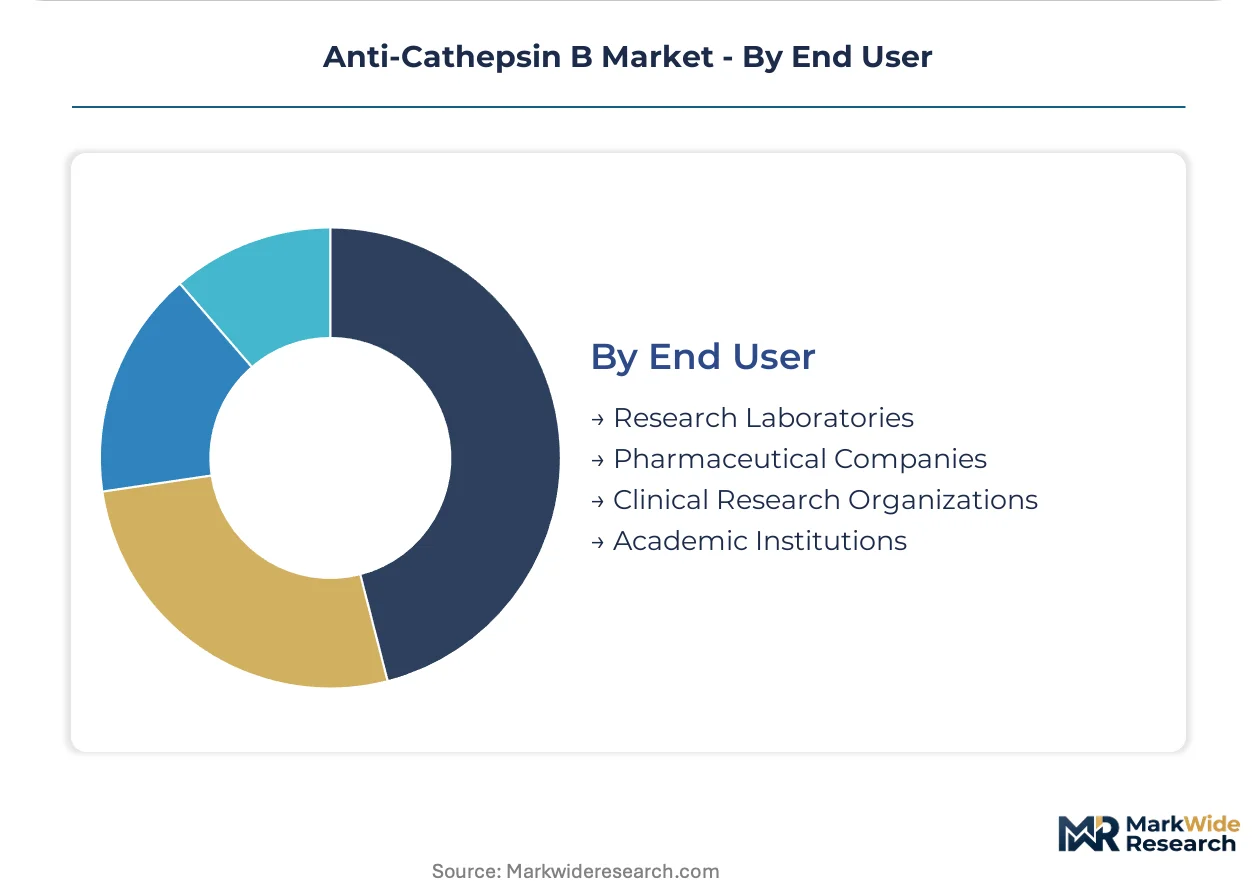
End User:
Customer type determines procurement centralization, technical support expectations, and compliance documentation burdens.
- Pharmaceutical Companies:Internal target-validation teams maintain consolidated vendor relationships with certified suppliers, mandating ISO 13485 certification and full lot-release documentation for IND-enabling studies. Procurement committees in United States headquarters enforce strict qualification protocols that elevate barriers for smaller reagent producers.
- Research Laboratories:Academic medical centers and independent research institutes exhibit fragmented purchasing with greater price sensitivity. Subscription-based access to recombinant libraries is hardening the commercial model in this segment.
- Clinical Research Organizations:Contract service providers balance client-mandated specifications with operational flexibility across multiple sponsor programs.
- Academic Institutions:University-based research groups retain entrenched hybridoma workflows despite performance advantages of newer platforms.
Pharmaceutical companies absorb the bulk of premium-grade supply; research laboratories are expanding most quickly as platform accessibility improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of anti-cathepsin B reagents concentrates in European and North American manufacturing hubs, while consumption gravitates toward United States biopharma clusters and East Asian research centers. This geographic split creates cross-border supply chains with distinct regulatory compliance burdens. Export-oriented suppliers maintain dual validation protocols to serve multiple pharmacopeial jurisdictions.
United States
FDA accelerated approval pathways for targeted cancer therapies compress clinical trial timelines, pulling forward demand for GMP-compliant cathepsin B inhibitors. The agency's stringent lot-release requirements for IND-enabling studies elevate barriers for uncertified reagent producers. Boston and San Francisco biopharma clusters drive dense preclinical sourcing, with procurement committees mandating ISO 13485 certification for threshold-volume orders.
Germany
Merck KGaA leverages its European manufacturing footprint to supply GMP-compliant reagents for early-phase drug discovery across the continent. EMA's MDR framework extends quality documentation obligations to diagnostic-grade reagents, favoring established suppliers with integrated European distribution. The Rhine-Main and Upper Bavaria regions host concentrated life sciences infrastructure serving contract research demand.
Japan
PMDA imposes additional stability-testing standards on temperature-sensitive biologicals, compelling exporters to maintain parallel validation protocols that inflate compliance costs. Domestic pharmaceutical companies consolidate procurement around certified antibody suppliers for target-validation studies. The Kanto and Kansai metropolitan areas concentrate R&D demand from major drug developers.
China
NMPA regulatory harmonization with ICH standards is reshaping import requirements for research-grade antibodies used in IND-enabling studies. Domestic biotech clusters in Shanghai and Suzhou expand preclinical sourcing capacity, though certified reagent supply remains import-dependent. The Yangtze River Delta biopharma corridor drives fastest-growing regional demand for tumor microenvironment research tools.
United Kingdom
Academic medical centers in London and Cambridge retain entrenched hybridoma workflows despite performance advantages of newer recombinant platforms. MHRA alignment with EU MDR post-Brexit creates transitional documentation requirements for diagnostic-grade reagent importers. The Golden Triangle research cluster sustains premium pricing tolerance for validated antibody suppliers.
Anti-Cathepsin B Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the anti-cathepsin B reagent landscape. Integrated life sciences conglomerates with captive bioreactor capacity face specialized antibody developers outsourcing manufacturing to contract production networks. Three archetypes dominate: diversified platform providers bundling reagents with automation hardware; focused recombinant technology specialists; and legacy hybridoma-derived product incumbents. Consolidation pressures favor M&A-driven portfolio expansion and strategic partnerships bridging technology gaps.
Among diversified platform providers, Thermo Fisher Scientific anchors the integrated procurement segment, while Merck KGaA exemplifies European manufacturing-centric supply. Bio-Techne occupies a position within the specialized antibody tier, reflecting hybridoma-derived incumbent archetype positioning. These three entities collectively represent the competitive spectrum from workflow automation bundling to regional GMP compliance leadership.
| Leading Market Players |
|---|
| Merck KGaA |
| Bio-Techne |
| Abcam Plc |
| Santa Cruz Biotechnology, Inc |
| Thermo Fisher Scientific |
| BioVision Inc. |
| Cayman Chemical |
| Selleck Chemicals |
| MedChemExpress |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap antibody specialists in Germany and Japan anchor premium pricing through captive bioreactor capacity, while private-equity-rolled-up distributors compress margins in the research-grade tier through volume aggregation. This ownership split creates divergent supply behaviors: integrated producers defend pricing through ISO 13485 certification bundling, whereas asset-light platforms sacrifice margin for procurement automation share.
Pricing Analysis
Margin tightening in the pharmaceutical-grade tier reflects FDA lot-release documentation burdens that extend production cycles and elevate fixed-cost absorption. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified antibodies for IND-enabling studies from research-grade reagents and bulk-screening compounds. Academic institutions exhibit highest price sensitivity, while United States biopharma procurement committees absorb premiums for validated suppliers with full traceability. Pricing pressure stems from subscription-based recombinant library access displacing perpetual licensing revenue.
Supply Chain Analysis
Return flows of temperature-compromised biologicals from Japan's PMDA-mandated stability-testing failures create reverse-logistics complexity that inflates exporter overhead. Supply concentrates in Germany, the United States, and China, with Merck KGaA's European manufacturing footprint and Boston-area biopharma clusters anchoring GMP-compliant production. Mammalian cell culture media, recombinant expression vectors, and synthetic peptide precursors constitute critical input dependencies. Single-source vulnerability in hybridoma-derived murine antibody lines threatens continuity for legacy academic workflows. Distribution runs through integrated procurement platforms bundling reagents with workflow automation hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures favor scaled platform providers as GMP certification timelines and dual-validation overhead force smaller reagent producers toward strategic exit or acquisition.
For Market Incumbents: Lock in procurement committee relationships at United States academic medical centers through ISO 13485 certification bundling with cloud-based lot-traceability systems. Defend against phage display displacement by acquiring recombinant technology specialists in Boston or San Francisco clusters. Prioritize backward integration into mammalian cell culture media production to secure input cost control. For New Entrants and Emerging Players: Contract research organizations in neurological disorder programs represent the most penetrable channel partner type for rapid epitope mapping services. Target blood-brain barrier penetration studies where phage display expertise remains concentrated and competitive dynamics are less mature than oncology. White-space exists in European diagnostic-grade reagent reimport compliance under EMA MDR framework extensions. For Investors and Strategic Acquirers: FDA accelerated approval pathway announcements for tumor microenvironment modulation therapies are the leading indicator that demand for validated cathepsin B inhibitors will tighten supply capacity. Long-term viability favors vertically integrated producers with captive bioreactor assets and established European distribution. Monitor ICH harmonization negotiations for impurity threshold divergence that would fragment supplier qualification requirements and trigger distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA accelerated approval pathways compress oncology study timelines and pull forward GMP reagent demand. |
| Regulatory Approval Pathway | EMA MDR framework extensions favor suppliers with integrated European quality documentation chains. |
| Manufacturing Scale-Up | Captive bioreactor capacity in Boston and San Francisco clusters secures premium pricing power. |
| Backward Integration | In-house production of mammalian cell culture media reduces input cost volatility for antibody manufacturers. |
| Strategic Partnership | Phage display technology licensing agreements bridge skill gaps at mid-tier pharmaceutical companies. |
Study Parameters
Independent corroboration across primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers, combined with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, underwrites the qualitative findings. Bottom-up demand modeling across product type, technology platform, therapeutic application, and end-user segments triangulates against top-down market sizing from trade data and SEC disclosures.
Comparable-period anchoring to historical antibody reagent consumption patterns established the forecast baseline, with projections extending across the analysis window through segmented CAGR derivation. Modeled dimensions span molecular format, production technology, disease indication, customer type, and regional regulatory cluster. Oncology pipeline advancement rates and neurological disorder research funding trajectories constitute key industry-specific forecast inputs.
Caveats apply where ICH pharmacopeial harmonization gaps, PMDA stability-testing standard revisions, or REACH substance registration extensions could materially shift the outlook. Practitioners should monitor FDA accelerated approval pathway designations and EMA MDR implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Gestational Trophoblastic Disease Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market