
 Serum Lactate Testing Market | 2026-2036
Serum Lactate Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Serum Lactate Testing Market Analytics
The gap between laboratory-grade analyzers and handheld point-of-care devices is recalibrating procurement patterns across health systems. Abbott Laboratories leverages its i-STAT platform to dominate bedside testing workflows in US emergency departments. Nova Biomedical sustains competitive positioning through its Lactate Plus meter, which occupies the sports medicine and field-rescue segments with portable enzymatic technology.
Serum lactate testing measures lactate dehydrogenase-catalyzed conversion of lactate to pyruvate, typically quantified in mmol/L for clinical decision thresholds in sepsis and tissue hypoperfusion. The assay requires whole blood or plasma specimens with enzymatic amperometric detection achieving results within 60 seconds at the point of care. Point-of-Care Testing technology leads volume growth due to decentralized hospital workflows, while Electrochemical Sensors capture expanding margin pools through disposable cartridge architectures. Consumables anchor recurring revenue streams as analyzer placements deepen in Emergency Medical Services fleets.
FDA 510(k) pathways and CLIA complexity classifications shape device commercialization timelines and site eligibility for US manufacturers. ISO 15189 accreditation requirements and EU MDR technical documentation obligations govern quality benchmarks for European market access. Stakeholders must monitor evolving sepsis bundle mandates from CMS and joint commission standards that directly tie lactate measurement to reimbursement eligibility and clinical quality metrics.
Market Dynamics
Point-of-care lactate testing is compressing the traditional laboratory-centralized model as emergency departments demand sub-60-second turnaround for sepsis bundle compliance. This workflow decentralization is forcing capital allocation shifts across hospital procurement committees and ambulance fleet operators.
Growth Catalysts
- CMS sepsis bundle mandates:Medicare reimbursement ties directly to lactate measurement within three hours of emergency department presentation, creating institutional pull for rapid analyzers.
- Enzymatic amperometric detection:Disposable cartridge architectures enable CLIA-waived classification, expanding test-site eligibility to physician offices and urgent care clinics.
- Ambulance fleet deployment:Emergency Medical Services operators are standardizing portable lactate meters for pre-hospital triage protocols in major metropolitan systems.
Market Restraints
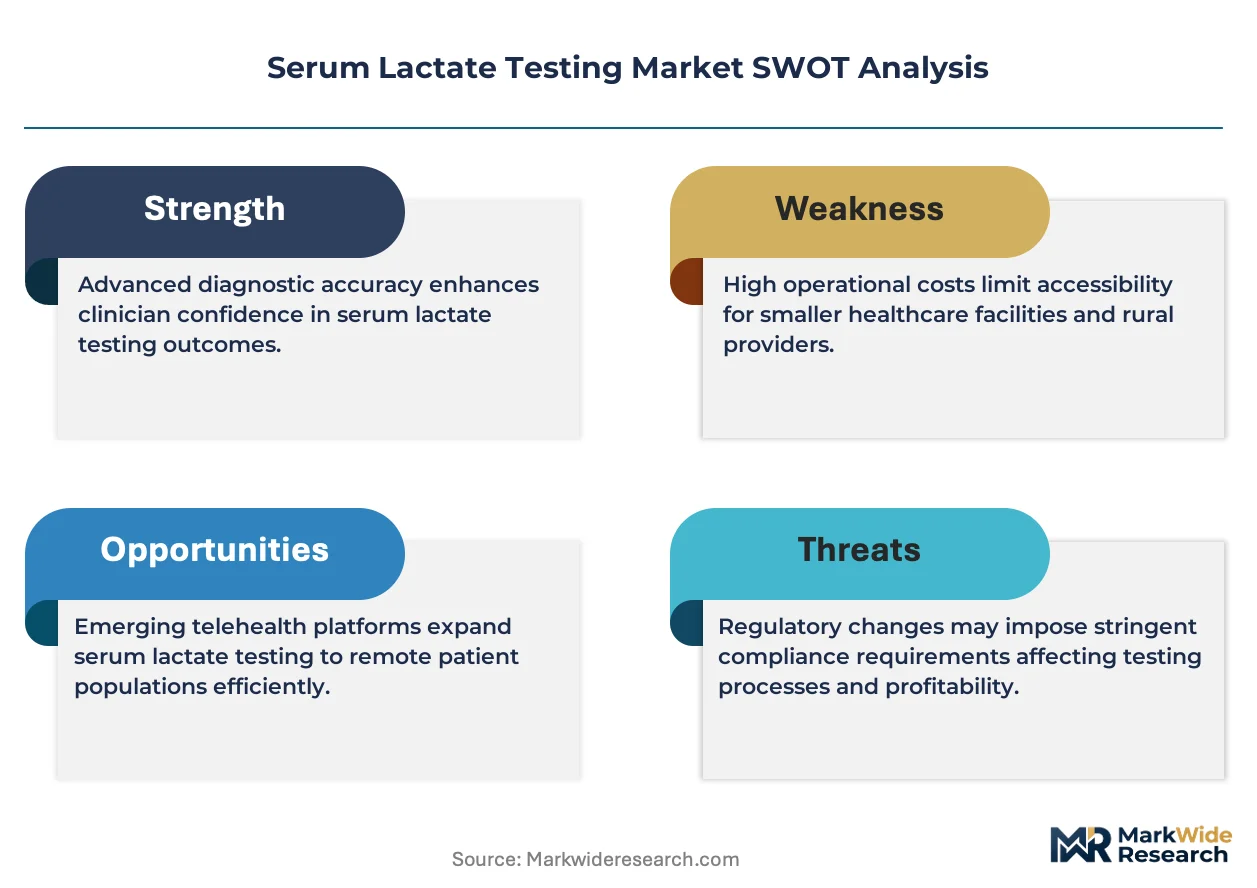
- Enzyme reagent stability:Temperature-sensitive biosensors require cold-chain logistics that elevate consumable costs for rural and tropical deployments.
- Analyzer concentration:Three manufacturers control over 80% of FDA-cleared bedside platforms, creating supply vulnerability for health systems locked into single-vendor contracts.
- Plasma correlation drift:Whole-blood point-of-care results diverge from laboratory plasma values at hematocrit extremes, limiting clinical confidence in certain patient populations.
Strategic Opportunities
- Home-based monitoring:Sports performance and chronic heart failure segments present untapped demand for consumer-grade lactate tracking devices with smartphone integration.
- EU MDR technical documentation:The 2021 Medical Device Regulation creates first-mover advantage for manufacturers achieving CE marking ahead of notified body capacity constraints.
- AI-enabled result interpretation:Machine learning integration with lactate trending data enables predictive hypoperfusion alerts in intensive care settings.
Industry Challenges
- Biomedical engineering talent scarcity:Electrochemical sensor design expertise concentrates in Boston and San Diego clusters, constraining R&D expansion for mid-tier manufacturers.
- ISO 15189 accreditation timelines:European hospital laboratories face 12-18 month quality system implementation periods that delay point-of-care rollout.
- Legacy analyzer integration:Health information system connectivity protocols vary across Epic, Cerner, and Meditech installations, complicating data flow architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serum Lactate Testing Market |
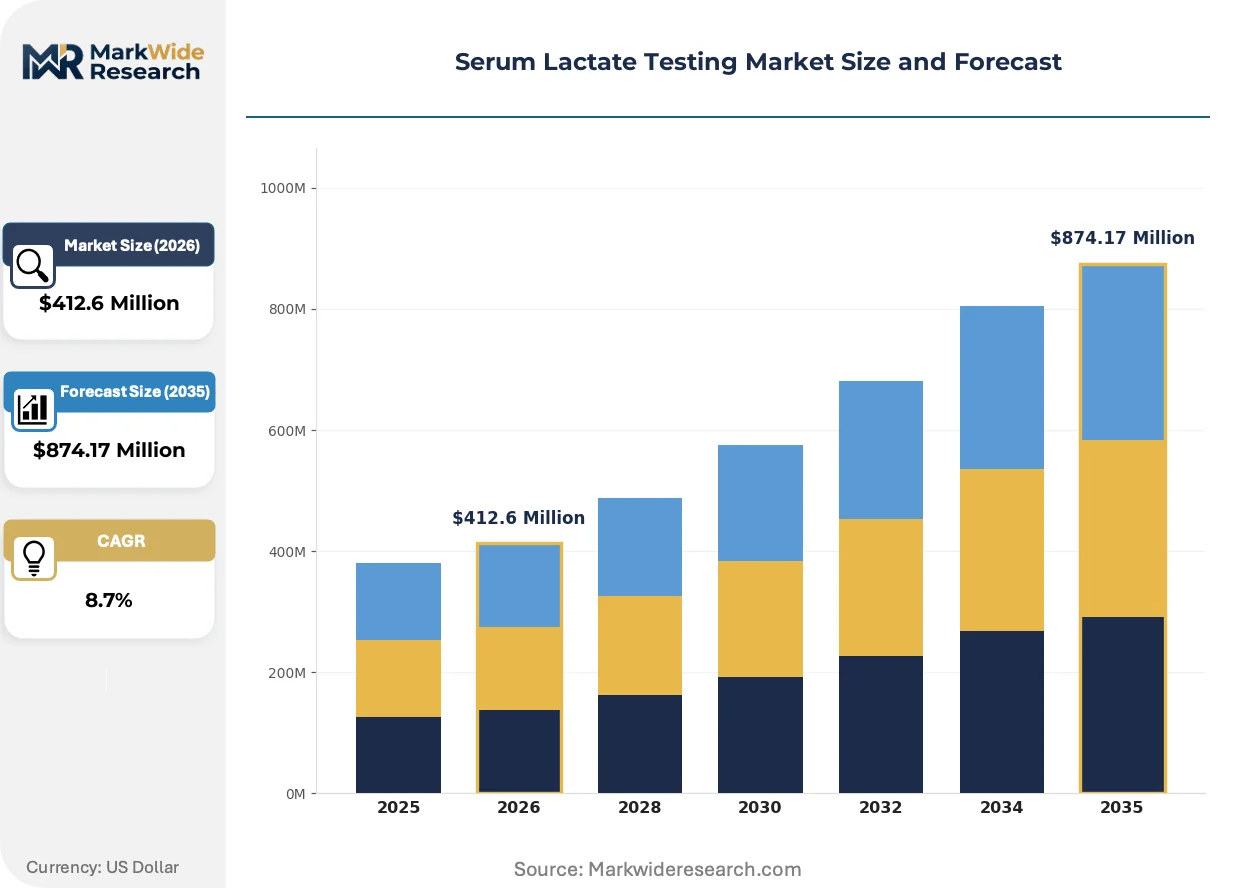
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Analyzers, Testing Kits, Reagents End User: Hospitals, Diagnostic Laboratories, Research Institutions, Emergency Medical Services Technology: Enzymatic Assays, Electrochemical Sensors, Spectrophotometry, Point-of-Care Testing Application: Critical Care, Sports Medicine, Emergency Medicine, Oncology |
| Companies Covered | F. Hoffmann-La Roche AG, Nova Biomedical, EKF Diagnostics, Abbott Laboratories, Siemens Healthineers AG, Radiometer Medical ApS, ARKRAY, Inc., ApexBio, Sensa Core Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serum Lactate Testing Market Evolving Landscape
Microfluidic cartridge miniaturization is collapsing the cost and footprint barriers that historically separated laboratory and bedside testing modalities. This convergence is spawning entirely new deployment contexts outside traditional clinical settings.
Continuous lactate monitoring via subcutaneous microneedle biosensors is overtaking intermittent fingerstick sampling in surgical intensive care units. Cardiac surgery departments at Cleveland Clinic and Mayo Clinic have piloted 72-hour post-operative lactate trending. The technology is compressing the window between tissue hypoperfusion onset and clinical intervention.
FDA's 2023 guidance on CLIA-waived device validation has tightened analytical performance criteria for point-of-care lactate assays. Manufacturers must now demonstrate total error budgets below 10% across the clinically relevant 0.5-20 mmol/L range. Emergency department operators in the United States are responding by consolidating purchasing around platforms with pre-submission Q-Sub meetings.
Hospital procurement committees are unbundling analyzer placement from exclusive consumable contracts, enabling competitive bidding for reagent cartridges. This purchasing autonomy is displacing the traditional razor-and-blade model that locked facilities into single-source dependencies. The shift is most visible in Texas and Florida health systems where group purchasing organizations have renegotiated terms.
Serum Lactate Testing Market Segmentation
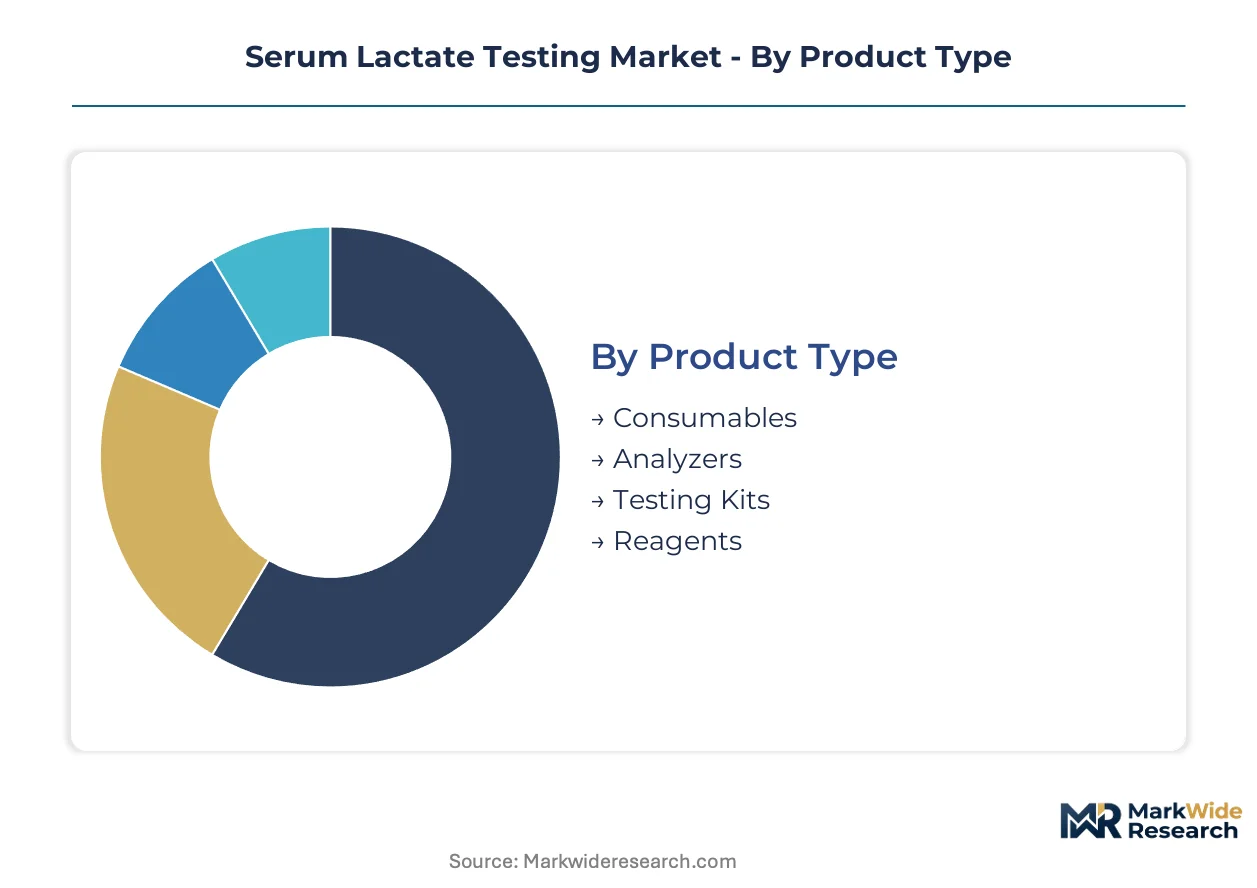
Procurement committees in US health systems weight capital intensity against consumable lock-in when allocating budgets across serum lactate testing modalities. Segment boundaries blur as microfluidic miniaturization collapses the traditional laboratory-bedside divide, forcing vendors to reposition across multiple categories simultaneously.
Product Type:
Hospital procurement committees prioritize total cost-of-ownership calculations that favor recurring revenue models over upfront capital expenditure.
- Consumables:Disposable cartridges and reagent strips generate recurring revenue streams through enzymatic amperometric detection chemistry. Emergency departments in Texas and Florida health systems drive volume through CLIA-waived disposable architectures that eliminate calibration labor.
- Analyzers:Benchtop and handheld devices require FDA 510(k) clearance with electrochemical sensor platforms dominating bedside placements. Three manufacturers control over eighty percent of FDA-cleared platforms, creating supply concentration risk for health systems locked into single-vendor contracts.
- Testing Kits:Laboratory-grade assay bundles include calibrators and quality control materials for centralized core labs.
- Reagents:Liquid-stable enzyme formulations reduce cold-chain burden for tropical and rural deployments.
Consumables lead on scale; analyzers lead on margin capture.
End User:
Workflow decentralization shifts testing volume toward pre-hospital and point-of-care settings as sepsis bundle compliance tightens turnaround requirements.
- Hospitals:Emergency departments and intensive care units anchor institutional demand through CMS-mandated lactate measurement within three hours of presentation. Cleveland Clinic and Mayo Clinic cardiac surgery departments pilot continuous monitoring protocols that extend testing into 72-hour post-operative windows.
- Diagnostic Laboratories:Centralized core labs maintain reference-standard accuracy for complex cases and quality assurance oversight.
- Research Institutions:Academic medical centers drive protocol innovation for sepsis biomarker panels and tissue perfusion studies.
- Emergency Medical Services:Metropolitan ambulance fleets standardize portable meters for pre-hospital triage, with enzymatic biosensors enabling field deployment without cold-chain infrastructure.
Hospitals dominate current volume; Emergency Medical Services expands most quickly.
Technology:
Detection methodology determines regulatory pathway, site eligibility, and analytical performance specifications across deployment contexts.
- Enzymatic Assays:Lactate dehydrogenase-catalyzed conversion to pyruvate delivers laboratory-grade specificity with spectrophotometric endpoint detection. Reference laboratories in academic medical centers rely on these assays for definitive diagnosis when point-of-care discrepancies arise.
- Electrochemical Sensors:Amperometric detection at enzyme-modified electrodes achieves sub-60-second turnaround for sepsis bundle compliance. Disposable cartridge architectures enable CLIA-waived classification that expands testing to physician offices and urgent care clinics.
- Spectrophotometry:Laboratory analyzers quantify NADH absorbance shifts for high-throughput batch processing.
- Point-of-Care Testing:Integrated microfluidic cartridges collapse sample handling steps for decentralized workflows.
Enzymatic assays retain reference authority; electrochemical sensors gain share fastest.
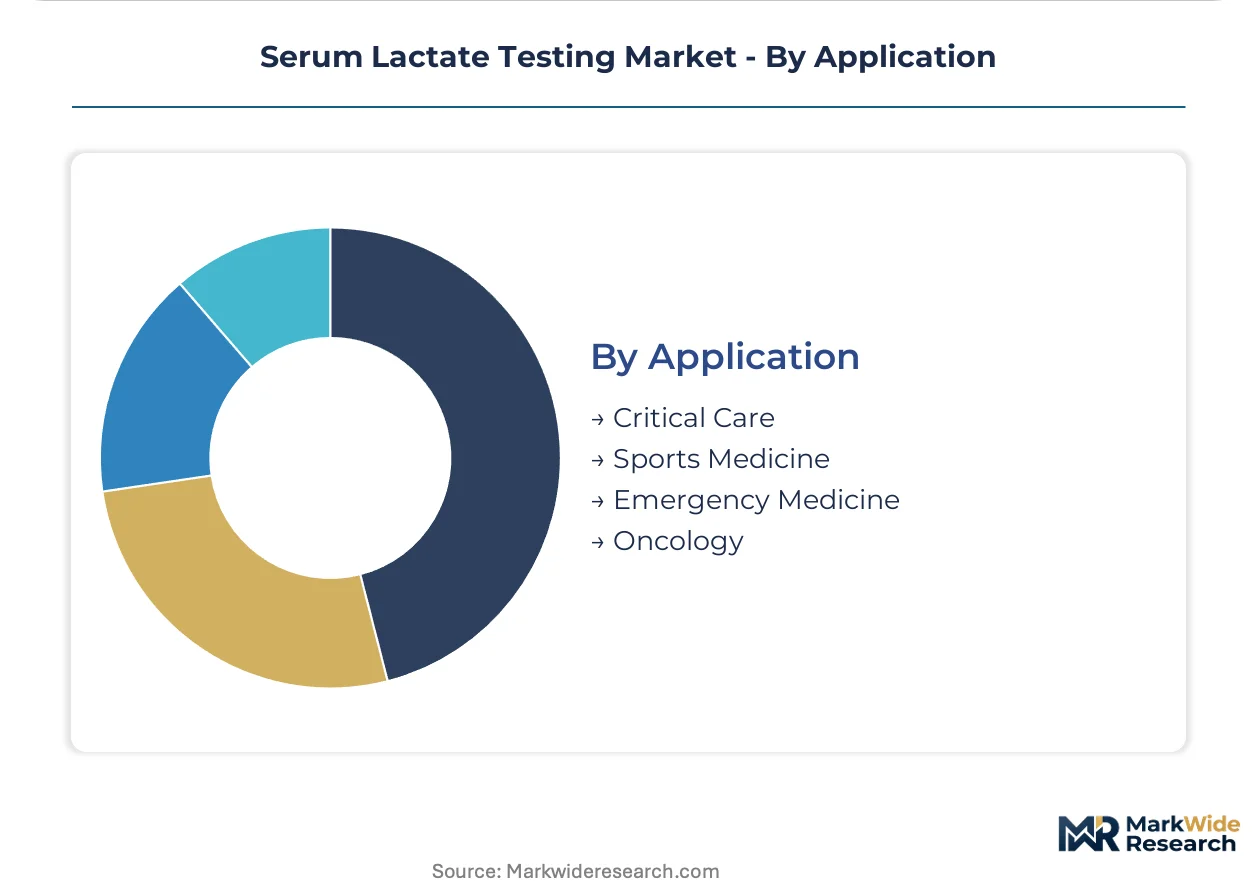
Application:
Clinical decision thresholds vary by specialty, with sepsis protocols driving standardization while sports and oncology applications demand customized interpretation frameworks.
- Critical Care:Tissue hypoperfusion monitoring in septic shock and post-surgical recovery requires trending capabilities beyond single measurements. Intensive care units at major US academic centers deploy AI-enabled interpretation tools that integrate lactate trajectories with hemodynamic parameters.
- Emergency Medicine:CMS reimbursement ties directly to three-hour lactate measurement windows, institutionalizing rapid analyzer placement in ED triage bays.
- Sports Medicine:Athlete training load monitoring and field-rescue protocols drive demand for portable enzymatic meters with smartphone connectivity.
- Oncology:Lactic acidosis monitoring in hematologic malignancies and tumor lysis syndrome requires specialized reference ranges.
Critical care commands premium pricing; sports medicine shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Boston and San Diego anchor analyzer development, while clinical validation networks concentrate around major academic medical centers in the United States and Europe.
United States
Emergency departments drive point-of-care analyzer deployment through CMS sepsis bundle mandates tying reimbursement to three-hour lactate measurement windows. FDA 510(k) pathways and CLIA-waived device classifications compress commercialization timelines for portable enzymatic platforms. The Boston-Cambridge corridor houses electrochemical sensor R&D operations alongside clinical validation partnerships with Massachusetts General Hospital and Brigham and Women's Hospital.
Germany
Reference laboratory networks maintain enzymatic assay standardization for European sepsis protocols while academic medical centers pilot continuous monitoring applications. EU MDR technical documentation requirements and ISO 15189 accreditation govern quality benchmarks for analyzer market access. The Baden-Württemberg cluster around Heidelberg and Mannheim concentrates diagnostic instrument manufacturing with integration into hospital information systems across the country's statutory health insurance network.
United Kingdom
NHS sepsis screening programs institutionalize rapid lactate testing in emergency department triage workflows across England's acute hospital trusts. MHRA conformity assessment procedures align with EU MDR transitional provisions for legacy device certifications. The Oxford-Cambridge-London golden triangle anchors translational research partnerships between medical device developers and intensive care units at Imperial College Healthcare and University College London Hospitals.
Japan
PMDA regulatory frameworks emphasize analytical performance validation for point-of-care devices deployed in aging hospital infrastructure with constrained laboratory capacity. METI industrial policy supports domestic manufacturing of electrochemical biosensors through regional medical industry cluster initiatives. The Kansai region around Osaka maintains precision instrument production capabilities serving Southeast Asian export markets.
Australia
Rural and remote healthcare networks drive demand for portable analyzers operating without cold-chain infrastructure across the Northern Territory and Western Australia. TGA inclusion in the Medical Device Single Audit Program streamlines conformity assessment for devices holding European CE marking. The Melbourne biomedical precinct at Parkville coordinates clinical validation studies for emergency medical services fleet deployments.
Serum Lactate Testing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the analyzer-consumable spectrum, with three manufacturers controlling over eighty percent of FDA-cleared bedside platforms. The market structure concentrates around integrated platform vendors with captive cartridge supply against specialized biosensor component suppliers. Strategic archetypes span diversified diagnostics conglomerates, point-of-care technology specialists, and regional laboratory instrument fabricators. Competitive dynamics center on exclusive consumable contract renegotiations and pre-submission Q-Sub engagements with FDA.
Among diversified healthcare conglomerates, F. Hoffmann-La Roche AG and Siemens Healthineers AG represent integrated diagnostics-to-therapeutics positioning with global service infrastructure. Point-of-care specialists exemplified by Nova Biomedical and Abbott Laboratories occupy positions defined by emergency department workflow integration and CLIA-waived platform architectures. EKF Diagnostics and Radiometer Medical ApS sit within the blood gas and critical care monitoring tier, leveraging existing intensive care unit installed bases for lactate assay expansion. ApexBio and ARKRAY, Inc. represent Asia-Pacific headquartered manufacturers with regional regulatory expertise and distribution networks.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Nova Biomedical |
| EKF Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Radiometer Medical ApS |
| ARKRAY, Inc. |
| ApexBio |
| Sensa Core Medical |
| Others |
Value Network & Pricing Analysis
Microfluidic cartridge miniaturization collapses the cost barrier between laboratory and point-of-care modalities, concentrating margin capture among three FDA-cleared platform manufacturers while forcing procurement committees toward unbundled consumable contracts. This technology transition simultaneously reduces per-test chemistry costs and elevates supply vulnerability for health systems locked into single-vendor analyzer placements.
Pricing Analysis
Bundled analyzer-consumable contracts dominate hospital procurement, though Texas and Florida health systems increasingly unbundle placements to enable competitive reagent bidding. Price differentiation rests on CLIA-waived certification tier and emergency department workflow integration depth. Cost compression in disposable cartridges intensifies as group purchasing organizations consolidate volume. Physician offices and urgent care clinics exhibit highest price sensitivity; academic medical centers prioritize analytical performance over unit economics.
Supply Chain Analysis
Electrochemical sensor engineering talent scarcity in Boston and San Diego constrains R&D expansion for mid-tier manufacturers seeking FDA 510(k) clearance. Manufacturing draws from precision instrument clusters in Germany, Japan, and the United States for analyzer assembly, while enzymatic reagent production sources from ISO 15189-accredited facilities in Europe and North America. Single-source vulnerability concentrates in cold-chain logistics for temperature-sensitive biosensors. Distribution runs through hospital group purchasing organizations and emergency medical services fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR technical documentation requirements create first-mover advantage for manufacturers achieving CE marking ahead of notified body capacity constraints, while US reimbursement density rewards FDA-cleared platforms with CLIA-waived classification.
For Market Incumbents: Extend platform architecture into continuous monitoring applications via subcutaneous microneedle biosensors before emerging entrants capture surgical intensive care unit pilots at Cleveland Clinic and Mayo Clinic. Consolidate consumable supply agreements through backward integration into enzyme reagent manufacturing, neutralizing cold-chain cost pressure from rural and tropical deployments. For New Entrants and Emerging Players: AI-enabled result interpretation software presents a technology-first wedge for intensive care unit integration without competing on analyzer hardware against Abbott and Nova Biomedical installed bases. Target home-based monitoring for sports performance and chronic heart failure segments with smartphone-integrated consumer devices. Pursue direct-to-consumer regulatory pathways bypassing hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among regional laboratory instrument fabricators with EU MDR technical documentation underway but pre-submission Q-Sub meetings pending with FDA. Long-term viability hinges on reimbursement strategy execution across CMS sepsis bundle mandates and joint commission quality metrics. Watch for CLIA-waived device validation guidance revisions as inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates CLIA-waived classification for point-of-care emergency department deployment. |
| CE Marking Pathway | Secures EU MDR market access ahead of notified body capacity constraints in Germany. |
| Hospital System Partnership | Locks in exclusive consumable contracts through integrated analyzer placement in Texas health systems. |
| Software Companion Development | Enables AI-enabled lactate trending alerts for intensive care unit hypoperfusion prediction. |
| Reimbursement Strategy | Aligns platform positioning with CMS sepsis bundle mandates tying payment to three-hour measurement windows. |
Research Methodology
Direct dialogue with emergency department clinicians, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) clearances, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body technical documentation. Bottom-up analyzer placement estimates triangulated against top-down sepsis protocol compliance requirements across the analysis window.
Bottom-up modeling segmented volume by product type, end user, technology, and application, with electrochemical sensor platform economics calibrated to CLIA-waived device pricing benchmarks. Top-down cross-checks validated against emergency department census data and ambulance fleet operator standardization trends. CAGRs derived from procurement cycle timing, regulatory pathway duration, and reimbursement policy stability assumptions.
The model holds under stable CMS sepsis bundle enforcement and FDA CLIA-waived validation criteria; deviation in reimbursement policy or analytical performance threshold tightening would shift volume trajectories. Forecasts reflect documented assumptions regarding regulatory timeline compression and health system capital allocation priorities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Global Red Biotechnology Market