
 Waldenstrom Macroglobulinemia Market | 2026-2036
Waldenstrom Macroglobulinemia Market Size, Share, and Industry Trends Forecast 2026-2036
Waldenstrom Macroglobulinemia Market Analytics
Buyer concentration across oncology treatment centers is restructuring how Waldenstrom macroglobulinemia therapies reach patients, with large hospital networks and specialty clinic chains gaining procurement leverage over dispersed community practices. AbbVie leverages its hematology portfolio depth to sustain formulary presence across major academic medical centers. BeiGene competes through geographic expansion of its BTK inhibitor franchise into European and Asia-Pacific markets. Johnson & Johnson anchors its position via long-standing relationships with hospital-based infusion centers.
Waldenstrom macroglobulinemia is a rare lymphoplasmacytic lymphoma characterized by bone marrow infiltration of IgM-secreting lymphoplasmacytoid cells, typically presenting with anemia, hepatosplenomegaly, and hyperviscosity syndrome requiring plasmapheresis intervention. The disease demands therapies that selectively deplete malignant clones while preserving immune function in elderly patient populations. Targeted therapy now leads treatment type segmentation as BTK and BCL-2 inhibitors displace conventional chemotherapy in frontline settings. Monoclonal antibodies within drug class segmentation occupy the deepest margin pools due to manufacturing complexity and premium positioning. Intravenous administration route maintains volume dominance though subcutaneous formulations are gaining share through home care and reduced infusion center burden.
FDA orphan drug designation and EMA PRIME eligibility compress regulatory review timelines for novel Waldenstrom macroglobulinemia therapies, while Health Canada and Japan's PMDA parallel track programs accelerate market access across North America and Asia. These frameworks shape manufacturer R&D prioritization by de-risking development investments in ultra-rare indications with limited commercial upside. Stakeholders must monitor evolving CMS and national payer evidence requirements for combination regimens, as value-based access agreements increasingly determine reimbursement for premium-priced hematology therapies.
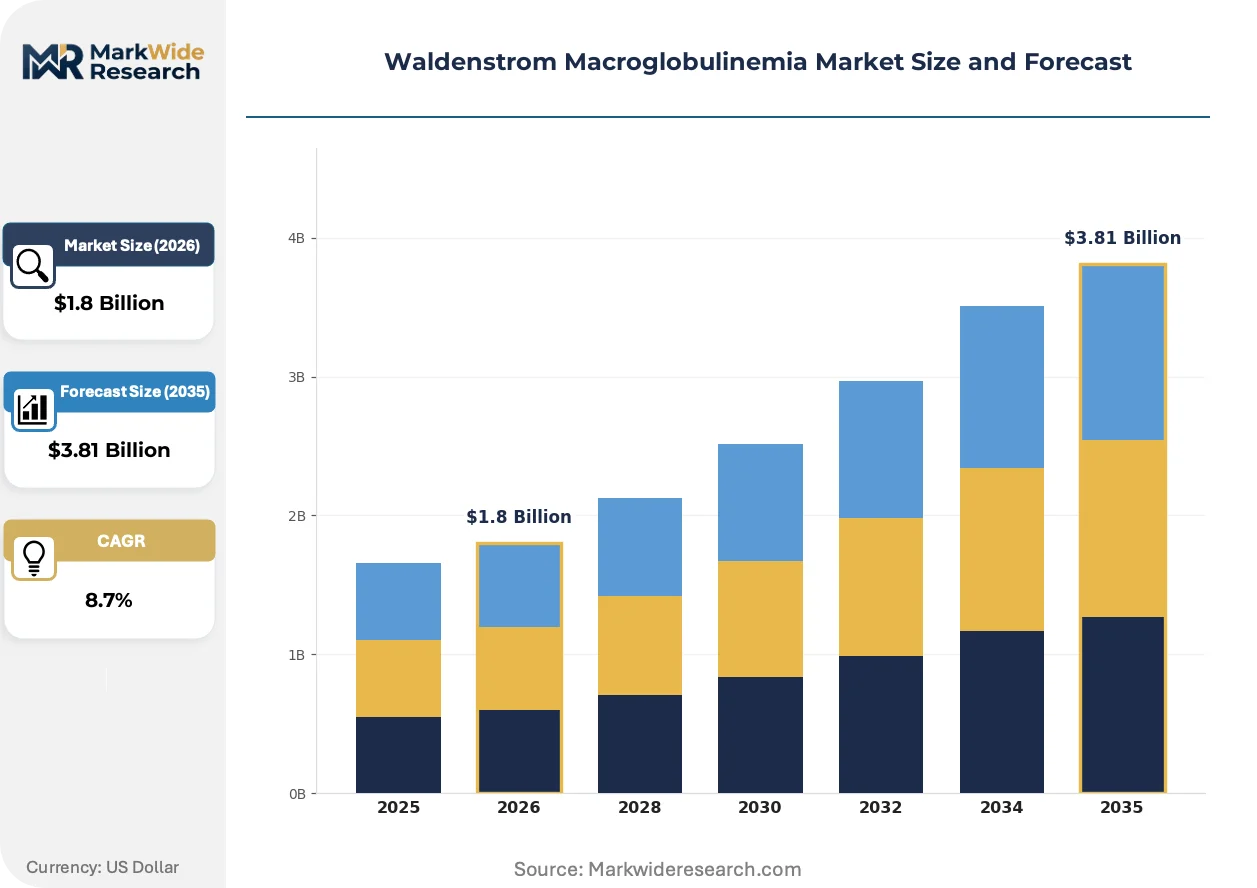
Market Dynamics
BTK inhibitor expansion is compressing treatment paradigms across Waldenstrom macroglobulinemia care, as oral targeted agents displace chemotherapy-dependent protocols and restructure infusion center economics.
Growth Catalysts
- FDA Accelerated Approval:Orphan oncology pathways compress Phase II-to-launch timelines, enabling earlier patient access for novel BTK and BCL-2 inhibitors.
- Subcutaneous Formulation Development:Reduced infusion burden expands home-based administration, broadening eligible patient pools beyond academic medical center catchments.
- Japan PMDA Sakigake Designation:Priority review for hematologic malignancies accelerates commercial entry for next-generation monoclonal antibodies in Asia-Pacific markets.
Market Restraints
- Plasma-Derived Input Volatility:Immunoglobulin supply constraints and fractionation capacity limitations create manufacturing bottlenecks for antibody-dependent combination regimens.
- Single-Source API Concentration:Active pharmaceutical ingredient production for BTK inhibitors concentrates among contract manufacturers in India and China, exposing supply continuity risks.
- Hyperviscosity Management Infrastructure:Plasmapheresis capability gaps in community oncology settings restrict frontline therapy initiation outside tertiary hematology networks.
Strategic Opportunities
- Germany Outpatient Reimbursement:Favorable AMNOG assessment pathways for orphan drugs enable premium pricing capture within statutory health insurance frameworks.
- Minimal Residual Disease Testing:ClonoSEQ and similar platforms create companion diagnostic adjacencies for therapy response monitoring and duration optimization.
- Telemedicine-Enabled Rural Access:Remote hematology consultation models penetrate underserved US markets, extending specialty clinic reach without physical infrastructure expansion.
Industry Challenges
- Hematopathology Subspecialty Scarcity:Diagnostic expertise concentration at academic centers delays accurate lymphoplasmacytic lymphoma classification in community settings.
- Combination Regimen Evidence Generation:Randomized trial design complexity for ultra-rare indications prolongs label expansion timelines and payer negotiation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waldenstrom Macroglobulinemia Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Immunotherapy, Chemotherapy, Targeted Therapy, Stem Cell Transplant Drug Class: Monoclonal Antibodies, Proteasome Inhibitors, CKD-516, Others Administration Route: Intravenous, Subcutaneous, Oral, Intrathecal End User: Hospitals, Specialty Clinics, Home Care, Research Institutes |
| Companies Covered | AbbVie, BeiGene, Amgen, Johnson & Johnson, TG Therapeutics, AstraZeneca, Novartis, Gilead Sciences, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waldenstrom Macroglobulinemia Market Evolving Landscape
Next-generation BTK inhibitors and bispecific antibody platforms are rewriting competitive benchmarks, while regulatory innovation incentives and patient-centric administration models reshape commercialization pathways.
Non-covalent BTK inhibitors are integrating into relapse protocols where covalent agent resistance mutations predominate. Academic medical centers in the United States and Germany are adopting these agents for MYD88-mutant disease subtypes. This technology is integrating treatment sequencing algorithms and compressing the relevance window for chemotherapy salvage options.
EMA PRIME eligibility for hematologic malignancies is streamrolling scientific advice and accelerated assessment timelines for combination therapy submissions. Manufacturers are restructuring European development programs to capture these procedural advantages. The regulatory pathway is compressing market access negotiations in France, Germany, and Italy where orphan drug status triggers distinct pricing frameworks.
Site-of-care migration is fragmenting historical infusion center concentration as subcutaneous formulations enable administration in hematology offices and home health settings. Specialty pharmacy networks are capturing dispensing volume previously held by hospital outpatient departments. This behavioral shift is most pronounced in United States markets where Medicare reimbursement differentials favor non-hospital administration for qualifying biologics.
Waldenstrom Macroglobulinemia Market Segmentation
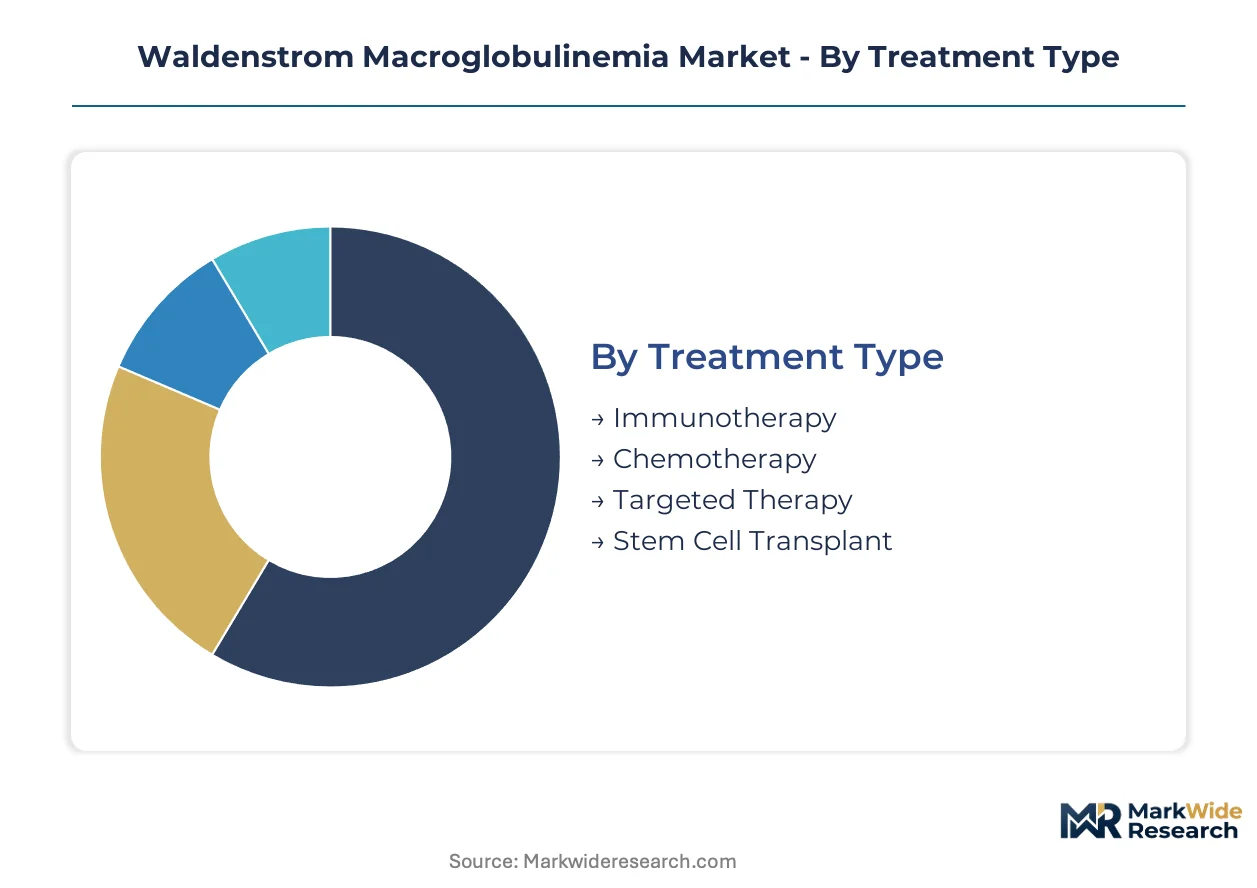
Waldenstrom macroglobulinemia treatment pathways fragment across therapeutic modalities, molecular targets, and care delivery settings. Segmentation reveals where pharmaceutical investment concentrates and how patient access patterns diverge by infrastructure availability.
Treatment Type:
Standardization dominates frontline protocols while customization intensifies in relapsed settings, with therapy selection increasingly guided by genomic stratification rather than age-adjusted algorithms alone.
- Targeted Therapy:BTK inhibitors and BCL-2 antagonists deliver oral, precision-directed malignant clone suppression with reduced immunosuppression versus legacy regimens. Academic medical centers in the United States and Germany prioritize these agents for MYD88-mutant subpopulations, though acquisition costs strain community oncology budgets.
- Immunotherapy:Anti-CD20 monoclonal antibodies deplete lymphoplasmacytoid cells through antibody-dependent cellular cytotoxicity, preserving stem cell reserves for eligible patients. Demand concentrates at tertiary hematology networks where infusion capacity and infectious disease support enable safe administration in elderly populations with baseline hypogammaglobulinemia.
- Chemotherapy:Bendamustine-based combinations retain utility in rapid disease control scenarios and resource-constrained settings where targeted agent access remains limited.
- Stem Cell Transplant:Autologous approaches apply to selected younger patients with chemosensitive relapse, requiring specialized cellular therapy infrastructure available at limited national referral centers.
Most installed capacity flows through Targeted Therapy. Expansion is steepest in Immunotherapy as next-generation monoclonal antibodies extend duration of response.
Drug Class:
Margin concentration tracks manufacturing complexity, with biologic production commanding premium positioning against small-molecule alternatives across reimbursement frameworks.
- Monoclonal Antibodies:Rituximab biosimilars and novel anti-CD20 constructs dominate volume through established hematology formularies, though cold agglutinin complications require pretreatment protocols. Japanese and German payers maintain favorable access pathways for these agents in lymphoplasmacytic lymphoma.
- Proteasome Inhibitors:Bortezomib and carfilzomib combinations achieve rapid IgM reduction in hyperviscosity emergencies, with peripheral neuropathy profiles limiting long-term exposure in frail patients. Community oncology adoption depends on infusion nursing support for subcutaneous administration.
- CKD-516:Investigational vascular disrupting agent advancing through orphan oncology pipelines with distinct mechanistic profile from established lymphoma therapeutics.
- Others:IMiD derivatives and alkylating agents occupy salvage niches where resistance mutations exclude standard-of-care options.
Commercial gravity centers on Monoclonal Antibodies. Pipeline activity concentrates in Proteasome Inhibitors for combination regimens.
Administration Route:
Patient convenience and site-of-care economics drive formulation innovation, with subcutaneous and oral alternatives displacing historical intravenous dependence in eligible populations.
- Intravenous:Maintains dominance for monoclonal antibodies and proteasome inhibitors requiring controlled infusion monitoring, particularly in first-dose settings where hypersensitivity protocols apply. Hospital outpatient departments capture reimbursement premiums for these administrations under Medicare payment structures.
- Subcutaneous:Rituximab and daratumumab subcutaneous formulations reduce chair time from hours to minutes, enabling hematology office administration without full infusion center infrastructure. Germany's outpatient reimbursement framework accelerates adoption in statutory health insurance populations.
- Oral:BTK inhibitor tablets eliminate facility-based administration entirely, supporting rural patient access through telemedicine monitoring models in United States markets.
- Intrathecal:Reserved for rare central nervous system involvement scenarios requiring direct cerebrospinal fluid drug delivery at specialized neuro-oncology centers.
Volume leadership remains with Intravenous administration. Patient preference and total cost reduction are accelerating Subcutaneous uptake fastest.
End User:
Care delivery stratification reflects disease rarity and complication management requirements, with site-of-care migration reshaping historical hospital-centric patterns.
- Specialty Clinics:Hematology-focused ambulatory centers concentrate diagnostic expertise and clinical trial access for lymphoplasmacytic lymphoma subtyping. United States metropolitan markets show pronounced consolidation into multi-site specialty groups with pharmacy dispensing integration.
- Hospitals:Tertiary academic centers retain complex case referrals requiring plasmapheresis, cellular therapy, or intensive supportive care during induction. Japanese designated cancer hospitals anchor national treatment networks through government credentialing systems.
- Home Care:Subcutaneous biologic administration and oral targeted therapy enable qualified patients to receive treatment outside facility settings, reducing transportation burden for elderly populations with mobility limitations.
- Research Institutes:National cancer centers and cooperative group institutions generate evidence for novel combination regimens and minimal residual disease-guided therapy duration.
Treatment initiation concentrates at Hospitals. Patient volume migration is most pronounced toward Specialty Clinics as oral and subcutaneous options expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hematopathology fellowship programs in the United States, Germany, and Japan anchor geographic demand concentration for Waldenstrom macroglobulinemia therapeutics. These specialist concentrations align with tertiary care infrastructure capable of managing complex lymphoplasmacytic lymphoma presentations.
United States
Academic medical centers in Boston and Houston drive protocol development for BTK inhibitor sequencing. FDA accelerated approval pathways compress orphan oncology timelines from Phase II to commercial launch. The Mayo Clinic Rochester anchors a regional referral network spanning the Upper Midwest for plasmapheresis-dependent hyperviscosity cases.
Germany
Statutory health insurance frameworks through G-BA enable premium pricing capture for orphan hematology indications. EMA PRIME eligibility streamlines scientific advice for combination therapy submissions. Heidelberg and Essen university hospitals concentrate minimal residual disease testing infrastructure for therapy response monitoring.
Japan
Designated cancer hospital credentialing systems channel lymphoplasmacytic lymphoma cases through government-accredited networks. PMDA Sakigake designation accelerates priority review for next-generation monoclonal antibodies. Tokyo and Osaka metropolitan clusters host the majority of cellular therapy infrastructure for eligible transplant candidates.
United Kingdom
NHS England specialized commissioning frameworks concentrate rare hematology treatment at designated tertiary centers. NICE technology appraisals determine access thresholds for premium-priced biologics in lymphoplasmacytic lymphoma. The Royal Marsden and University College London anchor London's concentration of clinical trial enrollment.
Waldenstrom Macroglobulinemia Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Waldenstrom macroglobulinemia therapeutic landscape. The vendor base organizes into three tiers: multinational pharmaceutical conglomerates with hematology portfolio breadth, mid-cap biotech firms with single-franchise dependence, and emerging biopharmaceutical developers with orphan oncology specialization. Strategic archetypes include BTK inhibitor platform builders, monoclonal antibody franchise holders, and combination regimen architects. Dominant competitive moves center on geographic expansion of approved indications and subcutaneous formulation development to capture site-of-care migration.
Among diversified pharmaceutical conglomerates, AbbVie and Johnson & Johnson occupy positions anchored by hematology portfolio depth and hospital-based infusion center relationships. BeiGene represents the geographic expansion archetype, with its BTK inhibitor franchise extending into European and Asia-Pacific markets. These three companies exemplify how regulatory pathway expertise and site-of-care economics reshape competitive positioning in ultra-rare oncology indications.
| Leading Market Players |
|---|
| AbbVie |
| BeiGene |
| Amgen |
| Johnson & Johnson |
| TG Therapeutics |
| AstraZeneca |
| Novartis |
| Gilead Sciences |
| Merck & Co. |
| Others |
Value Network & Pricing Analysis
EMA PRIME eligibility for orphan hematology indications gates qualified supply access and premium-tier pricing capture for Waldenstrom macroglobulinemia therapies, as manufacturers without accelerated assessment pathways face compressed reimbursement negotiations in statutory health insurance frameworks.
Pricing Analysis
Bundled infusion center services versus unbundled drug-only procurement splits pricing models across administration settings. Three-tier pricing structure across premium, standard, and economy levels tracks BTK inhibitor novelty, biosimilar monoclonal antibody availability, and generic chemotherapy access. Pricing pressure stems from AMNOG assessments in Germany and NICE technology appraisals in the United Kingdom demanding outcome evidence for premium positioning. Community oncology practices exhibit highest price sensitivity due to acquisition cost constraints, while academic medical centers with pharmacy dispensing integration capture margin from specialty clinic consolidation.
Supply Chain Analysis
FDA and EMA certification requirements gate active pharmaceutical ingredient supply for BTK inhibitors and monoclonal antibodies, with qualified manufacturing capacity concentrating in India, China, and Switzerland for small-molecule production. Plasma-derived immunoglobulin inputs and recombinant bioreactor capacity feed antibody-dependent combination regimens. Single-source contract manufacturer concentration in Asian markets creates tariff exposure and regulatory inspection vulnerability. Distribution runs through hospital outpatient departments, specialty pharmacy networks, and direct-to-clinic channels depending on formulation and reimbursement structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waldenstrom macroglobulinemia therapeutics offer margin expansion through subcutaneous formulation shifts that reduce infusion center overhead and extend patient reach beyond tertiary catchments.
For Market Incumbents: To counter biosimilar rituximab erosion and next-generation BTK inhibitor competition, AbbVie and Johnson & Johnson should deepen captive supply of plasma-derived inputs through backward integration into fractionation capacity, while BeiGene expands European manufacturing footprint to reduce API transit exposure and capture EMA PRIME procedural advantages for combination submissions. For New Entrants and Emerging Players: Begin with oral formulation development for rural United States markets where telemedicine monitoring models bypass infusion center infrastructure requirements, then layer subcutaneous biologic capabilities to penetrate German outpatient reimbursement frameworks where statutory health insurance favors home administration economics. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap biotech specialists with single-franchise BTK inhibitor dependence because FDA accelerated approval pathways de-risk development timelines and compress market access windows for orphan oncology assets. Platform consolidation around hematology portfolio depth offers five-to-ten-year viability as site-of-care migration fragments historical hospital-centric dispensing. Watch for EMA PRIME eligibility announcements as inflection indicators for European pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Rituximab and daratumumab subcutaneous variants reduce chair time and enable hematology office administration outside hospital outpatient departments. |
| EMA PRIME Pathway Structuring | Scientific advice and accelerated assessment eligibility compress market access negotiations in France, Germany, and Italy orphan drug frameworks. |
| Plasma-Derived Input Integration | Captive fractionation capacity mitigates immunoglobulin supply volatility for antibody-dependent combination regimens in hyperviscosity management. |
| Telemedicine-Enabled Rural Access | Remote hematology consultation models extend specialty clinic reach without physical infrastructure expansion in underserved United States markets. |
| Minimal Residual Disease Companion Diagnostic | ClonoSEQ platform integration creates therapy response monitoring adjacencies for duration optimization and payer evidence generation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling and top-down revenue triangulation anchored market size estimates.
Segment-weighting approaches distributed volume and value across treatment type, drug class, administration route, and end-user setting dimensions throughout the forecast period. CAGRs derived from therapy uptake curves, pricing trajectory assumptions, and geographic expansion patterns for approved indications. Forecast inputs incorporated BTK inhibitor sequencing algorithms, subcutaneous formulation launch timelines, and orphan drug exclusivity expiration schedules.
Several conditions sit outside the modeled scope, including pipeline discontinuations, manufacturing inspection delays, and reimbursement policy reversals. Forecasts reflect documented assumptions about regulatory pathway efficiency and payer evidence requirements. A model refresh is warranted upon material change in FDA accelerated approval criteria or EMA PRIME eligibility standards for hematologic malignancies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
Cell Surface Markers Market