
 Global DNA Vaccines Market | 2026-2036
Global DNA Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global DNA Vaccines Market Foresight
Multi-source clinical manufacturing partnerships is recalibrating how developers secure plasmid supply chains across Phase II and III programs. Inovio Pharmaceuticals leverages captive electroporation device production to control delivery-system margins. Merck anchors large-scale viral vector capacity while competing with emerging DNA platform specialists. Pfizer sustains global distribution infrastructure that extends reach into government procurement channels.
DNA vaccines are biopharmaceutical formulations comprising bacterial plasmids encoding target antigens under eukaryotic promoter control, manufactured through fed-batch E. coli fermentation followed by alkaline lysis purification. They stimulate cellular and humoral immunity without cold-chain dependency, positioning them for tropical and remote deployment. Plasmid DNA retains the largest development pipeline among vaccine type segments, while electroporation delivery commands premium pricing due to enhanced transfection efficiency. Oncology as a target disease category attracts the fastest-growing investigator-initiated trial volume, though infectious diseases still dominate government institute procurement.
The FDA's guidance on nucleic acid vaccine chemistry, manufacturing, and controls shapes investigational new drug submission requirements for U.S. developers, while the EMA's Committee for Medicinal Products for Human Use defines comparable standards across European Union member states. WHO prequalification pathways influence procurement decisions by government institutes in low- and middle-income countries. Stakeholders must monitor how the EU AI Act and FDA's evolving computational modeling expectations intersect with DNA sequence design and immunogenicity prediction workflows.
Market Dynamics
Electroporation delivery patents filed through the USPTO and EPO are concentrating competitive access around device-integrated platform developers, forcing late entrants into licensing negotiations or alternative delivery R&D.
Growth Catalysts
- EMA Committee for Medicinal Products for Human Use guidance:Clarity on nucleic acid chemistry, manufacturing, and controls accelerates investigational new drug submissions across European Union member states.
- Oncology immuno-oncology protocols:Hospital integration of plasmid DNA platforms into cellular therapy workflows expands addressable patient populations beyond infectious disease applications.
- South Korea clinical trial density:Government institute funding for infectious disease candidates creates concentrated demand for Phase II and III manufacturing partnerships.
Market Restraints
- Plasmid supply concentration:Fed-batch E. coli fermentation capacity concentrates among contract manufacturers in Germany and the United States, creating bottleneck risk for multi-source programs.
- Cold-chain substitution economics:mRNA platforms with established distribution infrastructure compete for government procurement contracts in tropical deployment scenarios.
- FDA computational modeling expectations:Evolving requirements for immunogenicity prediction workflows extend pre-submission timelines for sequence-optimized candidates.
Strategic Opportunities
- Brazil ANVISA regulatory pathway development:Prequalification alignment with WHO standards opens government institute procurement in Latin America's largest vaccine market.
- Electroporation-needle hybrid devices:Convergence of dermal delivery technologies with portable power systems enables point-of-care administration in remote geographies.
- India CDSCO fast-track designations:Priority review incentives for endemic disease targets accelerate market access for region-specific infectious disease candidates.
Industry Challenges
- Alkaline lysis purification scale-up:Supercoiled plasmid yield consistency across 10,000-liter fermentation runs requires specialized process analytical technology expertise that outstrips current talent pools.
- EU AI Act intersection:Computational sequence design tools face classification scrutiny, forcing revalidation of machine learning models used for codon optimization and epitope prediction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DNA Vaccines Market |
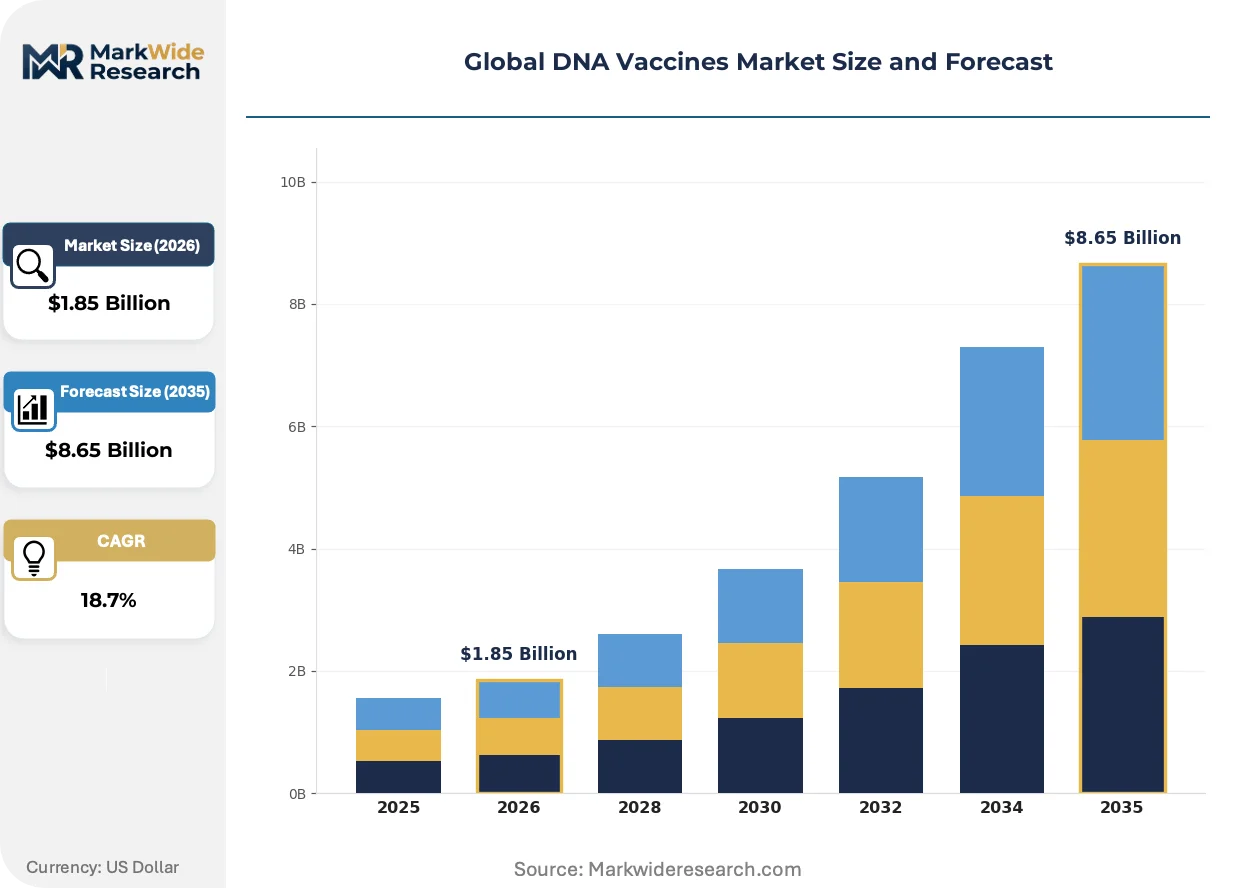
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Plasmid DNA, RNA-Based, Viral Vector, Peptide-Based, Subunit, Others Delivery Method: Intramuscular Injection, Electroporation, Needle-Free Injection, Gene Gun, Intradermal Injection, Sublingual Target Disease: Infectious Diseases, Oncology, Autoimmune Disorders, Allergies, Genetic Disorders, Neurological Conditions End User: Research Laboratories, Biotechnology Firms, Government Institutes, Academic Institutions, Contract Manufacturing Organizations, Private Clinics |
| Companies Covered | Inovio Pharmaceuticals, GeneOne Life Science, Genexine, Zydus Cadila, Merck, Pfizer, Sanofi, AstraZeneca, GSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DNA Vaccines Market Shifts & Advancements
Platform standardization around electroporation-compatible formulations is compressing development timelines while fragmenting delivery technology ownership. Developers now face strategic choices between captive device production and open-platform licensing.
Needle-free electroporation devices are decentralizing vaccine administration from centralized cold-chain hubs to regional clinics and field deployment settings. Military medical services and rural health networks in tropical geographies are piloting portable units. This shift is compressing the traditional three-tier distribution hierarchy into direct-to-site delivery models.
The FDA's evolving guidance on nucleic acid vaccine chemistry, manufacturing, and controls is tightening documentation requirements for plasmid host cell characterization. Sponsors must now submit extended stability data and raw material qualification protocols. United States-based developers are responding by embedding quality-by-design frameworks earlier in candidate selection.
Hospital procurement of oncology DNA vaccines is fragmenting across investigator-initiated trial sponsors and commercial sponsors, unbundling traditional centralized purchasing. Academic medical centers in Germany and South Korea are establishing direct manufacturing partnerships. This pattern is most visible in immuno-oncology protocols where personalized neoantigen programs require rapid turnaround from sequence to clinic.
Global DNA Vaccines Market Segmentation
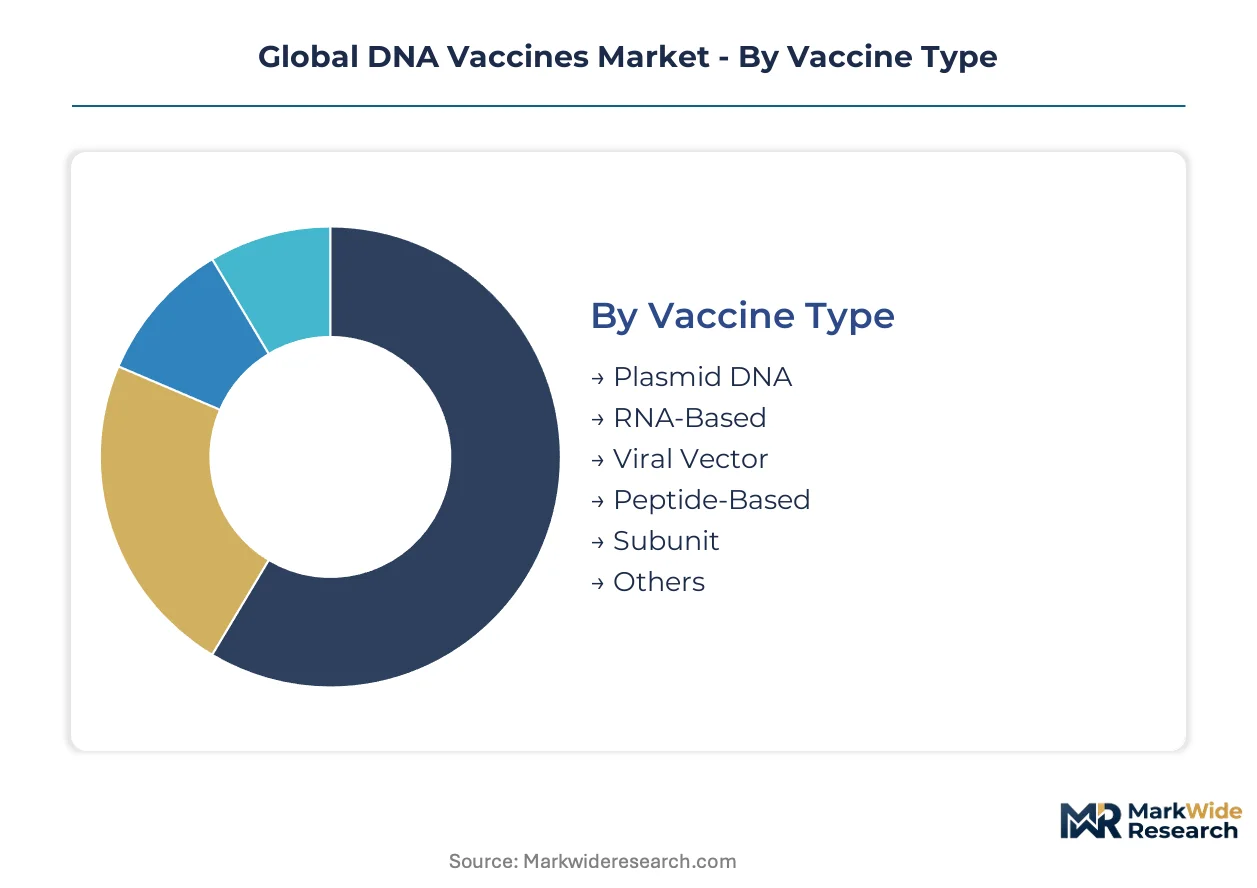
DNA vaccine segmentation reveals how regulatory pathways, manufacturing complexity, and clinical application shape commercial viability across distinct technology platforms. Developers must align segment selection with available CMC expertise and target market reimbursement structures.
Vaccine Type:
FDA nucleic acid CMC guidance applies differential stringency across platforms, with plasmid DNA facing the most mature regulatory precedent while RNA-based candidates navigate evolving stability requirements.
- Plasmid DNA:Bacterial plasmids encoding target antigens under eukaryotic promoter control, manufactured through fed-batch E. coli fermentation. Demand concentrates in United States and German hospital procurement channels for immuno-oncology protocols, driven by established alkaline lysis purification infrastructure and WHO prequalification alignment for tropical deployment scenarios.
- RNA-Based:Synthetic or in vitro transcribed mRNA formulations requiring modified nucleoside chemistry and lipid nanoparticle encapsulation. South Korean government institutes and United States biotechnology firms dominate clinical trial sponsorship, constrained by cold-chain dependency that limits remote geography access despite superior transfection kinetics.
- Viral Vector:Replication-deficient adenovirus or lentivirus platforms delivering transgenes via host cell infection machinery.
- Peptide-Based:Synthetic immunogenic epitopes combined with adjuvant systems for targeted T-cell activation.
- Subunit:Purified recombinant proteins administered with immunostimulatory adjuvants.
- Others:Emerging platforms including DNA-launched viral replicons and self-amplifying RNA constructs.
Plasmid DNA sits at the top of the volume ranking, with RNA-Based climbing the fastest.
Delivery Method:
Cost tier differentiation separates premium electroporation systems from standard injection platforms, with device-integrated approaches commanding procurement budgets three to five times higher per dose administered.
- Electroporation:Electrical pulse-mediated membrane permeabilization enhancing plasmid transfection efficiency tenfold over passive injection. German and United States patent filings through USPTO and EPO concentrate competitive access, with Inovio Pharmaceuticals leveraging captive device production to control margins in oncology applications.
- Intramuscular Injection:Standard needle-based administration into skeletal muscle tissue using standard syringes and adjuvant formulations. Government institutes in Brazil and India favor this approach for infectious disease campaigns, prioritizing cost minimization over immunogenicity optimization in resource-constrained procurement environments.
- Needle-Free Injection:High-pressure liquid or powder jet systems penetrating dermal and muscle tissue without metallic needles.
- Gene Gun:Helium-driven biolistic delivery of DNA-coated gold microparticles into epidermal cells.
- Intradermal Injection:Shallow dermal layer targeting exploiting dense antigen-presenting cell populations.
- Sublingual:Mucosal membrane absorption bypassing gastrointestinal degradation for systemic immune response.
Intramuscular Injection retains the largest installed base, though electroporation gains share fastest in premium oncology segments.
Target Disease:
Application maturity varies sharply, with infectious disease candidates occupying the deepest clinical pipeline while oncology attracts investigator-initiated trial volume expansion.
- Infectious Diseases:Prophylactic candidates targeting HIV, malaria, tuberculosis, and emerging viral pathogens through conserved antigen targeting. WHO prequalification pathways drive procurement decisions by government institutes in low- and middle-income countries, with South Korean funding agencies supporting Phase II and III manufacturing partnerships.
- Oncology:Therapeutic vaccines against tumor-associated antigens or patient-specific neoantigens integrated into cellular therapy workflows. Academic medical centers in Germany establish direct manufacturing partnerships for personalized programs, requiring rapid turnaround from sequence identification to clinical administration.
- Autoimmune Disorders:Tolerance-inducing formulations suppressing pathogenic immune responses against self-antigens.
- Allergies:Desensitization protocols redirecting Th2-dominated responses toward Th1 immunity.
- Genetic Disorders:In vivo gene supplementation for monogenic disease correction.
- Neurological Conditions:CNS-targeted immunomodulation for neurodegenerative or neuroinflammatory indications.
Infectious Diseases commands the deepest development pipeline, with Oncology expanding most quickly across immuno-oncology integration.
End User:
Customer type determines procurement scale and regulatory burden, with government institutes managing largest-volume tenders while research laboratories drive early-stage innovation.
- Government Institutes:National health ministries and supranational procurement bodies managing population-scale immunization programs. Brazil ANVISA regulatory pathway development and India CDSCO fast-track designations shape access priorities, with tenders favoring candidates demonstrating stability outside cold-chain infrastructure.
- Biotechnology Firms:Platform-integrated developers combining proprietary delivery technologies with candidate pipelines. These entities concentrate in United States and South Korean clusters, securing multi-source clinical manufacturing partnerships across Phase II and III programs.
- Research Laboratories:Academic and institutional investigators conducting preclinical and early-phase clinical evaluation.
- Academic Institutions:University-affiliated medical centers managing investigator-initiated trials.
- Contract Manufacturing Organizations:Specialized plasmid production facilities offering fed-batch E. coli fermentation and alkaline lysis purification services.
- Private Clinics:Specialized treatment centers administering personalized or premium therapeutic vaccines.
Government Institutes represent the highest-volume procurement segment, with biotechnology firms showing the steepest expansion trajectory in platform integration investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Diego biotechnology corridor anchors clinical trial density for DNA vaccine candidates, with electroporation device manufacturing and plasmid supply chains concentrating across three continents. Regulatory pathway maturity varies sharply by jurisdiction, shaping where developers file investigational new drug applications first.
United States
FDA nucleic acid CMC guidance drives submission timelines for plasmid-based candidates, with the agency's evolving computational modeling expectations extending pre-submission documentation. The National Institutes of Health funds infectious disease trials through its Vaccine Research Center. Boston and San Francisco Bay Area clusters host the deepest concentration of Phase II and III manufacturing partnerships.
Germany
EMA Committee for Medicinal Products for Human Use standards accelerate investigational new drug submissions across EU member states, with alkaline lysis purification capacity concentrating in Baden-Württemberg and Bavaria. The Paul-Ehrlich-Institute oversees nucleic acid vaccine quality oversight. Heidelberg and Munich academic medical centers establish direct manufacturing partnerships for personalized neoantigen programs.
South Korea
MFDS fast-track designations for endemic disease targets compress regulatory review timelines, with government institute funding driving Phase II and III trial density for infectious disease candidates. The Korea Drug Development Fund supports domestic platform developers. Seoul and Songdo bioclusters integrate electroporation device production with captive plasmid fermentation capacity.
Brazil
ANVISA regulatory pathway development aligned with WHO prequalification standards opens government institute procurement for tropical deployment scenarios. The Oswaldo Cruz Foundation manages national immunization program tenders favoring stability outside cold-chain infrastructure. São Paulo and Rio de Janeiro host emerging contract manufacturing partnerships for fed-batch E. coli fermentation.
India
CDSCO priority review incentives for endemic disease targets accelerate market access, with plasmid supply chain partnerships expanding across Phase II and III programs. The Department of Biotechnology funds infectious disease candidate development through its National Biopharma Mission. Hyderabad and Bengaluru clusters concentrate multi-source clinical manufacturing capacity for export markets.
Global DNA Vaccines Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue device-integrated platform specialization. The competitive structure fragments across captive electroporation manufacturers, large-scale viral vector anchors, and contract plasmid specialists. Three archetypes dominate: platform-integrated developers controlling delivery-system margins, diversified pharmaceutical incumbents leveraging global distribution infrastructure, and pure-play DNA specialists securing manufacturing partnerships. Competitive moves concentrate on strategic licensing for patent-protected electroporation access and backward integration into alkaline lysis purification capacity.
Among platform-integrated specialists, Inovio Pharmaceuticals exemplifies captive device production strategies, while GeneOne Life Science and Genexine occupy positions within the Asian contract development ecosystem. These entities represent varying approaches to securing electroporation delivery access—through proprietary hardware development, regional partnership networks, or hybrid licensing arrangements—without converging on a single dominant commercial model.
| Leading Market Players |
|---|
| Inovio Pharmaceuticals |
| GeneOne Life Science |
| Genexine |
| Zydus Cadila |
| Merck |
| Pfizer |
| Sanofi |
| AstraZeneca |
| GSK |
| Others |
Supply & Pricing Matrix
Government institute procurement programs in Brazil and India anchor the dominant pricing model, with tender structures favoring stability-optimized plasmid DNA candidates over cold-chain-dependent alternatives. This buyer concentration compresses margins for standard intramuscular formulations while preserving premium capture for electroporation-integrated oncology platforms.
Pricing Analysis
Input-cost pass-through from E. coli fermentation substrates and purification resins shapes contract manufacturing quotations, with three-tier pricing structure across premium, standard, and economy levels separating electroporation-device bundles from bare plasmid supply. Price differentiation hinges on supercoiled plasmid purity grades and WHO prequalification status. Cost compression in economy-tier infectious disease tenders is intensifying because mRNA platforms compete for tropical deployment contracts. Government institutes in South Korea and Brazil exhibit highest price sensitivity, while German academic medical centers accept premium pricing for personalized neoantigen programs.
Supply Chain Analysis
Dual-sourcing requirements from Phase II and III sponsors mandate multi-supplier qualification across German and United States contract manufacturers, with South Korean bioclusters emerging as tertiary options. Raw material dependencies center on pharmaceutical-grade E. coli host strains, alkaline lysis reagents, and electroporation device electronics. Supply chain risk concentrates in single-source vulnerability for supercoiled plasmid analytical technology expertise. Distribution runs through centralized cold-chain hubs for standard formulations, shifting to direct-to-site models for portable electroporation deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DNA vaccines market functions as a stable compounder, with platform standardization around electroporation-compatible formulations driving steady pipeline expansion and manufacturing partnership renewals.
For Market Incumbents: To counter emerging mRNA platform substitution in infectious disease procurement, deepen captive electroporation device production and secure backward integration into alkaline lysis purification capacity. Anchor manufacturing partnerships in Baden-Württemberg and Bavaria to exploit EMA-aligned regulatory precedent. For New Entrants and Emerging Players: Electroporation-needle hybrid device innovation offers the most penetrable wedge, targeting Brazil ANVISA prequalification pathways and India CDSCO fast-track designations for endemic disease candidates. Prioritize government institute tender participation over hospital direct sales to build volume credibility. For Investors and Strategic Acquirers: Platform-integrated biotechnology firms with captive device production are the most active acquirer in this space, consolidating alkaline lysis purification specialists to secure CMC expertise. The signal to watch is MFDS fast-track designation velocity for infectious disease candidates, indicating regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Electroporation Device Captive Production | Inovio Pharmaceuticals controls delivery-system margins through in-house hardware manufacturing. |
| Alkaline Lysis Purification Scale-Up | Specialized process analytical technology expertise concentrates among German contract manufacturers. |
| Multi-Source Clinical Manufacturing Partnerships | Phase II and III sponsors secure plasmid supply chain redundancy across three continents. |
| EMA Committee for Medicinal Products for Human Use Alignment | Clarity on nucleic acid CMC accelerates investigational new drug submissions across EU member states. |
| WHO Prequalification Pathway Navigation | Government institutes in low- and middle-income countries prioritize stability-optimized candidates. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and contract manufacturing officers informed demand-side assumptions. Secondary sources include FDA nucleic acid CMC guidance documents, EMA Committee for Medicinal Products for Human Use standards, ClinicalTrials.gov protocol registries, and WHO prequalification pathway documentation. Bottom-up and top-down triangulation anchored volume and value estimates.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. Segmentation dimensions modeled include vaccine type, delivery method, target disease, and end user, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from pipeline-stage probability-weighted revenue forecasts, incorporating electroporation device penetration curves and plasmid manufacturing capacity expansion timelines.
The model holds under stable FDA and EMA regulatory precedent; deviation in EU AI Act enforcement stringency or MFDS fast-track designation criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Human Placental Protein Market