
 Mitochondrial Myopathies Market | 2026-2036
Mitochondrial Myopathies Market Size, Share, and Industry Trends Forecast 2026-2036
Mitochondrial Myopathies Market Outlook
Buyer concentration among hospital networks is recalibrating procurement leverage for mitochondrial myopathy therapies. Stealth BioTherapeutics anchors its position through R&D intensity in mitochondrial-targeted drug platforms. PTC Therapeutics competes via geographic dominance in European rare disease markets. Khondrion specializes in small-molecule mitochondrial modulators for genetic subtypes.
Mitochondrial myopathies constitute a heterogeneous group of disorders arising from mitochondrial DNA or nuclear DNA mutations impairing oxidative phosphorylation, with phenotypic severity correlating to heteroplasmy levels and tissue-specific energy demands. These conditions primarily burden neuromuscular function, cardiac output, and metabolic homeostasis, driving sustained clinical intervention across multiple organ systems. The therapeutics segment captures the dominant margin pool given orphan pricing dynamics and chronic administration requirements, while diagnostic kits represent the fastest-growing category as genetic testing panels expand mutation coverage. Hospitals constitute the primary end user channel, though homecare settings are gaining traction for long-term supportive care administration.
The FDA's Orphan Drug Designation and EMA's Committee for Orphan Medicinal Products shape trial incentives and market exclusivity frameworks for developers. REACH compliance and EMA's MDR requirements govern diagnostic kit material standards and clinical evidence thresholds across European markets. Stakeholders must monitor evolving reimbursement pathways for gene-targeted therapies as health technology assessments tighten evidentiary demands for ultra-rare indications.
Market Dynamics
Hospital network consolidation across the United States, Germany, and Japan is compressing procurement timelines and amplifying price negotiation leverage for mitochondrial myopathy therapies. Specialized neuromuscular centers now coordinate formulary decisions through centralized rare disease purchasing coalitions.
Growth Catalysts
- FDA Orphan Drug Designation:The program accelerates clinical trial timelines and extends market exclusivity periods for mitochondrial-targeted drug developers, reducing regulatory friction for novel therapeutic platforms.
- Genetic testing panel expansion:Diagnostic laboratories are broadening mutation coverage for mitochondrial DNA and nuclear DNA variants, enabling earlier patient identification and intervention initiation.
- Specialized neuromuscular center clustering:Concentrated expertise in the United States, Germany, and Japan generates referral network effects that streamline patient access to investigational therapies.
Market Restraints
- Ultra-small patient populations:Heterogeneous genetic subtypes fragment addressable markets, forcing developers to amortize R&D costs across limited treatment-eligible cohorts.
- Heteroplasmy measurement variability:Tissue-specific mutation load assessment lacks standardized protocols, complicating clinical trial endpoint design and regulatory evidence packages.
- Chronic administration cost burden:Lifelong therapy requirements strain payer budgets, triggering prior authorization restrictions and step-therapy mandates from national health technology assessment bodies.
Strategic Opportunities
- Homecare administration models:Long-term supportive care delivery is migrating from hospital infusion centers to home-based settings, opening channel expansion for drug-device combination products.
- EMA MDR diagnostic kit pathway:In vitro device regulation harmonization across European member states streamlines market access for companion diagnostic developers targeting mitochondrial mutation panels.
- Gene therapy convergence:Viral vector delivery platforms are merging with mitochondrial genome editing tools, creating first-in-class curative modality candidates for heteroplasmic disorders.
Industry Challenges
- Specialized genetic counselor scarcity:Interpretation of complex heteroplasmy patterns and variant pathogenicity ratings requires rare expertise that outpaces training program output.
- Multi-organ endpoint harmonization:Cardiac, neuromuscular, and metabolic outcome measure integration across regulatory submissions demands unprecedented cross-functional clinical operations coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitochondrial Myopathies Market |
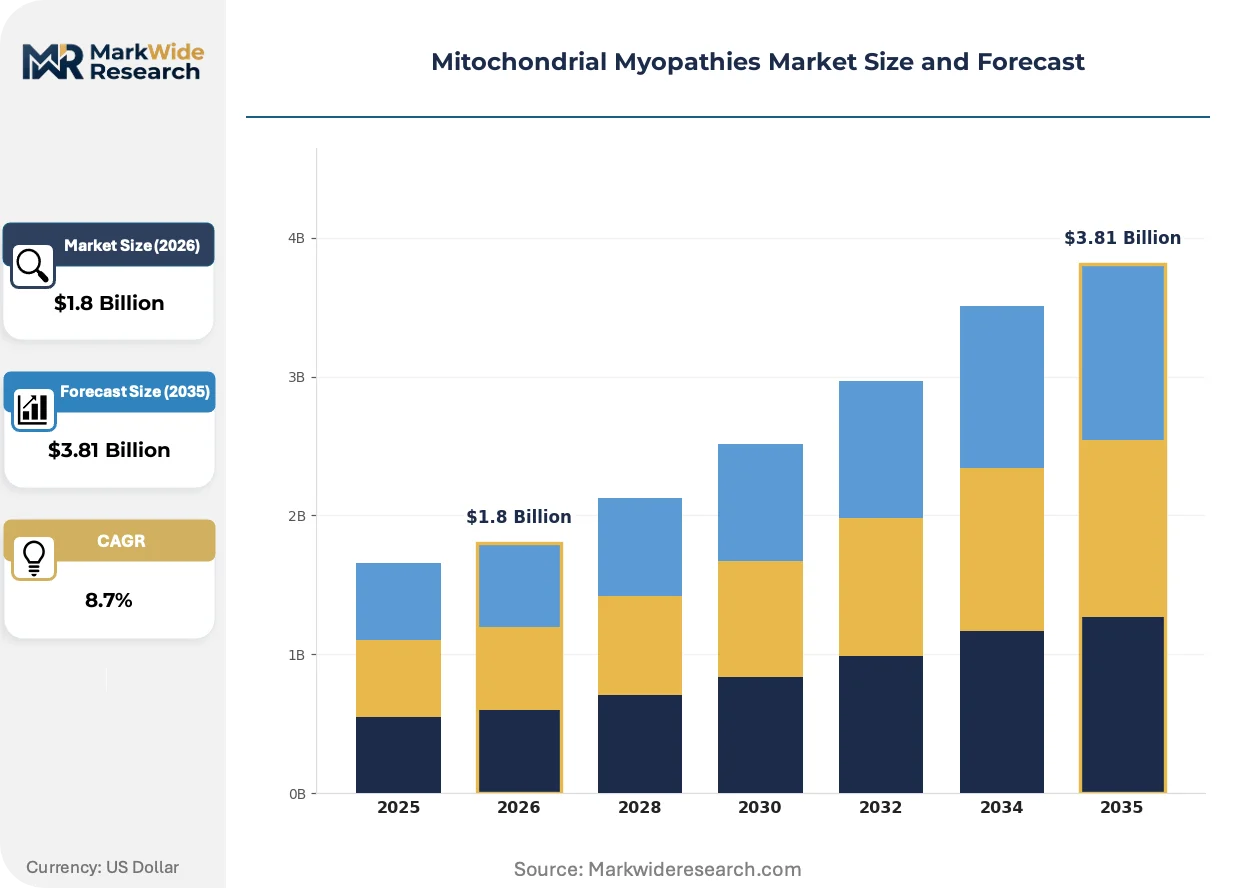
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Therapeutics, Supportive Care Products, Nutritional Supplements End User: Hospitals, Clinics, Rehabilitation Centers, Homecare Settings Therapy Area: Neuromuscular Disorders, Genetic Disorders, Metabolic Disorders, Rare Diseases Delivery Mode: Oral, Intravenous, Intramuscular, Topical |
| Companies Covered | PTC Therapeutics, Tisento Therapeutics, Stealth BioTherapeutics, Thiogenesis Therapeutics, Cyclerion Therapeutics, UCB, Pharming Technologies, Saol Therapeutics, Khondrion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitochondrial Myopathies Market Strategic Shifts
Biomarker-guided patient stratification is displacing empirical prescribing in mitochondrial myopathy management, while digital health infrastructure enables remote monitoring of multi-organ disease progression.
Next-generation sequencing platforms are integrating mitochondrial genome analysis with nuclear exome profiling in unified diagnostic workflows. Academic medical centers in Boston and Munich are deploying these combined panels for simultaneous heteroplasmy quantification and modifier gene identification. The technology is integrating previously siloed genetic testing pathways into single-sample protocols that compress diagnostic odyssey duration from years to weeks.
REACH compliance requirements for diagnostic kit materials are tightening evidentiary thresholds for clinical chemistry reagents used in mitochondrial enzyme activity assays. ECHA substance of very high concern listings now capture specific buffer components common to oxidative phosphorylation test kits. European IVD manufacturers are reformulating reagent compositions and resubmitting technical documentation to notified bodies under MDR Article 56.
Specialized neuromuscular centers are consolidating formulary decision authority through rare disease purchasing cooperatives that bypass traditional distributor relationships. Hospital networks in the United States and Germany are establishing direct contracting channels with mitochondrial therapy developers, displacing wholesale intermediaries. This concentration is most visible in pediatric metabolic centers where patient volume justifies dedicated supply chain infrastructure.
Mitochondrial Myopathies Market Segmentation
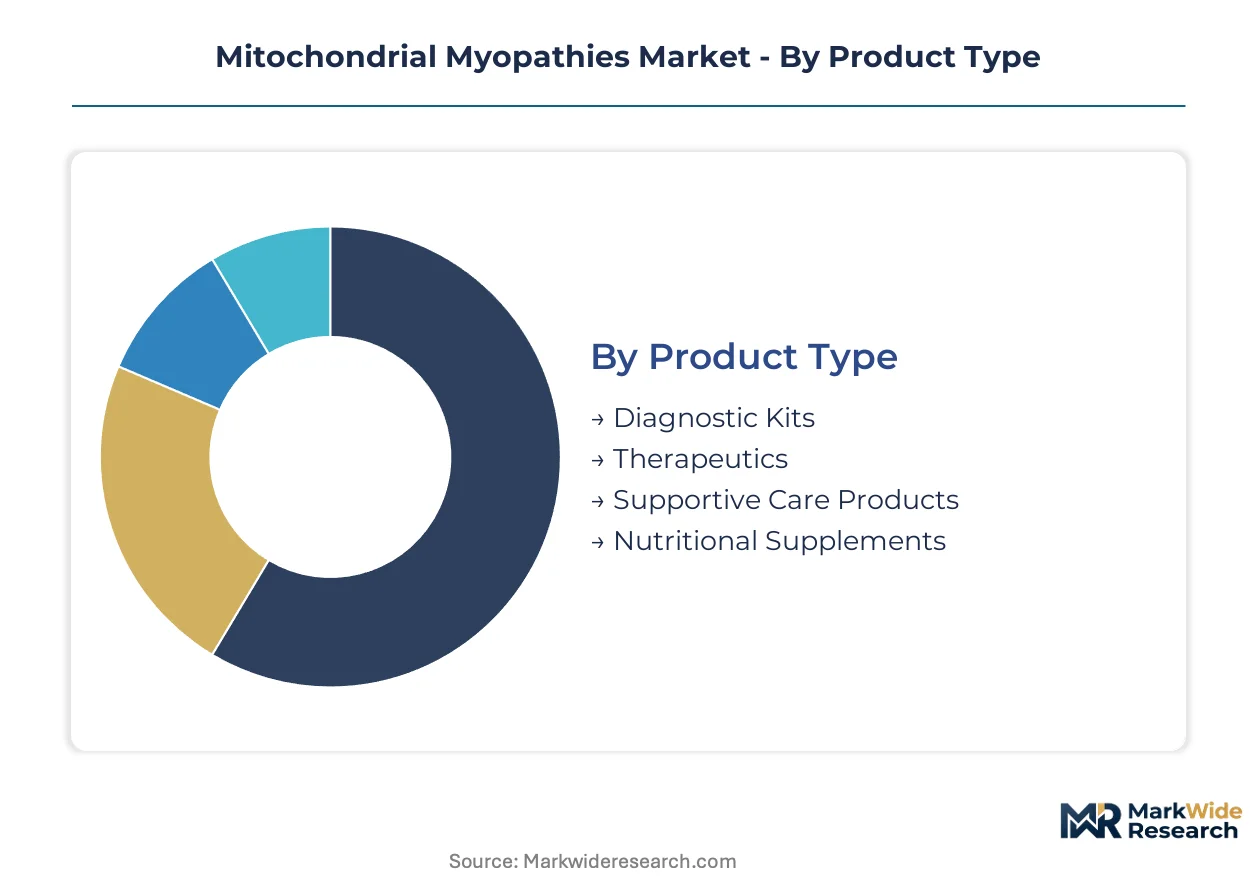
Mitochondrial myopathies demand heterogeneous intervention across diagnostic, therapeutic, and supportive domains. Segmentation reveals how supply concentration in therapeutics contrasts with diagnostic kit fragmentation, while delivery mode choices reflect site-of-care migration trends.
Product Type:
Supply concentration tilts heavily toward therapeutics manufacturers with orphan drug capabilities, while diagnostic kit producers face regulatory recertification cycles under EMA MDR and FDA IVD pathways.
- Therapeutics:Encompasses small-molecule mitochondrial modulators, enzyme replacement therapies, and emerging gene-targeted platforms requiring chronic administration. Demand clusters in specialized neuromuscular centers across the United States, Germany, and Japan where orphan pricing frameworks support margin capture despite ultra-small patient populations.
- Diagnostic Kits:Includes next-generation sequencing panels, heteroplasmy quantification assays, and oxidative phosphorylation enzyme activity tests. Academic medical centers in Boston and Munich drive adoption of unified nuclear-mitochondrial genome profiling that compresses diagnostic timelines from years to weeks.
- Supportive Care Products:Comprises respiratory aids, mobility devices, and cardiac monitoring equipment for multi-organ symptom management.
- Nutritional Supplements:Covers coenzyme Q10, L-carnitine, and vitamin cocktail formulations prescribed as metabolic cofactor adjuncts.
Today's leader: Therapeutics. Tomorrow's challenger: Diagnostic Kits.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from leaner homecare models, with reimbursement policy determining site-of-care economics.
- Hospitals:Academic medical centers and specialized neuromuscular units dominate complex diagnosis and acute intervention. Procurement consolidation through rare disease purchasing coalitions in the United States and Germany is compressing price negotiation timelines for mitochondrial therapy developers.
- Homecare Settings:Long-term supportive care delivery is migrating from infusion centers to home-based administration, opening channel expansion for drug-device combination products and remote monitoring infrastructure.
- Clinics:Outpatient neuromuscular practices handle stable patient monitoring and routine therapeutic adjustments.
- Rehabilitation Centers:Physical and occupational therapy facilities address progressive muscle weakness and functional decline management.
The steepest expansion trajectory belongs to Homecare Settings as payer pressure shifts chronic administration away from hospital cost centers.
Therapy Area:
Application focus determines clinical trial endpoint design, with neuromuscular specialists driving protocol development for heterogeneous genetic subtypes.
- Neuromuscular Disorders:Primary manifestation of mitochondrial myopathies involving progressive muscle weakness, exercise intolerance, and ptosis. FDA Orphan Drug Designation accelerates trial timelines for developers targeting this core indication cluster.
- Genetic Disorders:Encompasses both mitochondrial DNA and nuclear DNA mutation-driven disease mechanisms requiring distinct therapeutic platforms.
- Metabolic Disorders:Addresses lactic acidosis, hypoglycemia, and multi-organ energy failure complicating disease progression.
- Rare Diseases:Captures ultra-orphan regulatory pathways and health technology assessment frameworks governing market access.
Neuromuscular Disorders anchor current revenue pools. Genetic Disorders represent the emerging precision medicine frontier.
Delivery Mode:
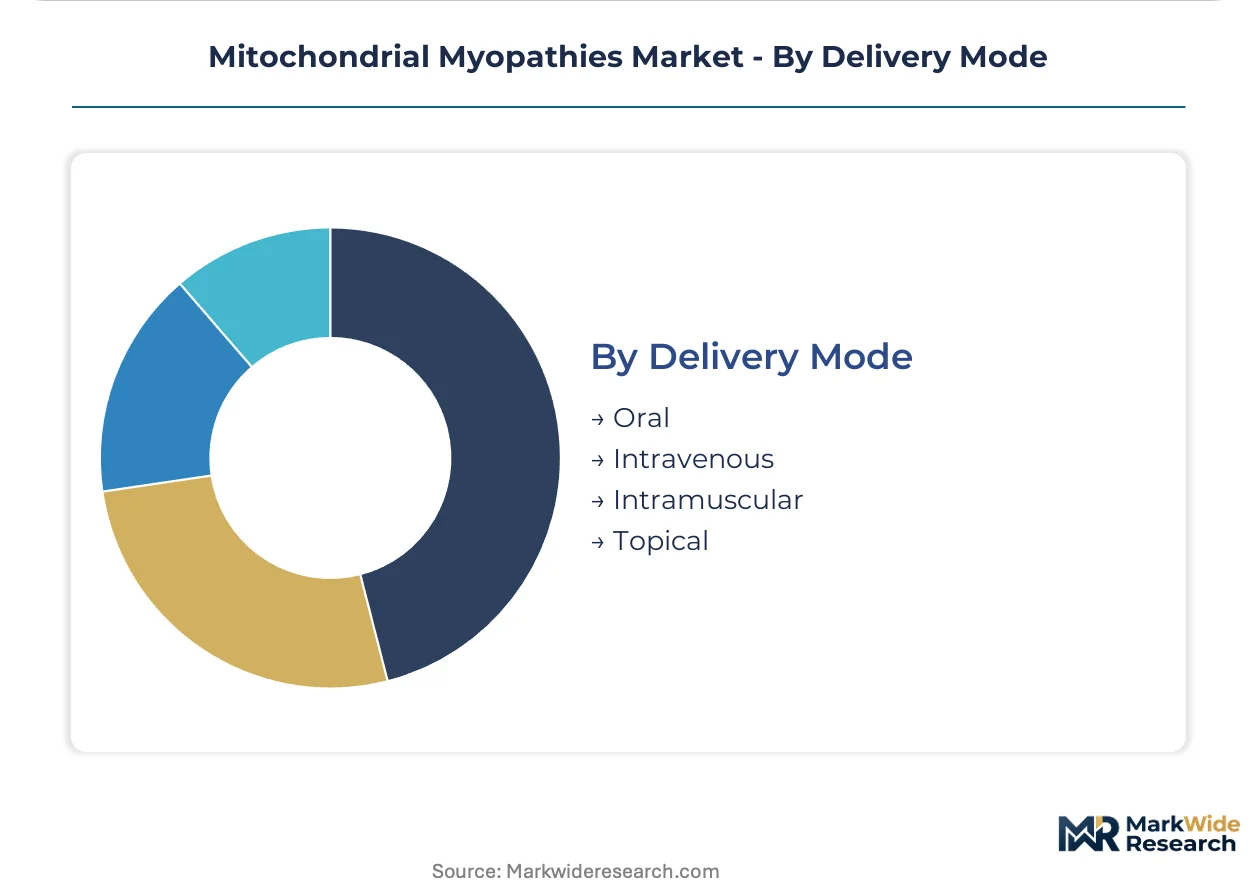
Volume distribution favors oral formulations for chronic maintenance, while intravenous routes retain acute and investigational therapy concentration.
- Oral:Small-molecule mitochondrial modulators and nutritional supplements administered through chronic outpatient regimens. Patient compliance challenges in pediatric populations drive formulation innovation toward palatable delivery systems.
- Intravenous:Enzyme replacement therapies and investigational biologics requiring hospital-based infusion infrastructure. EMA and FDA GMP compliance for sterile manufacturing constrains supplier base concentration.
- Intramuscular:Depot formulations and localized therapeutic delivery for specific neuromuscular symptom targets.
- Topical:Limited current application for cutaneous manifestations, with potential expansion for transdermal metabolic cofactor delivery.
Oral dominates patient-days. Intravenous commands per-dose value premiums in institutional settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized genetic counselors and neuromuscular specialists cluster in academic medical centers across the United States, Germany, and Japan, anchoring diagnostic and therapeutic demand for mitochondrial myopathies in these markets.
United States
FDA Orphan Drug Designations accelerate clinical trial timelines for mitochondrial-targeted therapies, while the NIH's Rare Diseases Clinical Research Network funds natural history studies. Boston and New York City host the highest concentration of specialized neuromuscular centers coordinating multi-site trials.
Germany
EMA Committee for Orphan Medicinal Products incentives attract developers to the European market entry point, with REACH compliance requirements governing diagnostic kit material standards. Munich and Heidelberg academic hospitals lead unified nuclear-mitochondrial genome profiling adoption.
Japan
PMDA's Sakigake designation system fast-tracks regenerative medicine and gene therapy candidates for mitochondrial disorders. Tokyo and Osaka medical centers concentrate expertise in heteroplasmy quantification and modifier gene identification protocols.
United Kingdom
NICE health technology assessments determine reimbursement for ultra-rare disease therapies, while MHRA post-Brexit regulatory pathways diverge from EMA frameworks. London and Cambridge bioclusters advance mitochondrial genome editing research platforms.
Switzerland
Swissmedic's streamlined orphan drug approval processes complement EMA centralized procedures for market access. Basel and Zurich pharmaceutical research hubs specialize in small-molecule mitochondrial modulator development.
Mitochondrial Myopathies Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the mitochondrial myopathies landscape, creating a tiered structure where R&D intensity separates market positions. Large-cap pharmaceutical firms leverage established rare disease infrastructure against mid-cap biotechs betting on platform-specific mitochondrial targeting. Three archetypes dominate: gene therapy platform developers, small-molecule mitochondrial modulator specialists, and diagnostic kit manufacturers navigating MDR recertification. Competitive moves center on strategic partnerships for patient access networks and geographic licensing arrangements for regulatory pathway optimization.
Within the pure-play specialist tier, Stealth BioTherapeutics and Khondrion exemplify mitochondrial-targeted platform approaches, while PTC Therapeutics occupies a position bridging diversified rare disease capabilities with neuromuscular focus. These developers represent contrasting bets on therapeutic modality—biologics versus small molecules—within the same addressable patient populations.
| Leading Market Players |
|---|
| PTC Therapeutics |
| Tisento Therapeutics |
| Stealth BioTherapeutics |
| Thiogenesis Therapeutics |
| Cyclerion Therapeutics |
| UCB |
| Pharming Technologies |
| Saol Therapeutics |
| Khondrion |
| Others |
Value Chain & Pricing Dynamics
Hospital network consolidation across the United States and Germany is compressing procurement timelines and forcing mitochondrial therapy developers to absorb distribution margin compression or risk formulary exclusion from rare disease purchasing coalitions.
Pricing Analysis
Capacity additions in Switzerland and the United States are reshaping price floors for small-molecule mitochondrial modulators as Stealth BioTherapeutics and Khondrion expand manufacturing footprints. Three-tier pricing structure across premium orphan biologics, standard small-molecule maintenance therapies, and economy nutritional supplement tiers reflects FDA Orphan Drug Designation exclusivity periods and chronic administration requirements. Pricing pressure stems from health technology assessment bodies demanding outcome-based evidence for ultra-rare indications. Pediatric metabolic centers exhibit highest price sensitivity due to constrained state Medicaid budgets, while private academic medical centers in Boston and New York City demonstrate lowest sensitivity given research funding offsets.
Supply Chain Analysis
Returns of expired heteroplasmy quantification reagents and refurbished next-generation sequencing platforms flow through specialized diagnostic distributors serving European academic medical centers. Active pharmaceutical ingredient production concentrates in Switzerland, Germany, and the United States for mitochondrial-targeted therapies, with sterile fill-finish capacity clustering in Basel and Boston hubs. Supply chains draw from rare isotope-labeled compounds, synthetic nucleotides, and viral vector substrates as critical inputs. Single-source vulnerability pervades gene therapy plasmid manufacturing, where GMP-certified facilities in Basel and Heidelberg anchor global supply. Distribution runs through rare disease purchasing cooperatives that displace wholesale intermediaries for hospital network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mitochondrial myopathies market functions as a stable compounder anchored by chronic administration requirements and orphan pricing protections that insulate revenue streams from cyclical pharmaceutical sector pressures.
For Market Incumbents: Deploy R&D pipeline diversification into gene therapy convergence platforms to counter substitution risk from curative modalities. Incumbent developers must secure long-term supply agreements for viral vector manufacturing capacity in Basel and Boston before capacity constraints tighten. Stealth BioTherapeutics and Khondrion should deepen backward integration into mitochondrial genome editing tool development to defend platform exclusivity against emerging CRISPR-based entrants. For New Entrants and Emerging Players: Homecare administration models represent the most penetrable white-space target as payer pressure shifts chronic supportive care delivery from hospital infusion centers to patient residences. Diagnostic kit manufacturers should pursue EMA MDR recertification pathways for unified nuclear-mitochondrial genome profiling panels, capitalizing on heteroplasmy quantification standardization gaps that complicate incumbent assay validation. A direct-to-specialist go-to-market angle targeting pediatric metabolic center formulary committees bypasses consolidated purchasing coalition gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with gene therapy platform developers possessing viral vector delivery and mitochondrial genome editing convergence capabilities. The five-to-ten-year investment horizon favors developers with Sakigake-designated candidates in Japan and FDA Breakthrough Therapy-aligned programs in the United States. Acquisition targets should demonstrate heteroplasmy measurement protocol standardization and multi-organ endpoint harmonization across cardiac, neuromuscular, and metabolic outcome measures. Practitioners should monitor FDA Orphan Drug Designation grant rates and EMA MDR diagnostic kit approval timelines as inflection indicators for platform valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA Orphan Drug Designation accelerates mitochondrial therapy development timelines and extends market exclusivity protections. |
| Regulatory Approval Pathway | EMA MDR recertification streamlines diagnostic kit market access across European member states for heteroplasmy assays. |
| Manufacturing Scale-Up | Viral vector capacity expansion in Basel and Boston addresses gene therapy supply constraints for mitochondrial genome editing platforms. |
| Hospital System Partnership | Rare disease purchasing cooperatives in the United States and Germany consolidate formulary decision authority for mitochondrial therapy procurement. |
| Reimbursement Strategy | NICE health technology assessments and German AMNOG processes determine market access for ultra-orphan mitochondrial therapies. |
Study Parameters
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases; plus bottom-up patient population sizing triangulated against top-down orphan drug revenue benchmarks — were reconciled to construct market estimates. Conversations with specialized genetic counselors and neuromuscular specialists at Boston and Munich academic medical centers informed heteroplasmy measurement protocol variability and diagnostic kit adoption patterns.
Historical revenue trajectories for approved mitochondrial therapies were cross-referenced against panel input from payer access specialists and GPO contracts managers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled encompassed product type, end user channel, therapy area, and delivery mode, with genetic subtype heterogeneity and regional regulatory cluster as industry-specific stratifiers. CAGRs were derived from natural history study enrollment trends, FDA Orphan Drug Designation grant velocity, and health technology assessment body evidentiary requirement evolution.
Inputs from FDA Adverse Event Reporting System and EudraVigilance databases were available through the study window; gaps in longitudinal heteroplasmy progression data and real-world evidence collection introduce uncertainty bands around patient population forecasts. Practitioners should monitor FDA Breakthrough Therapy designation grants, EMA PRIME eligibility decisions, and NICE single technology appraisal outcomes for early signals of regulatory and reimbursement inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Gestational Trophoblastic Disease Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
AI in Pharma and Biotech Market
Medical Biotechnology
Becker Muscular Dystrophy Market