
 Stem Cell Banking Market | 2026-2036
Stem Cell Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Stem Cell Banking Market Intelligence
AABB accreditation for cord blood banking is bifurcating the market between certified premium providers and smaller, regional players. Cryo-Cell International leverages its established brand and extensive storage facilities to attract clients in the United States. Cord Blood Registry (CBR) Systems specializes in private family banking, emphasizing long-term viability and service quality. In Europe, Vita34 AG competes on the basis of its dual public and private banking model, offering both individual storage and donation options.
Stem cell banking involves the collection, processing, and long-term storage of stem cells, primarily from umbilical cord blood and tissue. These cells are cryopreserved in liquid nitrogen at temperatures below -150°C to maintain their viability for future therapeutic applications. Umbilical cord blood remains the dominant source due to its non-invasive collection method and rich hematopoietic stem cell content. Within service types, cryopreservation and long-term storage services constitute the core revenue streams for most banking facilities.
Regulatory oversight from bodies like the U.S. FDA and the European Medicines Agency (EMA) dictates stringent standards for cell processing, testing, and facility accreditation. In parallel, Health Canada's regulations govern the safety and quality of cord blood banks, shaping market access and operational compliance. Future provider strategy will hinge on navigating the evolving ethical guidelines and the public versus private banking debate to secure long-term market position.
Market Dynamics
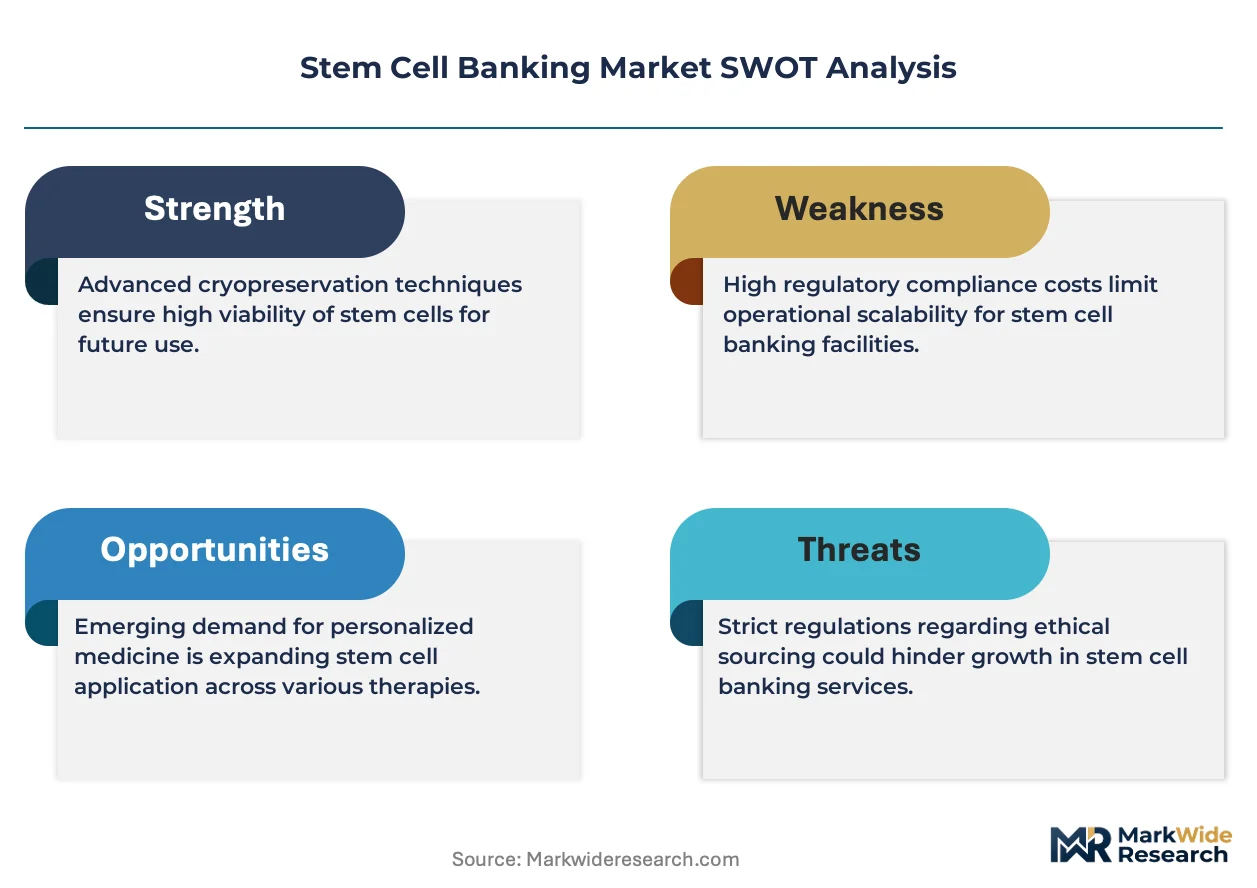
The central force shaping the stem cell banking market is the operational and reputational bifurcation driven by stringent accreditation standards. Bodies like the AABB create a clear divide between certified, premium providers and smaller regional players, influencing everything from client trust to pricing power.
Growth Catalysts
- Advanced Cryopreservation:Improvements in vitrification and cryopreservation protocols are enhancing the long-term viability and quality of stored stem cells, boosting consumer and clinician confidence in their future therapeutic utility.
- Government Support for Regenerative Medicine:National initiatives in countries like China and the United States provide funding and favorable regulatory pathways for cell therapy research, which stimulates demand for high-quality banked stem cells.
- Rising Parental Awareness:Educational campaigns by public health organizations and private banks are increasing awareness among expectant parents about the potential long-term health benefits of banking umbilical cord blood and tissue.
Market Restraints
- High Service Costs:The significant expense associated with the collection, processing, and long-term cryopreservation of stem cells makes private banking inaccessible for a large segment of the population, limiting market penetration.
- Ethical and Regulatory Ambiguity:Ongoing debates and heterogeneous regulations globally concerning the ownership, use, and ethical implications of stem cell research create market uncertainty and can deter potential customers.
- Limited Immediate Use Cases:The number of currently approved therapies using a patient's own cord blood cells is limited, leading some consumers to question the value proposition of long-term storage fees.
Strategic Opportunities
- Geographic Expansion:Entering underpenetrated markets in Latin America and Southeast Asia, where rising disposable incomes and improving healthcare infrastructure create new demand for private stem cell banking.
- Diversification of Stem Cell Sources:Developing and marketing banking services for alternative stem cell sources, such as dental pulp, adipose tissue, and menstrual blood, opens new revenue streams and customer segments.
- Hybrid Banking Models:Offering flexible models that combine private family storage with an option for public donation or research contribution can attract clients seeking both personal security and altruistic options.
Industry Challenges
- Global Compliance Burden:Adhering to a complex and evolving web of international standards from bodies like the FDA, EMA, and Health Canada requires continuous investment in quality management systems and personnel training.
- Cold Chain Integrity:Maintaining the viability of samples through an unbroken cold chain from the point of collection to the biorepository is a significant logistical and operational hurdle, especially across international borders.
- Public Misinformation:Combating scientifically inaccurate claims and managing public perception regarding the efficacy and applications of banked stem cells remains a persistent communication challenge for the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stem Cell Banking Market |
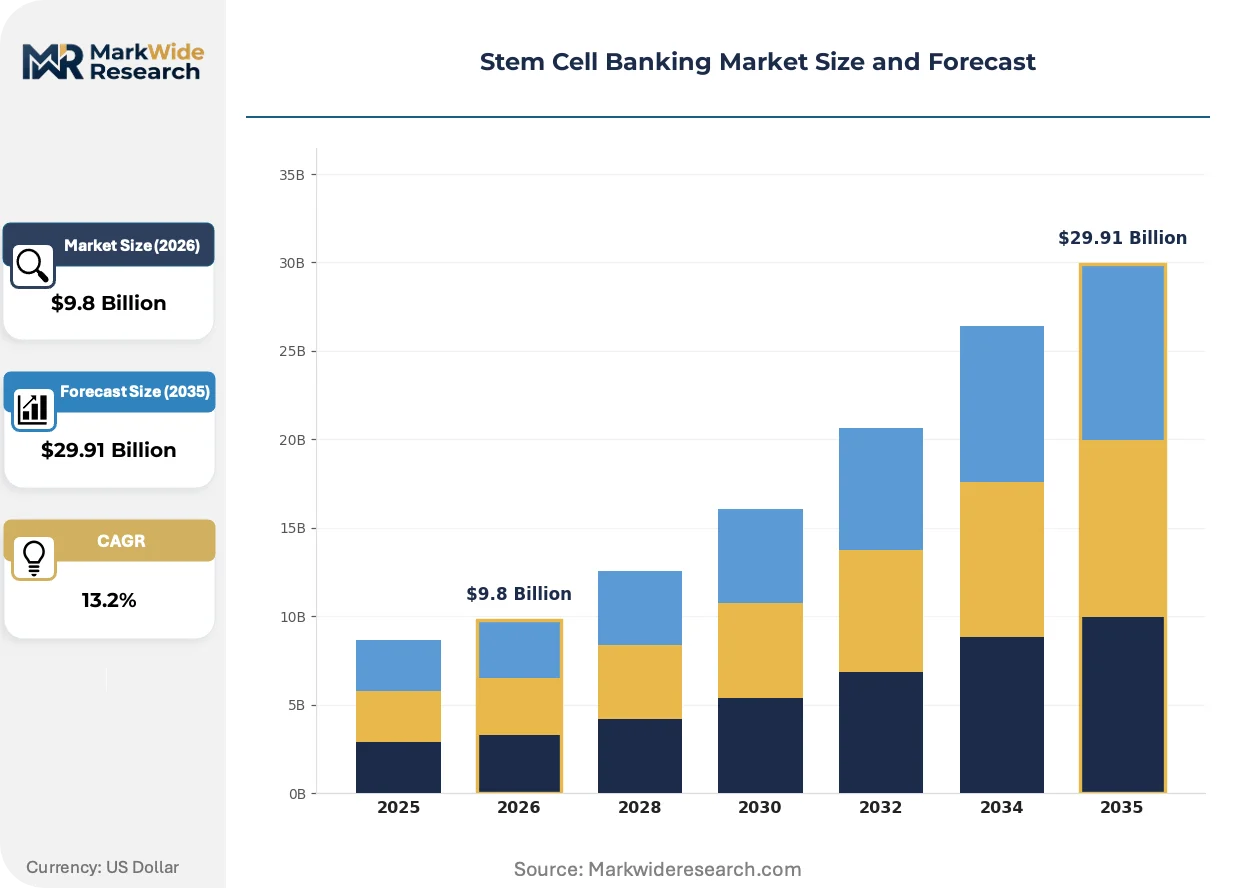
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $29.91 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Stem Cell Type: Umbilical Cord Blood, Adipose Tissue, Bone Marrow, Peripheral Blood Service Type: Cryopreservation, Isolation & Processing, Storage, Testing End User: Research Institutes, Regenerative Medicine Centers, Fertility Clinics, Pharmaceutical Companies Application: Hematopoietic Disorders, Immune Disorders, Genetic Diseases, Regenerative Therapies |
| Companies Covered | Cryo-Cell International, Cord Blood Registry (CBR) Systems, ViaCord, LifeCell International, Cordlife Group, StemCyte, Global Cord Blood Corporation, Vita34 AG, Smart Cells International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stem Cell Banking Market Strategic Shifts & Innovations
Technological refinement in cell processing and evolving regulatory frameworks are defining the next phase of the stem cell banking industry. These shifts are pushing providers to enhance service value beyond simple storage, focusing on data, quality, and compliance to differentiate in a competitive market.
Automated Processing Systems
Automated, closed-system cell processing units reduce manual handling and mitigate contamination risks during sample preparation. Major public and private banks are adopting these systems to standardize outcomes and increase operational efficiency. This technological shift is miniaturizing the physical footprint of processing laboratories, thereby lowering the capital and operational costs associated with facility expansion.
Harmonization with Medical Device Regulations
The European Union's Medical Device Regulation (MDR) is setting a new precedent for the materials used in stem cell banking. The regulation imposes stricter requirements for the validation and post-market surveillance of collection kits, processing consumables, and storage equipment. Stem cell banks operating in or exporting to Europe must now ensure their entire supply chain is MDR-compliant, impacting procurement strategies.
Demand for Integrated Genetic Data
A preference is emerging for banking services that include comprehensive genetic screening and HLA typing as part of the initial processing. This shift adds a layer of actionable data to the stored biological asset, displacing providers that offer only basic cryopreservation. This demand is most visible in North America, where consumers are increasingly focused on personalized medicine and future transplant compatibility.
Stem Cell Banking Market Segmentation
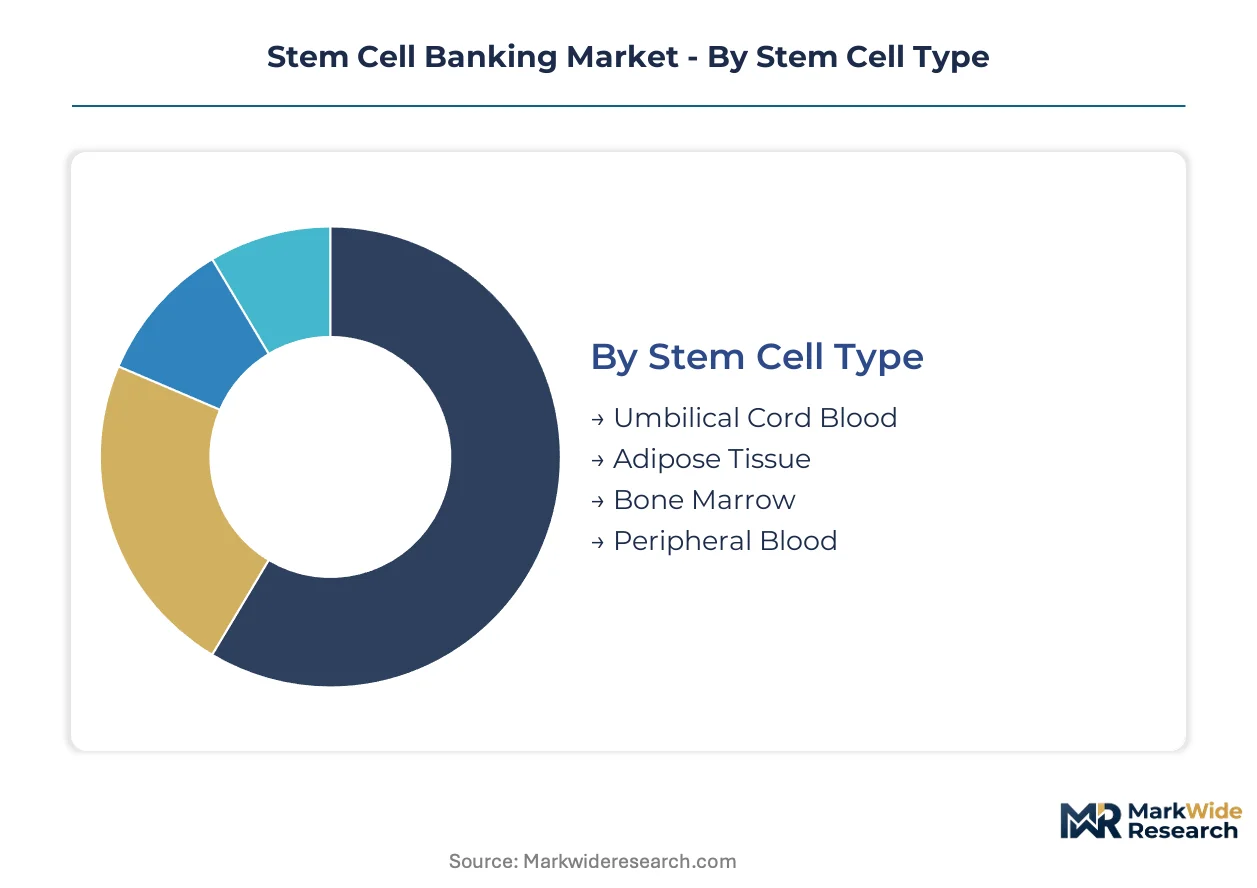
The stem cell banking market's structure reflects diverse biological sources and specialized service offerings. Market segmentation provides clarity on where value accrues and how different customer needs are addressed within this specialized healthcare sector.
Stem Cell Type:
Segments within stem cell type face substitution pressure from alternative biological sources, influencing collection protocols and therapeutic applications.
- Umbilical Cord Blood:This segment comprises hematopoietic stem cells collected from the umbilical cord after birth. Demand concentrates in pediatric applications and for immune reconstitution, driven by its non-invasive collection and lower immunogenicity risk compared to other sources.
- Adipose Tissue:Mesenchymal stem cells are isolated from fat tissue, offering multipotent capabilities for regenerative medicine. Its market demand is expanding for orthopedic and cosmetic applications, supported by minimally invasive harvesting techniques and ease of access.
- Bone Marrow:This traditional source of hematopoietic stem cells requires an invasive collection procedure. Its use is primarily for severe blood disorders.
- Peripheral Blood:Mobilized hematopoietic stem cells are collected non-invasively from circulating blood. This method is often used for adult stem cell transplants.
Umbilical Cord Blood retains volume leadership; Adipose Tissue holds the steepest expansion curve.
Service Type:
The cost tier of stem cell banking services varies significantly, reflecting the complexity and specialized infrastructure required for each operational phase.
- Cryopreservation:This service involves the controlled freezing and preservation of viable stem cells at ultra-low temperatures, typically below -150°C. Demand is driven by the long-term storage needs for future therapeutic use, underpinning the entire banking value proposition.
- Storage:Long-term storage maintains cryopreserved stem cells in specialized biorepositories under monitored conditions for decades. This core revenue stream for banks is critical for ensuring sample viability and availability for future medical interventions.
- Isolation & Processing:This initial stage prepares raw biological samples by separating and concentrating stem cells. It requires specialized laboratory equipment.
- Testing:Comprehensive testing ensures the quality, viability, and sterility of banked stem cell samples. This maintains regulatory compliance.
Cryopreservation services are fundamental to all clients; storage represents the primary ongoing customer commitment.
End User:
Customer type differentiation shapes service customization and regulatory compliance demands within the stem cell banking market.
- Regenerative Medicine Centers:These specialized facilities utilize banked stem cells for research and clinical therapies, focusing on tissue repair and disease treatment. Demand is high for high-quality, characterized samples for novel therapeutic development and patient application.
- Research Institutes:Academic and private research entities use stem cell banks as a source for basic science and preclinical studies. Their demand emphasizes genetic diversity and robust sample characterization for experimental purposes.
- Fertility Clinics:These clinics often partner with banks for cord blood collection services, offering options to expectant parents. They serve as a key referral point.
- Pharmaceutical Companies:Pharma companies leverage banked stem cells for drug discovery, toxicology screening, and cell-based therapeutic development. They require large, consistent batches.
Regenerative Medicine Centers drive clinical application volume; Research Institutes underpin future therapeutic breakthroughs.
Application:
Application volume varies, driven by disease prevalence and the maturity of therapeutic protocols utilizing banked stem cells.
- Hematopoietic Disorders:This segment involves conditions like leukemia, lymphoma, and sickle cell anemia, traditionally treated with stem cell transplants. Demand remains robust due to established clinical efficacy and broad medical acceptance for these life-threatening diseases.
- Regenerative Therapies:This emerging application area focuses on tissue repair and organ regeneration for conditions such as heart disease, neurological disorders, and spinal cord injuries. Demand is expanding rapidly with ongoing clinical trials and technological advancements in cell therapy.
- Immune Disorders:Stem cell therapies address various immune system deficiencies and autoimmune conditions. These applications are gaining clinical traction.
- Genetic Diseases:Banking offers potential future treatment for inherited genetic conditions. Therapies for these diseases are under active research and development.
Hematopoietic Disorders represent a mature application area; Regenerative Therapies are rapidly advancing in clinical trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government support for regenerative medicine research and increasing parental awareness drive regional demand for stem cell banking services. National initiatives in key economies foster innovation and therapeutic development. These factors collectively shape market dynamics across diverse geographies.
United States
High parental awareness for future therapeutic uses and a focus on personalized medicine drive significant demand in the United States. The FDA dictates stringent standards for cell processing and facility accreditation, ensuring quality. Biotech hubs in Boston and California's Bay Area conduct extensive research into stem cell applications, propelling innovation.
China
Expanding healthcare infrastructure and national initiatives supporting cell therapy research fuel substantial market growth in China. The country's favorable regulatory pathways stimulate demand for high-quality banked stem cells. Major cities like Beijing and Shanghai are seeing rapid expansion of public and private banking facilities, increasing accessibility.
Germany
An established healthcare system and a strong focus on regenerative medicine research create consistent demand in Germany. The European Medicines Agency (EMA) and MDR influence operational protocols for stem cell banks. Research institutions in Munich and Berlin contribute to advanced cryopreservation techniques, enhancing viability.
India
Rising disposable incomes and improving healthcare infrastructure contribute to market expansion in India. The country's national pharmaceutical regulator oversees quality and safety standards for cord blood banks. Metropolitan centers like Mumbai and Bangalore are witnessing growth in private stem cell banking services, driven by new entrants.
Brazil
A growing middle class and increasing awareness among expectant parents drive demand in Brazil. ANVISA regulations govern the collection, processing, and storage of biological materials, ensuring compliance. São Paulo and Rio de Janeiro serve as key hubs for stem cell banking facilities and clinical research activities.
Stem Cell Banking Market Key Industry Players
Player mix skews toward specialized providers focusing on service quality and long-term storage solutions. The market exhibits a tiered structure, with premium, AABB-accredited banks differentiating themselves from smaller regional entities. Strategic archetypes include established global players with extensive infrastructure, regional specialists, and niche service providers offering advanced testing. Companies pursue geographic expansion into underpenetrated markets and portfolio diversification into new stem cell sources as dominant competitive moves.
Within the established global player archetype, Cryo-Cell International and Cord Blood Registry (CBR) Systems exemplify providers with extensive storage facilities and a focus on private family banking. Vita34 AG, a European entity, represents a hybrid banking model, offering both individual storage and public donation options. These entities anchor market standards for quality and service breadth across different regional contexts, influencing operational best practices. Their presence underscores the market's emphasis on accreditation and comprehensive service offerings, particularly in mature economies.
| Leading Market Players |
|---|
| Cryo-Cell International |
| Cord Blood Registry (CBR) Systems |
| ViaCord |
| LifeCell International |
| Cordlife Group |
| StemCyte |
| Global Cord Blood Corporation |
| Vita34 AG |
| Smart Cells International |
Cost & Logistics Intelligence
Operational scale in cryopreservation facilities significantly influences supply concentration, allowing larger providers to leverage fixed costs across higher volumes. This scale also establishes price floors for premium services, influencing market entry for smaller players.
Pricing Analysis
Certification level (AABB accreditation) creates the primary spread in stem cell banking pricing, differentiating premium providers from regional entities. The dominant pricing model is a hybrid subscription and per-unit transactional structure, covering initial processing and annual storage fees. Brand premium and service breadth, including comprehensive genetic screening, serve as key differentiation drivers for pricing. Pricing softness reflects competition for private banking clients, particularly from smaller, non-accredited facilities. Regenerative Medicine Centers exhibit the least price sensitivity, prioritizing quality and characterization, while individual parents often show greater price sensitivity.
Supply Chain Analysis
Cold chain integrity from collection to biorepository presents a significant logistical cost, especially across international borders. Geographic supply concentration for collection kits and specialized cryopreservation media centers in regions with advanced medical device manufacturing, such as Germany and the United States. Raw material dependencies include medical-grade plastics for collection bags and vials, along with liquid nitrogen for long-term storage. Single-source vulnerability for specialized processing reagents represents a structural supply chain risk. Distribution runs through a direct-to-consumer model for private banking and direct institutional partnerships for public and research entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stem cell banking market requires a substitution defense, as alternative therapies or evolving ethical guidelines could displace current value propositions.
For Market Incumbents:Fortify market position by investing in advanced automated processing systems to enhance efficiency and reduce contamination risks. Pursue strategic geographic expansion into underpenetrated markets like Latin America, leveraging established brand recognition and AABB accreditation. Deepen vertical integration into genetic data services, offering comprehensive HLA typing and screening to provide greater value beyond basic storage. This strategy addresses competitive pressure from niche providers offering specialized data services.
For New Entrants and Emerging Players:Differentiate on specialized service offerings, such as banking alternative stem cell sources like adipose tissue or dental pulp. Target underpenetrated markets in Southeast Asia where healthcare infrastructure is improving and parental awareness is rising. A go-to-market angle focusing on hybrid banking models, combining private storage with public donation options, can attract a broader client base. This approach offers flexibility and altruistic options, appealing to diverse consumer preferences.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors established players with robust infrastructure and strong regulatory compliance. Long-term viability depends on navigating evolving ethical guidelines and the public versus private banking debate. Acquisition targets should include regional specialists with strong local market penetration or companies with proprietary cryopreservation technologies. The signal to watch is the expansion of approved therapeutic applications for banked stem cells, indicating increased clinical utility and market demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Automated Processing | Reduces manual handling and contamination risks, standardizing outcomes for premium providers. |
| Geographic Expansion into Latin America | Captures new demand from rising disposable incomes and improving healthcare infrastructure. |
| Diversify Stem Cell Sources | Unlocks new revenue streams from adipose tissue and dental pulp banking services. |
| Offer Hybrid Banking Models | Attracts clients seeking both personal security and altruistic options for stem cell use. |
| Enhance Genetic Data Integration | Adds actionable data to stored biological assets, supporting personalized medicine applications. |
Research Approach
Initial hypotheses were tested against primary input from clinicians, laboratory directors, regulatory affairs leads, and procurement managers, and refined through iterative analysis. This approach combined insights from direct stakeholder conversations with rigorous secondary validation. Secondary data sources included regulatory filings (FDA, EMA), scientific publications on cryopreservation techniques, and healthcare infrastructure reports from national health agencies. Bottom-up market sizing was triangulated against top-down industry revenue figures.
Variance decomposition informed the analytical framework, modeling market growth based on shifts in stem cell type adoption, service utilization, end-user demand, and application maturity across the analysis window. Segmentation dimensions modeled included stem cell source, service type, end-user segment, and primary therapeutic application. Compound Annual Growth Rates (CAGRs) were derived from historical growth trends and projected technological advancements. Key forecast inputs included projected birth rates and clinical trial success rates for regenerative therapies.
The analysis sits within stated boundaries; outcomes outside significant shifts in regulatory frameworks or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding clinical adoption rates and consumer awareness. Geopolitical events or major public health crises represent specific risk factors that could revise market projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Orthobiological Products Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Global Biological Stains Market