
 Cord Blood Banking Market | 2026-2036
Cord Blood Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Cord Blood Banking Market Analysis
The gap between premium private banking and commodity-oriented public donation is expanding as service tiers diverge on cryopreservation quality, genetic testing add-ons, and contractual duration terms. Cryo-Cell International leverages proprietary processing technologies to sustain margin premiums in the North American private segment. Cordlife Group anchors its competitive position across Southeast Asia through localized collection networks and laboratory infrastructure. China Cord Blood Corporation dominates the mainland market through exclusive regional licenses and captive hospital partnerships.
Cord blood banking encompasses the collection, processing, testing, cryopreservation, and long-term storage of hematopoietic stem cells derived from umbilical cord blood, maintained at temperatures below -150°C in liquid nitrogen vapor-phase systems to preserve viability for therapeutic transplantation. The service serves hematologic and oncologic treatment protocols, with private banking commanding higher per-unit economics than public donation models. Private banking generates the dominant revenue share as families pay upfront collection fees plus annual storage charges, while hybrid banking models are gaining traction by combining public donation rights with retained family access options. Therapeutic applications in transplantation currently occupy the largest application segment, though cellular therapy pipelines are deepening demand from biotech firms seeking qualified starting material.
The FDA regulates cord blood as a human cell and tissue product and biological drug depending on intended use, creating dual compliance pathways that shape operational costs and market access conditions. AABB accreditation and FACT-NetCord standards further define quality benchmarks that institutions must maintain for clinical acceptance and reimbursement eligibility. Stakeholders must monitor evolving FDA guidance on expanded cord blood indications and emerging state-level legislation governing direct-to-consumer marketing claims.
Market Dynamics
The FDA's Section 351 licensure pathway for cord blood biologics is compressing operational margins while simultaneously erecting competitive moats around capitalized incumbents. This regulatory density favors laboratories with captive collection networks and automated processing infrastructure.
Growth Catalysts
- Expanded Transplant Indications:FDA approvals for additional hematologic and oncologic conditions are widening the addressable patient pool for stored cord blood units.
- Cellular Therapy Pipelines:Biotech firms seeking qualified starting material for CAR-T and regenerative medicine applications are deepening demand for high-quality cryopreserved inventory.
- Expectant Parent Awareness:Direct-to-consumer education campaigns in the United States are accelerating private banking enrollment among first-time mothers.
Market Restraints
- Liquid Nitrogen Supply Concentration:Cryopreservation infrastructure depends on concentrated industrial gas suppliers, creating input vulnerability for regional laboratories.
- Dual Compliance Costs:The FDA's bifurcated regulatory pathway for human cell and tissue products versus biological drugs imposes redundant quality systems and documentation burdens.
- Public Donation Substitution:Zero-cost public banking alternatives in major metropolitan areas constrain price elasticity for private banking services.
Strategic Opportunities
- Hybrid Banking Models:Contracts combining public donation rights with retained family access options address ethical concerns while preserving revenue streams.
- Genetic Testing Add-ons:Pharmacogenomic and carrier screening services bundled with collection packages expand per-customer lifetime value.
- Southeast Asia Penetration:Underdeveloped cold chain infrastructure in Indonesia and Vietnam presents first-mover advantages for localized laboratory investment.
Industry Challenges
- Cryobiology Talent Scarcity:Qualified technicians for vapor-phase nitrogen management and viability testing command premium compensation in competitive labor markets.
- AABB Accreditation Timelines:Extended audit cycles and corrective action protocols delay market entry for new processing facilities.
- Legacy Inventory Integration:Merged operations struggle to harmonize disparate cryopreservation protocols and chain-of-custody documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cord Blood Banking Market |
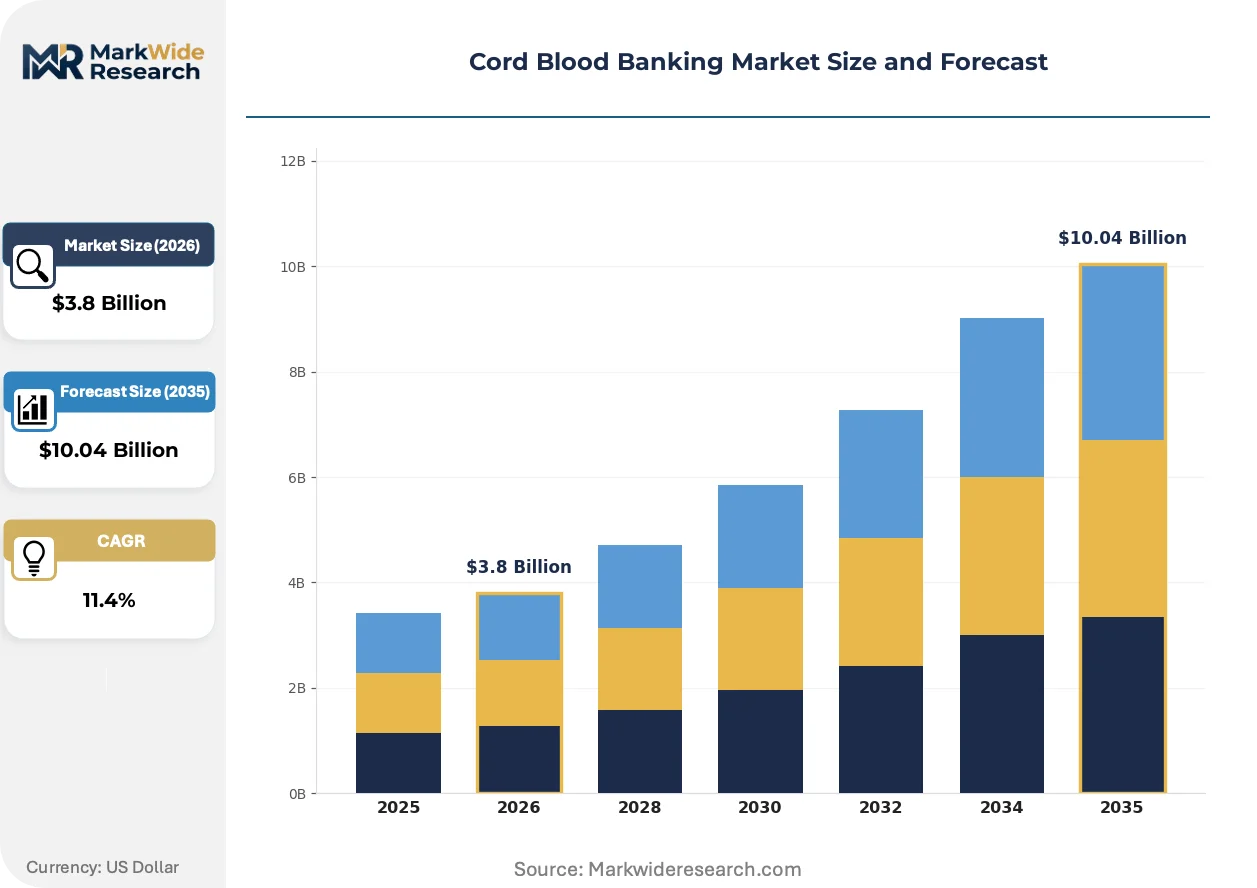
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Banking, Private Banking, Hybrid Banking, Storage Solutions Application: Therapeutic Uses, Research, Cellular Therapy, Transplantation End User: Hospitals, Research Institutions, Biotech Firms, Clinics Storage Method: Cryopreservation, Freezing, Liquid Nitrogen, Thawing Technique |
| Companies Covered | Cryo-Cell International, Inc., Cordlife Group Limited, China Cord Blood Corporation, FamiCord Group, Viacord, CBR Systems, StemCyte, Inc., Americord Registry, LifeCell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cord Blood Banking Market Emerging Trajectories
Automation is penetrating cord blood processing workflows while regulatory frameworks tighten around quality verification. These forces are reshaping capital deployment priorities across private and public banking operations.
Automated cell separation platforms are automating density-gradient processing and volume reduction steps that previously required manual technician intervention. Mid-scale private banks in the United States are adopting these systems to reduce labor costs and standardize unit-to-unit consistency. This technology compression is enabling smaller laboratories to achieve processing parity with established incumbents.
REACH chemical safety regulations in Europe are imposing new documentation requirements on cryoprotectant agents used in preservation media. Manufacturers must now submit extended toxicity dossiers for dimethyl sulfoxide and alternative stabilizing compounds. European cord blood facilities are responding by qualifying secondary suppliers and reformulating proprietary media blends.
Subscription-based storage contracts are displacing traditional upfront collection-plus-annual-fee structures in North American direct-to-consumer channels. Expectant parents increasingly prefer monthly payment plans that bundle processing, testing, and multi-decade storage into predictable outflows. This financing innovation is most visible in competitive metropolitan markets where customer acquisition costs have escalated.
Cord Blood Banking Market Segmentation
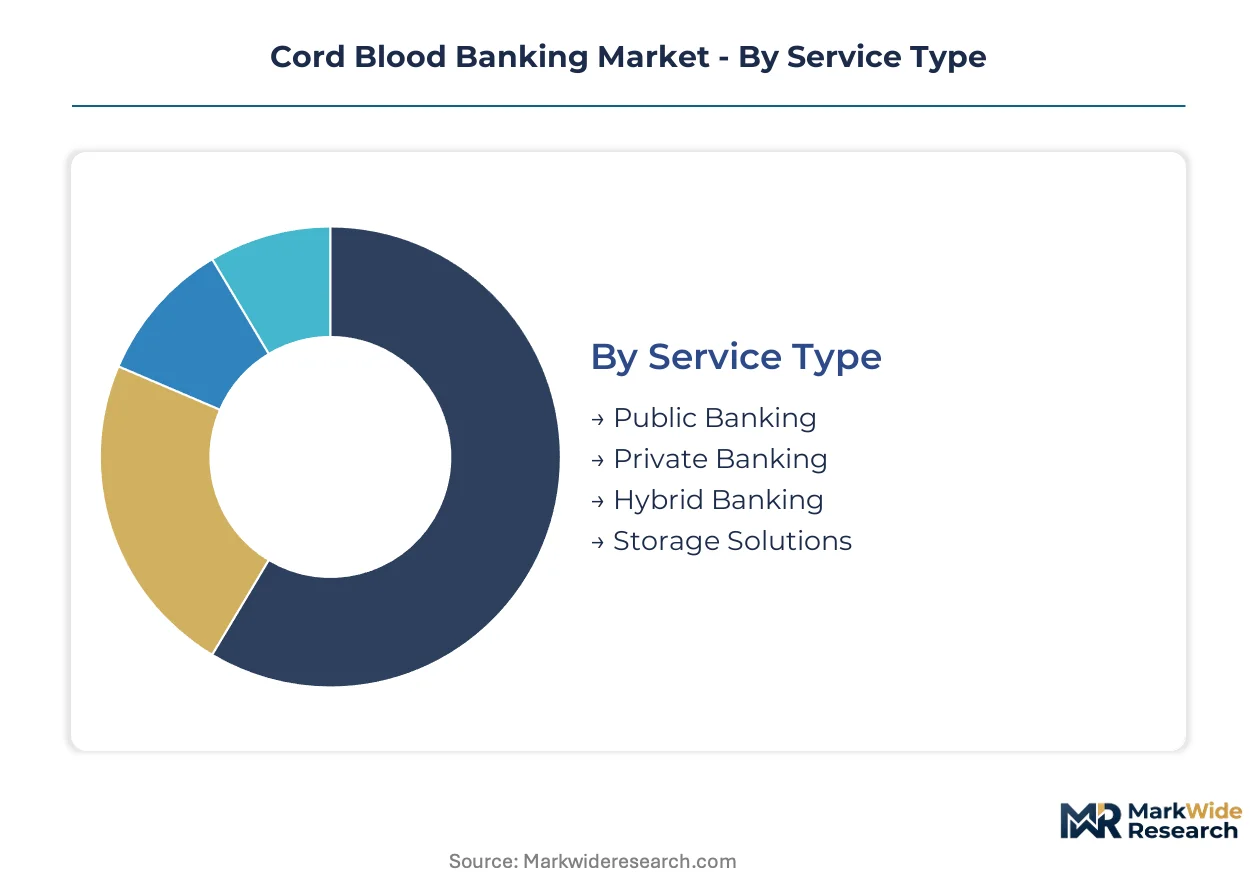
Segmentation in cord blood banking reveals how revenue models, technical specifications, and customer profiles diverge across service tiers. These distinctions shape capital deployment priorities and regulatory compliance burdens for operators.
Service Type:
Standalone services operate independently from hospital systems, while embedded services integrate directly with maternity care workflows.
- Public Banking:Donation-based model where families surrender ownership rights; units enter searchable registries for transplant matching. Demand concentrates in major metropolitan areas with established collection infrastructure, constrained by zero-cost positioning that limits operational investment.
- Private Banking:Fee-for-service model granting families exclusive storage rights and retrieval access. Families in the United States with high out-of-pocket healthcare spending sustain premium uptake, driven by direct-to-consumer education campaigns targeting first-time mothers.
- Hybrid Banking:Contracts split donation rights between public registry access and retained family priority. Emerging uptake in competitive markets addresses ethical concerns while preserving laboratory revenue streams.
- Storage Solutions:Third-party infrastructure services for laboratories lacking captive cryopreservation capacity.
Volume placements concentrate in Private Banking; the faster expansion belongs to Hybrid Banking.
Application:
Cost tiers separate mature therapeutic protocols from emerging research applications with unproven reimbursement pathways.
- Therapeutic Uses:Established clinical applications in hematologic and oncologic treatment protocols with defined reimbursement codes. Hospital systems in the United States anchor demand through standardized transplant procedures.
- Cellular Therapy:CAR-T and regenerative medicine pipelines require qualified starting material with stringent viability specifications. Biotech firms in Boston and San Francisco deepen procurement of high-quality cryopreserved inventory.
- Research:Academic and commercial investigations into stem cell biology and differentiation mechanisms.
- Transplantation:Allogeneic and autologous stem cell replacement procedures for blood disorders.
Therapeutic Uses commands the dominant placement volume; Cellular Therapy is climbing the fastest as biotech pipelines mature.
End User:
Customer type determines contract structure, with institutional procurement diverging sharply from individual family decisions.
- Hospitals:Integrated delivery networks perform collections and coordinate transplant referrals; captive partnerships with private banks in the United States lock in volume through exclusive agreements.
- Biotech Firms:Cell therapy developers source qualified starting material under master service agreements with defined quality specifications.
- Research Institutions:Academic medical centers access de-identified units for protocol development.
- Clinics:Independent obstetric practices facilitate collections without processing infrastructure.
Hospitals dominate placement volume; Biotech Firms are gaining share fastest as cellular therapy manufacturing scales.
Storage Method:
Maturity levels separate decades-proven cryopreservation protocols from emerging alternatives with limited clinical validation.
- Cryopreservation:Controlled-rate freezing with cryoprotectant media preserves viability below -150°C. Vapor-phase liquid nitrogen systems in the United States maintain the dominant installed base, shaped by FDA licensure requirements under Section 351.
- Liquid Nitrogen:Immersion and vapor-phase storage systems using industrial gas supply chains concentrated among regional suppliers.
- Freezing:Mechanical freezer storage above cryogenic temperatures for short-term holding.
- Thawing Technique:Standardized warming protocols to restore viability prior to therapeutic use.
Cryopreservation anchors placement volume; Liquid Nitrogen infrastructure is expanding most quickly as automated processing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-San Francisco corridor anchors North American cord blood banking activity, with biotech procurement clusters in Massachusetts and California driving demand for high-quality cryopreserved inventory. This geographic concentration shapes regulatory priorities and infrastructure investment patterns across national markets.
United States
Expectant parents in metropolitan markets sustain premium private banking enrollment through direct-to-consumer education campaigns targeting first-time mothers. The FDA's Section 351 licensure pathway under the Public Health Service Act elevates operational barriers while compressing margins for undercapitalized entrants. Cryo-Cell International leverages proprietary processing technologies from its Florida headquarters to maintain competitive positioning in the private segment.
China
Exclusive regional licenses and captive hospital partnerships concentrate market control among state-connected operators in Beijing, Shanghai, and Guangzhou. The National Medical Products Administration maintains stringent oversight of biological drug manufacturing while provincial health commissions regulate collection network expansion. China Cord Blood Corporation dominates mainland volume through its licensed regional monopolies.
Germany
REACH chemical safety regulations impose extended toxicity documentation requirements on cryoprotectant agents used in preservation media. The Paul-Ehrlich-Institut coordinates with EMA standards to maintain quality benchmarks for hematopoietic stem cell products. FamiCord Group anchors European operations through centralized laboratory infrastructure serving cross-border demand.
Singapore
Localized collection networks and laboratory infrastructure position the city-state as Southeast Asia's cord blood banking hub. The Health Sciences Authority aligns regulatory frameworks with international accreditation standards while supporting regional export capacity. Cordlife Group extends its Singapore-based processing capabilities into Indonesia and Vietnam through partnership structures.
India
Rising out-of-pocket healthcare spending in Mumbai, Delhi, and Bangalore accelerates private banking adoption among affluent households. The Central Drugs Standard Control Organization oversees biological product licensing while state-level health departments regulate collection facility licensing. LifeCell International operates processing infrastructure targeting tier-1 metropolitan demand.
Cord Blood Banking Market Vendor Landscape
Capital-heavy laboratories compete with asset-light marketing intermediaries in a tiered structure where captive collection networks determine sustainable margin capture. The market concentrates around incumbents with automated processing infrastructure and FDA licensure, while smaller operators struggle under dual compliance burdens. Three archetypes dominate: integrated laboratory-network operators, regional collection specialists, and hybrid public-private service providers. Competitive intensity manifests through exclusive hospital partnerships and geographic license acquisitions rather than price competition.
Among North American integrated operators, Cryo-Cell International, Inc. and CBR Systems exemplify the capital-intensive archetype with captive processing infrastructure. Viacord occupies a position within the same tier. In Asia-Pacific markets, Cordlife Group Limited and China Cord Blood Corporation represent contrasting models—Singapore-based regional expansion versus mainland Chinese licensed regional monopolies. These named entities anchor industry-level commentary on geographic specialization and regulatory arbitrage strategies without implying specific strategic actions or market positions beyond their evident archetype alignment.
| Leading Market Players |
|---|
| Cryo-Cell International, Inc. |
| Cordlife Group Limited |
| China Cord Blood Corporation |
| FamiCord Group |
| Viacord |
| CBR Systems |
| StemCyte, Inc. |
| Americord Registry |
| LifeCell International |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen spot prices in the US Gulf Coast feed directly into cord blood banking economics, compressing margins at regional laboratories while amplifying pricing power for vertically integrated operators with captive industrial gas contracts. This input-cost cascade stratifies service tiers across the industry.
Pricing Analysis
Outcome-linked pricing anchors private cord blood banking, where families pay premium collection fees based on guaranteed viability thresholds and multi-decade storage access. Three-tier pricing structure across premium, standard, and economy levels separates FDA-licensed facilities from AABB-accredited laboratories and unaccredited collection intermediaries. Cost compression in the economy tier is intensifying because public donation alternatives constrain price elasticity in major metropolitan markets. First-time mothers in competitive US markets show highest price sensitivity, while biotech procurement teams demonstrate lowest sensitivity due to stringent quality specifications for cellular therapy starting material.
Supply Chain Analysis
Cryoprotectant supply rests on German and Japanese specialty chemical producers manufacturing dimethyl sulfoxide and trehalose formulations under REACH and pharmaceutical-grade standards. Automated cell separation hardware draws from US and Swiss precision engineering clusters, while vapor-phase liquid nitrogen infrastructure sources from regional industrial gas distributors concentrated in Texas, Louisiana, and Alberta. Single-source vulnerability in cryoprotectant qualification creates regulatory risk for European laboratories reformulating preservation media. Distribution runs through hospital-integrated collection networks and direct-to-consumer obstetric partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cord blood banking operates as a capacity-constrained industry where FDA Section 351 licensure bottlenecks prop pricing premiums for qualified incumbents. Laboratory throughput limits and extended AABB accreditation timelines sustain this supply constraint.
For Market Incumbents: Anchor competitive position through automated processing infrastructure deployment and exclusive hospital partnership renewals in high-birth-rate metropolitan markets. Cryobiology talent scarcity threatens operational scalability; defend against this through captive training pipelines and retention premiums for vapor-phase nitrogen technicians. FDA licensure maintenance represents the priority lever for margin preservation. For New Entrants and Emerging Players: Direct-to-consumer telehealth platforms offer the lowest-friction entry vector for expectant parent acquisition without captive hospital infrastructure. Hybrid banking contracts in Southeast Asian markets present the most penetrable white-space, combining public registry access with retained family priority. Target Indonesia and Vietnam through partnership structures with local obstetric networks rather than greenfield laboratory investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale private banks with existing AABB accreditation and underutilized processing capacity in the United States. Long-term viability hinges on cellular therapy pipeline maturation and biotech procurement contract renewals. Watch FDA expanded indication approvals as the inflection signal for inventory valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Infrastructure Deployment | Reduces labor costs and standardizes unit consistency for FDA licensure compliance. |
| Hybrid Banking Model Introduction | Addresses ethical concerns while preserving revenue streams in competitive metropolitan markets. |
| Exclusive Hospital Partnership Expansion | Locks in collection volume through captive maternity care workflow integration. |
| Genetic Testing Add-on Bundling | Expands per-customer lifetime value through pharmacogenomic and carrier screening services. |
| Southeast Asia Laboratory Investment | Captures first-mover advantages in Indonesia and Vietnam cold chain infrastructure gaps. |
Methodological Framework
Document review covered FDA BLA filings, AABB accreditation directories, and EMA hematopoietic stem cell guidance documents, complemented by interviews with cord blood laboratory directors, obstetric practice managers, biotech procurement specialists, and hospital transplant coordinators. Secondary sources included SEC 10-K disclosures from listed operators, CMS transplant outcome databases, and clinical trial registries tracking expanded indication studies. Bottom-up unit economics modeling triangulated against top-down market sizing from national birth statistics and banking enrollment rates.
Segment-level outputs across the projection horizon incorporated service type, application, end user, and storage method dimensions with geographic regulatory cluster overlays. CAGRs were derived from historical enrollment trajectories and pipeline-stage cellular therapy demand projections. Cryopreservation viability benchmarks and FDA licensure status served as industry-specific forecast inputs shaping revenue recognition timing.
The model holds under stable FDA regulatory frameworks and continued liquid nitrogen supply availability; deviation in cord blood indication approvals or industrial gas supply disruptions would shift inventory valuation assumptions. A small set of named triggers warrants ongoing watch: FDA expanded indication decisions, REACH cryoprotectant regulatory amendments, and Southeast Asian cold chain infrastructure development milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Cellular Immunotherapy Market