
 Global Ornithine-Transcarbamylase Deficiency Market | 2026-2036
Global Ornithine-Transcarbamylase Deficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ornithine-Transcarbamylase Deficiency Market Foresight
Specialty clinics are redrawing demand patterns in ornithine-transcarbamylase deficiency care, pulling volume from general hospital settings toward dedicated metabolic centers. Ultragenyx Pharmaceutical Inc. leverages its rare disease infrastructure to sustain geographic dominance in enzyme replacement access. Zevra Therapeutics competes through pipeline specialization in small-molecule urea cycle modulators. Abbott Laboratories anchors the nutritional management segment with medical food formulations for hyperammonemia prevention.
Ornithine-transcarbamylase deficiency denotes an X-linked genetic disorder impairing the urea cycle enzyme that catalyzes carbamoyl phosphate and ornithine into citrulline, resulting in toxic ammonia accumulation requiring lifelong nitrogen-scavenging intervention. The condition demands acute hyperammonemia management through intravenous sodium phenylbutyrate or glycerol phenylbutyrate, plus chronic protein-restricted nutrition with essential amino acid supplementation. Enzyme replacement therapies currently dominate commercial value while gene therapy approaches represent the fastest-expanding development category, with multiple AAV-vector candidates in late-stage trials. Nutritional supplements constitute a mature, volume-driven segment where margin pools concentrate in insurance-reimbursed medical foods rather than over-the-counter formulations.
The FDA's orphan drug program and EMA's PRIME designation for rare diseases accelerate clinical development timelines and extend market exclusivity protections for qualified therapies. Japan's PMDA operates a distinct sakigake review pathway that grants priority consultation to urea cycle disorder innovators, compressing pre-market regulatory phases. China's NMPA has expanded conditional approval mechanisms for ultra-rare metabolic conditions, broadening patient access ahead of full confirmatory data. Stakeholders must monitor how evolving gene therapy reimbursement frameworks in Germany and France reshape pricing negotiations for one-time curative interventions against chronic enzyme replacement economics.
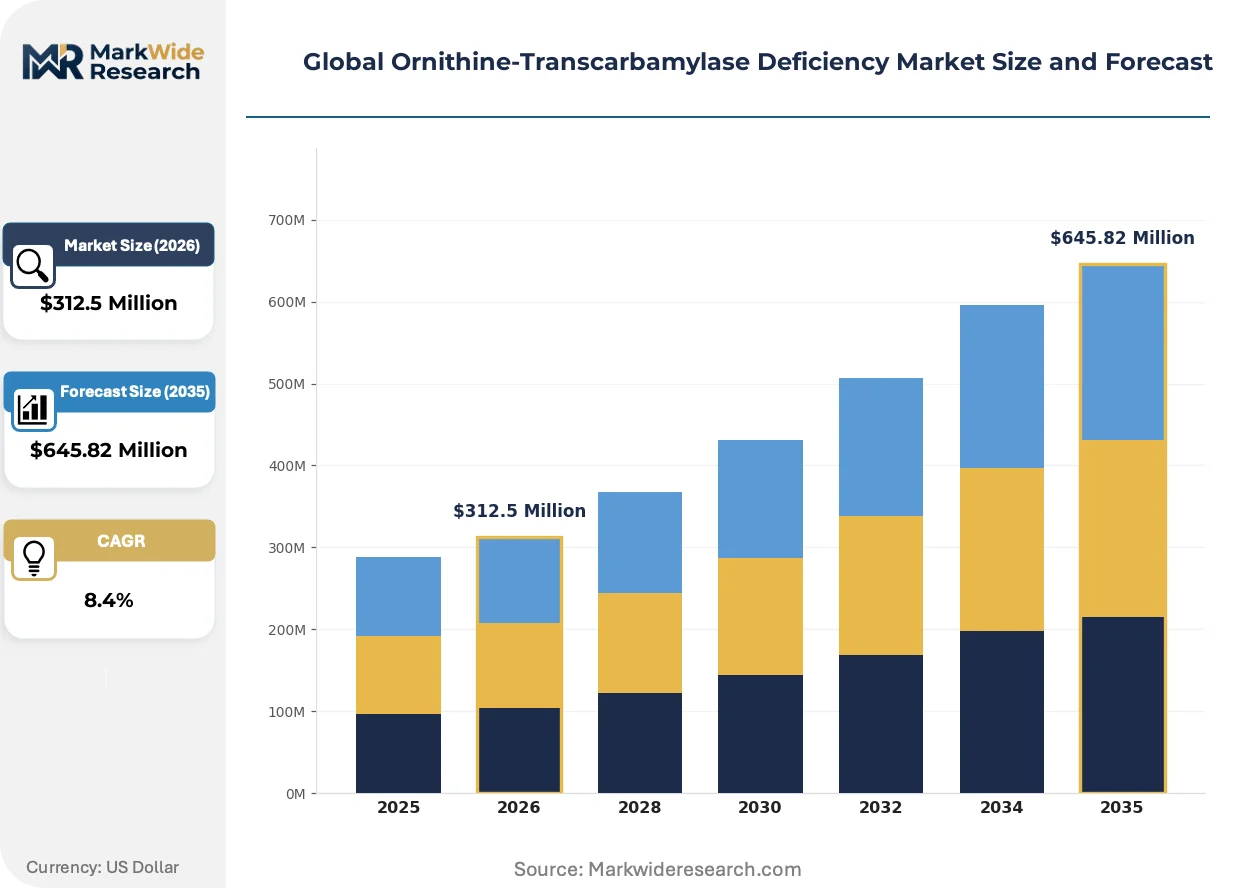
Market Dynamics
Gene therapy pipelines are compressing commercial timelines for chronic enzyme replacement therapies, forcing incumbents to reposition around acute hyperammonemia management while AAV-vector candidates advance through regulatory review.
Growth Catalysts
- EMA Accelerated Assessment Pathway:Rare disease developers gain compressed review timelines and extended market exclusivity, incentivizing orphan drug investment across European metabolic centers.
- Japan's Sakigake Review System:Priority consultation access grants urea cycle disorder innovators earlier regulatory engagement, shortening pre-market phases for novel nitrogen-scavenging agents.
- Newborn Screening Expansion:State-level program adoption in the United States and Germany drives presymptomatic patient identification, expanding addressable populations for early intervention protocols.
Market Restraints
- AAV Manufacturing Bottlenecks:Viral vector production capacity concentrates at limited contract manufacturing organizations, constraining gene therapy supply scalability.
- Reimbursement Uncertainty for Curative Therapies:Germany's gene therapy pricing frameworks remain unresolved, complicating value demonstration for one-time interventions against chronic treatment economics.
- Protein-Restricted Diet Adherence:Patient compliance variability limits therapeutic efficacy of nutritional management protocols, creating residual hyperammonemia risk.
Strategic Opportunities
- China's Conditional Approval Expansion:NMPA mechanisms for ultra-rare metabolic conditions enable earlier patient access ahead of full confirmatory data, opening commercial pathways.
- Telemedicine Integration:Remote metabolic monitoring platforms connect dispersed patients to specialized urea cycle disorder centers, reducing geographic access barriers.
- Biomarker-Guided Dosing:Real-time ammonia monitoring technologies enable personalized nitrogen-scavenger titration, differentiating next-generation chronic management offerings.
Industry Challenges
- Gene Therapy Vector Immunogenicity:Pre-existing neutralizing antibodies in patient populations complicate AAV-based candidate enrollment and durable efficacy.
- Cross-Border Care Coordination:Fragmented metabolic center networks across the United States, Germany, and Japan create inconsistent acute crisis management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ornithine-Transcarbamylase Deficiency Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement, Gene Therapy, Nutritional Supplements, Diagnostic Kits, Others Therapy Area: Metabolic Disorders, Genetic Disorders, Urea Cycle Disorders, Rare Diseases End User: Specialty Clinics, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies Delivery Mode: Oral, Intravenous, Subcutaneous, Inhalation |
| Companies Covered | Ultragenyx Pharmaceutical Inc., Amgen Inc., Zevra Therapeutics, Bausch Health Companies Inc., Danone Group (Nutricia), Abbott Laboratories, Arcturus Therapeutics Inc., Reckitt Benckiser Group (Mead Johnson), Nestlé Health Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ornithine-Transcarbamylase Deficiency Market Shifts & Advancements
AAV-vector engineering and CRISPR-based editing platforms are reconfiguring the therapeutic hierarchy in urea cycle disorders, shifting competitive focus from symptomatic control toward functional cure development.
Next-generation AAV capsid variants with enhanced liver tropism and reduced immunogenicity profiles are fragmenting the gene therapy development landscape. Biopharmaceutical developers are prioritizing these engineered vectors for late-stage OTC deficiency candidates, accelerating transition timelines from chronic enzyme replacement to potential curative modalities. Manufacturing scale-up for these novel capsids remains the binding constraint on commercial readiness.
REACH regulation amendments for advanced therapy medicinal products are tightening environmental release controls for viral vector manufacturing facilities across European production sites. Industrial consequence includes mandatory closed-system bioreactor adoption and expanded waste-stream monitoring protocols. German and French gene therapy developers face the steepest compliance cost escalations as they scale toward commercial batches.
Metabolic center procurement officers are consolidating supplier relationships around integrated care platforms that bundle acute rescue medications, chronic nitrogen scavengers, and nutritional formulations under single-source contracts. Specialty pharmacy distributors are displacing traditional hospital purchasing in the United States as preferred channels for patient home-infusion services. This concentration pattern appears most pronounced in states with mature newborn screening infrastructure and established urea cycle disorder clinical networks.
Global Ornithine-Transcarbamylase Deficiency Market Segmentation
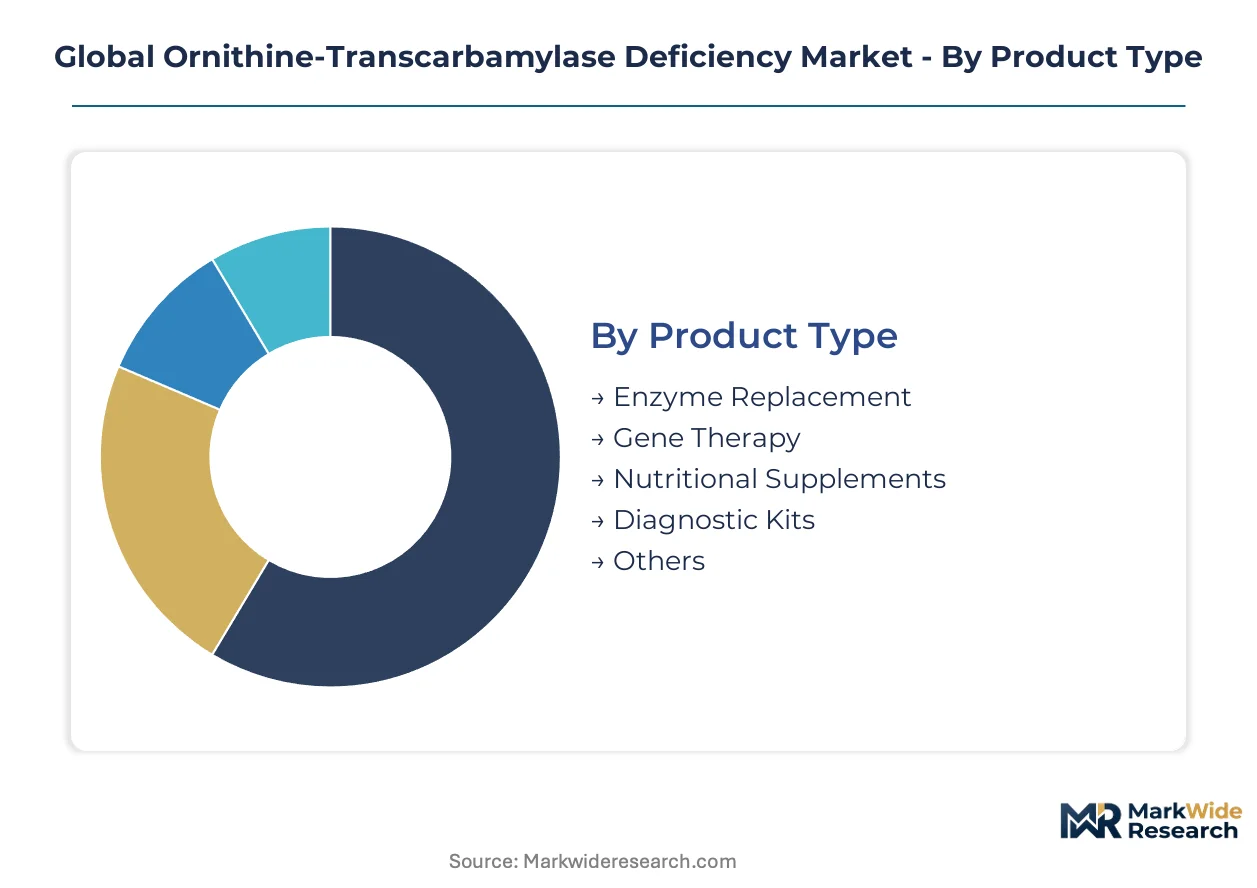
Ornithine-transcarbamylase deficiency treatment spans curative, chronic, and supportive modalities with divergent regulatory pathways and reimbursement economics. Segment boundaries reflect how FDA, EMA, and PMDA orphan frameworks allocate exclusivity premiums across intervention types.
Product Type:
FDA breakthrough therapy and EMA PRIME designations cluster disproportionately in gene therapy pipelines, while nutritional supplements navigate distinct medical food regulatory channels.
- Enzyme Replacement:Recombinant ornithine transcarbamylase formulations administered chronically to compensate for enzymatic deficiency. Demand concentrates in Germany and Japan where statutory health insurance covers biologic maintenance therapy without prior authorization hurdles.
- Gene Therapy:AAV-vector mediated liver-directed gene transfer aiming at functional cure through durable transgene expression. Clinical trial recruitment accelerates in the United States where the FDA's regenerative medicine advanced therapy designation compresses development timelines.
- Nutritional Supplements:Essential amino acid formulations and nitrogen-scavenging medical foods for protein-restricted dietary management.
- Diagnostic Kits:Newborn screening assays and acute hyperammonemia quantification platforms for metabolic emergency detection.
- Others:Adjunctive hepatoprotective agents and experimental RNA-based modulation approaches in preclinical stages.
Established volume favors enzyme replacement; emerging adoption favors gene therapy.
Therapy Area:
Orphan drug incentives reshape competitive intensity across metabolic and genetic disease classifications with varying prevalence thresholds.
- Metabolic Disorders:Broad category encompassing urea cycle dysfunction and intersecting inborn errors of metabolism. Patient identification rates climb fastest in US states with tandem mass spectrometry newborn screening expansion.
- Genetic Disorders:X-linked inheritance pattern drives cascade screening protocols and reproductive counseling demand in Japan's prefectural genetic centers.
- Urea Cycle Disorders:Specific enzymopathy classification triggering specialized metabolic center referral pathways in Germany.
- Rare Diseases:Regulatory umbrella capturing ultra-orphan pricing and extended exclusivity provisions across European markets.
Diagnostic volume concentrates in metabolic disorders; therapeutic innovation investment clusters in rare diseases.
End User:
Care delivery fragmentation between acute crisis management and chronic disease control determines procurement authority distribution.
- Specialty Clinics:Dedicated metabolic centers managing acute hyperammonemia episodes and longitudinal enzyme replacement therapy. Germany's university-affiliated centers command preferred formulary placement through integrated care contracts.
- Diagnostic Laboratories:State newborn screening programs and reference laboratories quantifying plasma ammonia and amino acid profiles. Japanese municipal health authorities drive standardization through centralized proficiency testing mandates.
- Research Institutes:Academic medical centers conducting natural history studies and gene therapy trial enrollment.
- Pharmaceutical Companies:Sponsors of investigator-initiated studies and compassionate access programs for pre-approval candidates.
Revenue concentration favors specialty clinics; trial enrollment growth favors research institutes.
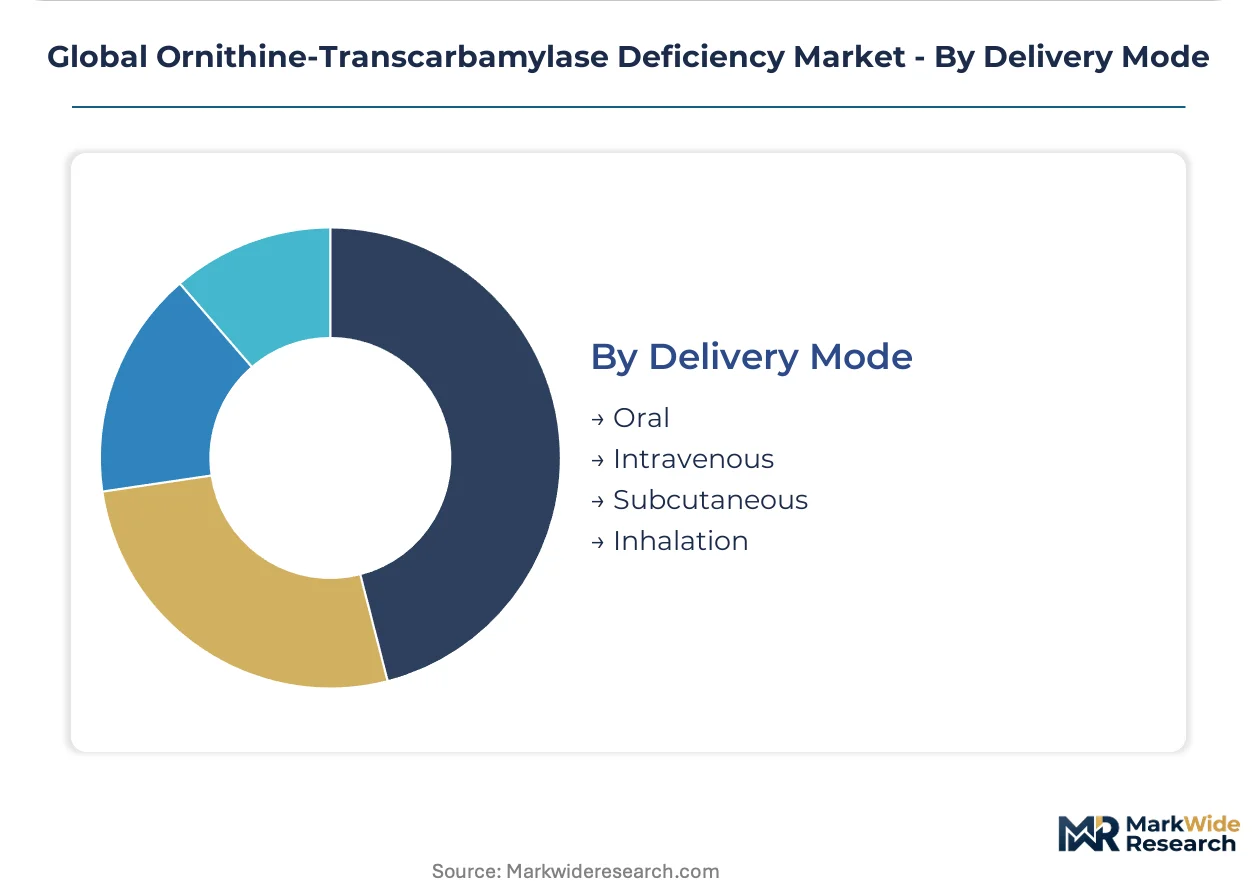
Delivery Mode:
Route selection dictates manufacturing complexity, cold chain requirements, and patient self-administration feasibility.
- Oral:Sodium phenylbutyrate tablets and glycerol phenylbutyrate liquid formulations for chronic nitrogen scavenging. Patient compliance challenges in pediatric populations drive palatability formulation investment in the United States.
- Intravenous:Acute hyperammonemia rescue protocols requiring hospital-based administration. German metabolic centers maintain 24-hour infusion capability through statutory emergency care mandates.
- Subcutaneous:Investigational depot formulations and enzyme replacement candidates in early-phase development.
- Inhalation:Experimental ammonia chelation approaches with limited current clinical application.
Clinical volume dominates intravenous delivery; pipeline expansion favors subcutaneous innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ornithine-Transcarbamylase Deficiency Market concentrates in healthcare systems with mature newborn screening infrastructure and dedicated metabolic disorder centers. The United States, Germany, Japan, United Kingdom, and China anchor commercial activity through distinct regulatory and reimbursement frameworks.
United States
State-level tandem mass spectrometry newborn screening programs drive presymptomatic patient identification in California, New York, and Texas. The FDA's regenerative medicine advanced therapy designation compresses gene therapy development timelines for liver-directed AAV candidates. Boston's academic medical centers anchor clinical trial enrollment through integrated urea cycle disorder networks.
Germany
Statutory health insurance covers biologic maintenance therapy without prior authorization hurdles, expanding enzyme replacement access. The EMA's PRIME designation for rare diseases accelerates regulatory review timelines for qualified metabolic therapies. Munich and Heidelberg university-affiliated metabolic centers command preferred formulary placement through integrated care contracts.
Japan
Prefectural genetic centers drive cascade screening protocols and reproductive counseling demand for X-linked inheritance patterns. The PMDA's sakigake review pathway grants priority consultation access to urea cycle disorder innovators. Tokyo and Osaka metabolic centers concentrate acute hyperammonemia management capacity through municipal health authority mandates.
United Kingdom
NHS England's specialized commissioning framework consolidates rare disease treatment at designated metabolic centers in London, Manchester, and Birmingham. The MHRA operates an early access to medicines scheme for ultra-orphan conditions ahead of full marketing authorization. Cambridge and Oxford research institutes anchor gene therapy natural history studies and trial infrastructure.
China
Provincial maternal and child health hospitals expand newborn screening coverage in Guangdong, Jiangsu, and Zhejiang provinces. The NMPA's conditional approval mechanisms for ultra-rare metabolic conditions enable earlier patient access ahead of confirmatory data. Shanghai and Beijing gene therapy developers scale viral vector manufacturing through state-backed biotechnology parks.
Global Ornithine-Transcarbamylase Deficiency Market Competitive Landscape
Concentration sits with rare disease specialists and diversified pharmaceutical conglomerates competing across enzyme replacement, gene therapy, and nutritional management segments. The vendor base stratifies into three tiers: integrated rare disease platforms with metabolic center contracts, biotech developers advancing AAV-vector candidates, and nutritional formulation suppliers serving protein-restricted diet protocols. Dominant competitive moves include gene therapy pipeline acceleration through regulatory designations and specialty pharmacy distribution partnerships for home-infusion services.
Within the rare disease platform tier, Ultragenyx Pharmaceutical Inc. and Zevra Therapeutics exemplify contrasting strategic positions. Ultragenyx anchors geographic dominance through established metabolic center infrastructure and enzyme replacement access. Zevra occupies a pipeline specialization position in small-molecule urea cycle modulators. Among diversified healthcare conglomerates, Abbott Laboratories represents the nutritional management segment with medical food formulations for hyperammonemia prevention.
| Leading Market Players |
|---|
| Ultragenyx Pharmaceutical Inc. |
| Amgen Inc. |
| Zevra Therapeutics |
| Bausch Health Companies Inc. |
| Danone Group (Nutricia) |
| Abbott Laboratories |
| Arcturus Therapeutics Inc. |
| Reckitt Benckiser Group (Mead Johnson) |
| Nestlé Health Science |
| Others |
Supply & Pricing Matrix
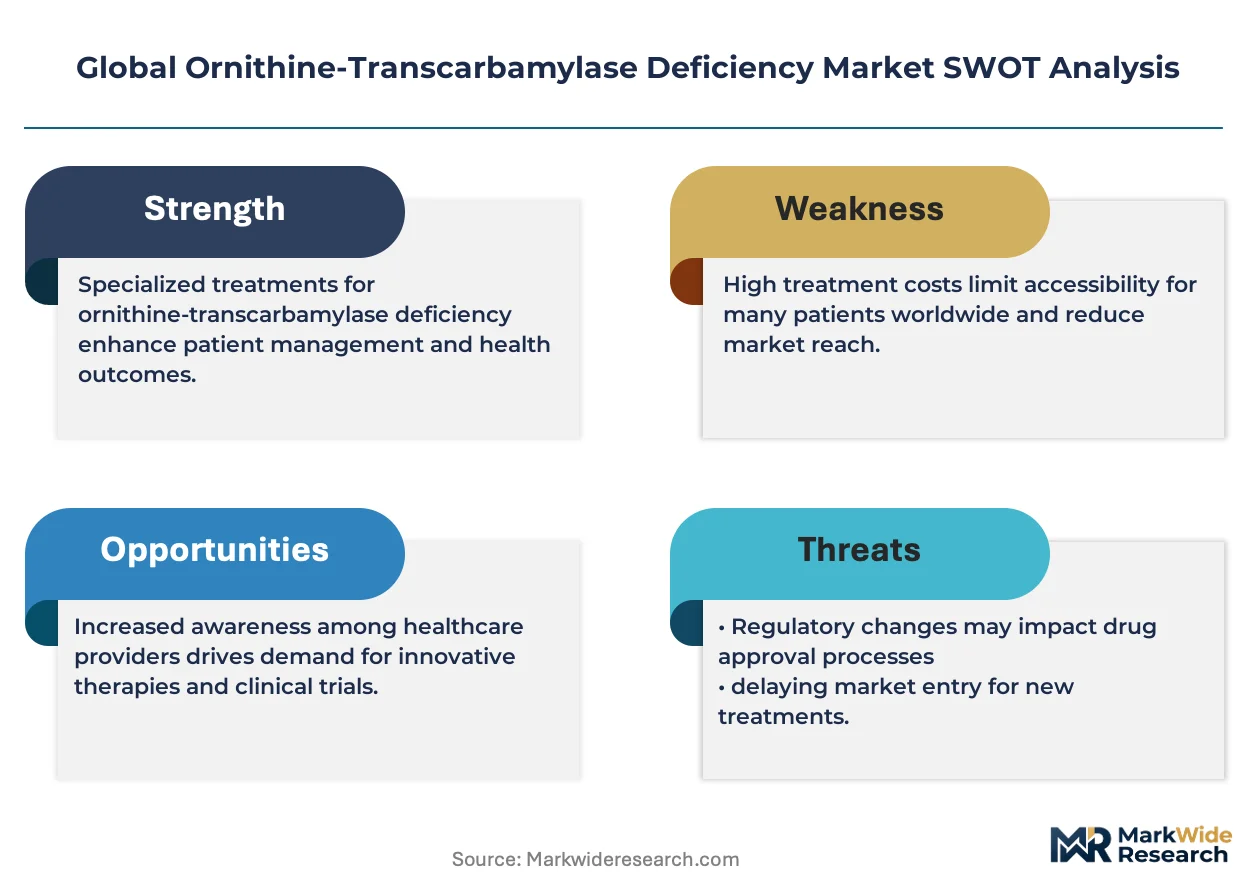
Ninety-day viral vector manufacturing lead times concentrate pricing power among contract manufacturers with validated AAV platforms, compressing margins for gene therapy developers while amplifying procurement leverage for integrated rare disease platforms with captive bioreactor capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts for nitrogen-scavenging agents and medical foods. Price differentiation hinges on FDA orphan drug exclusivity status and volume commitment scale, with statutory health insurance reimbursement floors in Germany and Japan insulating premium tiers from downward pressure. Cost compression in standard-tier enzyme replacement intensifies as biosimilar development programs advance through EMA scientific advice. Pediatric metabolic centers exhibit highest price sensitivity due to constrained formulary budgets, while adult specialty clinics with integrated care contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of recombinant enzyme inventories dominates procurement protocols given acute hyperammonemia mortality risk, displacing just-in-time preferences common in chronic disease categories. Manufacturing concentrates in the United States, Germany, and Switzerland for active pharmaceutical ingredients, with fill-finish operations distributed across Ireland and Singapore. Raw material dependencies include HEK293 cell lines, plasmid DNA templates, and specialized chromatography resins. Single-source vulnerability for AAV vector production strains commercial readiness for gene therapy candidates. Distribution runs through specialty pharmacy channels in the United States and hospital-centric procurement networks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy regulatory acceleration represents a high-growth disruption reshaping competitive economics, with FDA regenerative medicine advanced therapy designations compressing development timelines and forcing incumbent repositioning around acute rescue indications.
For Market Incumbents: Fortify metabolic center contracts through integrated care platform bundling that combines acute rescue medications, chronic nitrogen scavengers, and nutritional formulations under single-source agreements. Expand backward integration into AAV vector manufacturing capacity to offset contract manufacturing organization pricing leverage and secure supply continuity for pipeline candidates. Prioritize certification investment in REACH-compliant closed-system bioreactor infrastructure ahead of European commercial scale-up. For New Entrants and Emerging Players: Anchor in China's provincial maternal and child health hospital networks where NMPA conditional approval mechanisms enable earlier patient access ahead of confirmatory data completion. Target telemedicine-integrated metabolic monitoring platforms as the most penetrable white-space segment, addressing geographic access barriers for dispersed urea cycle disorder patients. Pursue biomarker-guided dosing differentiation as the primary go-to-market angle against established chronic management protocols. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized rare disease infrastructure and dormant gene therapy assets. Long-term viability centers on curative modality transition economics over chronic replacement maintenance. The signal to watch is AAV-vector immunogenicity resolution rates in late-stage trials, which would validate one-time intervention pricing premiums against lifetime treatment cost benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses gene therapy development timelines for liver-directed candidates. |
| Manufacturing Scale-Up | Closed-system bioreactor adoption satisfies REACH amendments for viral vector production across European sites. |
| Pipeline Diversification | Small-molecule urea cycle modulators complement biologic portfolios against gene therapy competitive threat. |
| Hospital System Partnership | Integrated care contracts with German university-affiliated metabolic centers secure preferred formulary placement. |
| Reimbursement Strategy | Outcome-based pricing negotiations with Germany's statutory health insurers validate one-time curative intervention value. |
Research Methodology
Desk research of FDA orphan drug designations, EMA PRIME eligibility assessments, and ClinicalTrials.gov enrollment data preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from SEC 10-K filings, CMS Medicare reimbursement databases, and Japanese municipal health authority screening program reports. Bottom-up patient population estimates triangulated against top-down metabolic center capacity assessments across the United States, Germany, and Japan.
Variance decomposition across therapy modality, patient age segment, and regional regulatory cluster anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by addressable population expansion and pricing trajectory assumptions. Forecast inputs incorporated newborn screening program adoption curves, gene therapy manufacturing capacity build-out schedules, and statutory health insurance reimbursement policy evolution.
Material uncertainties — AAV-vector immunogenicity resolution, gene therapy pricing framework finalization in Germany, and China NMPA conditional approval scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory designation continuity and manufacturing scale-up execution. Revision becomes warranted when pre-existing neutralizing antibody prevalence in patient populations crosses thresholds that materially impair gene therapy candidate enrollment feasibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market