
 Casting and Splinting Market | 2026-2036
Casting and Splinting Market Size, Share, and Industry Trends Forecast 2026-2036
Casting and Splinting Market Intelligence
The replacement of traditional plaster with advanced fiberglass and thermoplastic composites is broadening the range of applications for immobilization devices. BSN Medical GmbH leverages its portfolio in fiberglass casting tapes to serve high-volume hospitals. Stryker Corporation differentiates through its focus on complementary orthopedic and trauma care systems. 3M Company competes on material science innovation, developing proprietary polyurethane resins for its casting products.
Casting and splinting involve the application of rigid or semi-rigid devices to immobilize and support injured limbs, joints, or bones. These products are engineered with a padded liner for skin protection and an outer shell, often a resin-impregnated fabric that hardens upon activation. Within product types, rigid casts made from fiberglass material dominate hospital end-user segments due to superior strength and radiolucency. Thermoplastic splints show significant uptake in clinics for acute injury stabilization and post-operative support.
Medical device regulations, including the FDA's 510(k) pathway in the United States and the EU's Medical Device Regulation (MDR), govern product classification and market clearance. These frameworks mandate stringent testing for biocompatibility and mechanical strength, directly influencing material selection and manufacturing processes. Future material development will need to balance clinical performance requirements with increasing institutional pressure for sustainable and recyclable product components.
Market Dynamics
The central force shaping the market is the bifurcation of material science. One path pursues higher-performance composites for clinical superiority, while another explores sustainable and cost-effective materials to address institutional purchasing pressures and environmental mandates, creating distinct innovation tracks.
Growth Catalysts
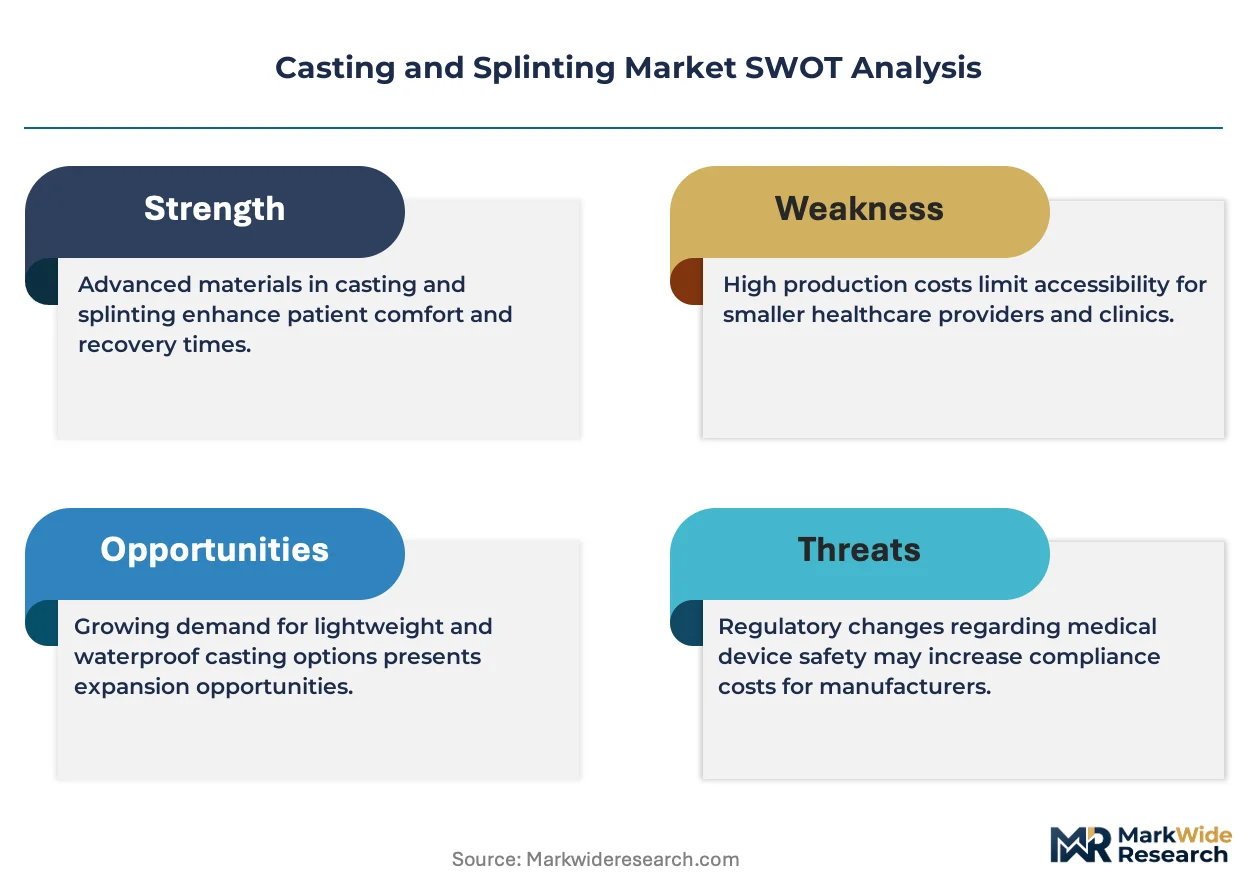
- Advanced Composite Materials:The adoption of breathable fiberglass and semi-rigid composites enhances patient comfort and clinical outcomes by reducing skin complications. This drives use in high-value settings like sports medicine clinics and pediatric orthopedics.
- Geriatric Population Growth:An expanding elderly demographic in developed countries, including Germany and Japan, leads to a higher incidence of fractures from falls and osteoporosis, sustaining baseline demand for immobilization products in hospitals and long-term care facilities.
- Surgical Volume Expansion:Rising rates of orthopedic procedures, from trauma surgeries to elective joint replacements, directly increase the consumption of post-operative splints and casts for stabilization and support, particularly in the United States.
Market Restraints
- Cost Containment Pressures:Healthcare providers, especially in public systems and emerging economies, face pressure to control costs. The higher price of advanced fiberglass and thermoplastic materials compared to traditional plaster of Paris can limit their widespread adoption.
- Regulatory Scrutiny:Stringent regulatory frameworks, such as the FDA's 510(k) clearance process and the EU's Medical Device Regulation (MDR), impose significant costs and long timelines for product validation and market entry, acting as a barrier for new innovators.
- Alternative Treatment Modalities:For certain sprains and minor fractures, orthopedic soft goods, functional braces, and kinesiology taping present viable clinical alternatives. This substitution threat can cap demand for rigid immobilization devices in specific injury categories.
Strategic Opportunities
- Customization with 3D Printing:Additive manufacturing offers the potential to create patient-specific, lightweight, and ventilated casts. This technology provides an opportunity for premium-priced devices tailored to complex anatomical needs and improved patient quality of life.
- Biodegradable Materials:Developing casting tapes from recyclable or biodegradable polymers addresses growing institutional demand for sustainable medical supplies. This aligns with environmental initiatives like the EU Green Deal and can create a key point of differentiation.
- Emerging Market Penetration:Untapped demand exists in Latin American and Southeast Asian nations where healthcare infrastructure is improving. Expanding distribution networks in countries like Brazil and India offers significant volume growth potential as advanced orthopedic care becomes more accessible.
Industry Challenges
- Clinical Training Requirements:The proper application of modern thermoplastic splints and polyester casting systems requires specific techniques that differ from plaster. A lack of standardized training can lead to improper application, suboptimal patient outcomes, and clinician resistance to adoption.
- Raw Material Dependency:The supply chain for casting products relies on a concentrated group of specialized chemical companies that produce polyurethane resins and fiberglass yarns. This dependency creates vulnerability to price volatility and supply disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casting and Splinting Market |
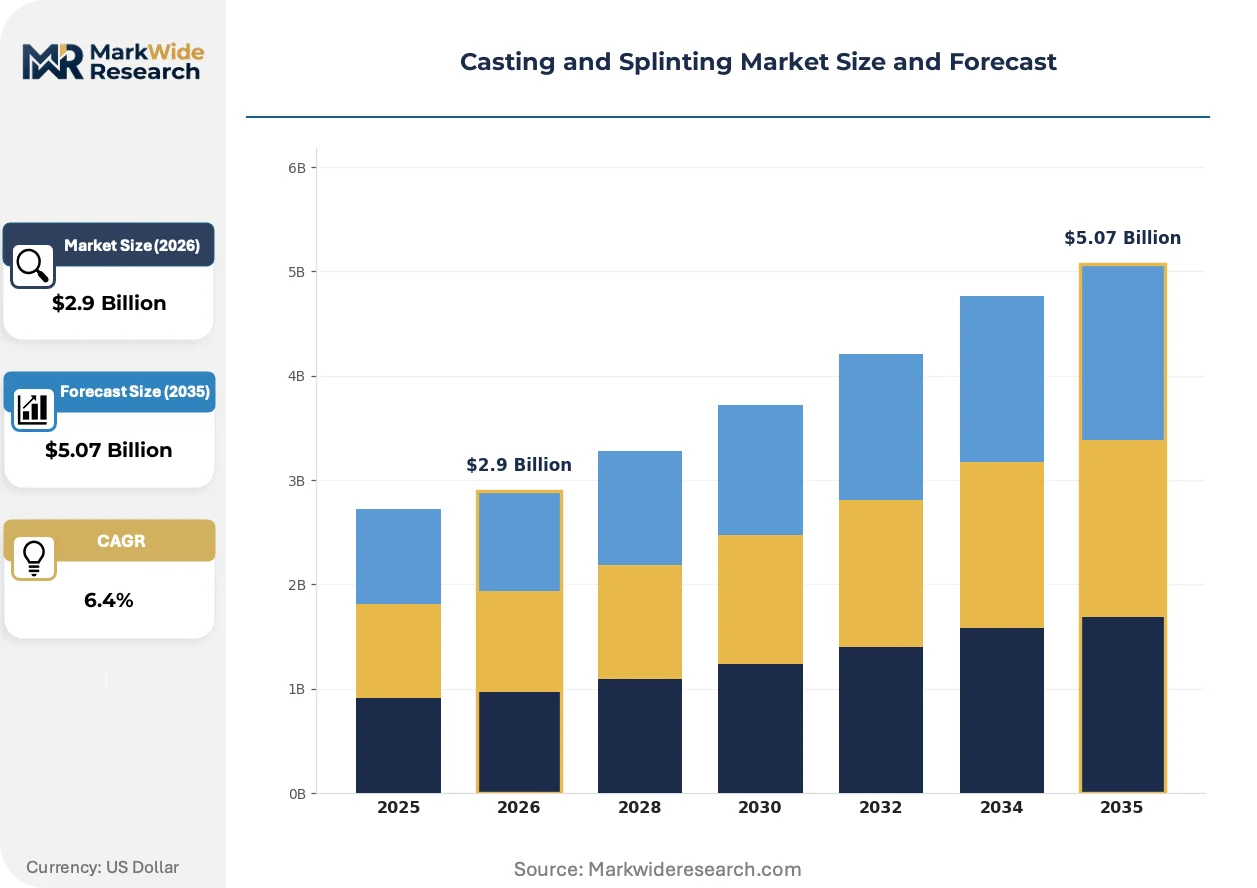
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Casts, Soft Casts, Splints, Orthopedic Braces Material: Fiberglass, Plaster, Thermoplastics, Polyurethane End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Settings Distribution Channel: Online Sales, Retail Pharmacies, Direct Sales, Medical Supply Distributors |
| Companies Covered | Zimmer Biomet Holdings, Inc., DJO Global, Inc., 3M Company, Össur hf., DeRoyal Industries, Inc., BSN Medical GmbH, Essity AB, AliMed, Inc., Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casting and Splinting Market Strategic Shifts & Innovations
Material science advancements are pushing immobilization devices beyond simple structural support. Innovations focus on improving the patient experience through enhanced breathability and reduced weight, while also addressing clinical needs for radiolucency and conformability during application.
Thermoplastic splinting systems provide pre-cut, moldable sheets that can be quickly formed to a patient's limb. Outpatient clinics and emergency departments are rapidly adopting these materials for acute injury stabilization due to their speed and reusability. This trend is modularizing post-operative recovery protocols, enabling clinicians to create adjustable or removable supports that adapt to changes in swelling without a full recast.
The European Union's Medical Device Regulation (MDR) is a significant policy shift impacting the market. It imposes stricter requirements for clinical evidence, risk management, and post-market surveillance across all device classes. Manufacturers of fiberglass and synthetic casting tapes are most affected, as they must now generate more extensive data to prove safety and performance to maintain their CE marking for market access in Europe.
A preference for vendor consolidation is altering purchasing behavior within large hospital networks and Group Purchasing Organizations (GPOs). These powerful buyers are reducing their number of suppliers, favoring companies that offer a complete portfolio of orthopedic trauma products, from internal fixation to external supports. This shift challenges niche casting and splinting specialists and is most prominent within the highly consolidated United States healthcare system.
Casting and Splinting Market Segmentation
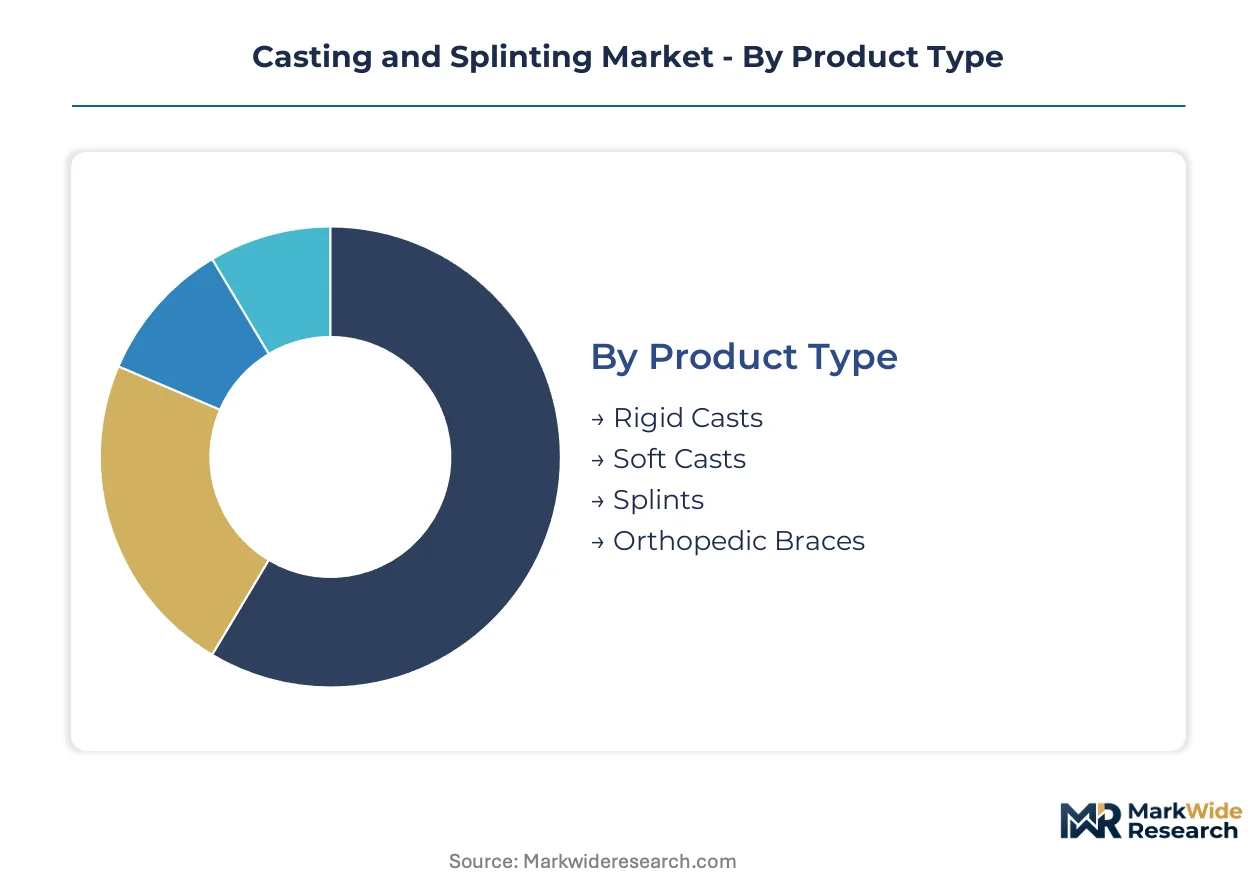
The segmentation of the Casting and Splinting Market provides a granular view of product evolution and demand drivers across diverse healthcare environments. Understanding these distinct categories helps manufacturers align product development with specific clinical needs and procurement strategies. This breakdown also highlights areas where innovation in materials and delivery methods is most impactful.
Product Type:
The product type segmentation highlights the trade-off between immobilization effectiveness and patient comfort, influencing procurement decisions across clinical settings.
- Rigid Casts:These immobilization devices are typically made from fiberglass or plaster, providing maximum support and stabilization for severe fractures. Hospitals are the primary end-users, valuing their superior strength and radiolucency for orthopedic trauma cases.
- Soft Casts:Designed for less severe injuries or as a transition from rigid casts, soft casts offer flexible support and greater patient mobility. Clinics and rehabilitation centers utilize these for conditions requiring moderate immobilization and gradual return to function.
- Splints:These semi-rigid devices, often thermoplastic, are used for acute injury stabilization, post-operative support, and conditions requiring adjustable immobilization. Outpatient clinics and emergency departments frequently adopt splints for their quick application and reusability, adapting to changes in swelling.
- Orthopedic Braces:Braces provide external support for joints or limbs, often used for rehabilitation, post-operative care, or to manage chronic conditions. Rehabilitation centers and home care settings represent significant demand for these adjustable and often reusable devices.
Today's leader: Rigid Casts. Tomorrow's challenger: Splints.
Material:
Material choices reflect a spectrum of cost, performance, and application specificity, with advanced composites offering distinct advantages.
- Fiberglass:This material forms lightweight, strong, and radiolucent casts that harden quickly, improving patient comfort and diagnostic capabilities. Hospitals and sports medicine clinics prioritize fiberglass for its clinical superiority and reduced complication rates.
- Plaster:Traditional plaster of Paris remains a cost-effective option for immobilization, particularly in public healthcare systems and emerging economies. Its ease of application and moldability continue to secure its use despite longer drying times.
- Thermoplastics:These materials become pliable when heated and rigid when cooled, allowing for custom-molded splints that are often reusable and adjustable. Clinics and rehabilitation centers value thermoplastics for their versatility in acute and post-operative care.
- Polyurethane:Primarily used as a resin in fiberglass casting tapes, polyurethane provides the hardening agent that gives casts their structural integrity. 3M Company differentiates its products through proprietary polyurethane resin formulations.
Fiberglass materials maintain dominant share, while thermoplastics show the steepest expansion trajectory.
End User:
End-user segments delineate distinct purchasing behaviors and clinical requirements, from high-volume hospital settings to personalized home care.
- Hospitals:These institutions represent the largest end-user segment, driven by high volumes of orthopedic surgeries and trauma cases requiring rigid immobilization. Procurement focuses on bulk purchasing and comprehensive product portfolios from major suppliers like BSN Medical GmbH.
- Clinics:Outpatient clinics, including urgent care and specialized orthopedic clinics, utilize splints and soft casts for acute injury stabilization and follow-up care. Speed of application and reusability are key factors in their material selection.
- Rehabilitation Centers:These facilities focus on patient recovery and functional improvement, driving demand for adjustable splints, soft casts, and orthopedic braces. Sports medicine and geriatric care are significant sub-segments within rehabilitation.
- Home Care Settings:As healthcare shifts towards community-based care, home care settings increasingly require user-friendly splints and braces for patient self-management and convenience. Ease of application and comfort are critical considerations.
Hospitals remain the primary revenue source, with rehabilitation centers gaining share through specialized care.
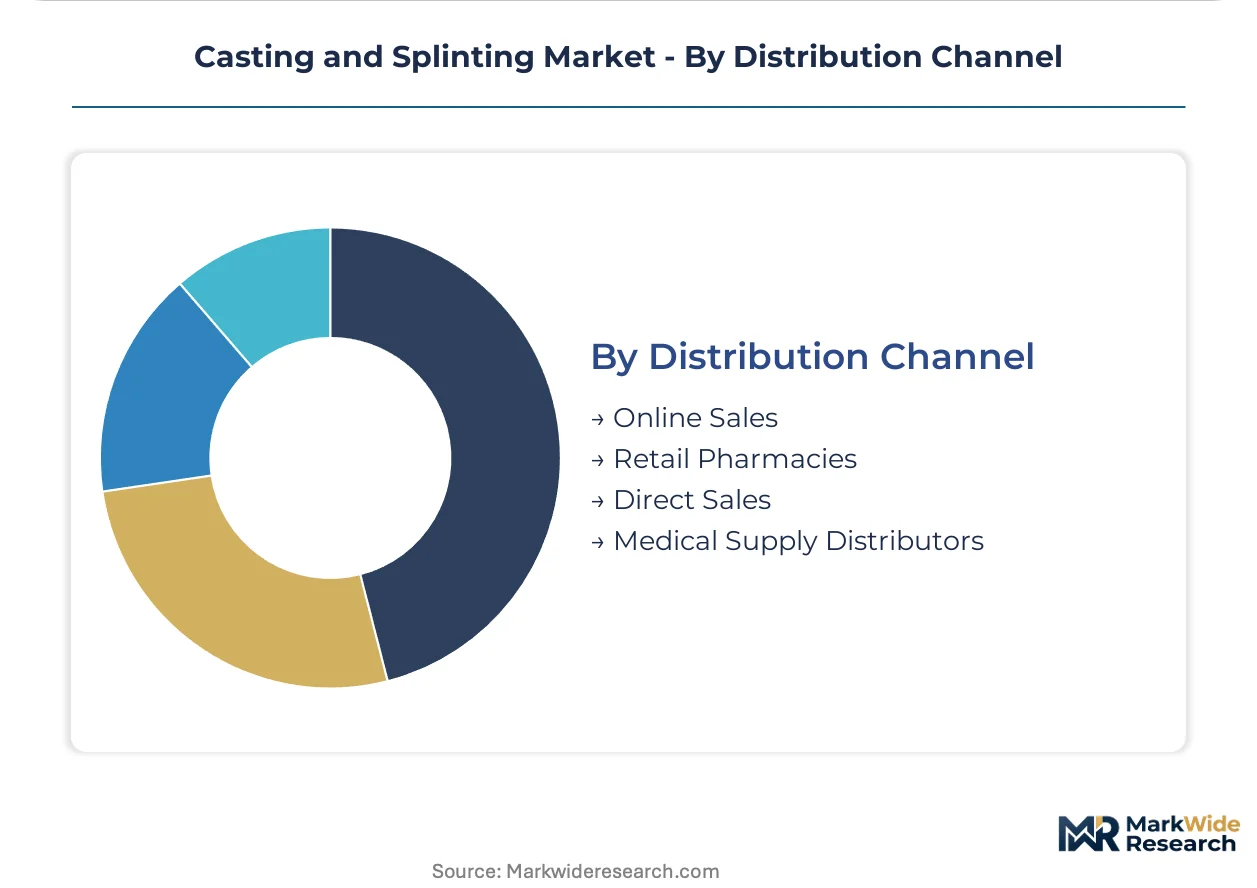
Distribution Channel:
Distribution channels illustrate the evolving landscape of medical device procurement, balancing traditional sales with digital accessibility.
- Online Sales:E-commerce platforms provide convenience and a broader product selection for individual consumers and smaller clinics, particularly for less complex orthopedic supports. This channel is expanding as digital procurement becomes more common.
- Retail Pharmacies:Pharmacies offer over-the-counter options for minor injuries and post-operative support, catering to immediate patient needs. They typically stock a range of soft casts and basic splints.
- Direct Sales:Manufacturers engage in direct sales to large hospital networks and Group Purchasing Organizations (GPOs), facilitating bulk orders and specialized product training. This channel allows for direct negotiation and relationship building.
- Medical Supply Distributors:These distributors serve as intermediaries, providing a crucial link between manufacturers and a wide range of healthcare providers, including hospitals, clinics, and home care agencies. They manage logistics and inventory for diverse product lines.
Medical Supply Distributors secure the largest portion of sales, with online platforms expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York's dense healthcare networks, alongside other advanced infrastructure, drive significant demand for casting and splinting products. The market's regional dynamics reflect advanced healthcare systems, aging demographics, and evolving regulatory landscapes. These factors influence material adoption and procurement strategies across different geographies.
United States
Demand for immobilization devices in the United States is propelled by high rates of orthopedic surgeries and a focus on advanced patient care. The FDA's 510(k) pathway mandates stringent product testing for market clearance. Major medical hubs like those in Boston, Massachusetts, concentrate innovation in orthopedic device development and clinical trials.
Germany
Germany's robust healthcare infrastructure and expanding geriatric population sustain a consistent need for casting and splinting solutions. The EU's Medical Device Regulation (MDR) imposes strict requirements for clinical evidence and post-market surveillance. Research clusters in Munich, Bavaria, actively contribute to material science advancements for medical applications.
Japan
An aging demographic in Japan significantly contributes to the baseline demand for immobilization products due to increased fracture incidence. Japan's PMDA ensures rigorous safety and efficacy standards for medical devices. Tokyo's advanced medical facilities are early adopters of innovative splinting systems and patient-centric designs.
China
China's improving healthcare infrastructure and expanding access to orthopedic care are driving volume growth for casting and splinting products. The NMPA regulates medical device approval, focusing on local manufacturing and quality control. Cities like Shanghai are developing specialized orthopedic hospitals that increase the consumption of advanced materials.
Brazil
Brazil's growing middle class and increasing investment in healthcare infrastructure present opportunities for market expansion in Latin America. ANVISA oversees medical device registration and compliance within the country. São Paulo's private hospital networks are adopting more sophisticated immobilization techniques, expanding demand for modern splints.
Casting and Splinting Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution network reach, creating a dynamic competitive environment. The market exhibits a tiered structure, with large diversified healthcare companies alongside specialized orthopedic device manufacturers. Strategic archetypes include material science innovators, comprehensive portfolio providers, and cost-effective solution developers. Dominant competitive moves involve strategic partnerships to expand product offerings, geographic expansion into high-growth emerging markets, and targeted acquisitions to consolidate technology.
On the premium-tier vector, 3M Company exemplifies material science innovation, focusing on proprietary polyurethane resins for its advanced casting products. BSN Medical GmbH sits within the high-volume hospital segment, leveraging its extensive portfolio in fiberglass casting tapes and broad distribution. Stryker Corporation anchors the market through its focus on complementary orthopedic and trauma care systems, providing integrated solutions for complex injury management. These established players represent significant market presence and specialized offerings across diverse clinical settings.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings, Inc. |
| DJO Global, Inc. |
| 3M Company |
| Össur hf. |
| DeRoyal Industries, Inc. |
| BSN Medical GmbH |
| Essity AB |
| AliMed, Inc. |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Proper application of modern casting systems requires specific clinical training, particularly in regions like the United States and Germany. This specialized workforce concentration influences labor costs, which in turn affects the pricing tiers for advanced immobilization devices, creating a spread between high-skill and basic application services.
Pricing Analysis
Input-cost pass-through for specialized polyurethane resins and fiberglass yarns directly impacts pricing for advanced casting tapes. The market primarily uses a contract-based long-term offtake model for hospitals, with per-unit transactional pricing for clinics. Quality grade (e.g., radiolucency, breathability) and after-sales service (training support) drive differentiation. Cost compression in public healthcare systems is intensifying due to budget constraints. Clinics and home care settings are most price-sensitive, while large hospital networks prioritize performance over cost.
Supply Chain Analysis
Polyurethane resin supply rests heavily on a concentrated group of specialized chemical companies primarily based in Germany and the United States. The supply chain relies on fiberglass yarns and proprietary polyurethane formulations. Key manufacturing centers for these inputs are found in Germany, the United States, and increasingly China for basic components. Commodity price volatility for chemical precursors represents a significant structural risk. Medical supply distributors form the dominant downstream structure, managing logistics for a wide range of healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Casting and Splinting Market presents a geographic-arbitrage play, leveraging cost-effective manufacturing in regions like China against premium market demand in advanced healthcare systems such as the United States, driven by differing regulatory scrutiny levels.
For Market Incumbents: Deploy comprehensive portfolio integration to counter niche specialists and maintain market share against alternative treatment modalities. Invest in advanced material science R&D for proprietary polyurethane resins to differentiate products and meet stringent regulatory frameworks like the EU MDR. Expand training programs for clinicians to ensure proper application of complex systems, mitigating adoption resistance. This strategy defends against cost containment pressures from GPOs and hospital networks.
For New Entrants and Emerging Players: Additive manufacturing capabilities offer a technology-first wedge into the premium segment for patient-specific, lightweight, and ventilated casts. Target underpenetrated rehabilitation centers with customizable thermoplastic splints for post-operative support and chronic conditions. A go-to-market angle focusing on improved patient comfort and faster recovery can attract early adopters in private clinics. This strategy leverages unmet needs for personalized orthopedic solutions.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized material science innovators developing biodegradable polymers, offering long-term growth potential over a 5-10 year window. Target acquisition archetypes include companies with proprietary manufacturing processes for advanced composites or strong intellectual property in 3D printing for orthotics. The signal to watch is an increase in institutional mandates for sustainable medical supplies, indicating broader market acceptance. These investments align with evolving environmental and clinical performance demands.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Biodegradable Material R&D | Addresses EU Green Deal mandates and creates differentiation for Essity AB. |
| Expand 3D Printing Customization Services | Offers premium-priced devices for complex anatomical needs, enhancing patient quality of life. |
| Deepen Hospital System Partnerships | Secures high-volume contracts and strengthens distribution for BSN Medical GmbH. |
| Pursue Emerging Market Distribution | Unlocks significant volume growth potential in Brazil and India for Stryker Corporation. |
| Enhance Clinician Training Programs | Improves proper application of modern thermoplastic systems, boosting adoption rates. |
Research Approach
Direct dialogue with orthopedic surgeons, hospital procurement managers, biomedical engineers, and rehabilitation therapists grounded the qualitative insights. Secondary validation involved reviewing FDA 510(k) clearances, EU MDR documentation, GPO purchasing contracts, and specialized medical device publications. This approach combined bottom-up market intelligence with top-down industry analysis, ensuring comprehensive data triangulation.
The quantitative model generated volume and value projections across the analysis window, segmented by product type, material, end-user, and distribution channel. CAGRs were derived through historical trend analysis and future growth drivers, incorporating orthopedic surgery rates and geriatric population shifts. Forecast inputs included healthcare expenditure data and material innovation timelines for polyurethane resins.
The model holds under current regulatory stability and material supply chain continuity; deviation in major policy shifts like new EU MDR amendments or significant raw material price spikes would shift projections. Forecasts reflect assumptions regarding healthcare infrastructure development and orthopedic surgery trends. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryotubes Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
United States Intravenous Solutions Market