
 Radiolucent Wrist Fixator Market | 2026-2036
Radiolucent Wrist Fixator Market Size, Share, and Industry Trends Forecast 2026-2036
Radiolucent Wrist Fixator Market Analytics
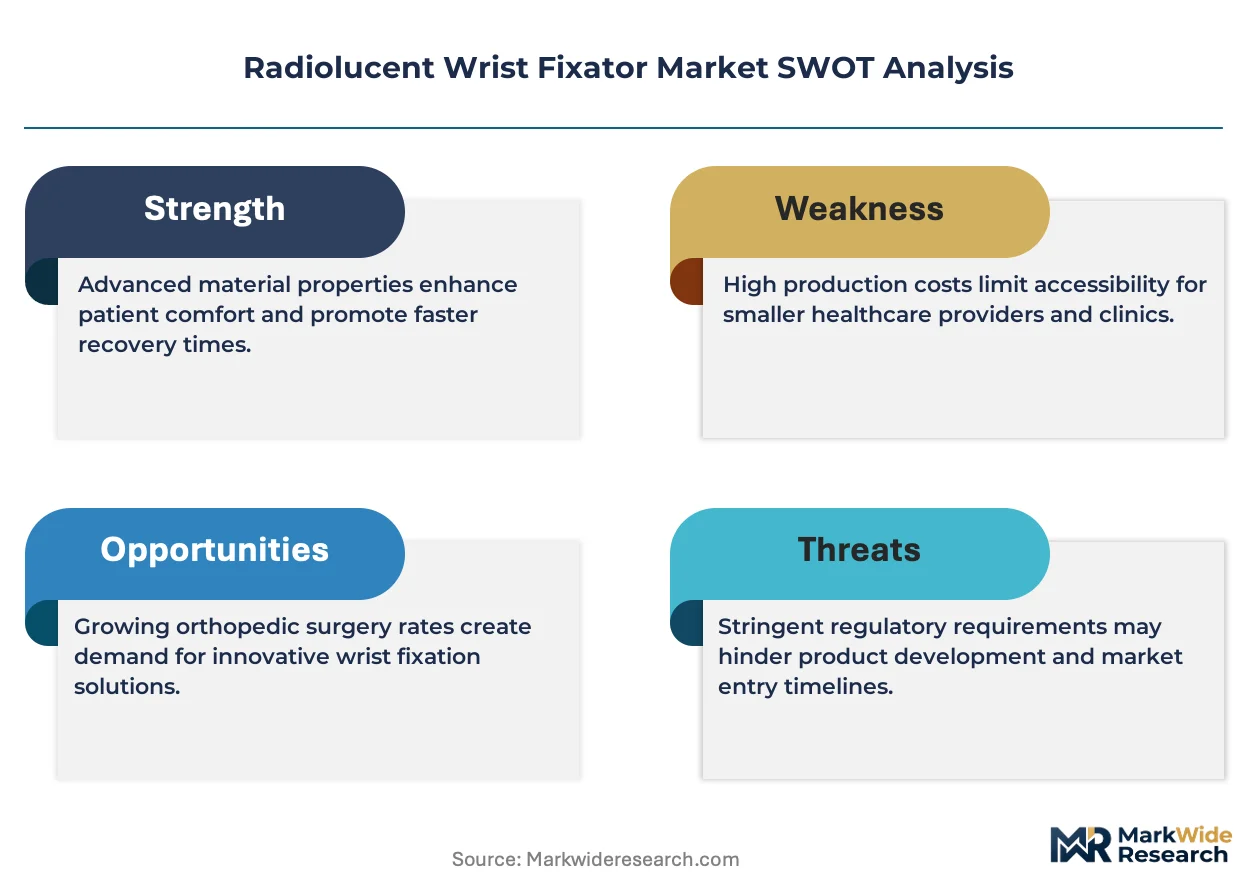
The EU Medical Device Regulation is realigning material disclosure and biocompatibility requirements for radiolucent orthopedic hardware, compelling manufacturers to reformulate composite fixators. Stryker Corporation leverages its trauma division scale to sustain broad hospital contracting across North American and European markets. Smith & Nephew plc anchors its competitive stance through specialized carbon-fiber fixation platforms that optimize intraoperative imaging clarity. Orthofix Medical Inc. differentiates via concentrated R&D investment in patient-specific external fixation geometries.
A radiolucent wrist fixator is an orthopedic stabilization device engineered from carbon-fiber-reinforced polymers, PEEK, or other radiotransparent composites that permit unobstructed X-ray and CT visualization during fracture reduction and healing monitoring. These devices typically achieve tensile strengths exceeding 1,500 MPa while maintaining complete radiographic transparency, enabling real-time surgical guidance without hardware removal. External Fixator systems dominate current revenue flows due to established trauma protocols and reusable frame economics, though Stabilization Frame configurations represent the fastest-expanding category as ambulatory surgical centers adopt lighter single-use alternatives. Bone Plate segments retain mature margin pools in developed markets where inpatient surgical volumes persist, while Intramedullary Nail applications concentrate in academic medical centers with advanced arthroscopic capabilities.
The FDA governs radiolucent fixators through Class II medical device pathways requiring 510(k) substantial equivalence demonstrations, while the EU MDR mandates updated clinical evidence and notified body recertification for legacy products. Japan's PMDA enforces distinct biocompatibility testing protocols under JIS T 0301 that influence composite material selection for Asia-Pacific market entry. Stakeholders must monitor evolving notified body capacity constraints in Europe and anticipate FDA guidance on patient-matched fixation manufacturing to preserve competitive positioning.
Market Dynamics
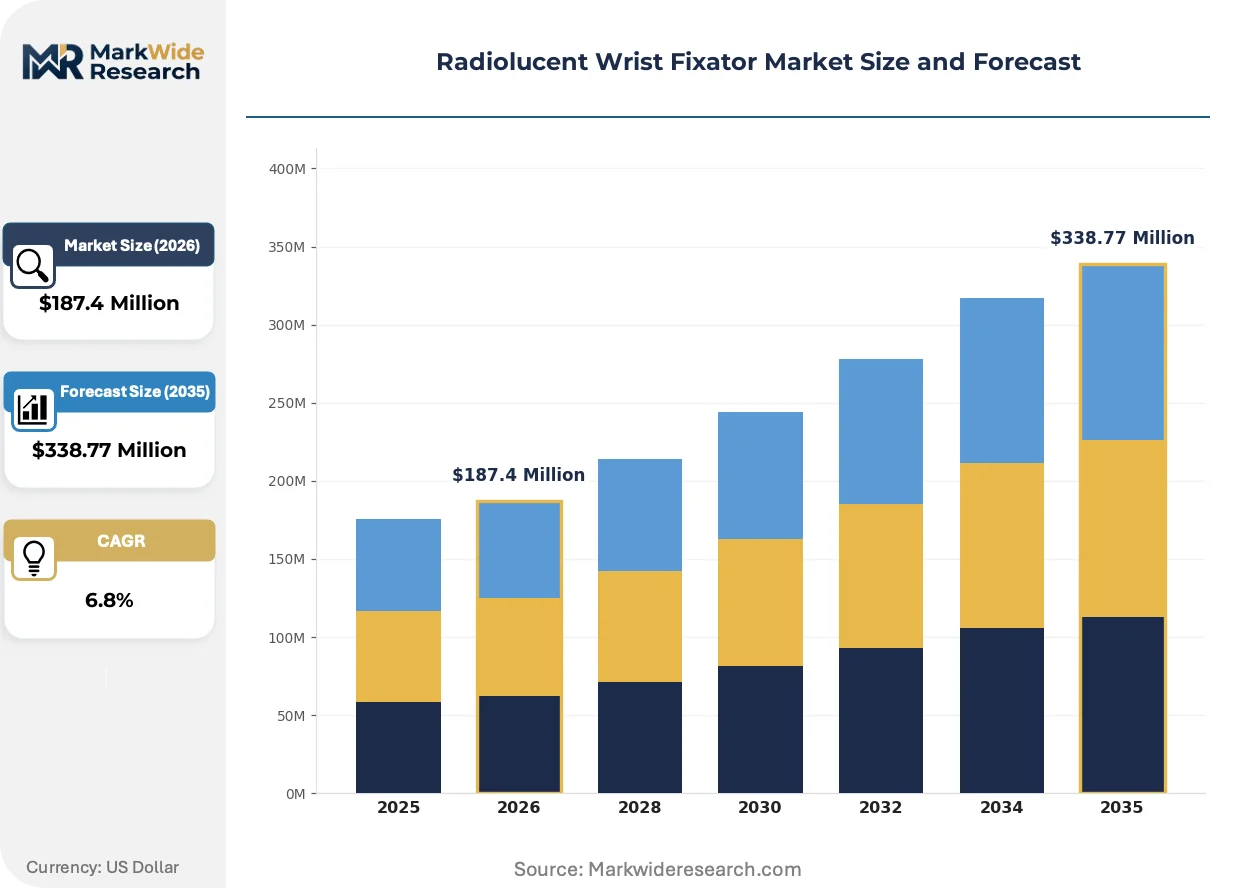
The EU Medical Device Regulation's material disclosure mandates are forcing composite reformulation across radiolucent fixation manufacturing, while trauma centers in Germany, the United States, and Japan simultaneously expand premium hardware procurement. This dual pressure—regulatory compliance on one flank, clinical upgrade cycles on the other—defines current competitive maneuvering.
Growth Catalysts
- EU MDR material transparency mandates:The regulation compels manufacturers to document biocompatibility profiles for carbon-fiber-reinforced polymers, accelerating R&D investment in next-generation composites that satisfy notified body scrutiny.
- Carbon-fiber imaging optimization:Trauma surgeons in academic medical centers now prioritize intraoperative CT clarity, creating pull-through demand for PEEK-based stabilization frames that eliminate metal artifact interference.
- Ambulatory surgical center expansion:United States outpatient facilities are adopting single-use external fixator configurations to streamline turnover economics and reduce sterilization infrastructure.
Market Restraints
- PEEK resin supply concentration:Specialty polymer production clusters in Western Europe, exposing manufacturers to feedstock volatility and extended lead times during regional energy disruptions.
- Notified body capacity constraints:EU MDR recertification backlogs delay legacy product market access, compressing revenue recognition timelines for established fixator portfolios.
- Reusable metal fixator substitution:Cost-conscious hospital systems in price-sensitive markets retain stainless steel external fixation systems despite imaging limitations.
Strategic Opportunities
- Japan PMDA pathway optimization:JIS T 0301 biocompatibility testing alignment creates first-mover advantage for composite fixators engineered to Asia-Pacific protocol specifications.
- Patient-matched geometry adoption:3D-printed fixation frames derived from preoperative imaging are penetrating German trauma centers, enabling premium pricing for anatomically customized stabilization.
- Integrated imaging-OR workflow convergence:Fixator systems designed for seamless C-arm compatibility are capturing preference in United States hybrid operating suites.
Industry Challenges
- Composite manufacturing talent scarcity:Aerospace-to-medical device engineering migration has thinned the specialist labor pool for carbon-fiber layup and PEEK machining.
- 510(k) substantial equivalence pathway compression:FDA scrutiny of predicate device similarity extends submission preparation cycles for novel radiolucent materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiolucent Wrist Fixator Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Fixator, Intramedullary Nail, Bone Plate, Stabilization Frame End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Application: Fracture Treatment, Surgical Stabilization, Trauma Management, Post-Surgery Care Delivery Mode: Surgical, Outpatient, Inpatient, Emergency Care |
| Companies Covered | Orthofix Medical Inc., Smith & Nephew plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., DePuy Synthes (Johnson & Johnson), Arthrex, Inc., Medartis, Conmed Corporation, Fixus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiolucent Wrist Fixator Market Evolving Landscape
Digital surgical planning and intraoperative navigation are converging to redefine fixation accuracy standards, while regulatory frameworks on both sides of the Atlantic accelerate material disclosure requirements. These forces are compressing product development timelines and elevating composite engineering capabilities as a core differentiator.
Carbon-fiber-reinforced polymer systems with tunable radiolucency profiles are unifying mechanical performance and imaging transparency in single-platform designs. Orthopedic surgical units in German university hospitals are adopting these configurations for complex distal radius reconstructions. The technology is unifying previously separate procurement streams for structural fixation and diagnostic clarity into integrated purchasing decisions.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence updates for legacy radiolucent implants previously cleared under the Medical Device Directive. Manufacturers face notified body re-audit cycles that compress margin structures for mature product lines. Stabilization frame categories bear the heaviest compliance burden due to their higher patient-contact surface area and corresponding biocompatibility scrutiny.
Ambulatory surgical centers in the United States are consolidating vendor relationships around single-source fixator suppliers capable of delivering sterilized, procedure-ready kits. This consolidation displaces traditional hospital-materials-management procurement patterns. The shift is most visible in Florida and Texas outpatient networks where surgical volume growth outpaces infrastructure expansion.
Radiolucent Wrist Fixator Market Segmentation
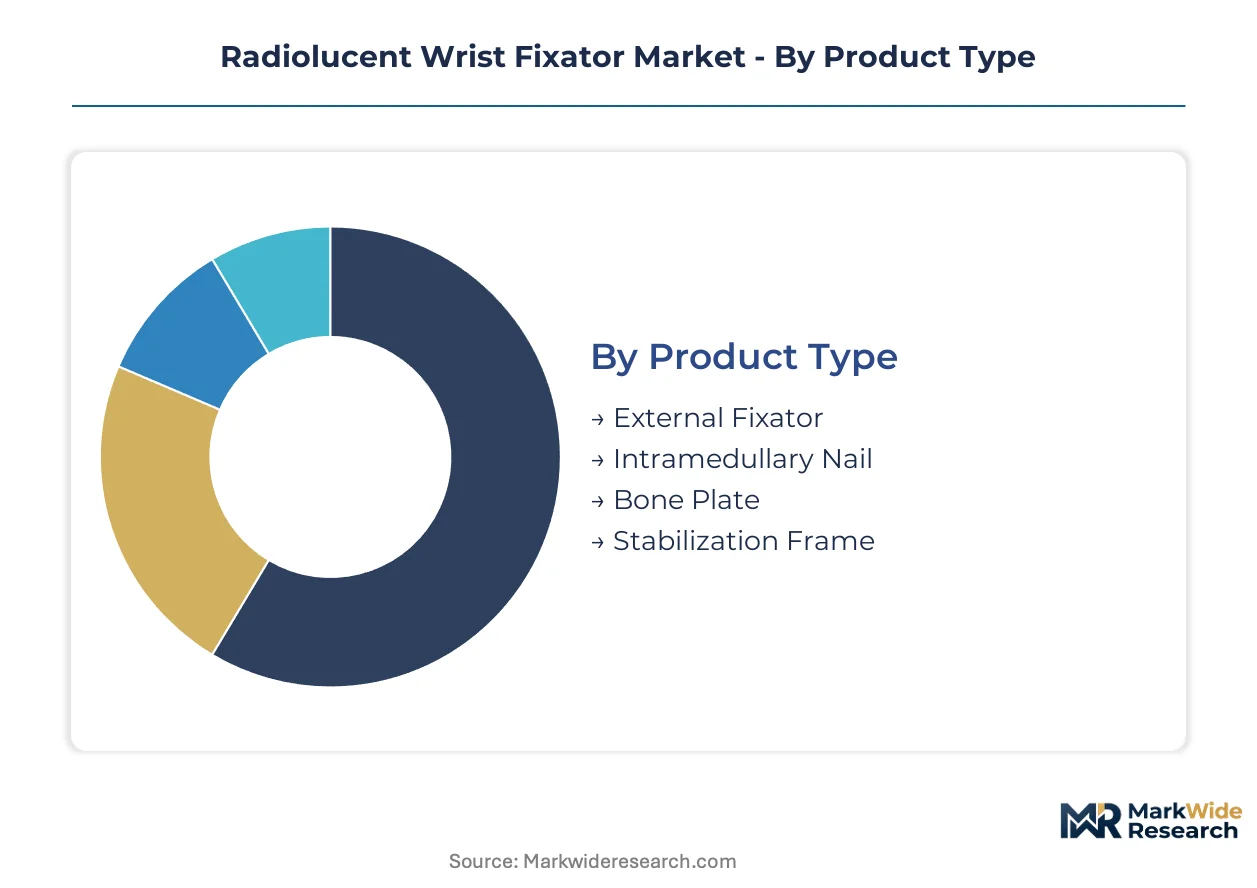
Radiolucent wrist fixation technology fragments across multiple procurement axes, each shaping how manufacturers configure composite engineering and commercial access. Trauma centers prioritize imaging transparency specifications while ambulatory facilities weight single-use economics, creating divergent product requirements within the same therapeutic category.
Product Type:
Carbon-fiber-reinforced polymer systems differentiate by structural architecture and reusability profile, with each configuration serving distinct surgical workflows and capital allocation strategies.
- External Fixator:Modular frame assemblies employing PEEK or carbon-fiber struts achieve tensile strengths exceeding 1,500 MPa while permitting unobstructed intraoperative fluoroscopy. Demand concentrates in United States Level I trauma centers where reusable frame economics align with high-volume fracture protocols and established sterilization infrastructure.
- Stabilization Frame:Lightweight single-use configurations optimize for ambulatory surgical center turnover requirements, eliminating reprocessing delays. German outpatient networks and United States freestanding surgery centers are expanding procurement fastest as procedure migration accelerates from inpatient settings.
- Bone Plate:Anatomically contoured radiolucent plates maintain mature margin pools in developed markets where inpatient surgical volumes persist and OR time premiums justify premium hardware.
- Intramedullary Nail:Intramedullary fixation applications concentrate in academic medical centers with advanced arthroscopic capabilities and intraoperative CT navigation systems.
Mature deployment sits with External Fixator systems. Newer deployment is concentrated in Stabilization Frame configurations.
End User:
Procurement authority and sterilization capacity determine how radiolucent fixation products flow through healthcare delivery organizations, with facility type dictating reusable versus disposable preference.
- Hospitals:Integrated delivery networks with captive sterile processing departments sustain preference for reusable carbon-fiber external fixation systems, amortizing capital across high fracture case volumes.
- Ambulatory Surgical Centers:United States outpatient facilities in Florida and Texas are consolidating vendor relationships around procedure-ready sterilized kits, displacing traditional materials management procurement.
- Specialty Clinics:Orthopedic-focused practices concentrate demand for patient-specific fixation geometries derived from preoperative imaging.
- Rehabilitation Centers:Post-operative monitoring facilities drive secondary demand for radiolucent hardware that permits healing assessment without device removal.
Volume concentration remains with Hospitals. Procurement innovation is accelerating most quickly in Ambulatory Surgical Centers.
Application:
Clinical indication shapes material specification requirements, with acute trauma demanding maximum mechanical performance and post-operative phases prioritizing imaging access for healing verification.
- Fracture Treatment:Distal radius and carpal fractures constitute the primary volume driver, with German university hospitals adopting tunable radiolucency profiles for complex reconstructions.
- Surgical Stabilization:Elective orthopedic procedures leverage PEEK-based systems to eliminate metal artifact interference during concurrent diagnostic imaging.
- Trauma Management:Emergency protocols favor external fixation for rapid stabilization with deferred definitive fixation, creating demand for C-arm-compatible frame geometries.
- Post-Surgery Care:Healing monitoring applications require sustained radiographic transparency across multi-month treatment windows, favoring carbon-fiber durability over biodegradable alternatives.
Established utilization centers on Fracture Treatment. Expanding utilization is concentrating in Surgical Stabilization as intraoperative navigation adoption broadens.
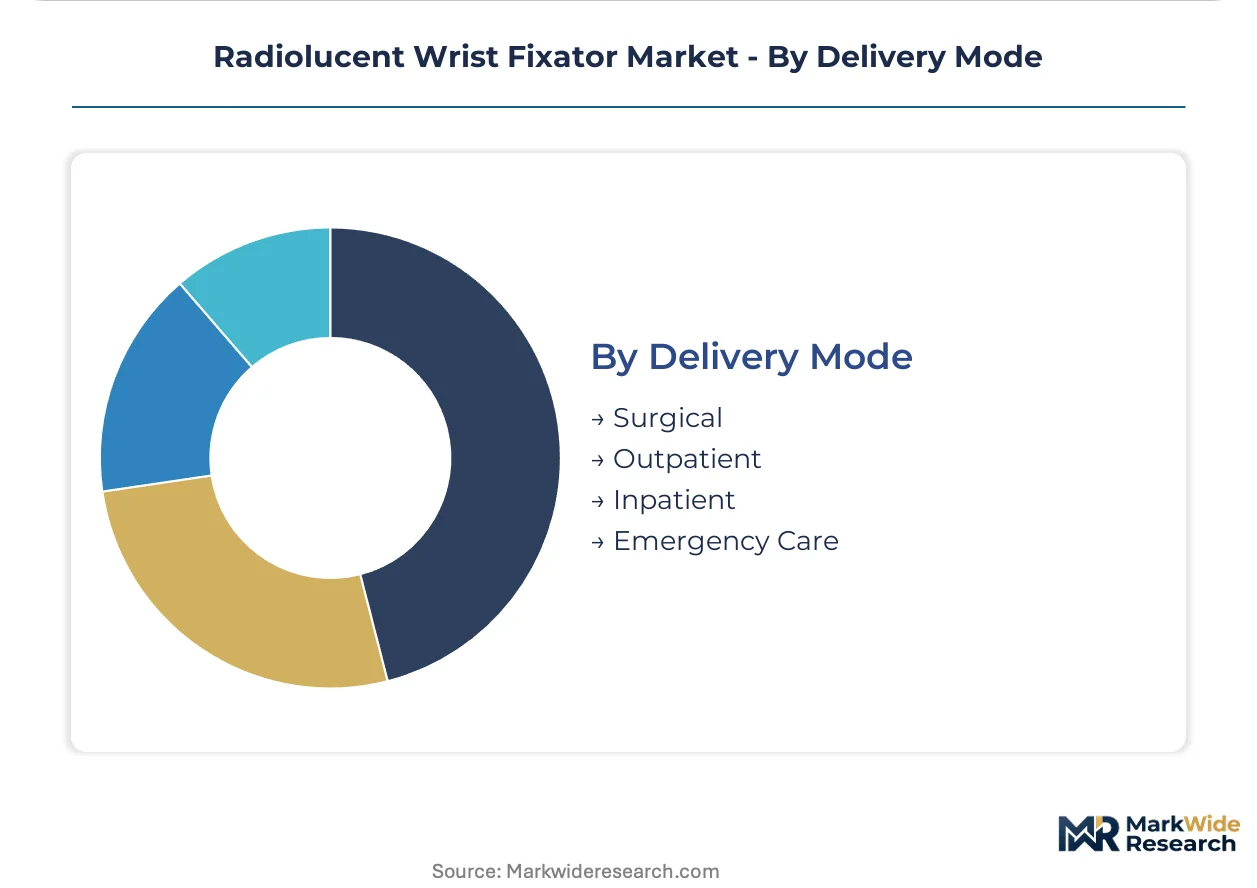
Delivery Mode:
Care setting determines regulatory pathway, reimbursement coding, and supply chain configuration for radiolucent fixation products.
- Surgical:Operating room-based implantation captures premium pricing tiers tied to sterile field requirements and OR time economics.
- Emergency Care:Trauma bay applications demand rapid-deployment external fixation systems with minimal assembly complexity.
- Inpatient:Hospital admission status sustains reimbursement advantages for complex fixation procedures requiring multi-day stays.
- Outpatient:Same-day discharge protocols are expanding fastest in United States markets where ambulatory surgical center infrastructure outpaces hospital bed growth.
Revenue concentration aligns with Inpatient delivery. Fastest volume expansion is occurring in Outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trauma centers in Stuttgart, Germany anchor European demand for radiolucent wrist fixation systems, where university hospital networks drive composite hardware procurement. Manufacturing clusters in Solingen and Tuttlingen supply carbon-fiber components to orthopedic device producers across the continent. Regulatory divergence between FDA, EU MDR, and Japan PMDA pathways fragments certification timelines for multinational suppliers.
United States
Level I trauma centers in Baltimore and Houston expand PEEK-based external fixator procurement for complex distal radius reconstructions. FDA 510(k) substantial equivalence pathways govern composite material clearances, with CDRH scrutiny intensifying for novel radiolucent polymers. Florida ambulatory surgical centers in the Tampa Bay metro consolidate vendor relationships around sterilized procedure-ready kits.
Germany
University hospitals in Heidelberg and Berlin adopt patient-matched 3D-printed stabilization frames derived from preoperative CT imaging. EU MDR Article 10 technical documentation mandates biocompatibility recertification for legacy carbon-fiber implants previously cleared under the Medical Device Directive. The Tuttlingen medical technology cluster concentrates precision machining expertise for PEEK component fabrication.
Japan
Academic medical centers in Tokyo and Osaka prioritize intraoperative CT navigation compatibility for wrist trauma protocols. PMDA enforces JIS T 0301 biocompatibility testing standards that diverge from ISO 10993 protocols, complicating composite material market entry. The Kobe biomedical device corridor hosts carbon-fiber layup specialists serving domestic orthopedic manufacturers.
United Kingdom
NHS trauma networks in London and Manchester standardize radiolucent hardware procurement for emergency wrist stabilization procedures. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR material disclosure requirements while streamlining notified body engagement for domestic manufacturers. The Cambridge medical technology cluster advances composite engineering for next-generation fixation geometries.
Switzerland
Swissmedic regulates radiolucent implants through streamlined Class IIb certification pathways that attract EU manufacturers seeking dual-market access. Orthopedic research institutes in Basel and Zurich collaborate with polymer suppliers on tunable radiolucency profiles. The Lake Geneva medical device corridor concentrates precision manufacturing for premium fixation components.
Radiolucent Wrist Fixator Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material transparency and imaging optimization capabilities. The vendor base stratifies into three tiers: diversified orthopedic conglomerates with trauma division scale, specialized radiolucent fixation platforms, and regional composite engineering shops. Structural consolidation proceeds through strategic partnerships between polymer suppliers and device manufacturers, alongside vertical integration into carbon-fiber layup operations.
Within the diversified orthopedic tier, Stryker Corporation and Smith & Nephew plc occupy positions anchored by broad hospital contracting networks across North American and European markets. Orthofix Medical Inc. exemplifies the specialized platform archetype, concentrating development resources on patient-specific external fixation geometries. These three entities represent distinct competitive vectors: scale-driven procurement leverage, imaging-optimized material science, and anatomical customization capabilities.
| Leading Market Players |
|---|
| Orthofix Medical Inc. |
| Smith & Nephew plc |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| DePuy Synthes (Johnson & Johnson) |
| Arthrex, Inc. |
| Medartis |
| Conmed Corporation |
| Fixus |
| Others |
Value Network & Pricing Analysis
EU MDR material transparency mandates gate qualified supply for premium-tier radiolucent fixation systems, compressing margin structures for manufacturers lacking notified body recertification while elevating pricing power for compliant composite engineering specialists serving German and United States trauma centers.
Pricing Analysis
Value-based pricing anchors on intraoperative imaging clarity and OR throughput efficiency, with trauma centers in Baltimore and Houston paying premiums for PEEK-based systems that eliminate metal artifact interference. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared carbon-fiber platforms from CE-marked alternatives and unregistered regional substitutes. Price differentiation hinges on JIS T 0301 biocompatibility certification for Japan entry and patient-matched geometry capabilities for German academic hospitals. Cost compression in standard-tier external fixators is intensifying because Florida ambulatory surgical centers consolidate procurement around sterilized procedure-ready kits. United States hospital systems exhibit lowest price sensitivity for reusable frame configurations, while Southeast Asian distributors remain most sensitive due to stainless steel substitution availability.
Supply Chain Analysis
PEEK resin supply rests on Western European specialty polymer producers, with carbon-fiber prepeg manufacturing concentrated in Japan and Germany. Raw material dependencies include aerospace-grade carbon fiber tow, medical-device-certified PEEK granulate, and biocompatible epoxy resin systems. Supply chain risk centers on single-source vulnerability for high-purity PEEK resin subject to regional energy disruption. Distribution runs through orthopedic device distributors with GPO contracts in the United States, direct hospital contracting in Germany, and specialized trauma product importers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radiolucent wrist fixator market operates as a cost-of-compliance story where EU MDR recertification burdens create a barrier-to-entry moat for established players with notified body relationships and legacy clinical evidence portfolios.
For Market Incumbents: Lock in backward integration into carbon-fiber layup operations to secure aerospace-to-medical engineering talent migration and insulate against PEEK feedstock volatility. Defend market position by accelerating patient-matched 3D-printed fixation geometries for German university hospitals before specialty clinics consolidate vendor relationships. Prioritize JIS T 0301 testing alignment to capture Japan PMDA pathway optimization ahead of composite manufacturing talent scarcity intensification. For New Entrants and Emerging Players: Enter via ambulatory surgical center single-use stabilization frame segments in Florida and Texas where procedure-ready kit demand outpaces incumbent supply flexibility. Target United States outpatient networks with C-arm-compatible frame geometries designed for hybrid operating suite workflow convergence. Pursue strategic partnerships with PEEK resin distributors to bypass Western European supply concentration and establish sterilized kit co-manufacturing relationships. For Investors and Strategic Acquirers: First-mover completion of EU MDR Article 10 technical documentation is the leading indicator that composite fixator manufacturers will sustain premium pricing through notified body capacity constraints. Long-term viability favors specialists with captive carbon-fiber machining capabilities and established German trauma center relationships over diversified orthopedic conglomerates facing margin compression across mature product lines. Watch for ambulatory surgical center vendor consolidation announcements as inflection signals for single-use configuration market share capture.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Recertification | Preserves market access for legacy carbon-fiber implants under tightened biocompatibility scrutiny. |
| Patient-Matched 3D-Printed Frame Development | Captures premium pricing in Heidelberg and Berlin university hospital networks. |
| JIS T 0301 Biocompatibility Testing Alignment | Accelerates PMDA market entry for composite fixators engineered to Asia-Pacific protocols. |
| Ambulatory Surgical Center Kit Sterilization Partnership | Displaces traditional hospital materials management procurement in Florida outpatient networks. |
| C-Arm Compatibility Workflow Integration | Captures preference in United States hybrid operating suites with seamless imaging convergence. |
Research Methodology
Independent corroboration across trauma surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers underwrites the qualitative findings in this study. Primary interviews with German university hospital procurement directors and United States Level I trauma center OR managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, Japan PMDA submission records, and hospital procurement database audits. Bottom-up demand modeling across product type, end user, application, and delivery mode segments triangulated against top-down macroeconomic indicators.
Comparable-period anchoring to historical trauma procedure volumes and radiolucent hardware adoption curves established the forecast baseline across the modeling period. Segmentation dimensions modeled include structural architecture, facility sterilization capacity, clinical indication, and care setting regulatory pathway. CAGRs derived from weighted average of procedure growth projections, pricing trajectory assumptions, and composite material cost evolution. Industry-specific forecast inputs incorporated ambulatory surgical center expansion rates and EU MDR recertification completion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended notified body audit delays or PEEK resin supply disruption scenarios. Forecasts reflect documented assumptions regarding trauma procedure migration patterns and composite manufacturing capacity expansion. Regulatory timeline slippage, single-use configuration adoption acceleration, and carbon-fiber layup labor market tightness warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laser Resurfacing Market
Medical Devices
Artificial Implants Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Digital BTE Market
Medical Devices
Light Therapy Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Depression Devices Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Supraglottic Device Market
Medical Devices
Drug Delivery Devices Market