
 Safety Pen Needles Market | 2026-2036
Safety Pen Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Pen Needles Market Analytics
The capital-intensity gap between automated assembly specialists and manual-scale producers is collapsing as shielded needle manufacturing demands cleanroom investment and precision molding at volumes exceeding ten million units annually. Becton, Dickinson and Company anchors North American hospital supply chains through backward integration into polymer extrusion and automated tip grinding. Ypsomed AG differentiates via pen needle compatibility across multiple drug delivery platforms, sustaining its position in European homecare channels.
Safety pen needles are single-use injection devices incorporating passive or active shielding mechanisms to prevent needlestick injuries, typically manufactured from electro-polished stainless steel cannulas bonded to polypropylene hubs with silicone lubrication to reduce injection force. Their primary purpose is enabling safe subcutaneous drug delivery in non-clinical settings where healthcare worker supervision is absent. Shielded designs currently dominate hospital procurement due to lower unit cost and simpler mechanical reliability, while retractable configurations are expanding fastest in homecare as patients prioritize one-handed activation and disposal safety. The therapy area dimension shows diabetes commanding the largest volume base, though hormonal therapy applications are generating disproportionate margin pools due to smaller batch sizes and premium pricing for fertility treatment protocols.
The FDA's sharps injury prevention guidelines under OSHA's Bloodborne Pathogens Standard mandate engineered safety devices in US healthcare settings, while the EU MDR's general safety and performance requirements enforce needle shielding verification across CE-marked products. Japan's PMDA classifies safety pen needles as highly controlled medical devices, requiring clinical evidence of injury reduction for market authorization. Stakeholders must monitor evolving reimbursement thresholds for smart delivery modes and integrated systems as payers weigh device cost against downstream needlestick treatment expenses.
Market Dynamics
Cleanroom-grade polymer extrusion capacity is fragmenting across automated assembly specialists and contract manufacturers, compressing the capital barrier that once separated hospital-scale suppliers from homecare entrants.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:US healthcare facilities must deploy engineered safety devices, mandating passive shielding mechanisms in all reimbursed insulin delivery protocols.
- Japan's aging diabetes population:Self-injection protocols among patients over 65 are accelerating demand for one-handed retractable activation designs.
- Electro-polished stainless steel sourcing:German and Swiss precision metalworking clusters now supply cannula blanks at volumes supporting ten million unit annual production runs.
Market Restraints
- Medical-grade polypropylene price volatility:Hub molding feedstock costs fluctuate with propylene monomer supply tied to European petrochemical crackers.
- Cleanroom infrastructure concentration:Automated assembly lines requiring ISO 7 certification cluster in southern Germany and western Switzerland, creating geographic supply risk.
- Silicone lubricant technical limitation:Alternative bio-based coatings fail to achieve equivalent glide force reduction in subcutaneous tissue penetration testing.
Strategic Opportunities
- India's homecare underpenetration:Type 2 diabetes self-management protocols remain hospital-centered in tier-2 cities, creating white space for shielded needle distribution.
- EU MDR needle safety verification:The regulation's general safety requirements create compliance-driven demand tailwinds for CE-marked retractable designs.
- Connected delivery convergence:Bluetooth-enabled dose tracking is merging with passive shielding mechanisms, opening premium positioning in fertility hormone protocols.
Industry Challenges
- Precision molding skill scarcity:Polypropylene hub flash control and cannula bonding alignment require technicians trained in micro-assembly tolerances below 50 microns.
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Pen Needles Market |
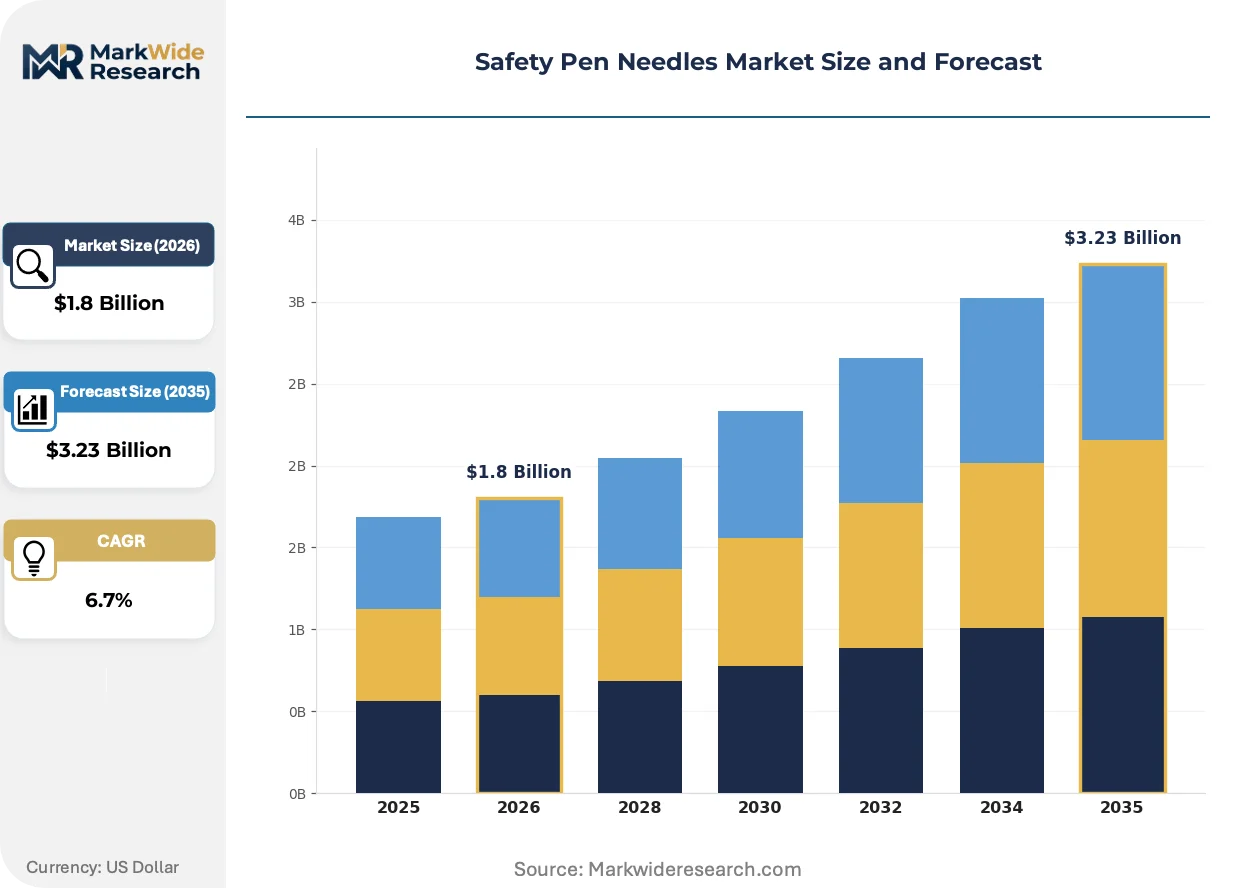
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable, Shielded, Fixed, Adjustable Therapy Area: Diabetes, Hormonal Therapy, Fertility Treatment, Autoimmune Disorders End User: Hospitals, Homecare, Clinics, Pharmacies Delivery Mode: Manual, Automatic, Smart Devices, Integrated Systems |
| Companies Covered | Novo Nordisk A/S, B. Braun SE, Becton, Dickinson and Company (BD), Ypsomed AG, Nipro Corporation, Embecta Corp., Terumo Corporation, Owen Mumford, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Pen Needles Market Evolving Landscape
Mechanical safety engineering is diverging from universal hospital designs toward patient-specific activation protocols, splitting manufacturing investment between shielded and retractable platforms.
Passive shielding is fragmenting into two incompatible design philosophies: spring-loaded outer sleeves favored by US hospital procurement for mechanical simplicity, and integrated hub-shield mechanisms preferred by European homecare channels for disposal compactness. German diabetes patients are adopting the latter at faster replacement cycles than institutional buyers. This divergence is compressing economies of scale for universal platform suppliers and rewarding regional specialization.
Japan's PMDA revised its highly controlled medical device classification in 2023, requiring clinical evidence of needlestick injury reduction for market authorization of new safety pen needle submissions. The industrial consequence is a documentation burden favoring established manufacturers with retrospective injury databases. Retractable configurations face steeper evidentiary requirements than shielded alternatives, tilting new product development toward incremental shielding improvements.
Hospital purchasing consortiums in the United States are consolidating insulin delivery device procurement under single-source agreements that bundle safety pen needles with continuous glucose monitors. This bundling is displacing independent needle suppliers from formulary access. The shift is most visible in integrated delivery networks across the Midwest and Southeast, where pharmacy benefit managers now control device selection.
Safety Pen Needles Market Segmentation
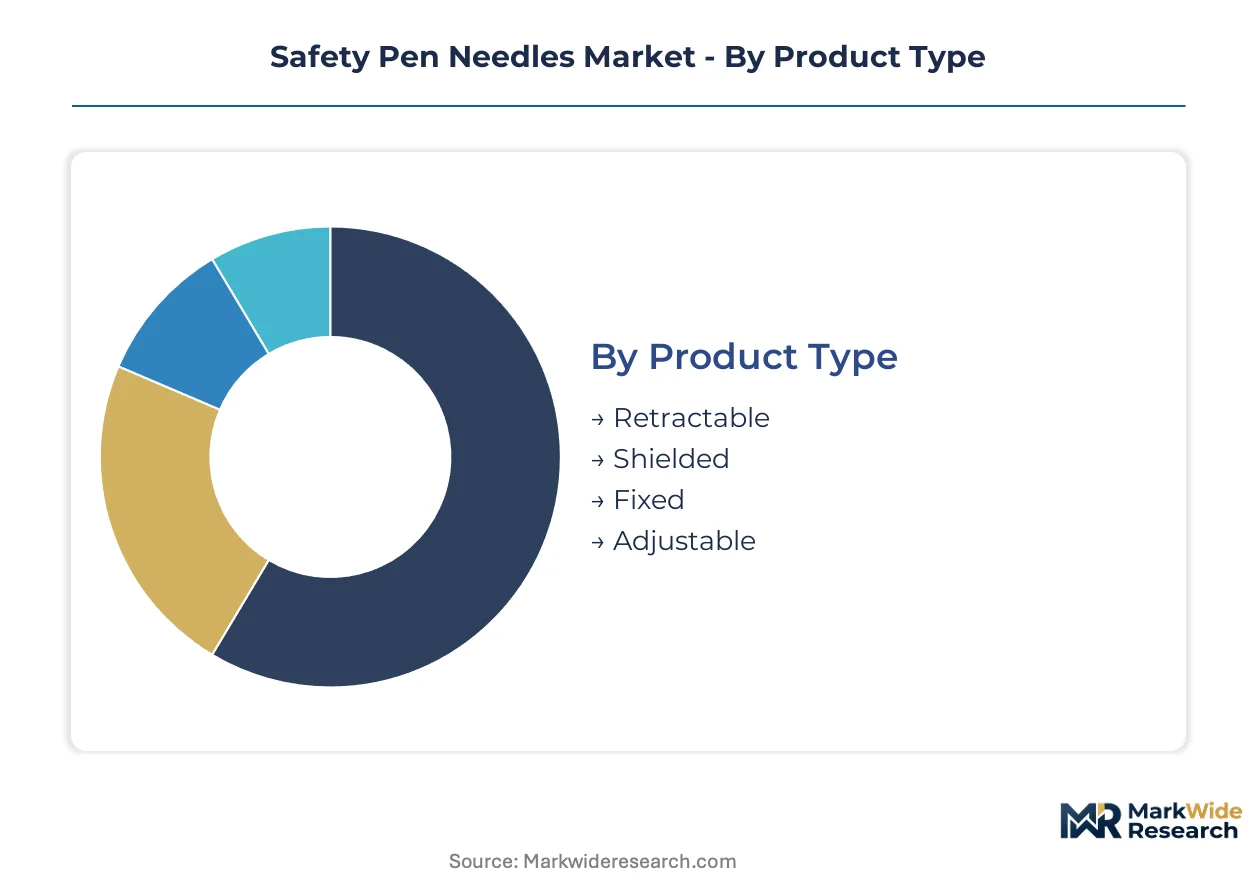
Safety pen needle procurement splits across institutional and patient-directed channels with divergent mechanical requirements. Shielded and retractable platforms command premium positioning in regulated healthcare settings, while fixed designs retain cost-sensitive volume in emerging markets.
Product Type:
Retractable configurations capture the steepest margin pools through one-handed activation patents and homecare premium positioning.
- Retractable:Spring-loaded cannula retraction mechanisms eliminate post-injection exposure. Demand concentrates in Japanese and German homecare channels where patients over 65 prioritize disposal safety and PMDA evidence requirements favor established suppliers with injury databases.
- Shielded:Outer sleeve barriers deploy passively upon needle withdrawal. US hospital procurement favors this design for mechanical reliability and lower unit cost under OSHA-mandated engineered safety protocols.
- Fixed:Non-safety conventional needles retain position in price-sensitive institutional tenders and developing market clinics where regulatory enforcement remains uneven.
- Adjustable:Variable-length cannula settings accommodate subcutaneous tissue depth variation across patient BMI ranges.
Shielded designs hold installed capacity across Midwest and Southeast US integrated delivery networks. Retractable configurations are rotating up the share rankings in European fertility hormone protocols.
Therapy Area:
Volume concentration sits with diabetes, yet fertility treatment generates disproportionate margin through smaller batch sizes and premium pricing.
- Diabetes:Insulin delivery protocols drive unit economics through replacement cycles of 3-4 daily injections. Demand concentrates in United States, Germany, and Japan where reimbursement frameworks for safety-engineered devices are most developed.
- Fertility Treatment:Gonadotropin protocols require precise dosing with minimal tissue trauma. European homecare channels absorb premium retractable designs for patient self-administration outside clinical supervision.
- Hormonal Therapy:Growth hormone and testosterone replacement applications favor shielded platforms in pediatric and geriatric populations.
- Autoimmune Disorders:Biologic subcutaneous delivery for rheumatoid arthritis and psoriasis expands retractable adoption in specialty pharmacy distribution.
Diabetes commands manufacturing scale through ten-million-unit annual production runs. Fertility treatment is climbing the fastest toward premium positioning as connected delivery convergence opens Bluetooth-enabled dose tracking.
End User:
Procurement authority is fragmenting between pharmacy benefit managers and direct patient acquisition.
- Hospitals:Consolidated purchasing consortiums bundle safety pen needles with continuous glucose monitors, displacing independent suppliers from formulary access.
- Homecare:Self-injection protocols among aging diabetes populations in Japan and Germany accelerate demand for one-handed retractable activation.
- Clinics:Outpatient endocrinology practices balance OSHA compliance with cost containment through shielded platform standardization.
- Pharmacies:Retail channels in India's tier-2 cities remain underpenetrated, creating white space for shielded needle distribution as type 2 diabetes self-management protocols shift from hospital-centered care.
Hospitals retain volume concentration through integrated delivery network contracts. Homecare is gaining share fastest as patient-directed procurement bypasses institutional purchasing constraints.
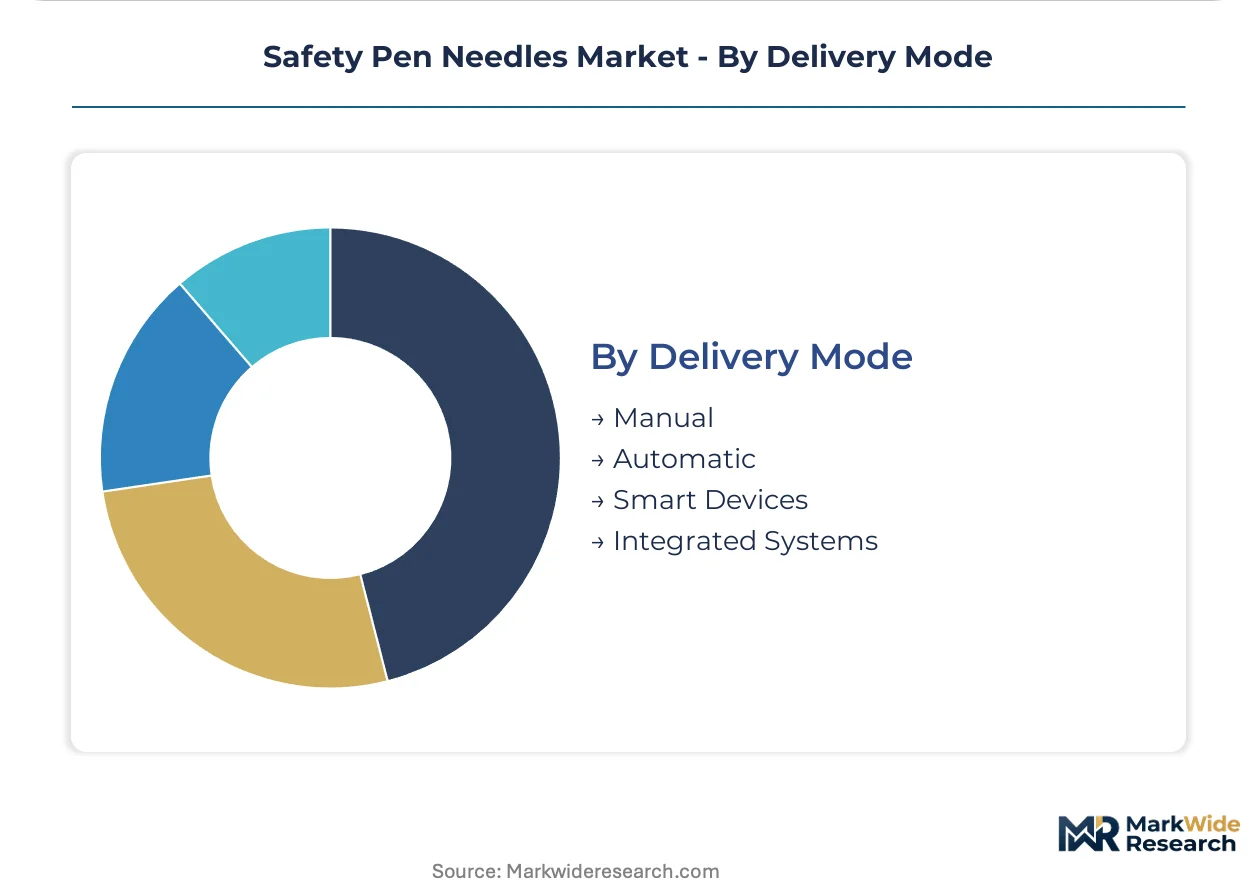
Delivery Mode:
Smart device integration is compressing the addressable market for standalone needle suppliers.
- Manual:Conventional pen injector compatibility sustains broad platform adoption across disposable and reusable delivery systems.
- Automatic:Spring-assisted injection mechanisms reduce activation force for arthritis patients and pediatric populations.
- Smart Devices:Bluetooth-enabled dose tracking merges with passive shielding mechanisms, opening premium positioning in fertility hormone protocols where timing precision affects treatment efficacy.
- Integrated Systems:Continuous glucose monitor and insulin pump bundling concentrates procurement under single-source agreements controlled by pharmacy benefit managers.
Manual delivery holds installed capacity through backward compatibility requirements. Smart devices are rotating up the share rankings as EU MDR needle safety verification creates compliance-driven demand tailwinds for CE-marked retractable designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for safety pen needles varies sharply across markets. US and German buyers absorb premium retractable designs under robust reimbursement, while Indian and Brazilian procurement remains cost-constrained.
United States
Hospital purchasing consortiums across the Midwest and Southeast bundle safety pen needles with continuous glucose monitors, concentrating procurement under pharmacy benefit manager control. OSHA's Bloodborne Pathogens Standard mandates engineered safety devices in all reimbursed insulin delivery protocols. Cleanroom-grade manufacturing clusters in North Carolina and Minnesota supply shielded platforms to integrated delivery networks.
Germany
Aging diabetes patients over 65 in Bavaria and Baden-Württemberg accelerate demand for one-handed retractable activation designs in homecare channels. The EU MDR's general safety and performance requirements enforce needle shielding verification across CE-marked products. Precision metalworking clusters in southern Germany supply electro-polished stainless steel cannula blanks at ten-million-unit annual volumes.
Japan
Self-injection protocols among elderly diabetes populations drive replacement cycles for retractable configurations with disposal safety features. The PMDA's 2023 revised classification for highly controlled medical devices requires clinical evidence of needlestick injury reduction for market authorization. Manufacturing concentration in the Kanto region around Tokyo serves domestic homecare demand.
India
Type 2 diabetes self-management protocols remain hospital-centered in tier-2 cities, creating white space for shielded needle distribution as patients shift toward homecare. The country's national pharmaceutical regulator enforces medical device quality standards through CDSCO oversight. Distribution networks in Maharashtra and Gujarat are expanding retail pharmacy access to safety-engineered devices.
Switzerland
Fertility treatment protocols in Geneva and Basel absorb premium retractable designs for gonadotropin self-administration outside clinical supervision. Swissmedic maintains stringent biocompatibility certification timelines extending product launch cycles. Precision molding expertise in the Jura Arc supports micro-assembly tolerances below 50 microns for hub flash control.
Safety Pen Needles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on cleanroom certification and cannula sourcing relationships. The upper tier controls backward integration into polymer extrusion and automated tip grinding, while mid-scale players rely on contract manufacturers for ISO 7 assembly. Two strategic archetypes dominate: diversified medical device conglomerates with hospital supply chain anchoring, and focused pen needle specialists with multi-platform compatibility. Competitive moves concentrate on single-source procurement bundling and regional specialization for homecare activation preferences.
Among diversified conglomerates, Becton, Dickinson and Company and Terumo Corporation occupy positions reflecting integrated manufacturing footprints. B. Braun SE exemplifies the European hospital-system specialist archetype. Within the focused specialist tier, Ypsomed AG represents multi-platform compatibility positioning, while Novo Nordisk A/S anchors pharmaceutical-origin device development. Nipro Corporation and Owen Mumford sit within mid-scale specialist categories serving regional procurement channels. Cardinal Health and Embecta Corp. reflect distribution and spin-off archetypes respectively, each occupying distinct competitive positions without overlapping core manufacturing strategies.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| B. Braun SE |
| Becton, Dickinson and Company (BD) |
| Ypsomed AG |
| Nipro Corporation |
| Embecta Corp. |
| Terumo Corporation |
| Owen Mumford |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Sixty-day cannula blank lead times from southern German precision metalworking clusters compress pricing power for retractable designs while shielded platforms compete on polymer hub molding economies. This inventory-to-pricing nexus rewards backward integration into electro-polished stainless steel sourcing and penalizes contract-dependent assemblers facing ISO 7 cleanroom slot scarcity.
Pricing Analysis
After-sales revenue from sharps disposal containers and patient training programs drives lifetime value capture beyond the initial device transaction. Three-tier pricing structure across premium retractable, standard shielded, and economy fixed designs stratifies by activation mechanism complexity and regulatory certification tier. Cost compression in shielded platforms intensifies as US hospital purchasing consortiums consolidate procurement under bundled continuous glucose monitor agreements. Price-sensitive volume concentrates in Indian tier-2 city clinics where CDSCO enforcement remains uneven, while Japanese homecare patients absorb premium positioning for PMDA-compliant retractable designs with clinical injury reduction evidence.
Supply Chain Analysis
Germany and Switzerland anchor electro-polished stainless steel cannula production at ten-million-unit annual scales, while southern Germany and western Switzerland concentrate ISO 7 cleanroom automated assembly capacity. Polypropylene hub molding draws from European petrochemical crackers with propylene monomer price volatility, and silicone lubricant coatings hinge on specialty chemical suppliers with limited bio-based alternatives. Single-source vulnerability concentrates in cleanroom infrastructure clustering, with geographic supply risk amplified by precision molding technician scarcity for micro-assembly tolerances below 50 microns. Distribution runs through hospital purchasing consortiums in the United States, pharmacy benefit manager networks, and direct patient acquisition channels in European homecare markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-assembly tolerance capability below 50 microns represents the binding constraint separating automated assembly specialists from manual-scale entrants, with technician training pipelines failing to match cleanroom expansion timelines.
For Market Incumbents: Secure backward integration into polymer extrusion and automated tip grinding to defend margin position against contract manufacturer cost convergence. Anchor hospital formulary access through single-source procurement bundling with continuous glucose monitors, displacing independent needle suppliers from integrated delivery network contracts. Prioritize ISO 10993 biocompatibility certification investment to compress 14-18 month launch cycles versus emerging competitors. For New Entrants and Emerging Players: Anchor in India's tier-2 city retail pharmacy channels where type 2 diabetes self-management protocols remain hospital-centered and shielded needle distribution penetration lags. Target European fertility treatment homecare protocols for premium retractable positioning, leveraging Bluetooth-enabled dose tracking convergence to bypass established hospital supply chain barriers. Pursue EU MDR needle safety verification as a compliance-driven market entry credential. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because OSHA, EU MDR, and PMDA evidence requirements create documentation moats favoring established manufacturers with retrospective injury databases. Acquisition targets should display multi-platform pen needle compatibility across insulin and hormone delivery systems, with cleanroom certification and cannula sourcing relationships as minimum viable assets. Monitor Japan PMDA submission volumes for retractable designs as an inflection indicator for homecare premium positioning adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR needle safety verification creates compliance-driven demand tailwinds for retractable designs. |
| Hospital System Partnership | Midwest and Southeast US integrated delivery networks consolidate procurement under pharmacy benefit manager control. |
| Backward Integration | Captive polymer extrusion and automated tip grinding capacity separates tier-one suppliers from contract-dependent assemblers. |
| Software Companion Development | Bluetooth-enabled dose tracking merges with passive shielding for fertility hormone protocol premium positioning. |
| Reimbursement Strategy | OSHA-mandated engineered safety devices and developed reimbursement frameworks in US, Germany, and Japan anchor pricing power. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and homecare diabetes educators converged on the working assumptions for safety pen needle demand modeling. Primary interviews with regulatory affairs specialists at notified bodies and precision molding technicians supplemented secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, PMDA approval records, and hospital procurement contract repositories. Bottom-up unit volume estimates across shielded, retractable, fixed, and adjustable product types triangulated against top-down therapy area spending analysis for diabetes, fertility treatment, hormonal therapy, and autoimmune disorder applications.
Segmentation dimensions modeled include product type activation mechanism, therapy area drug delivery protocol, end user procurement authority, and delivery mode technology integration across the projection horizon. CAGRs derived from replacement cycle analysis for insulin injection frequency, patient population growth in aging diabetes demographics, and regulatory mandate adoption curves. Industry-specific forecast inputs incorporated OSHA compliance penetration rates, EU MDR transition timelines, and PMDA clinical evidence requirements for highly controlled medical device classifications.
Underlying assumptions cover cleanroom capacity expansion trajectories, propylene monomer price stability, and silicone lubricant supply continuity, with deviation risk concentrated in precision molding technician availability and biocompatibility certification timeline extensions. Recalibration cycles align with material shifts in regulatory enforcement intensity, reimbursement threshold revisions, and connected delivery technology adoption inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Microcarrier Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Global Needles Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Spain Hospital Supplies Market