
 Middle East and Africa Hospital Supplies Market | 2026-2036
Middle East and Africa Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hospital Supplies Market Foresight
Multi-source procurement is expanding across Middle East and Africa health systems as governments diversify vendor relationships to reduce supply vulnerability. Becton, Dickinson and Company leverages its regional distribution partnerships to anchor diagnostic consumable flows into Gulf state hospitals. Cardinal Health competes through centralized procurement contracts with public hospital networks in Saudi Arabia and Egypt. Stryker specializes in orthopedic and surgical equipment segments where private clinic expansion in the UAE creates premium product pull.
Hospital supplies encompass the full range of consumable, durable, and capital goods required for clinical operations, patient handling, and surgical intervention within acute and sub-acute care settings; these items must meet biocompatibility, sterility assurance level (SAL), and electrical safety specifications governed by IEC 60601 for powered equipment. The primary commercial purpose centers on enabling continuous clinical workflow while minimizing nosocomial transmission risk. Consumables capture recurring revenue streams through high-turnover items such as syringes, catheters, and wound dressings where procurement auctions drive price transparency. Equipment segments concentrate margin pools in imaging and patient monitoring systems where GE Healthcare and Philips maintain technology leadership. Surgical instruments represent the fastest-growing product category as ambulatory surgical centers proliferate across Gulf cities and South African metropolitan areas.
SFDA in Saudi Arabia and SAHPRA in South Africa enforce device registration and quality management system requirements that filter market access for non-compliant manufacturers. Egypt's drug authority and UAE's Ministry of Health and Prevention apply convergent standards for sterile barrier packaging and traceability labeling, compelling suppliers to harmonize documentation across multiple national frameworks. Stakeholders must monitor regulatory reciprocity negotiations between Gulf states and assess whether centralized procurement platforms will consolidate distributor tiers or preserve fragmented channel structures.
Market Dynamics
SFDA sterilization audits and SAHPRA device registration timelines are compressing supplier qualification windows across Saudi Arabia and South Africa, forcing procurement teams to pre-validate alternative vendors before contract renewals expire.
Growth Catalysts
- Gulf hospital infrastructure expansion:Greenfield medical cities in Riyadh and Dubai absorb advanced surgical suites and patient monitoring systems. Public tenders for infection control consumables accelerate procurement cycles.
- SAHPRA sterilization standard tightening:South Africa's upgraded quality management system requirements filter non-compliant imports. Domestic distributors invest in cold-chain verification capabilities to maintain market access.
- Ambulatory surgical center proliferation:Private clinic networks in Abu Dhabi and Johannesburg expand day-surgery capacity. Disposable instrument demand concentrates in ophthalmology and orthopedics segments.
Market Restraints
- Freight cost volatility:Red Sea shipping disruptions elevate container rates for European and Asian-sourced capital equipment. Egyptian public hospitals delay imaging system deployments.
- Single-source sterilization film supply:Tyvek and medical-grade paper substrate production concentrates in Western European plants. Gulf distributors hold 90-day safety stocks against customs delays.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity assessments queue at accredited laboratories in Germany and Singapore. South African manufacturers face six-month certification timelines for new wound dressing formulations.
Strategic Opportunities
- Underpenetrated East African markets:Ethiopia and Kenya public health systems lack centralized procurement platforms. Regional distributors can anchor supply contracts before government tender formalization.
- Reusable surgical instrument reprocessing:Steam sterilization and hydrogen peroxide plasma systems converge to reduce per-procedure costs. Saudi private hospital groups pilot instrument tracking via RFID.
- MOHAP traceability mandate:UAE serialization requirements for sterile barrier packaging create first-mover advantage for suppliers with integrated labeling systems. Compliance investments lock out smaller competitors.
Industry Challenges
- Biomedical engineering talent scarcity:Patient monitoring equipment maintenance requires specialized technicians. Egyptian and Nigerian hospitals outsource service contracts to OEM field engineers at premium rates.
- Legacy ERP integration friction:South African public hospital networks operate on fragmented procurement software. Centralized ordering platforms stall due to data migration complexity and staff retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hospital Supplies Market |
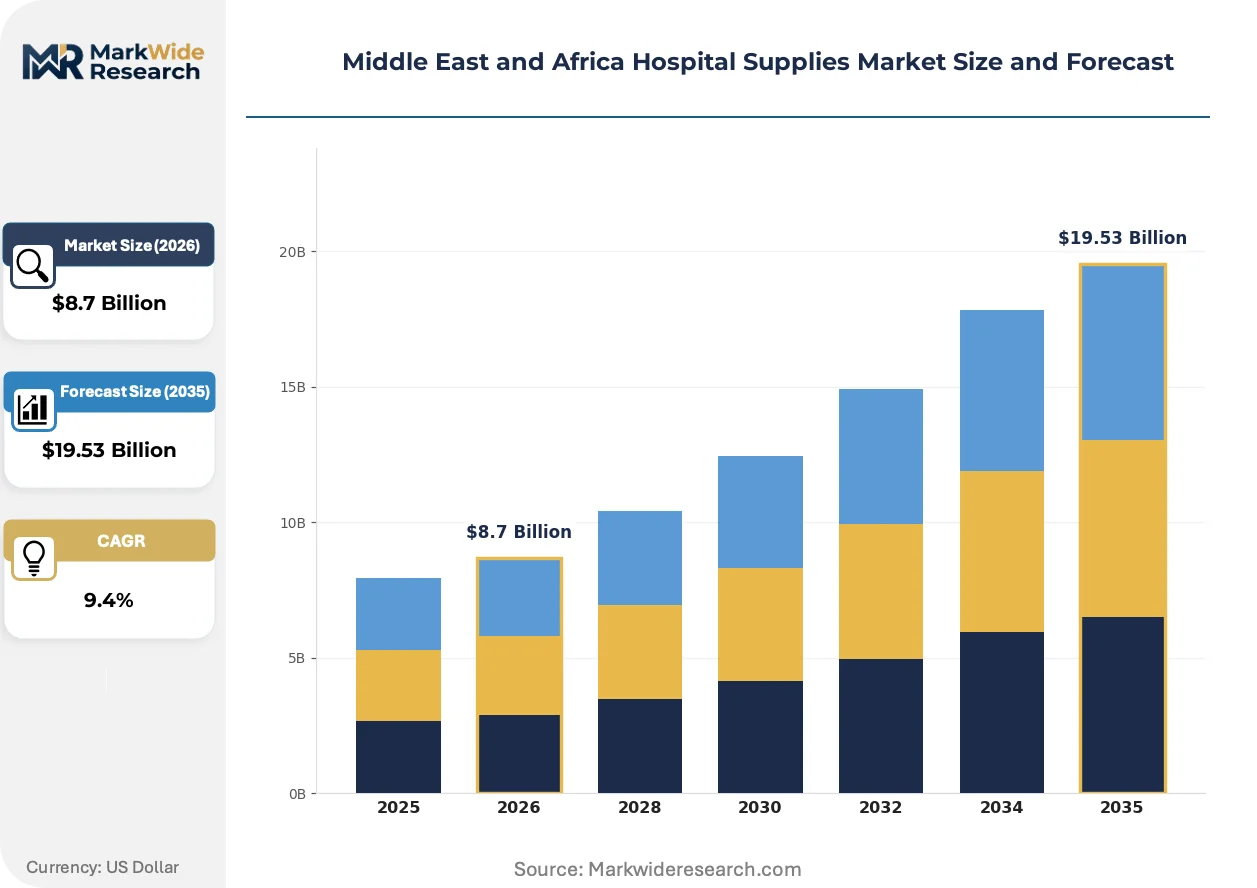
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Equipment, Furniture, Surgical Instruments End User: Public Hospitals, Private Clinics, Ambulatory Surgical Centers, Long-term Care Facilities Application: Infection Control, Diagnostics, Surgery, Patient Care Supply Channel: Direct Sales, Distributors, Online Retailers, Procurement Auctions |
| Companies Covered | Becton, Dickinson and Company, Cardinal Health Inc., General Electric Company (GE Healthcare), Stryker Corporation, B. Braun Melsungen AG, Invacare Corporation, Koninklijke Philips N.V., Siemens Healthcare Private Limited, Medtronic, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hospital Supplies Market Shifts & Advancements
Digital supply chain visibility tools and single-use device reprocessing protocols are restructuring how Gulf and African health systems manage consumable flows and capital equipment lifecycles.
Smart infusion pump connectivity is consolidating medication administration workflows across Saudi tertiary hospitals. Wireless dose-error reduction software integrates with electronic health records. Nursing staff adoption accelerates as interoperability standards stabilize, compressing training cycles and reducing adverse event liability exposure.
SAHPRA's device establishment licensing framework tightens importer accountability for post-market surveillance. Foreign manufacturers must designate local authorized representatives with pharmacovigilance capabilities. South African distributors absorb compliance costs or surrender product lines to better-resourced competitors.
Consolidated procurement platforms disintermediate traditional distributor tiers in UAE and Saudi Arabia. Ministry of Health central purchasing bodies aggregate demand across hospital networks. Volume commitments extract price concessions from manufacturers while squeezing margins for regional wholesalers dependent on fragmented clinic sales.
Middle East and Africa Hospital Supplies Market Segmentation
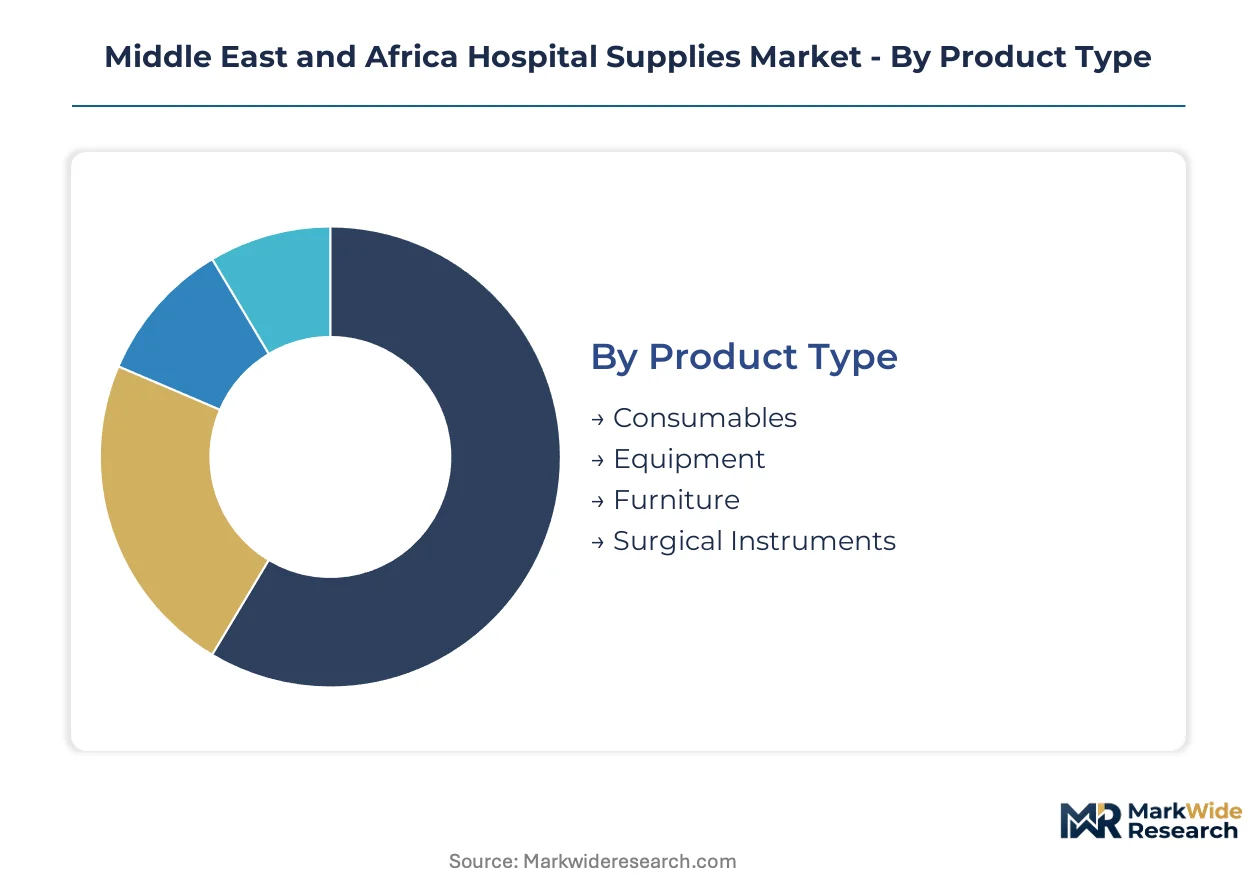
Hospital supplies in the Middle East and Africa fragment across product durability, care setting intensity, and procurement sophistication. Each dimension shapes margin pools, regulatory exposure, and distributor channel selection differently across Gulf and African markets.
Product Type:
Volume turnover concentrates in consumables while premium margins anchor equipment and surgical instruments.
- Consumables:Single-use syringes, catheters, wound dressings, and sterilization barriers dominate procurement tonnage. Saudi public hospital networks tender these through centralized MOH platforms, compressing distributor margins while guaranteeing volume offtake.
- Equipment:Patient monitoring systems, infusion pumps, and diagnostic imaging devices carry capital expenditure cycles. Private hospital groups in Dubai and Riyadh absorb advanced suites where GE Healthcare and Philips compete on interoperability certification.
- Furniture:Hospital beds, stretchers, and patient handling equipment fall into mid-tier procurement categories. Egyptian public tenders prioritize domestic assembly requirements over import specifications.
- Surgical Instruments:Reusable and disposable instrument sets serve orthopedic and ophthalmology expansion. Ambulatory surgical centers in Abu Dhabi and Johannesburg drive fastest uptake of single-use kits to eliminate reprocessing overhead.
Mature deployment sits with consumables. Newer deployment is concentrated in surgical instruments.
End User:
Public procurement scale contrasts with private clinic premium pricing and ambulatory efficiency demands.
- Public Hospitals:Government-owned tertiary facilities across Saudi Arabia, Egypt, and South Africa aggregate demand through ministry-level tenders. SFDA and SAHPRA registration requirements filter supplier pools, favoring established distributors with compliance infrastructure.
- Private Clinics:Specialty cardiology and oncology centers in UAE and Qatar source premium consumables and capital equipment outside auction mechanisms. Direct manufacturer relationships bypass distributor markups for high-value imaging systems.
- Ambulatory Surgical Centers:Day-surgery facilities proliferate across Gulf cities and South African metros. Disposable instrument demand concentrates here as throughput maximization eliminates sterilization turnaround constraints.
- Long-term Care Facilities:Post-acute and rehabilitation centers in Kuwait and Morocco absorb patient handling equipment and basic wound care supplies. Procurement fragmentation limits centralized contracting leverage.
Public hospitals anchor volume contracting. Private clinics are expanding most quickly.
Application:
Regulatory intensity varies sharply across clinical use cases, with infection control facing tightest sterilization mandates.
- Infection Control:Sterile barrier packaging, hand hygiene consumables, and environmental disinfection products face SFDA sterilization audits and SAHPRA quality management system requirements. Gulf distributors hold extended safety stocks against customs delays for Tyvek and medical-grade substrates.
- Diagnostics:Specimen collection devices, reagents, and point-of-care testing equipment flow through Becton Dickinson's regional distribution partnerships. Laboratory accreditation standards in Saudi Arabia and UAE filter non-compliant imports.
- Surgery:Operating room consumables and instrument sets serve expanding procedure volumes. Day-surgery networks in Johannesburg and Dubai prioritize disposable kits to minimize reprocessing liability.
- Patient Care:General ward supplies including infusion sets, oxygen delivery devices, and basic monitoring equipment rotate on high-turnover procurement cycles. Price transparency through centralized auctions compresses margins.
Infection control commands tightest regulatory scrutiny. Surgery is gaining share fastest.
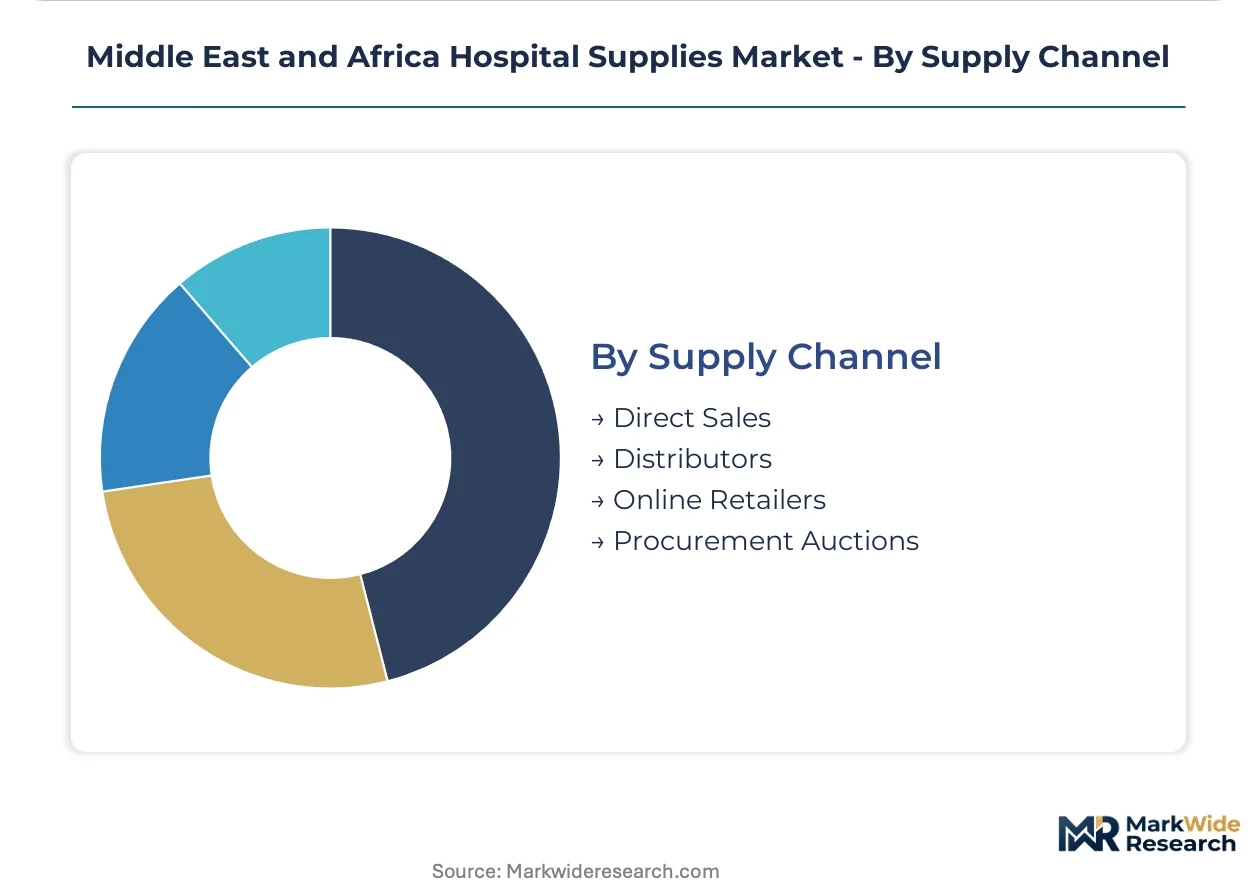
Supply Channel:
Channel selection determines margin capture, with direct sales preserving manufacturer pricing power while auctions maximize transparency.
- Direct Sales:Capital equipment manufacturers including GE Healthcare and Philips negotiate directly with Saudi and UAE ministry procurement bodies. Volume commitments extract price concessions while eliminating distributor tiers.
- Distributors:Regional wholesalers including Cardinal Health's Saudi and Egyptian operations manage consumable flows to fragmented clinic networks. Cold-chain verification capabilities differentiate compliant from marginal players.
- Online Retailers:E-procurement platforms penetrate lower-value consumable categories where standard specifications reduce pre-purchase inspection requirements. South African public hospital ERP fragmentation limits adoption.
- Procurement Auctions:Centralized tender platforms in Saudi Arabia and UAE aggregate demand across hospital networks. Price transparency benefits buyers while squeezing margins for suppliers dependent on information asymmetry.
Distributors anchor fragmented clinic access. Direct sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital supplies demand concentrates in Gulf Cooperation Council states where infrastructure expansion absorbs advanced surgical instruments and patient monitoring equipment. Public procurement scale across Saudi Arabia and South Africa anchors volume contracting for infection control consumables. Regulatory tightening by SFDA and SAHPRA filters supplier pools while compressing qualification timelines.
Saudi Arabia
Greenfield medical cities in Riyadh absorb advanced surgical suites and diagnostic imaging systems. SFDA sterilization audits compress supplier qualification windows, forcing procurement teams to pre-validate alternative vendors. The King Abdullah Financial District cluster anchors centralized Ministry of Health procurement platforms that aggregate demand across hospital networks.
United Arab Emirates
Private clinic expansion in Dubai and Abu Dhabi creates premium product pull for orthopedic and surgical equipment segments. MOHAP traceability mandates for sterile barrier packaging compel suppliers to harmonize documentation with serialization requirements. Dubai Healthcare City concentrates ambulatory surgical center proliferation where disposable instrument demand eliminates reprocessing overhead.
South Africa
Public hospital networks scale procurement of infection control consumables through centralized tender mechanisms. SAHPRA's upgraded quality management system requirements filter non-compliant imports while extending device registration timelines. The Johannesburg-Pretoria metropolitan corridor anchors domestic distributor investment in cold-chain verification capabilities.
Egypt
Public tenders for basic patient care supplies and hospital furniture prioritize domestic assembly requirements over import specifications. The country's drug authority applies convergent standards for sterile barrier packaging that align with Gulf state frameworks. Cairo's hospital network expansion drives demand for general ward equipment on high-turnover procurement cycles.
Kenya
Public health system fragmentation creates first-mover opportunities for regional distributors before government tender formalization. General functional descriptors for the national pharmaceutical regulator apply quality management expectations to imported medical devices. Nairobi anchors East African supply chain consolidation where underpenetrated procurement platforms lag Gulf state sophistication.
Middle East and Africa Hospital Supplies Market Competitive Landscape
Multi-source procurement dominates the current landscape as health systems diversify vendor relationships to reduce supply vulnerability. The vendor base organizes around three tiers: multinational manufacturers with direct ministry relationships, regional distributors managing cold-chain verification, and specialized wholesalers serving fragmented clinic networks. Consolidated procurement platforms and sterilization standard tightening represent the two dominant competitive pressures reshaping channel structures.
Among diversified health technology conglomerates, Becton, Dickinson and Company and Cardinal Health exemplify archetypes anchored in diagnostic consumable flows and centralized public network contracts respectively. Stryker occupies a position within the orthopedic and surgical equipment specialization tier where private clinic expansion in premium Gulf markets creates differentiated demand. These three entities represent distinct strategic postures: consumable volume anchoring, procurement platform integration, and premium segment surgical focus.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Cardinal Health Inc. |
| General Electric Company (GE Healthcare) |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Invacare Corporation |
| Koninklijke Philips N.V. |
| Siemens Healthcare Private Limited |
| Medtronic |
| Others |
Supply & Pricing Matrix
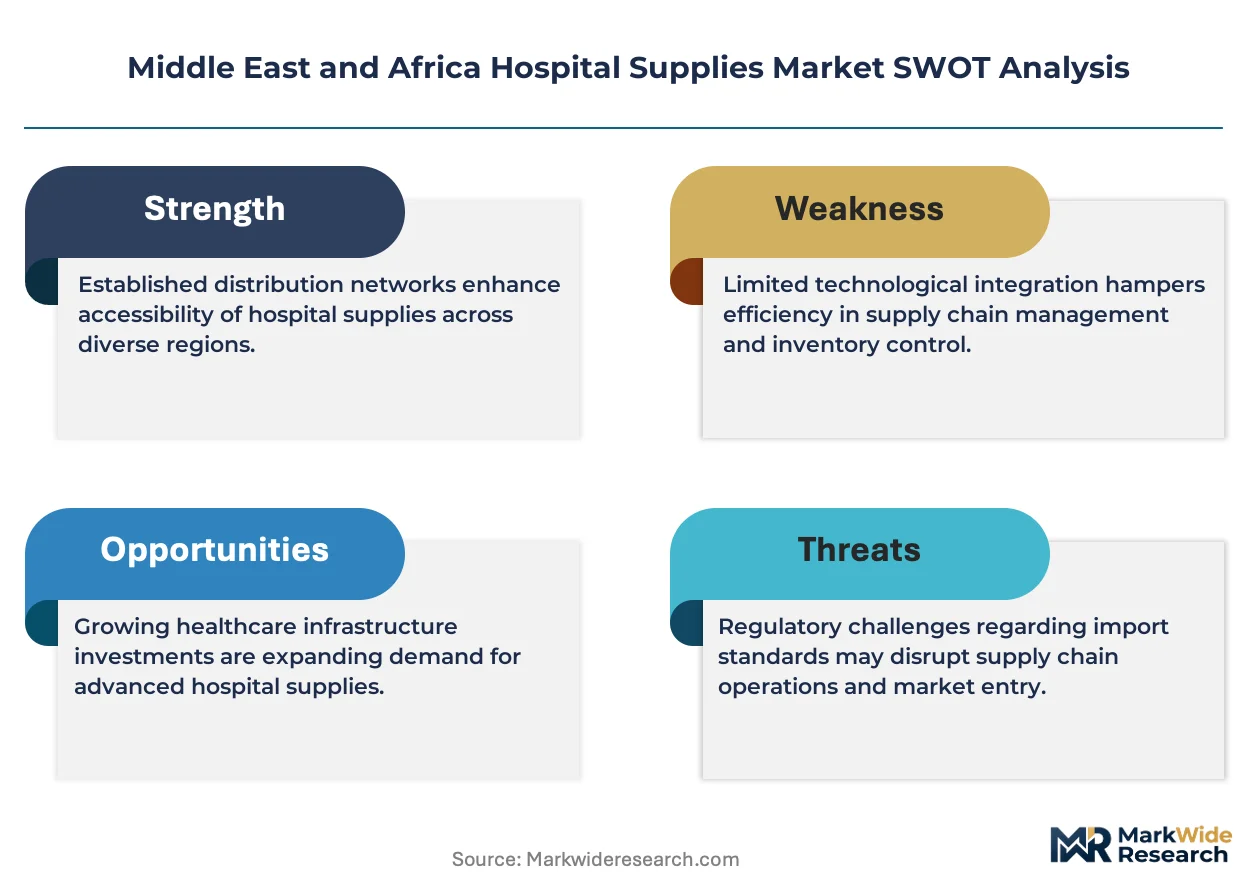
SFDA sterilization audits and SAHPRA quality management system requirements gate qualified supply access while anchoring premium-tier pricing for compliant manufacturers serving Gulf and South African hospital networks.
Pricing Analysis
Volume turnover concentrates in consumables where procurement auctions compress margins, while premium margins anchor equipment and surgical instruments sold through direct ministry relationships. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified manufacturers from regional distributors and gray-market suppliers. Cost compression in standard-tier consumables is intensifying because Saudi MOH centralized platforms aggregate demand and extract price concessions. Public hospital procurement committees demonstrate highest price sensitivity, whereas private clinic networks in Dubai and Abu Dhabi absorb premium markups for advanced surgical suites.
Supply Chain Analysis
Biomedical engineering talent scarcity in Egypt and Nigeria constrains maintenance capacity for patient monitoring equipment, forcing hospitals to outsource service contracts at premium rates. Manufacturing concentration rests on Germany and Singapore for ISO 10993 biocompatibility testing, Western Europe for Tyvek and medical-grade sterilization substrates, and China for basic consumable production. Single-source vulnerability in sterilization film supply exposes Gulf distributors to customs delay risks. Distribution runs through regional wholesalers with cold-chain verification capabilities serving fragmented clinic networks, while direct sales channels bypass intermediaries for capital equipment tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart infusion pump connectivity is displacing legacy medication administration workflows across Saudi tertiary hospitals, compressing training cycles and reducing adverse event liability exposure.
For Market Incumbents: Acquire cold-chain verification infrastructure to defend against SAHPRA sterilization standard tightening and SFDA audit compression. Backward integration into sterilization barrier packaging production reduces dependency on Western European Tyvek suppliers. Lock in multi-year centralized procurement contracts with Saudi MOH and UAE Ministry of Health before qualification windows narrow further.
For New Entrants and Emerging Players: Launch via e-procurement platforms targeting underpenetrated East African markets in Ethiopia and Kenya before government tender formalization completes. Anchor supply contracts with regional distributors serving fragmented public health systems lacking centralized platforms. Prioritize disposable surgical instrument kits for ambulatory surgical centers in Johannesburg and Abu Dhabi where throughput maximization eliminates reprocessing overhead.
For Investors and Strategic Acquirers: SAHPRA device establishment licensing framework extensions are the leading indicator that compliance cost absorption will consolidate South African distributor tiers toward better-resourced competitors. Long-term viability centers on manufacturers with integrated pharmacovigilance capabilities and local authorized representative infrastructure. Target acquisition candidates with RFID instrument tracking pilots and MOHAP serialization-ready labeling systems.
| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Device Establishment Licensing | Foreign manufacturers must designate local authorized representatives with pharmacovigilance capabilities. |
| MOHAP Traceability Mandate Compliance | Serialization requirements for sterile barrier packaging create first-mover advantage for integrated labeling systems. |
| RFID Surgical Instrument Tracking Pilot | Saudi private hospital groups pilot reprocessing cost reduction via automated instrument lifecycle management. |
| Centralized Procurement Platform Integration | Volume commitments extract price concessions while squeezing margins for fragmented clinic-dependent wholesalers. |
| Cold-Chain Verification Infrastructure Investment | Domestic distributors absorb compliance costs or surrender product lines to competitors with verified capabilities. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings for this Middle East and Africa hospital supplies analysis. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from SFDA registration filings, SAHPRA quality management system records, and customs trade data. Bottom-up demand modeling across consumable turnover rates and capital equipment replacement cycles triangulates with top-down healthcare expenditure allocation estimates.
Comparable-period anchoring to historical procurement auction volumes and ministry tender award patterns stabilizes the forecast framework across the projection horizon. Segmentation dimensions modeled include product durability tier, care setting intensity, application regulatory intensity, and procurement sophistication level. CAGRs derive from weighted average of equipment replacement cycles and consumable consumption rates. Forecast inputs incorporate ambulatory surgical center proliferation trajectories and sterilization standard tightening timelines.
The model assumes a particular technology adoption path; alternative pathways for smart infusion pump interoperability standards would alter the outlook. Forecasts reflect assumptions regarding SFDA-SAHPRA regulatory reciprocity negotiations and Red Sea shipping disruption persistence. Material deviation in centralized procurement platform consolidation rates or biocompatibility testing laboratory capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Port Access Needles Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
South America Syringe Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Micro Vials Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Nasal Oxygen Cannula Market