
 Hirsutism Treatment Market | 2026-2036
Hirsutism Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hirsutism Treatment Market Outlook
Single-source reliance on branded hormonal APIs is decoupling as dermatology chains and hospital systems diversify procurement across laser OEMs and topical compounders. Merck & Co. sustains its position through captive manufacturing of anti-androgen active pharmaceutical ingredients. Alma Lasers Ltd. dominates the installed base of diode and Nd:YAG platforms across premium dermatology centers in North America and Europe. Ajanta Pharma competes on cost-structured topical formulations distributed through emerging-market pharmacy networks.
Hirsutism treatment encompasses pharmacological, energy-based, and mechanical interventions targeting excessive terminal hair growth in androgen-sensitive skin regions, typically involving 755 nm alexandrite or 1064 nm Nd:YAG wavelengths for photothermal destruction of follicular stem cells. The primary commercial purpose centers on restoring patient-reported quality-of-life metrics in cases of idiopathic or endocrine-mediated hypertrichosis. Hormonal therapy retains the largest patient volume pool due to oral contraceptive and anti-androgen prescription patterns, though laser treatment captures disproportionate revenue per procedure across cash-pay aesthetic channels. Home care as an end-user category is expanding fastest, fueled by FDA-cleared intense pulsed light devices and direct-to-consumer electrolysis hardware.
FDA 510(k) clearances govern laser and radiofrequency device commercialization, while EMA marketing authorizations shape anti-androgen drug access across European Union member states. REACH compliance constrains mercury-based electrolysis equipment imports, redirecting procurement toward solid-state and galvanic alternatives. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether nurse practitioners or aestheticians may independently operate energy-based hair removal platforms.
Market Dynamics
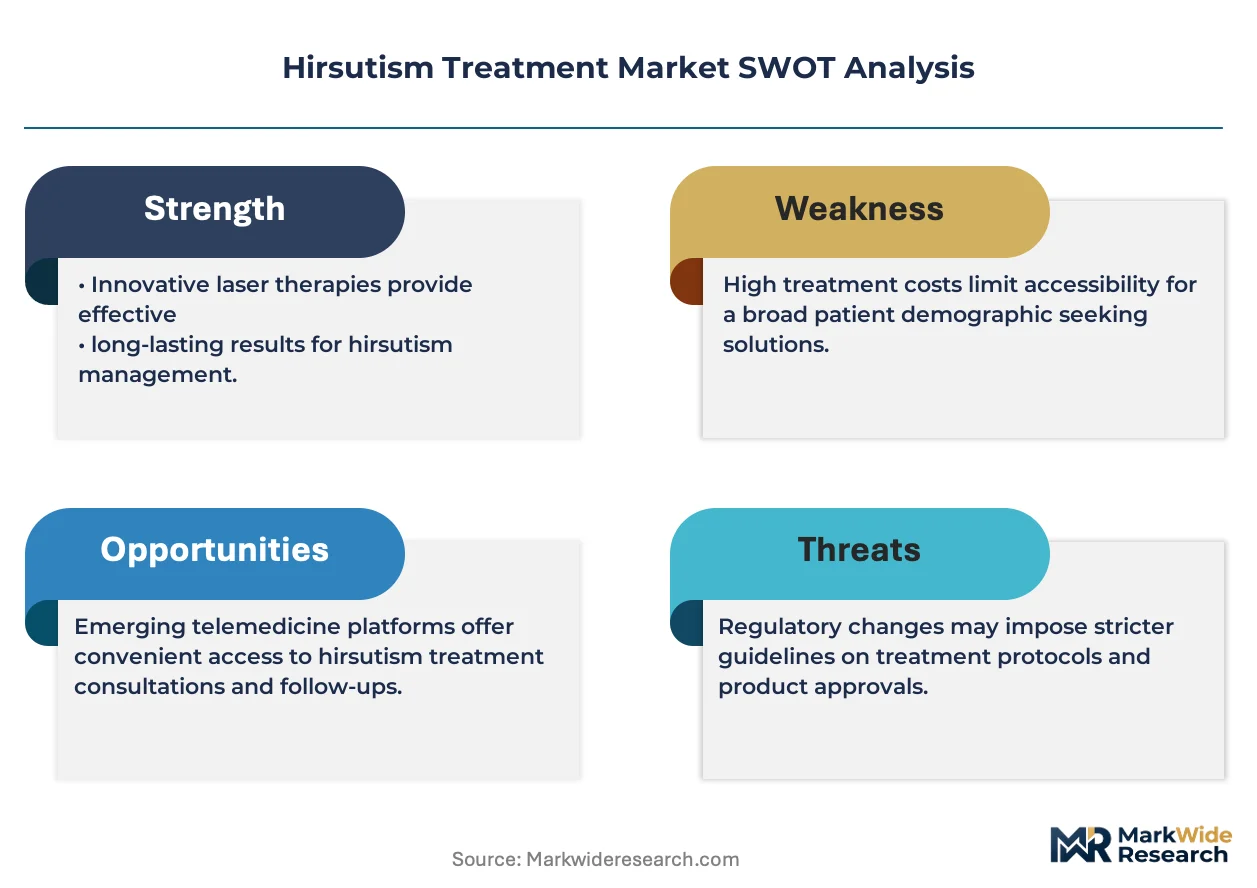
Combination protocols integrating hormonal modulation with energy-based devices are consolidating patient journeys into single-provider ecosystems, pressuring standalone topical or laser-only service lines to merge capabilities or exit.
Growth Catalysts
- Home-use IPL devices:FDA 510(k) clearances for intense pulsed light systems are expanding addressable patient populations beyond clinical settings into direct-to-consumer channels.
- REACH compliance:Mercury-based electrolysis equipment restrictions across European Union member states are redirecting procurement toward solid-state and galvanic alternatives, stimulating equipment replacement cycles.
- Dermatology center expansion:Aesthetic medicine infrastructure in the United States is absorbing combination protocols into service menus, capturing patients seeking consolidated care pathways.
Market Restraints
- Branded API concentration:Single-source reliance on captive anti-androgen manufacturing creates supply vulnerability when primary producers face production interruptions.
- Laser OEM oligopoly:Diode and Nd:YAG platform supply concentrates among premium equipment manufacturers, limiting price negotiation leverage for mid-tier dermatology chains.
- Reimbursement fragmentation:Hormonal therapy coverage dialogues remain institution-specific in the United States, creating cash-pay barriers for oral contraceptive and anti-androgen prescriptions.
Strategic Opportunities
- Topical compounding networks:Cost-structured formulation distribution through emerging-market pharmacy channels opens volume access where branded hormonal therapy remains unaffordable.
- Nurse practitioner scope expansion:State-level regulatory evolution in the United States permitting independent operation of energy-based platforms unlocks labor pool expansion for cash-pay aesthetic channels.
- Radiofrequency convergence:Integration of RF energy with traditional photothermal wavelengths is creating next-generation combination devices targeting resistant terminal hair types.
Industry Challenges
- Electrolysis technician certification:Galvanic and thermolysis modalities require specialized training pipelines that lag behind equipment innovation cycles, constraining service scaling.
- 510(k) pathway duration:FDA clearance timelines for novel laser wavelengths or RF parameters compress competitive entry windows for device innovators.
- Protocol integration complexity:Synchronizing hormonal therapy timing with laser treatment windows demands clinical coordination systems that fragment across electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hirsutism Treatment Market |
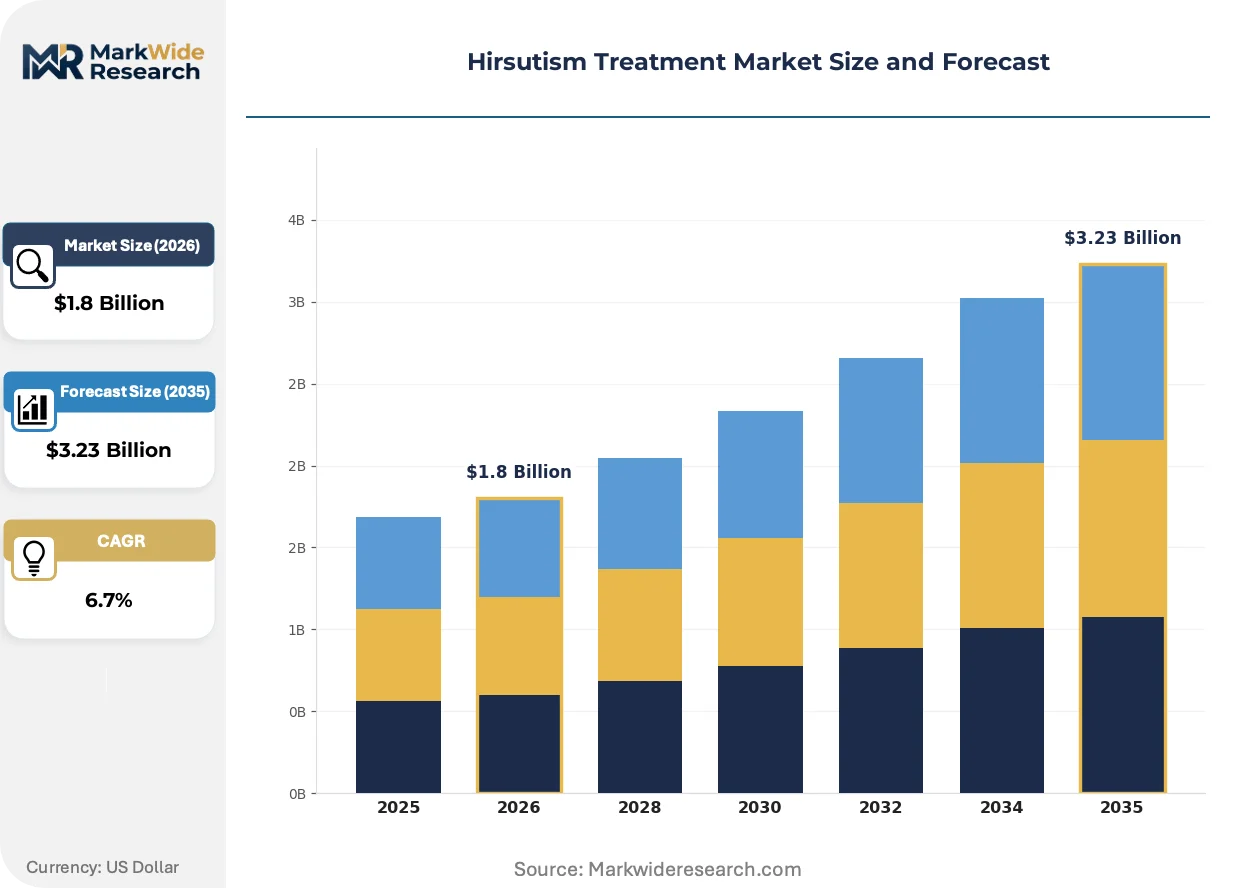
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Laser Treatment, Electrolysis, Topical Creams End User: Clinics, Dermatology Centers, Hospitals, Home Care Technology: Intense Pulsed Light, Radiofrequency, Pulsed Dye Laser, Diode Laser Distribution Channel: Online Pharmacies, Retail Pharmacies, Direct Sales, Hospital Pharmacies |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Bayer AG, AbbVie Inc., Cynosure Inc., Lumenis Inc., Alma Lasers Ltd., Ajanta Pharma, Cutera Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hirsutism Treatment Market Strategic Shifts
Device architecture and service delivery models are converging around patient-controlled treatment cadences and protocol bundling, compressing the traditional separation between clinical and home-based care.
Fractional RF microneedle systems are modularizing the energy delivery stack by separating depth control, thermal dose, and pulse sequencing into independently adjustable parameters. Premium dermatology centers in Germany and South Korea are adopting these platforms for resistant facial hirsutism cases previously managed through electrolysis. This architecture is modularizing vendor lock-in by enabling cross-manufacturer handpiece compatibility and open-protocol software updates.
EMA marketing authorization harmonization for anti-androgen drug access is compressing cross-border prescription variability across European Union member states. The centralized procedure is reducing national regulatory fragmentation that previously delayed topical spironolactone formulations in peripheral markets. Dermatology chains operating across France, Italy, and Poland are consolidating procurement under centralized pharmacy tenders as authorization pathways standardize.
Direct-to-consumer subscription models for home IPL devices are displacing single-transaction retail relationships with recurring revenue structures tied to consumable gel and replacement cartridge schedules. Aesthetic medicine e-commerce platforms in the United States are capturing patient data streams that feed back into personalized treatment protocol recommendations. This channel evolution concentrates highest visibility in urban coastal markets where digital health literacy and disposable income thresholds align.
Hirsutism Treatment Market Segmentation
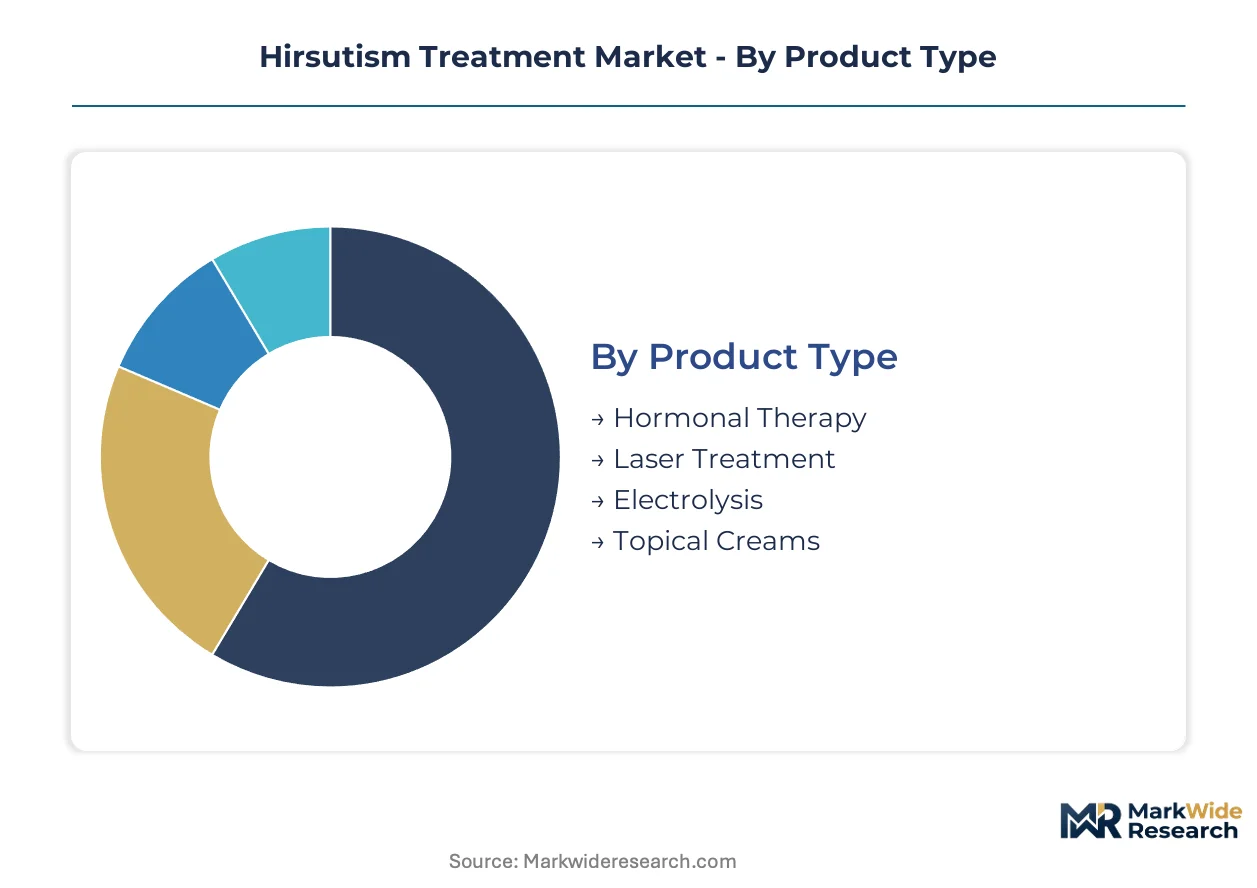
Treatment modality selection in hirsutism care hinges on integration depth — standalone hormonal protocols versus embedded energy-based systems within dermatology workflows. Segmentation reveals where procurement authority concentrates and which channels capture patient lifetime value across clinical and home-based settings.
Product Type:
Standalone hormonal formulations dominate prescription volume, while laser and electrolysis platforms embed into multi-service dermatology ecosystems.
- Hormonal Therapy:Oral contraceptives and anti-androgen compounds modulate androgen receptor sensitivity. Demand concentrates in United States institutional settings where reimbursement dialogues for spironolactone and finasteride remain fragmented.
- Laser Treatment:Photothermal platforms operating at 755 nm alexandrite or 1064 nm Nd:YAG wavelengths destroy follicular stem cells. United States premium dermatology centers absorb disproportionate revenue per procedure through cash-pay aesthetic channels.
- Electrolysis:Galvanic and thermolysis modalities target resistant terminal hair through direct current destruction.
- Topical Creams:Eflornithine-based formulations inhibit ornithine decarboxylase enzyme activity.
Volume placements concentrate in Hormonal Therapy; the faster expansion belongs to Laser Treatment.
End User:
Service delivery splits between institutional capture of combination protocols and direct-to-consumer bypass of clinical gatekeepers.
- Clinics:Independent aesthetic practices bundle hormonal consultation with laser packages. United States mid-tier chains face margin pressure as nurse practitioner scope expansion unlocks labor pool growth in cash-pay channels.
- Dermatology Centers:Premium multi-specialty facilities consolidate patient journeys through integrated hormonal and energy-based protocols. Germany and South Korea facilities adopt fractional RF microneedle systems for resistant facial cases.
- Hospitals:Academic medical centers manage complex endocrine-mediated hirsutism through reproductive endocrinology referrals.
- Home Care:FDA 510(k)-cleared IPL devices and electrolysis hardware displace single-transaction retail with subscription consumable models. United States urban coastal markets show highest digital health literacy alignment.
Revenue per patient peaks at Dermatology Centers; Home Care is climbing the fastest.
Technology:
Energy delivery architectures differentiate by penetration depth, thermal dose control, and compatibility with varying skin phototypes.
- Intense Pulsed Light:Broad-spectrum flashlamp systems target melanin-rich follicles across 500-1200 nm wavelengths. Home-use IPL devices expand addressable populations beyond clinical settings into direct-to-consumer channels.
- Radiofrequency:Electromagnetic energy generates dermal heating independent of melanin absorption. Next-generation platforms integrate RF with photothermal wavelengths for resistant terminal hair types.
- Pulsed Dye Laser:585-595 nm yellow light targets vascular components within follicular units.
- Diode Laser:800-810 nm semiconductor sources balance penetration depth with epidermal safety margins.
Installed base dominance sits with Diode Laser; steepest expansion trajectory belongs to Radiofrequency.
Distribution Channel:
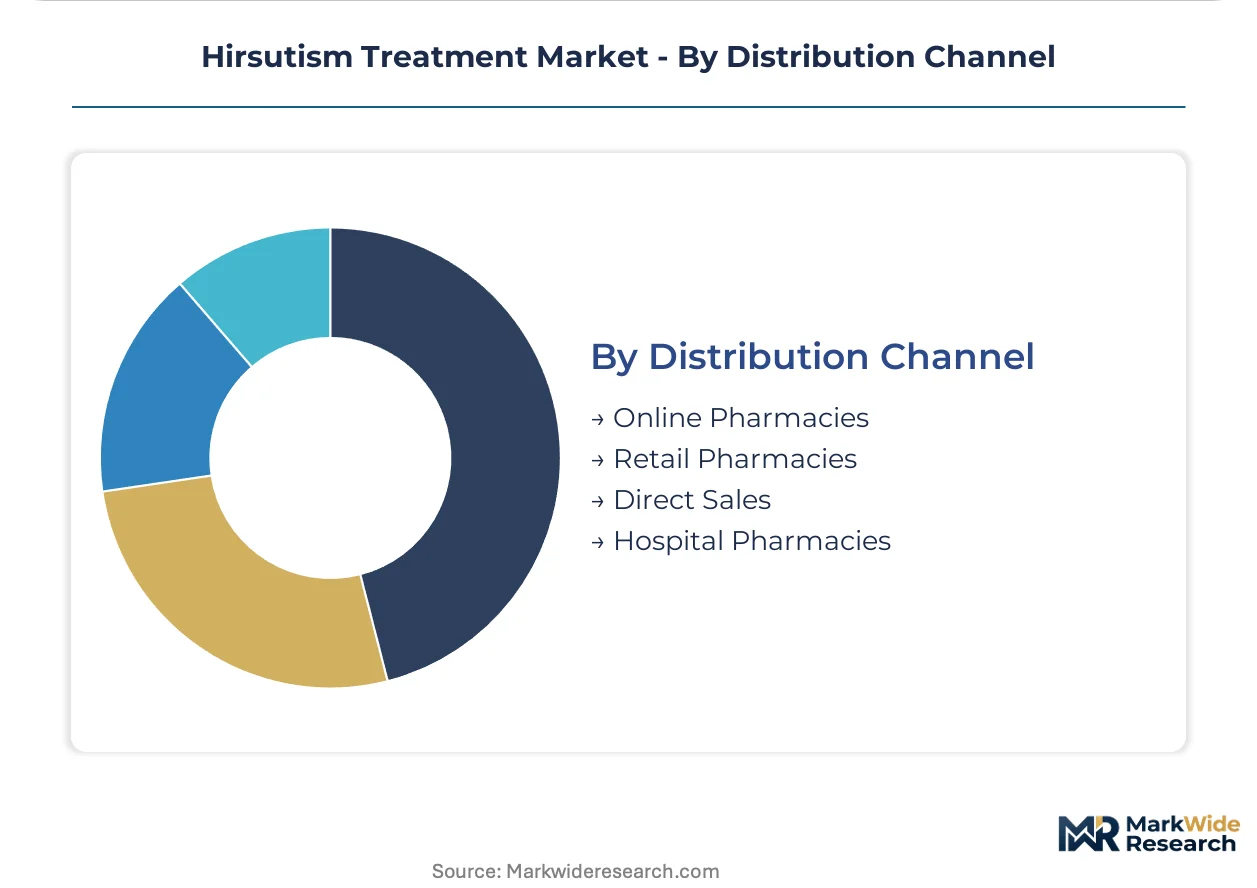
Channel selection determines patient data capture, protocol adherence monitoring, and recurring revenue attachment rates.
- Online Pharmacies:Digital platforms aggregate topical compounded formulations and home-use devices. Emerging-market pharmacy networks open volume access where branded hormonal therapy remains unaffordable.
- Retail Pharmacies:Brick-and-mortar chains dispense oral contraceptives and prescription topicals through traditional prescription workflows.
- Direct Sales:OEM-controlled channels for laser and RF equipment bypass distributor markups for premium dermatology center procurement.
- Hospital Pharmacies:Captive procurement for academic medical center endocrinology and dermatology departments.
Transaction volume concentrates in Retail Pharmacies; Online Pharmacies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anti-androgen active pharmaceutical ingredient production concentrates in the United States and Germany, while laser device manufacturing clusters in Israel and South Korea. These localities anchor supply-side capacity for hormonal therapies and energy-based platforms respectively.
United States
Dermatology center expansion and nurse practitioner scope liberalization drive procedural volume growth. FDA 510(k) clearances for home-use IPL devices are expanding direct-to-consumer channels. Premium multi-specialty facilities in Manhattan and Los Angeles consolidate combination protocols into integrated care pathways.
Germany
Fractional RF microneedle adoption for resistant facial hirsutism cases propels device demand. EMA centralized marketing authorization procedures harmonize anti-androgen access across EU member states. Aesthetic medicine clusters in Munich and Hamburg adopt modular energy delivery platforms with cross-manufacturer handpiece compatibility.
South Korea
Advanced dermatology infrastructure and high aesthetic medicine penetration support energy-based device uptake. MFDS device approvals align with export-oriented manufacturing strategies. Seoul-based dermatology chains pioneer protocol bundling that synchronizes hormonal consultation with laser treatment scheduling.
India
Cost-structured topical formulation demand expands through emerging-market pharmacy networks. CDSCO regulatory pathways for compounded hormonal therapies create distribution flexibility. Mumbai and Hyderabad anchor generic API production that supplies regional compounding operations.
Israel
Laser OEM concentration and photonics expertise sustain premium equipment export competitiveness. Ministry of Health device regulations align with FDA and CE marking standards for streamlined global market access. Tel Aviv-area manufacturing clusters supply diode and Nd:YAG platforms to North American and European dermatology centers.
Hirsutism Treatment Market Competitive Environment
Global majors compete with regional champions across hormonal API manufacturing and energy-based device fabrication, producing a tiered structure where captive pharmaceutical production sits alongside specialized laser OEM supply. Three archetypes dominate: multinational pharmaceutical conglomerates with anti-androgen manufacturing capabilities, premium laser equipment specialists with installed base advantages, and emerging-market topical compounders competing on cost-structured distribution. Competitive moves concentrate on strategic partnerships between hormonal therapy prescribers and energy-based service providers, plus portfolio diversification into home-use device categories.
Among pharmaceutical conglomerates, Merck & Co., Inc. and Pfizer Inc. exemplify the API-integrated archetype, while Alma Lasers Ltd. occupies a position within the premium device manufacturer tier. Ajanta Pharma represents the cost-structured topical formulation specialist competing through emerging-market pharmacy network penetration.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Bayer AG |
| AbbVie Inc. |
| Cynosure Inc. |
| Lumenis Inc. |
| Alma Lasers Ltd. |
| Ajanta Pharma |
| Cutera Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA 510(k)-cleared laser platforms and uncertified home-use alternatives manifests in both pricing power and procurement pathways. Premium dermatology centers absorb diode and Nd:YAG systems through direct OEM relationships, while cost-structured topical compounders route through emerging-market pharmacy networks.
Pricing Analysis
Service-bundling separates premium dermatology centers that wrap laser protocols with hormonal consultation from standalone device retailers. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and after-sales support depth. Cost compression in the home-use IPL segment is intensifying because direct-to-consumer subscription models displace single-transaction retail. Mid-tier dermatology chains show highest price sensitivity due to laser OEM oligopoly constraints.
Supply Chain Analysis
Regional distribution centers in Israel and South Korea anchor hub-and-spoke patterns for laser platform fulfillment. Manufacturing concentrates in Israel for diode and Nd:YAG systems, Germany for fractional RF microneedle devices, and India for generic anti-androgen APIs. Component sourcing draws from semiconductor foundries in Taiwan, optical crystal suppliers in Russia and China, and precision motion control vendors in Japan. Single-source vulnerability in alexandrite crystal supply creates chokepoint exposure. Distribution runs through direct OEM sales for premium equipment and online pharmacy networks for compounded topicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hirsutism treatment market sits in a technology-transition phase where radiofrequency-integrated platforms displace legacy photothermal-only systems. RF convergence with traditional wavelengths is reshaping competitive positioning across premium dermatology centers.
For Market Incumbents: Hedge against home-use IPL displacement by deepening service-bundling capabilities that combine hormonal consultation with energy-based protocols. Captive manufacturing of anti-androgen APIs at Merck & Co. and similar conglomerates provides margin insulation against topical compounder erosion. Laser OEMs should expand nurse practitioner training pipelines to capture labor pool growth in cash-pay aesthetic channels.
For New Entrants and Emerging Players: Compounding pharmacy networks in emerging markets offer the most penetrable white-space for cost-structured topical formulations. Direct-to-consumer subscription models for home-use devices present secondary entry angles where digital health literacy and disposable income thresholds align. A go-to-market strategy anchored in FDA 510(k) clearance acceleration unlocks addressable population expansion beyond clinical settings.
For Investors and Strategic Acquirers: Re-rating potential sits with fractional RF microneedle specialists given EMA marketing authorization harmonization compressing cross-border prescription variability. Long-term viability across the analysis window favors device manufacturers with modular energy delivery architectures enabling cross-manufacturer handpiece compatibility. Watch FDA 510(k) clearance timelines for novel RF parameters as the inflection signal for competitive entry windows.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Expands addressable populations into direct-to-consumer channels for home-use IPL devices. |
| Combination Protocol Integration | Consolidates patient journeys into single-provider ecosystems at premium dermatology centers. |
| EMA Marketing Authorization Harmonization | Reduces national regulatory fragmentation delaying topical spironolactone access. |
| Nurse Practitioner Scope Expansion | Unlocks labor pool growth for cash-pay aesthetic channels in state-level regulatory evolution. |
| Backward Integration into Anti-Androgen API Production | Insulates margin position against topical compounder cost competition. |
Study Parameters
Document review covered FDA 510(k) filings, EMA marketing authorization submissions, and REACH compliance directives, complemented by interviews with dermatology center procurement directors, laser OEM product managers, compounding pharmacy network operators, and reproductive endocrinology clinic administrators. Secondary validation drew from hospital procurement databases, GPO contracts, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated against top-down pharmaceutical API production data.
Segment-level outputs across the projection horizon reflect modeled treatment modality splits, end-user channel shares, and technology adoption curves. The analytical framework incorporated hormonal therapy prescription patterns, laser platform installed base growth, and home-use device penetration trajectories. CAGRs derived from regression analysis of historical procedure volumes and pharmaceutical shipment data, cross-referenced against reimbursement policy evolution and regulatory clearance timelines.
Caveats apply where FDA 510(k) pathway duration extensions or EMA authorization delays could materially shift the outlook. Forecasts reflect documented assumptions regarding nurse practitioner scope liberalization and REACH compliance enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Body Contouring Market