
 Powder-Free Disposable Medical Gloves Market | 2026-2036
Powder-Free Disposable Medical Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Powder-Free Disposable Medical Gloves Market Insights
Hospital procurement consortiums is rewriting purchasing dynamics for powder-free disposable medical gloves. Top Glove Corporation Bhd leverages integrated nitrile production lines to anchor supply contracts with large integrated delivery networks. Hartalega Holdings Berhad differentiates through thin-gauge high-dexterity formulations that command premium positioning in surgical segments. Cardinal Health controls extensive North American distribution infrastructure, competing on logistics reliability rather than manufacturing scale.
Powder-free disposable medical gloves are single-use hand protection devices manufactured without cornstarch or other donning powders, typically produced through dipped latex coagulation or synthetic polymer extrusion with chlorinated or polymer-coated inner surfaces to reduce surface friction. These gloves serve primarily to prevent cross-contamination between healthcare workers and patients during examination, surgical, or diagnostic procedures. Nitrile formulations now dominate new capacity investments due to latex allergy prevalence and superior chemical resistance, while biodegradable segments attract pilot interest though cost structures remain prohibitive for mass hospital adoption. Examination applications generate the highest volume throughput, though surgical-grade specifications retain concentrated margin pools due to stringent ASTM and EN certification requirements.
FDA enforcement of powder-ban provisions under 21 CFR 880.6250 eliminates legacy powdered inventory from US clinical settings, while EMA MDR requirements and REACH chemical compliance shape European import specifications for accelerator residues. The EU F-Gas Regulation indirectly affects nitrile production through controlled substance tracking in synthetic rubber polymerization cooling systems. Stakeholders must monitor evolving biodegradability certification standards and regional accelerator-free claims to avoid mislabeling exposure in regulated markets.
Market Dynamics
FDA powder-ban enforcement under 21 CFR 880.6250 has eliminated legacy powdered inventory from US clinical settings, forcing wholesale manufacturing retooling toward chlorinated inner surfaces and polymer coatings while Malaysian production clusters absorb capacity migration from latex-dependent facilities.
Growth Catalysts
- Accelerator-free latex formulations:EMA MDR chemical residue limits are compelling European hospital procurement to specify reduced-thiuram and carbamate-free gloves, opening premium positioning for compliant manufacturers.
- Nitrile chemical resistance superiority:Oncology units and chemotherapy handling protocols specify nitrile examination gloves exclusively, creating dedicated demand pools insulated from latex price volatility.
- Thailand:Integrated glove manufacturing clusters near Rayong and Surat Thani offer captive nitrile butadiene rubber supply chains with port-adjacent logistics infrastructure serving North American bulk orders.
Market Restraints
- Acrylonitrile price volatility:Nitrile glove margins compress when petrochemical feedstock costs spike, as synthetic rubber polymerization lacks short-term input substitution options.
- Malaysian supply concentration:Overreliance on Klang Valley production corridors creates single-point vulnerability to flooding, labor disputes, or energy rationing events.
- Biodegradability cost premium:Compostable glove formulations require PLA or PBAT blending that doubles unit economics versus standard nitrile, blocking mass hospital adoption.
Strategic Opportunities
- Indonesia:Domestic glove consumption lags regional peers despite population scale, presenting greenfield distribution partnerships with Jakarta and Surabaya hospital networks.
- Home healthcare expansion:Post-acute care settings and dialysis-at-home programs generate recurring glove demand outside traditional hospital procurement channels.
- EU F-Gas Regulation compliance:Controlled substance tracking in synthetic rubber cooling systems creates certification barriers that favor incumbent Malaysian and Thai producers with established environmental management systems.
Industry Challenges
- ASTM D6319 surgical-grade certification timelines:New entrants face 18-24 month validation periods for tensile strength and viral penetration testing, delaying revenue recognition.
- Chlorination process wastewater treatment:Environmental permits for surface modification facilities require capital-intensive effluent neutralization systems that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder-Free Disposable Medical Gloves Market |
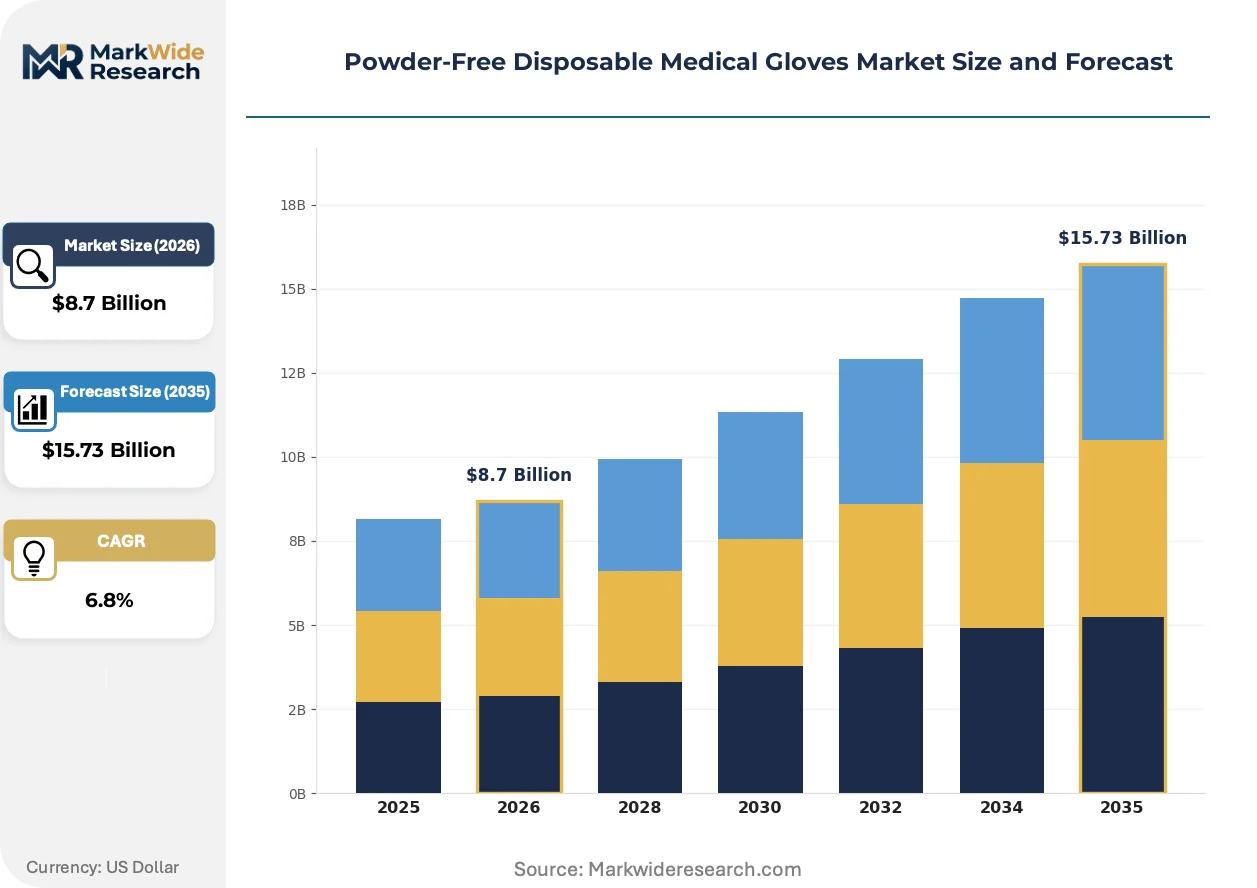
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Nitrile, Vinyl, Biodegradable End User: Hospitals, Clinics, Dental Offices, Laboratories Application: Examination, Surgical, Infection Control, Food Handling Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Ansell Ltd., Kossan Rubber Industries Bhd, Sri Trang Gloves PLC, Supermax Corporation Berhad, Semperit AG Holding, Cardinal Health, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder-Free Disposable Medical Gloves Market Trends and Innovations
Production-line automation and real-time quality monitoring systems are compressing defect rates while reshaping workforce skill requirements across Southeast Asian manufacturing bases. Three developments warrant particular attention.
Automated optical inspection systems with machine-learning defect classification are digitizing final glove quality verification, replacing manual visual checks in Hartalega and Top Glove facilities. Malaysian producers deploy these systems to meet ASTM pinhole rate specifications for surgical-grade certification. The technology is digitizing compliance documentation for FDA and EMA audits, reducing batch rejection risk.
REACH chemical compliance is tightening accelerator residue thresholds for European imports, forcing reformulation of sulfur-based vulcanization systems. Manufacturers serving EU markets now specify zinc diethyldithiocarbamate alternatives or peroxide curing methods. German hospital procurement consortiums have begun requiring third-party REACH attestation as a contract precondition, shifting competitive advantage toward integrated chemical laboratories.
Hospital procurement consortiums in North America are consolidating purchasing authority through integrated delivery networks, displacing fragmented distributor relationships. These entities negotiate multi-year supply agreements with volume guarantees and penalty clauses for stockout events. The concentration is most visible in Texas and California health systems, where three IDNs control over sixty percent of acute-care glove expenditure.
Powder-Free Disposable Medical Gloves Market Segmentation
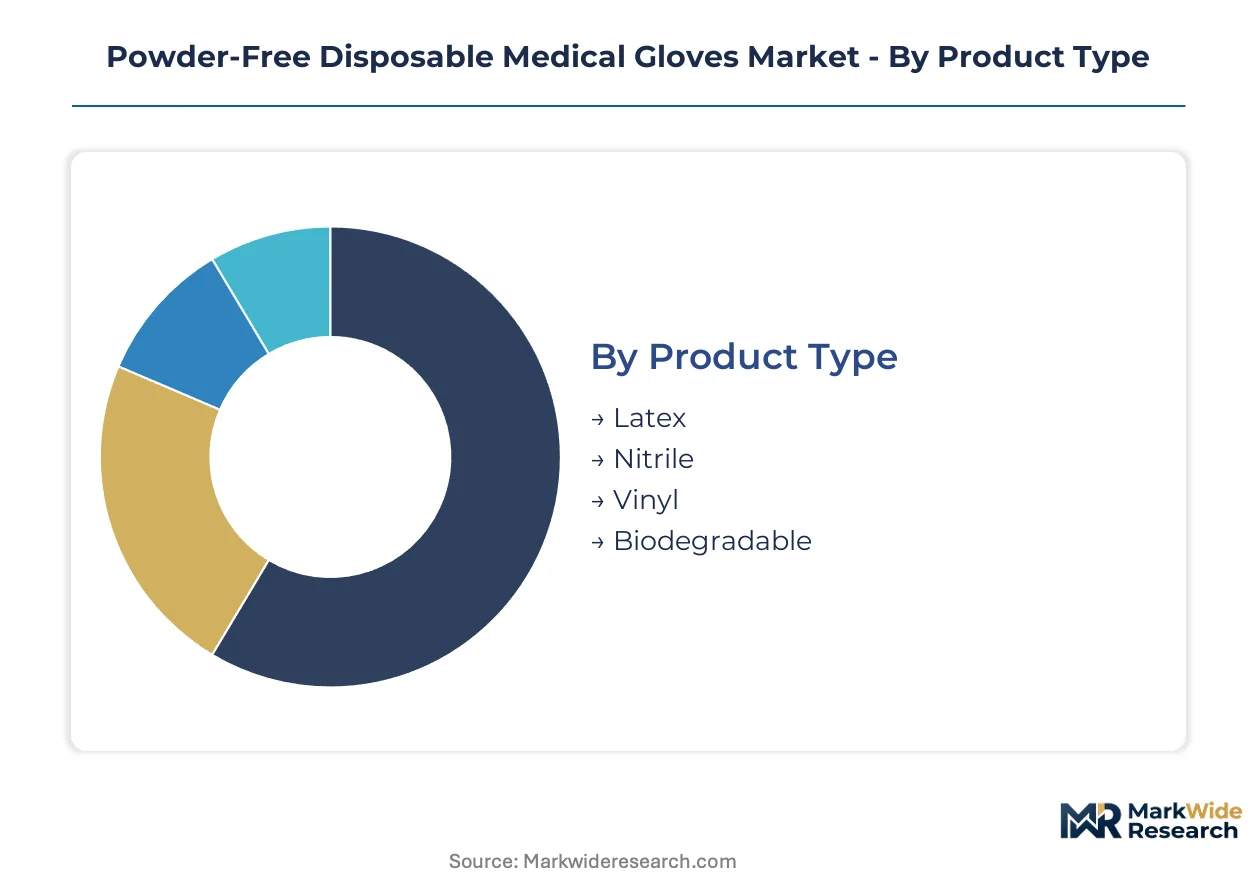
Segmentation in powder-free disposable medical gloves reveals how procurement cycles, clinical requirements, and supply chain configurations create distinct commercial pockets. Understanding these divisions exposes where volume concentrates versus where margin extraction succeeds.
Product Type:
Inventory velocity varies dramatically across material formulations, with examination-grade nitrile turning over fastest due to bulk hospital contracts while surgical latex sits longer in specialty distributor warehouses.
- Nitrile:Synthetic acrylonitrile-butadiene rubber formulation delivers superior puncture resistance and chemical protection against chemotherapy agents. Oncology units in US hospital systems specify nitrile exclusively, insulating demand from latex price swings while commanding stable contract premiums.
- Latex:Natural rubber formulation maintains dominance in surgical suites requiring maximum tactile sensitivity and elasticity. Malaysian producers accelerate transition to accelerator-free vulcanization to meet EMA MDR residue limits, with compliant batches capturing European hospital procurement at tiered premiums.
- Vinyl:Polyvinyl chloride composition offers lowest unit cost for low-risk examination tasks with minimal durability requirements.
- Biodegradable:PLA or PBAT blended formulations target sustainability mandates despite doubling unit economics versus standard nitrile.
Nitrile dominates installed base. Biodegradable is where expansion concentrates.
End User:
Procurement sophistication separates institutional buyers, with consolidated purchasing power reshaping contract structures across acute and ambulatory settings.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements with volume guarantees and stockout penalty clauses. Texas and California health systems concentrate over sixty percent of acute-care glove expenditure through three dominant IDNs.
- Clinics:Outpatient facilities purchase through group purchasing organizations with less stringent certification requirements than surgical settings.
- Dental Offices:Smaller-scale procurement relies on distributor relationships with higher per-unit costs offset by lower inventory carrying requirements.
- Laboratories:Research and diagnostic facilities specify chemical resistance profiles matching specific reagent handling protocols.
Hospitals anchor volume throughput. Laboratories show steepest expansion trajectory as diagnostic testing capacity scales.
Application:
Certification intensity creates tiered margin structures, with surgical-grade ASTM validation timelines stretching eighteen to twenty-four months versus rapid examination-grade qualification.
- Examination:General-purpose barrier protection for non-sterile patient contact drives highest unit volume through standardized EN 455 and ASTM D6319 specifications.
- Surgical:Sterile formulations meeting ASTM D3577 tensile strength and viral penetration standards retain concentrated margin pools due to stringent validation requirements and limited qualified supplier base.
- Infection Control:Isolation protocols and outbreak response generate surge demand with less price sensitivity than routine procurement.
- Food Handling:Non-medical applications escape FDA medical device regulations but face NSF and HACCP compliance for commercial kitchen deployment.
Examination commands volume leadership. Surgical captures premium positioning.
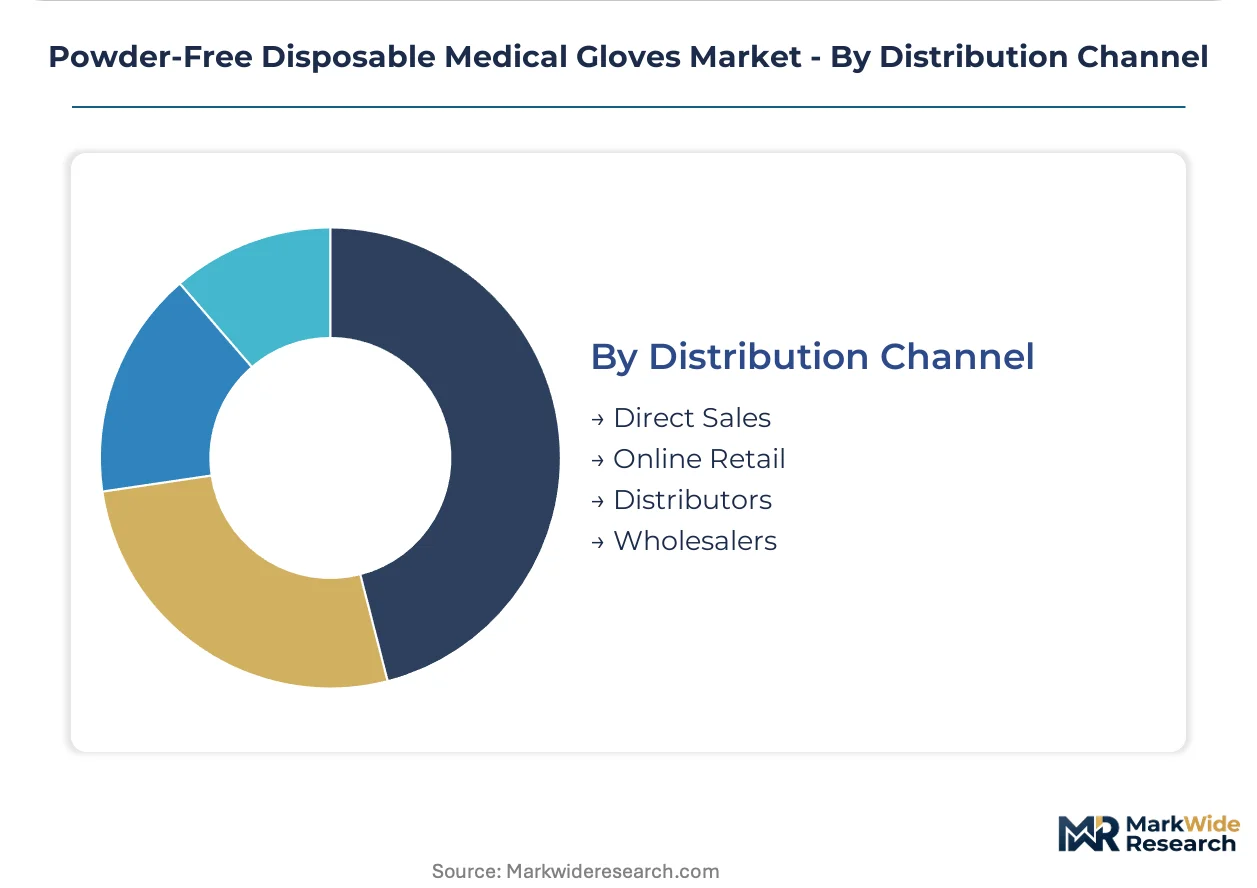
Distribution Channel:
Channel selection reflects buyer scale and urgency requirements, with direct contracts displacing fragmented relationships among large health systems.
- Direct Sales:Manufacturer relationships with IDNs and procurement consortiums eliminate distributor margins while enabling custom specification negotiation.
- Distributors:Cardinal Health and regional medical-surgical distributors maintain extensive North American logistics infrastructure competing on reliability rather than manufacturing scale.
- Wholesalers:Secondary supply channels serve smaller facilities with less predictable demand patterns and higher inventory carrying costs.
- Online Retail:E-commerce platforms capture dental and small clinic procurement with convenience positioning despite limited bulk pricing access.
Distributors retain installed base dominance. Direct sales channels are gaining share fastest as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA powder-ban enforcement under 21 CFR 880.6250 anchors North American demand patterns, while Malaysian production corridors and Thai manufacturing clusters supply the bulk of hospital procurement across multiple continents.
United States
Integrated delivery networks in Texas and California consolidate over sixty percent of acute-care glove expenditure through three dominant procurement entities. FDA enforcement of 21 CFR 880.6250 eliminates legacy powdered inventory from clinical settings, forcing wholesale manufacturing retooling toward chlorinated inner surfaces. Cardinal Health maintains extensive distribution infrastructure competing on logistics reliability rather than manufacturing scale.
Germany
Hospital procurement consortiums specify reduced-thiuram and carbamate-free gloves under EMA MDR chemical residue limits, opening premium positioning for compliant manufacturers. REACH chemical compliance tightens accelerator residue thresholds for European imports, forcing reformulation of sulfur-based vulcanization systems. German distributors now require third-party REACH attestation as a contract precondition.
Malaysia
Top Glove Corporation Bhd leverages integrated nitrile production lines to anchor supply contracts with large integrated delivery networks. Klang Valley production corridors concentrate global supply capacity, creating single-point vulnerability to flooding or labor disputes. Hartalega Holdings Berhad differentiates through thin-gauge high-dexterity formulations commanding premium positioning in surgical segments.
Thailand
Integrated glove manufacturing clusters near Rayong and Surat Thani offer captive nitrile butadiene rubber supply chains with port-adjacent logistics infrastructure. Sri Trang Gloves PLC and Supermax Corporation Berhad serve North American bulk orders through established environmental management systems. Domestic consumption lags regional peers despite population scale, presenting greenfield distribution partnership opportunities.
Indonesia
Jakarta and Surabaya hospital networks generate underpenetrated domestic demand relative to regional peers with comparable population scale. Post-acute care settings and dialysis-at-home programs create recurring glove demand outside traditional hospital procurement channels. Local distribution partnerships remain fragmented compared to Malaysian and Thai supply chain maturity.
Powder-Free Disposable Medical Gloves Market Competitive Landscape
Vertically integrated Southeast Asian producers and North American distribution specialists split the market into distinct capability tiers. Malaysian and Thai manufacturers control upstream nitrile butadiene rubber supply chains while competing on polymer formulation and certification velocity. The vendor base clusters around three archetypes: integrated chemical-to-glove producers, thin-gauge surgical specialists, and logistics-heavy distributors. Capacity expansion and REACH compliance certification represent the dominant competitive moves reshaping contract structures.
Within the integrated production tier, Top Glove Corporation Bhd and Hartalega Holdings Berhad exemplify divergent strategic positioning—one anchoring volume contracts through scale, the other commanding surgical-grade premiums through formulation precision. Cardinal Health occupies a distinct position as a North American distributor competing on reliability infrastructure rather than manufacturing ownership. These three entities represent the archetypal splits between upstream chemical integration, product specialization, and channel control.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Ansell Ltd. |
| Kossan Rubber Industries Bhd |
| Sri Trang Gloves PLC |
| Supermax Corporation Berhad |
| Semperit AG Holding |
| Cardinal Health |
| Kimberly-Clark Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals from Malaysian nitrile production corridors are compressing contract margins while simultaneously accelerating buyer consolidation through multi-year volume guarantees. Klang Valley manufacturers absorb utilization shocks by shifting spot inventory toward distributor channels, creating divergent pricing postures between committed hospital procurement and opportunistic spot purchasing.
Pricing Analysis
Malaysian export prices for examination-grade nitrile gloves run fifteen to twenty percent below Thai surgical-grade thin-gauge formulations, reflecting divergent certification intensities and polymer coating investments. Three-tier pricing structure across premium, standard, and economy levels separates accelerator-free latex surgical batches from chlorinated nitrile examination stock and vinyl low-durability alternatives. Cost compression in standard nitrile is intensifying because acrylonitrile feedstock volatility transfers directly into contract renegotiation clauses. Group purchasing organizations exhibit highest price sensitivity, while integrated delivery networks prioritize stockout penalty structures over unit cost minimization.
Supply Chain Analysis
EU F-Gas Regulation compliance requirements for controlled substance tracking in synthetic rubber cooling systems restrict technology transfer to uncertified facilities, favoring incumbent Southeast Asian producers with established environmental management systems. Supply concentrates in Malaysia, Thailand, and Indonesia, with Klang Valley corridors anchoring global nitrile butadiene rubber polymerization capacity. Raw material dependencies center on acrylonitrile monomer, natural rubber latex, and sulfur-based vulcanization accelerators. Single-source vulnerability concentrates in Malaysian energy infrastructure and port-adjacent logistics clusters. Distribution runs through Cardinal Health and regional medical-surgical distributors serving North American hospital networks with just-in-time replenishment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand fastest in sterilization validation and compliance documentation, where recurring certification support generates margin pools exceeding base glove economics. After-sales layers including batch traceability systems and regulatory audit preparation are capturing procurement preference among integrated delivery networks.
For Market Incumbents: Harden accelerator-free formulation capabilities to defend European hospital contracts against REACH compliance escalation, while expanding captive nitrile butadiene rubber production in Thai Rayong corridors to offset Malaysian concentration risk. Certification velocity serves as the critical lever—compressing ASTM D6319 validation timelines protects surgical-grade premium positioning against thin-gauge specialists. For New Entrants and Emerging Players: Indonesian domestic consumption gaps present white-space targets, with Jakarta and Surabaya hospital networks operating below regional penetration benchmarks despite comparable population scale. Dialysis-at-home programs and post-acute care settings offer secondary entry vectors outside consolidated hospital procurement channels. Greenfield distribution partnerships with local logistics operators bypass entrenched Malaysian supply chain dominance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chemical-to-glove producers with in-house REACH attestation laboratories and established FDA 510(k) submission track records. Long-term viability across the five-to-ten year window hinges on biodegradability certification positioning as compostable formulations approach cost parity. Acquisition targets should demonstrate environmental management system maturity and port-adjacent production footprints. The signal to monitor is EU F-Gas Regulation enforcement intensity affecting cooling system compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Free Formulation Transition | REACH MDR compliance secures European hospital procurement at tiered premiums. |
| Backward Integration into Nitrile Butadiene Rubber | Captive feedstock supply insulates margins from acrylonitrile price volatility. |
| Automated Optical Inspection Deployment | Machine-learning defect classification compresses ASTM pinhole rates for surgical certification. |
| Integrated Delivery Network Direct Contracts | Multi-year volume guarantees with stockout penalties displace fragmented distributor relationships. |
| Biodegradability Certification Investment | PLA and PBAT blending capabilities position for sustainability mandate acceleration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract disclosures, and Southeast Asian customs export records. Primary interviews engaged glove manufacturing plant managers, hospital purchasing committee directors, biomedical engineers specifying chemical resistance profiles, and group purchasing organization contracts managers. Bottom-up volume modeling triangulates against top-down expenditure analysis across acute-care and ambulatory settings.
Forecast inputs incorporate material formulation segmentation, end-user procurement sophistication tiers, application-grade certification requirements, and distribution channel concentration patterns across the analysis window. CAGRs derive from regression analysis against historical capacity utilization, regulatory enforcement intensity, and input cost trajectories. Modeled variables include nitrile versus latex formulation mix shifts, integrated delivery network consolidation velocity, and REACH accelerator residue threshold evolution.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, Malaysian ringgit exchange rates, or EU F-Gas Regulation enforcement would shift the trajectory. Forecasts assume stable FDA powder-ban enforcement and EMA MDR chemical residue limits. Material shifts in biodegradability certification standards or Thai production corridor energy infrastructure would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Suture Tapes Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Sterile Container Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market