
 Disposable Medical Gloves Market | 2026-2036
Disposable Medical Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Medical Gloves Market Intelligence
High-volume, standard-grade glove manufacturing is tilting profit pools toward producers with extreme economies of scale and captive raw material supply. This dynamic favors large-scale producers capable of managing input cost fluctuations. Top Glove Corporation Bhd leverages its immense production capacity to serve high-volume tenders. In contrast, Ansell Ltd differentiates its portfolio with specialized gloves for surgical and cleanroom environments, targeting higher-margin niches.
Disposable medical gloves are single-use protective barriers designed to prevent cross-contamination between caregivers and patients. These products, made from polymers like nitrile or latex, must meet specific quality benchmarks such as Acceptable Quality Level (AQL) for pinholes. Nitrile gloves continue to displace latex products due to allergenicity concerns. Demand from surgical applications requires sterile, high-tactility gloves, whereas diagnostic testing drives consumption of non-sterile examination gloves.
Market access is governed by stringent regulatory frameworks that ensure product safety and efficacy. The US FDA requires 510(k) premarket notification for most medical gloves, while the EU's Medical Device Regulation (MDR) imposes rigorous conformity assessments. These regulations, alongside ISO quality standards, set performance benchmarks for barrier protection. Navigating raw material price volatility while investing in automation will determine long-term competitive advantage.
Market Dynamics
The disposable medical gloves market is defined by tension between concentrated manufacturing in Southeast Asia and stringent regulatory demands from North American and European health authorities. This dynamic places a premium on scale and compliance.
Growth Catalysts
- Infection Control Mandates:Stricter protocols in hospitals and ambulatory surgical centers, aligned with WHO guidelines, compel higher glove consumption to mitigate cross-contamination.
- EU Medical Device Regulation (MDR):The EU's framework elevates quality standards, stimulating demand for certified gloves and forcing product upgrades across the supply chain.
- Diagnostic Laboratory Growth:Expanding diagnostic testing volumes in pathology labs directly increases the consumption of non-sterile examination gloves for routine procedures.
Market Restraints
- Raw Material Volatility:Price fluctuations in nitrile butadiene rubber (NBR) create significant margin pressure and forecasting challenges for producers reliant on Southeast Asian supply.
- Supply Chain Concentration:Heavy reliance on manufacturing in Malaysia and Thailand exposes the market to geopolitical risks and logistical disruptions affecting global supply continuity.
- Latex Allergenicity:Persistent hypersensitivity to natural rubber latex continues to drive substitution towards nitrile, constraining the addressable market for latex products.
Strategic Opportunities
- Biodegradable Polymers:Developing sustainable glove materials can meet green procurement mandates emerging within EU healthcare systems, creating a premium product tier.
- Factory Automation:Implementing Industry 4.0 in Malaysian and Thai plants reduces labor dependency, improves production consistency, and lowers long-term operational costs.
- High-Margin Surgical Niches:A market exists for gloves with enhanced tactility or antimicrobial coatings for specialized procedures like neurosurgery and ophthalmology.
Industry Challenges
- Regulatory Compliance Burden:Navigating the complex 510(k) premarket notification process with the US FDA and conformity assessments for the EU's MDR requires significant investment and expertise.
- Automation Capital Expenditure:High upfront costs for automating dipping lines and packaging systems present a financial hurdle for smaller manufacturers competing on scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Medical Gloves Market |
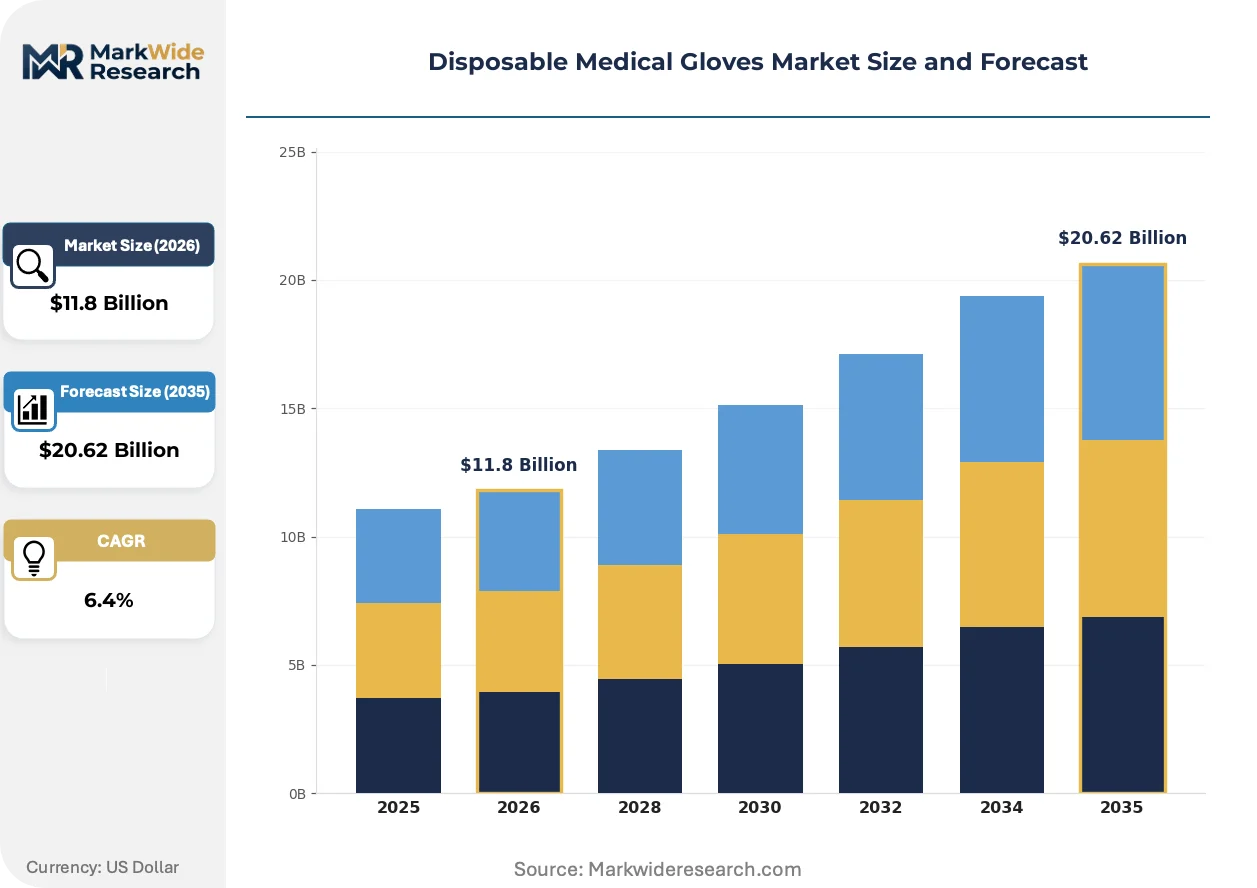
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Nitrile, Vinyl, Neoprene, Polyethylene Application: Surgical Procedures, Diagnostic Testing, Emergency Response, Dental Procedures, Food Handling End User: Hospitals, Diagnostic Laboratories, Dental Clinics, Home Care Providers, Ambulance Services Distribution Channel: Online Retailers, Medical Supply Distributors, Direct Sales, Pharmacies, Wholesale Suppliers |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Ansell Ltd, Kossan Rubber Industries Bhd, Cardinal Health, Medline Industries, Semperit AG Holding, McKesson Corporation, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Medical Gloves Market Strategic Shifts & Innovations
Material science advancements and regulatory pressures are accelerating a flight to quality and specialization. This shift creates clearer distinctions between commodity examination gloves and high-performance products, altering competitive dynamics.
Advanced nitrile formulations provide latex-like elasticity and comfort without the associated allergen risks. Healthcare systems and diagnostic labs are rapidly standardizing on these next-generation nitrile products for general examination purposes. This widespread adoption is collapsing the performance gap that previously justified the use of latex gloves in many non-surgical applications.
The US FDA's quality system requirements and enforcement of Acceptable Quality Level (AQL) standards are forcing manufacturers to tighten process controls. This regulatory scrutiny increases market access complexity, favoring larger producers with robust quality management systems. Examination glove importers targeting the US are most affected, needing to switch suppliers to ensure compliance.
Large hospital networks are consolidating purchasing through group purchasing organizations (GPOs) to leverage volume for better pricing. This trend marginalizes smaller distributors and favors large-scale manufacturers capable of fulfilling high-volume tenders. This procurement shift is most pronounced in the North American healthcare market.
Disposable Medical Gloves Market Segmentation
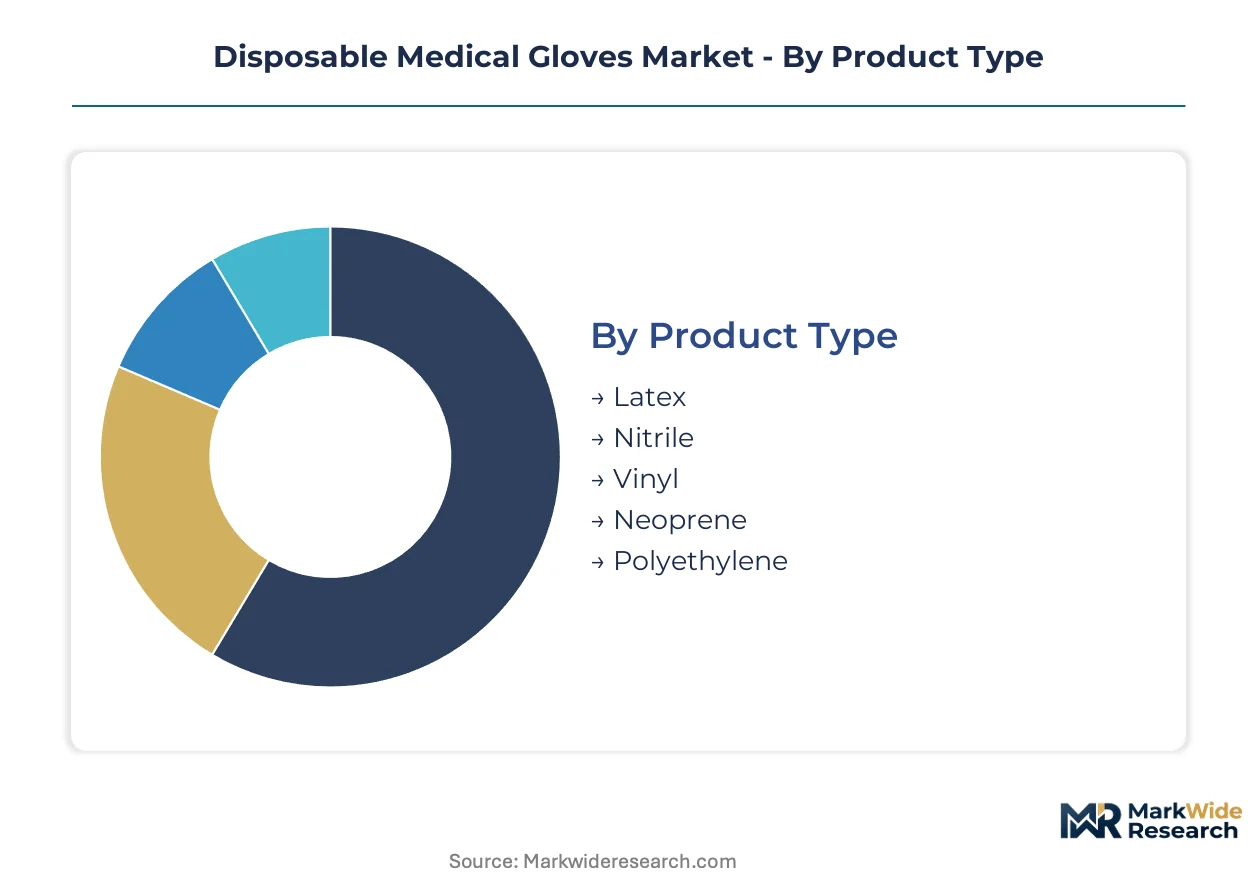
The disposable medical gloves market differentiates across material, application, end-user, and distribution channels. Understanding these segments is essential for manufacturers to tailor product development, pricing, and distribution. This granular segmentation reveals where value is created and competitive advantages are sustained.
Product Type:
The product type segment spans mature, established materials and newer, high-performance formulations that address specific user needs. Nitrile gloves are rapidly gaining dominance, while latex products face significant headwinds.
- Nitrile:These synthetic rubber gloves offer superior puncture resistance and chemical barrier protection without triggering natural rubber latex allergies. Demand concentrates heavily in diagnostic laboratories and hospitals across North America and Europe, driven by stringent infection control mandates.
- Latex:Derived from natural rubber, latex gloves provide excellent elasticity and tactile sensitivity, making them suitable for surgical applications. However, widespread allergenicity concerns have led to a steady decline in their market share, particularly in developed economies like Germany and the United Kingdom.
- Vinyl:Vinyl gloves, made from PVC, are cost-effective for low-risk, short-duration tasks.
- Neoprene:Neoprene gloves are a latex-free alternative with good elasticity and chemical resistance.
- Polyethylene:Lightweight and inexpensive, polyethylene gloves suit very brief, low-barrier tasks.
Latex handles the majority of throughput; Nitrile is the fastest mover on share.
Application:
The application segment delineates glove usage based on specific procedural requirements and risk profiles, ranging from sterile surgical environments to routine examination tasks. Each application demands distinct glove characteristics, influencing material choice and regulatory compliance.
- Diagnostic Testing:This category encompasses routine lab work, specimen handling, and patient examinations, primarily requiring non-sterile examination gloves. The expanding volume of pathology labs in countries like the United States and France drives significant consumption of standard-grade nitrile products.
- Surgical Procedures:These applications necessitate sterile, high-tactility gloves with exceptional barrier integrity for invasive medical interventions. Demand for specialized surgical gloves is robust in hospital operating rooms across major healthcare markets such as Canada and Australia.
- Emergency Response:First responders use gloves for protection during accident scenes and pre-hospital patient care.
- Dental Procedures:Dentists and hygienists use examination gloves for patient contact and instrument handling.
- Food Handling:Lower-grade gloves are used to prevent contamination in food preparation settings.
Diagnostic Testing applications consistently generate the largest consumption volumes.
End User:
The end-user segment reflects the diverse institutional and care settings that procure and utilize disposable medical gloves. Each user group possesses unique purchasing power, regulatory environments, and product specifications. This segmentation highlights distinct demand patterns.
- Hospitals:These large institutions represent the primary consumers of both sterile surgical and non-sterile examination gloves for a wide array of patient care activities. Group purchasing organizations in the US and Germany consolidate hospital procurement, influencing manufacturer strategies.
- Diagnostic Laboratories:Labs conducting clinical pathology, microbiology, and molecular diagnostics are high-volume users of non-sterile examination gloves. Growth in diagnostic testing services in countries like Japan and South Korea drives consistent demand for these essential barrier products.
- Dental Clinics:Dental practices routinely use examination gloves for patient contact and infection control measures.
- Home Care Providers:Professionals delivering care in home settings require gloves for patient safety and hygiene.
- Ambulance Services:Emergency medical personnel depend on gloves for protection during patient assessment and transport.
Hospitals remain the dominant procurement entity.
Distribution Channel:
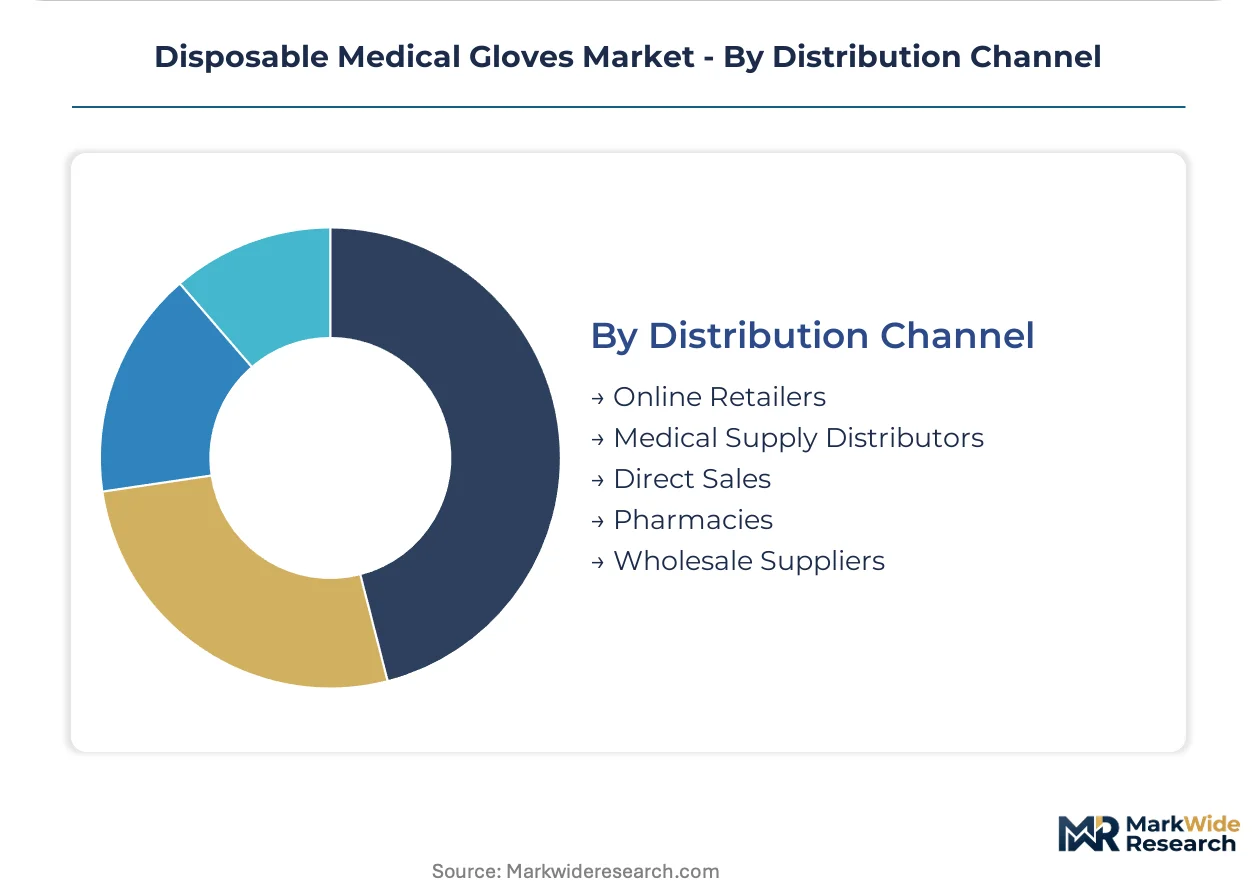
The distribution channel segment illustrates the various pathways through which disposable medical gloves reach end-users. These channels range from traditional bulk procurement to increasingly digitized retail options. Channel efficiency and reach are critical for market penetration.
- Medical Supply Distributors:These entities form the backbone of glove distribution, managing logistics and inventory for a vast network of healthcare providers. Major distributors in the United Kingdom and Canada serve as crucial intermediaries, consolidating orders from multiple manufacturers.
- Direct Sales:Large manufacturers often employ direct sales teams to engage directly with major hospital networks or government tenders. This channel allows for customized solutions and stronger relationship management with high-volume clients in markets like the United States.
- Online Retailers:Online platforms provide convenient access for smaller clinics and individual practitioners.
- Pharmacies:Pharmacies offer gloves for over-the-counter sales to consumers and small medical offices.
- Wholesale Suppliers:Wholesale suppliers provide bulk quantities to various resellers and larger institutions.
Medical Supply Distributors continue to manage the largest share of transactional volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for disposable medical gloves varies significantly by region; high-volume, cost-sensitive procurement dominates in some areas, while others prioritize specialized, high-performance products. Stringent regulatory frameworks in developed economies compel consistent product quality and compliance. Manufacturing concentration in Southeast Asia supplies global markets, creating complex trade flows.
United States
Diagnostic testing and surgical procedures drive substantial consumption of medical gloves across the United States. The US FDA's 510(k) premarket notification process ensures product safety and efficacy for market entry. Major hospital networks and group purchasing organizations in cities like Chicago and New York consolidate procurement, influencing market dynamics.
Germany
Hospitals and ambulatory surgical centers in Germany maintain high demand for certified disposable medical gloves. The EU's Medical Device Regulation (MDR) sets rigorous standards for product conformity and quality assurance. Manufacturing clusters in regions like Bavaria focus on specialized medical device components, complementing glove distribution.
Malaysia
Malaysia remains a dominant global manufacturing hub for disposable medical gloves, leveraging its access to raw materials and established production infrastructure. The country's Department of Standards Malaysia (DSM) oversees quality control and export certifications. Large-scale production facilities around Kuala Lumpur and Ipoh supply high-volume tenders worldwide.
Japan
Expanding diagnostic laboratory services and an aging population contribute to consistent demand for examination gloves in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical devices, emphasizing product quality and user safety. Major medical device distribution centers in Tokyo and Osaka ensure efficient market access.
Canada
Surgical applications and infection control protocols in Canadian healthcare facilities sustain robust demand for sterile and non-sterile gloves. Health Canada regulates medical devices, ensuring they meet safety and effectiveness requirements before market approval. Major medical supply distributors in Toronto and Montreal manage logistics for hospitals and clinics.
Disposable Medical Gloves Market Key Industry Players
Large-scale commodity producers and specialized solution providers split the disposable medical gloves market. The industry structure shows consolidation among top-tier manufacturers, particularly those with captive raw material supply. Key strategic archetypes include high-volume, low-cost manufacturers and niche players focusing on advanced materials or specialized applications. Capacity expansion and strategic partnerships remain dominant competitive moves across the sector.
At the scale-driven end, Top Glove Corporation Bhd and Hartalega Holdings Berhad represent the immense production capabilities concentrated in Southeast Asia, serving global high-volume tenders. Ansell Ltd, in contrast, occupies a position focused on specialized gloves for surgical and cleanroom environments, exemplifying a strategy of differentiation through product performance. These companies collectively anchor competitive dynamics, balancing commodity production with specialized offerings to address diverse market needs.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Ansell Ltd |
| Kossan Rubber Industries Bhd |
| Cardinal Health |
| Medline Industries |
| Semperit AG Holding |
| McKesson Corporation |
| Kimberly-Clark Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Southeast Asian manufacturing plants drives aggressive pricing strategies among producers. This utilization pressure influences supplier behavior and their ability to absorb raw material cost fluctuations.
Pricing Analysis
Long-term contract renewals drive lifetime value for disposable medical glove producers. The dominant pricing model is transactional, often structured through long-term offtake agreements for high-volume tenders. Price differentiation stems from quality grade, specifically Acceptable Quality Level (AQL) standards, and stringent certification levels like US FDA 510(k) clearance. Pricing pressure is generally downward due to intense competition among Southeast Asian manufacturers and raw material volatility, with group purchasing organizations exhibiting high price sensitivity for commodity examination gloves.
Supply Chain Analysis
Raw material price volatility for nitrile butadiene rubber (NBR) represents a significant structural risk for the disposable medical gloves market. Geographic supply concentration centers in Malaysia and Thailand, primary manufacturing hubs that draw from global sources for polymers like NBR and natural rubber latex. Logistical disruptions or geopolitical events in Southeast Asia can impact global supply continuity. Downstream distribution runs predominantly through medical supply distributors, managing inventory for healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable medical gloves market presents a service-attach opportunity, with quality assurance and compliance consulting expanding faster than basic product sales. This recurring revenue layer offers a distinct path for market participants.
For Market Incumbents: Harden supply chain resilience through backward integration into raw material production, particularly for nitrile butadiene rubber. Invest in factory automation to reduce labor dependency and improve production consistency against volatile input costs. Focus on maintaining stringent regulatory compliance, such as US FDA 510(k) and EU MDR, to differentiate from lower-grade competitors. This protects market share against emerging entrants and margin pressure.
For New Entrants and Emerging Players: Establish a beachhead in high-margin surgical or cleanroom glove niches, focusing on specialized materials or enhanced features like antimicrobial coatings. Target the growing demand for biodegradable polymers within EU healthcare systems as a distinct green procurement angle. Develop robust quality management systems from inception to meet stringent regulatory requirements. This strategy avoids direct competition with high-volume commodity producers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the disposable medical glove manufacturing segment, driven by automation investments. The long-term viability of this market remains strong, supported by persistent infection control mandates. Identify acquisition targets among mid-sized manufacturers possessing strong intellectual property in advanced nitrile formulations or efficient automation technologies. Increased venture capital funding into sustainable polymer development for medical applications signals market evolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Large manufacturers like Top Glove reinforce economies of scale for global tenders. |
| Advanced Nitrile Formulation Development | Manufacturers enhance product performance and reduce allergen risks for healthcare systems. |
| Automation of Production Lines | Producers in Malaysia reduce labor costs and improve consistency in high-volume output. |
| EU MDR Conformity Assessment | Companies ensure market access and demonstrate product safety within European healthcare. |
| Biodegradable Polymer Research | New players address emerging green procurement mandates in developed economies. |
Research Approach
Operator-level perspectives from hospital procurement managers, diagnostic lab directors, and medical device regulatory specialists anchored the qualitative base. Primary interviews provided crucial insights into market dynamics and regulatory compliance. Secondary validation involved reviewing US FDA 510(k) submissions, EU MDR guidance, and national trade statistics. This approach utilized bottom-up and top-down triangulation.
Scenario-bracketing across optimistic and conservative outlooks informed the market forecast over the projection horizon. The analytical framework modeled segmentation dimensions including material type, application, end-user, distribution channel, and geographic region. Compound Annual Growth Rates were derived from historical data analysis and projected trend extrapolation. Key inputs included raw material price forecasts and healthcare expenditure growth rates.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or trade policies would shift the market's trajectory. Forecasts reflect documented assumptions regarding raw material stability and regulatory enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Micro Vials Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Anti Venom Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Smear Mask Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Skin Tac Market
Medical Supplies
Disposable Sanitary Pad Market