
 Japan Hospital Supplies Market | 2026-2036
Japan Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Hospital Supplies Market Foresight
Aftermarket service revenue for diagnostic equipment is rewriting how suppliers capture lifetime value from hospital clients. GE Healthcare leverages its installed base of imaging systems to lock in multi-year maintenance contracts across Japan's prefectural hospitals. Becton Dickinson and Company anchors its position through deep integration with blood collection and specimen handling workflows in tertiary care centers.
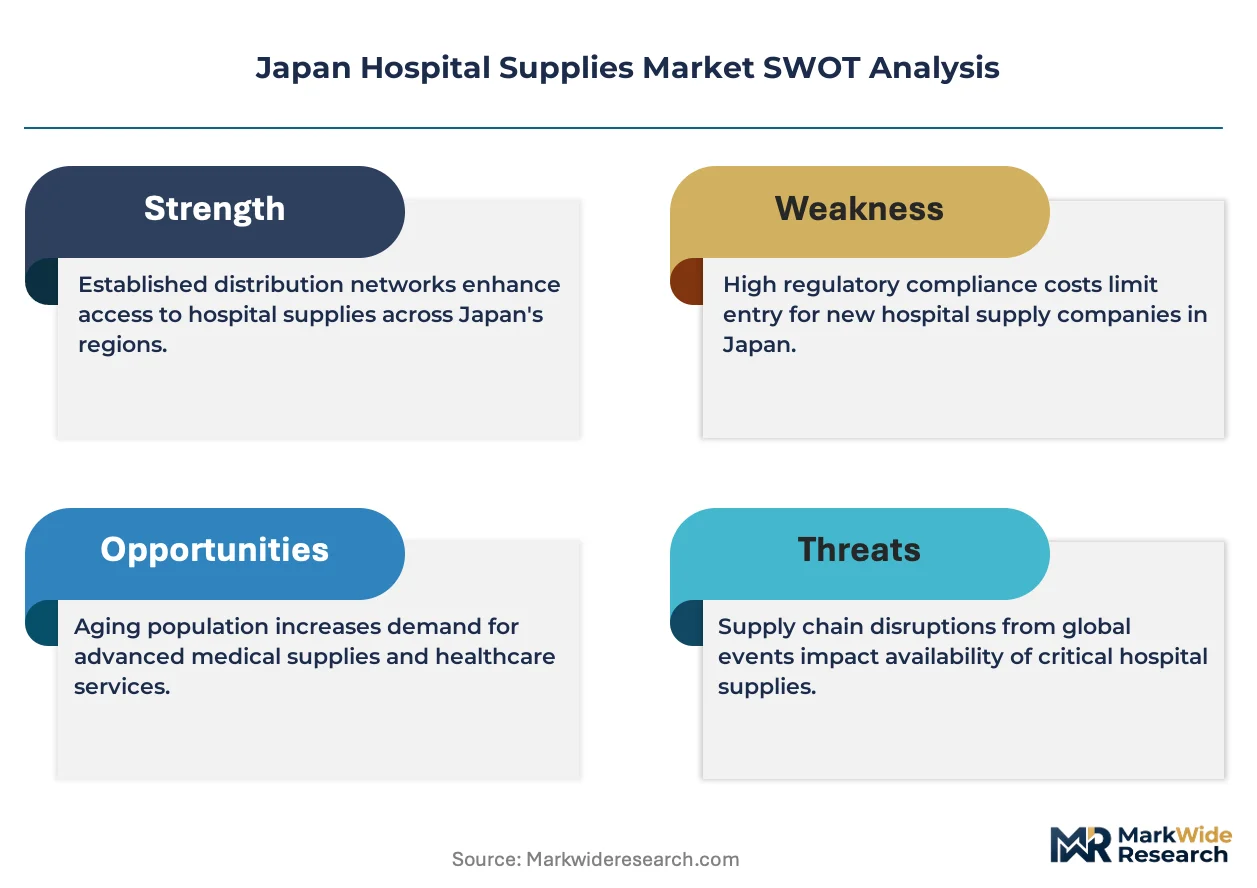
Japan hospital supplies encompass the full spectrum of materials, instruments, and apparatus used in inpatient diagnosis, intervention, and ongoing patient management, ranging from single-use syringes and catheters to electromechanical monitoring systems and advanced surgical platforms. These products must conform to Japan's stringent quality benchmarks, including JIS standards for metallic instruments and PMDA clearance pathways for Class III and IV devices. Consumables and infection control applications command the most predictable revenue streams due to their replenishment-driven purchase cycles, while diagnostic equipment generates concentrated margin pools through bundled service agreements. Surgical instruments occupy a mature but stable position where domestic manufacturers compete on precision craftsmanship against multinational scale.
PMDA's device review timelines and METI's industrial policy for critical medical goods jointly determine which product categories achieve rapid market access versus extended qualification periods. JIS standards for sterilization packaging and instrument traceability shape procurement specifications at the hospital level, effectively filtering non-compliant suppliers from vendor lists. Stakeholders must track how Japan's pharmaceutical and medical device agency recalibrates priority review designations for digital health-integrated supply categories.
Market Dynamics
Japan's hospital supplies sector is experiencing a fundamental recalibration as METI's domestic manufacturing resilience mandates redirect procurement toward local supply chains, compressing margins for importers while elevating domestic producers with JIS-certified production capabilities.
Growth Catalysts
- Acute Care Expansion:Japan's aging population intensifies demand for infection control consumables in public hospitals, creating predictable replenishment cycles for sterilization packaging and single-use instruments.
- PMDA Priority Review Pathways:Accelerated clearance designations for digital health-integrated supply categories reduce time-to-market for connected monitoring devices and smart surgical platforms.
- Kanto Region Hospital Density:Tokyo's concentrated network of tertiary care centers consumes disproportionate volumes of diagnostic equipment and precision surgical instruments, anchoring supplier revenue concentration.
Market Restraints
- PMDA Review Timelines:Extended qualification periods for Class III and IV devices create cash flow bottlenecks for foreign manufacturers without established Japanese regulatory affairs infrastructure.
- Domestic Supply Concentration:METI's industrial policy favors established domestic producers with existing JIS certification, raising barriers for new entrants lacking pre-qualified manufacturing partnerships.
- Stainless Steel Price Volatility:Surgical instrument margins compress when nickel and chromium input costs spike, disproportionately affecting mid-tier domestic manufacturers without long-term raw material hedging.
Strategic Opportunities
- Kansai Underpenetration:Osaka-Kobe hospital networks maintain lower supplier consolidation than Kanto, presenting white space for diagnostic equipment vendors with localized service capabilities.
- RFID-JIS Convergence:Integration of radio-frequency identification with instrument traceability standards enables real-time sterilization compliance monitoring in prefectural hospital networks.
- Prefectural Procurement Reform:Regional health authority purchasing consortiums are consolidating vendor lists, favoring suppliers offering bundled consumables-instruments-service packages.
Industry Challenges
- PMDA QMS Inspector Shortage:Limited regulatory audit capacity extends factory certification timelines for foreign manufacturers seeking Japanese market entry.
- Legacy HIS Integration:Hospital information system fragmentation across Japan's prefectural networks complicates deployment of connected supply chain management platforms.
- Specialized Biomedical Technician Scarcity:Diagnostic equipment maintenance contracts face renewal pressure where trained service personnel concentrate in metropolitan hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Hospital Supplies Market |
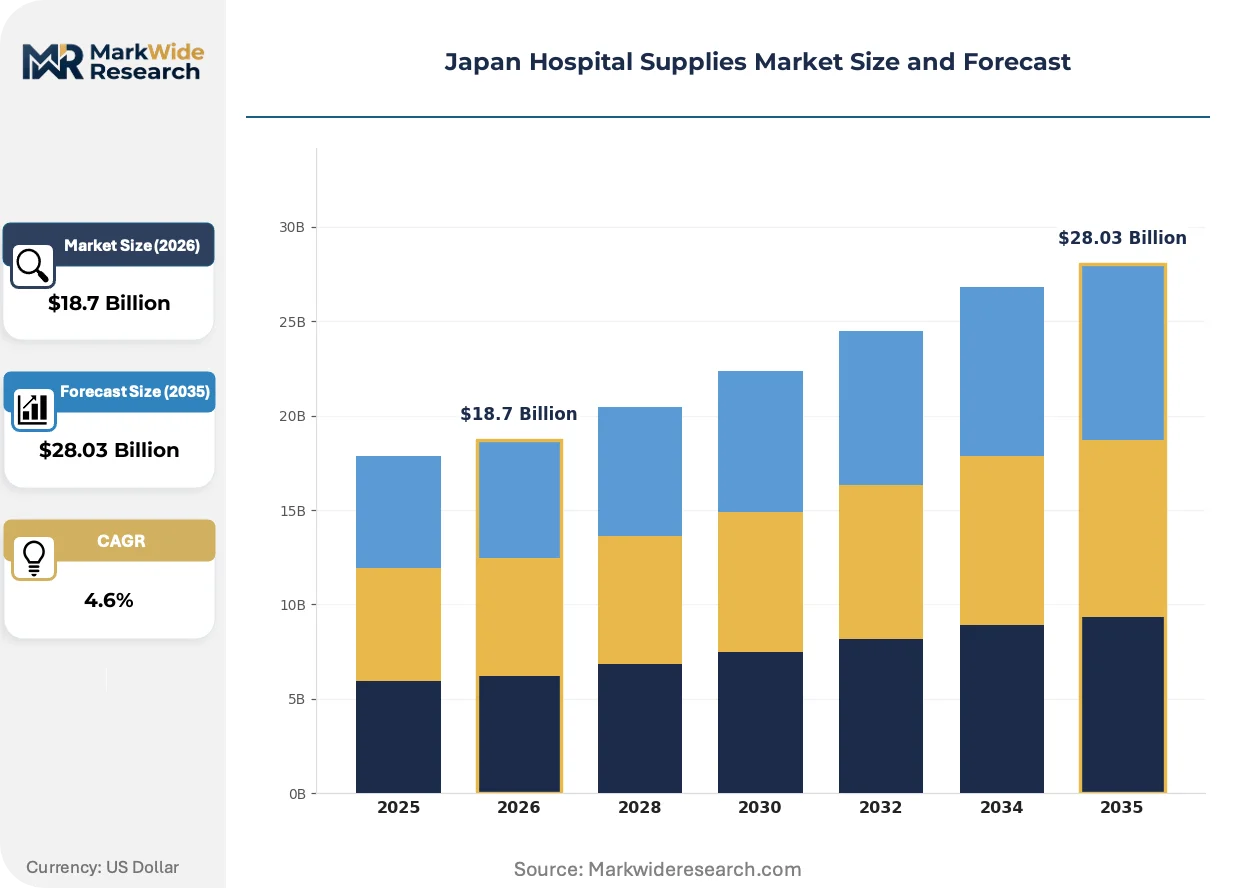
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Surgical Instruments, Diagnostic Equipment, Medical Devices Application: Patient Care, Surgery, Diagnostics, Infection Control End User: Public Hospitals, Private Clinics, Research Institutes, Home Care Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesalers |
| Companies Covered | 3M, Medtronic, Cardinal Health, Boston Scientific Corporation, B. Braun SE, Baxter International, Becton Dickinson and Company, GE Healthcare, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Hospital Supplies Market Shifts & Advancements
Digital integration and service model reinvention are compressing traditional hardware-centric revenue streams while elevating data-enabled supply chain relationships as the primary competitive battleground.
Single-use surgical instruments with embedded RFID traceability chips are rendering obsolete manual sterilization logbooks and batch-record documentation in Japan's tertiary care centers. Prefectural hospitals in Kanto and Kansai regions are adopting these instruments at accelerating pace to satisfy JIS instrument tracking mandates. The technology is rendering obsolete legacy stainless steel reusable instrument sets that require costly reprocessing infrastructure and carry infection liability exposure.
METI's 2024 medical device manufacturing resilience framework imposes domestic content thresholds on critical supply categories including syringes, catheters, and infusion sets. The policy redirects procurement patterns toward local producers with certified cleanroom manufacturing capabilities. Foreign suppliers are responding by establishing Japanese manufacturing joint ventures or acquiring domestic contract manufacturers to maintain hospital vendor list eligibility.
Prefectural hospital consortiums are consolidating purchasing decisions through regional supply cooperatives, displacing individual hospital procurement autonomy. These cooperatives negotiate multi-year framework agreements with preferred vendors for consumables and diagnostic equipment maintenance. The consolidation is most visible in Chubu and Tohoku regions where rural hospital networks pool volumes to extract pricing concessions from multinational suppliers.
Japan Hospital Supplies Market Segmentation
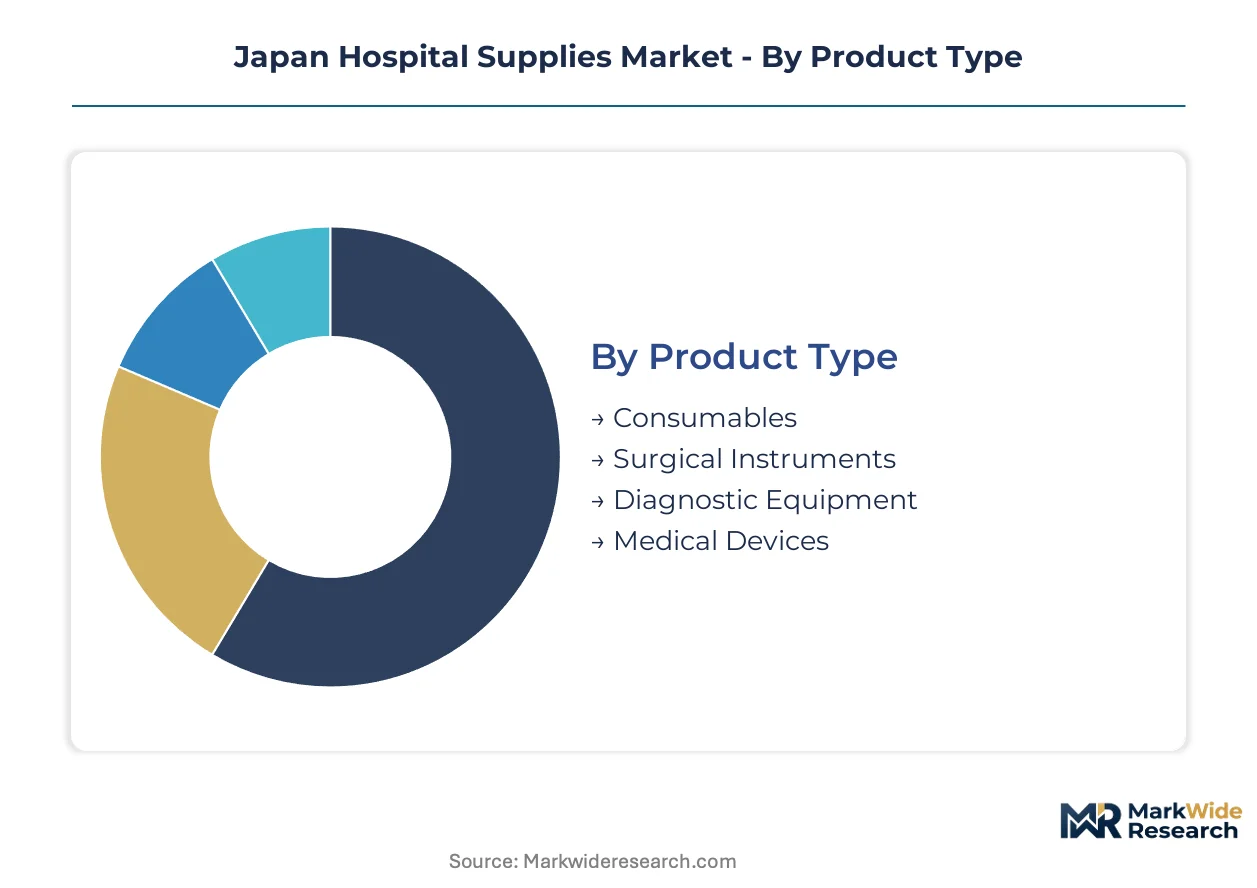
Hospital supplies in Japan fragment across four critical dimensions that determine regulatory pathways, margin structures, and competitive positioning. Each segmentation axis reveals distinct procurement behaviors shaped by METI's domestic manufacturing mandates and PMDA clearance requirements.
Product Type:
Cost tier differentiation separates high-velocity consumables from capital-intensive diagnostic platforms with divergent margin profiles.
- Consumables:Single-use syringes, catheters, and infusion sets manufactured under JIS sterilization standards. Public hospitals in Kanto consume disproportionate volumes as acute bed capacity expands for aging patient populations.
- Surgical Instruments:Electromechanical platforms and precision stainless steel instruments requiring PMDA Class III clearance. Tertiary care centers in Tokyo anchor demand for advanced laparoscopic and robotic-assisted systems.
- Diagnostic Equipment:Imaging modalities and laboratory analyzers generating recurring service revenue through multi-year maintenance contracts.
- Medical Devices:Monitoring systems and therapeutic apparatus integrated with hospital information systems for real-time patient data capture.
Consumables hold installed capacity. Diagnostic equipment is rotating up the share rankings.
Application:
Clinical workflow integration determines product specification intensity and replacement frequency across Japan's hospital networks.
- Patient Care:Beds, monitoring systems, and mobility aids supporting extended inpatient stays. Prefectural hospitals in Chubu prioritize durable equipment with 10-year depreciation cycles.
- Surgery:Operating theater consumables and precision instruments governed by JIS traceability mandates. RFID-embedded single-use instruments are displacing reusable stainless steel sets in Kanto tertiary centers.
- Diagnostics:Laboratory reagents, imaging contrast media, and specimen handling consumables with predictable replenishment rhythms.
- Infection Control:Sterilization packaging, antimicrobial coatings, and barrier protection materials. METI's resilience framework prioritizes domestic sourcing for this category.
Surgery commands premium pricing. Infection control is climbing the fastest.
End User:
Procurement autonomy varies sharply across institutional types, from centralized prefectural purchasing to fragmented clinic networks.
- Public Hospitals:Government-funded institutions bound by METI domestic content thresholds and regional supply cooperative frameworks. Kanto's dense hospital network concentrates volume for negotiated pricing leverage.
- Private Clinics:Independent physician practices with flexible vendor selection but limited capital budgets for diagnostic equipment.
- Research Institutes:Academic medical centers piloting digital health-integrated supply categories eligible for PMDA priority review.
- Home Care:Post-acute and long-term care settings driving demand for portable monitoring and infusion devices outside traditional hospital infrastructure.
Public hospitals hold installed capacity. Home care is rotating up the share rankings.
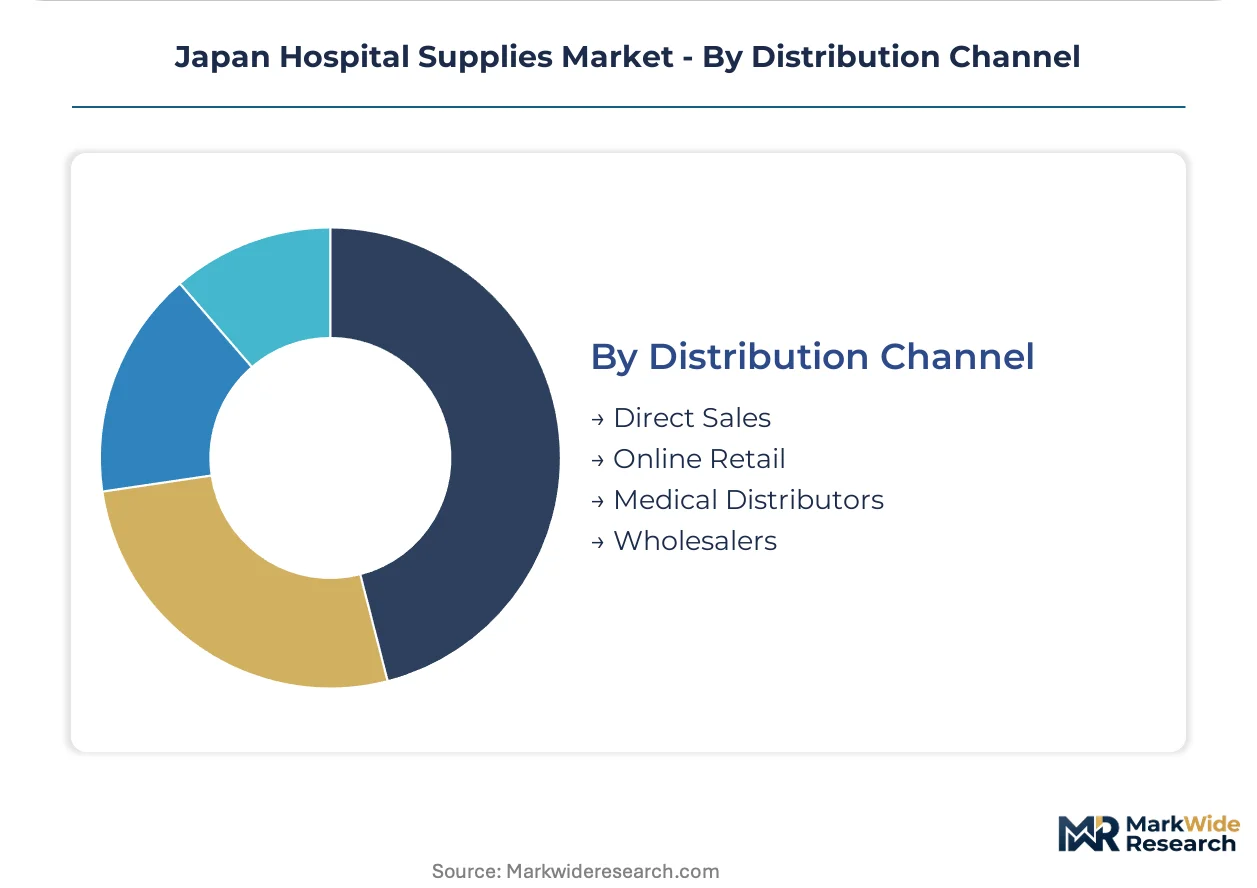
Distribution Channel:
Channel configuration directly shapes supplier margin capture and customer relationship depth in Japan's fragmented logistics landscape.
- Direct Sales:Manufacturer-led account management for diagnostic equipment with bundled service agreements. GE Healthcare and Siemens Healthineers deploy dedicated Tokyo-based teams for prefectural hospital networks.
- Online Retail:E-procurement platforms gaining traction for standardized consumables among private clinics seeking price transparency.
- Medical Distributors:Specialized intermediaries with JIS-certified warehousing and cold chain capabilities for temperature-sensitive supplies.
- Wholesalers:Volume aggregators serving rural hospital networks in Tohoku and Hokkaido where direct manufacturer presence remains thin.
Medical distributors hold installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital supply consumption patterns diverge sharply across Japan's prefectural networks, with metropolitan tertiary centers prioritizing diagnostic equipment service contracts while rural prefectures concentrate procurement through regional cooperatives for standardized consumables.
Kanto/Tokyo
Tokyo's dense hospital network consumes disproportionate volumes of surgical instruments and diagnostic equipment, with prefectural hospitals locking in multi-year maintenance agreements with imaging system vendors. METI's domestic manufacturing resilience mandates redirect procurement toward JIS-certified local producers for infection control consumables. The metropolitan cluster anchors supplier revenue concentration through bundled consumables-instruments-service packages.
Kansai/Osaka
Osaka-Kobe hospital networks maintain lower supplier consolidation than Kanto, presenting expansion opportunities for diagnostic equipment vendors with localized service capabilities. PMDA priority review pathways accelerate clearance for digital health-integrated supply categories piloted at academic medical centers. The region's manufacturing heritage supports domestic surgical instrument producers competing on precision craftsmanship.
Chubu/Nagoya
Prefectural hospital consortiums in Chubu consolidate purchasing decisions through regional supply cooperatives, displacing individual hospital procurement autonomy. Rural hospital networks pool volumes to extract pricing concessions from multinational suppliers for sterilization packaging and single-use instruments. The region's automotive manufacturing base supplies precision engineering talent to medical device component fabricators.
Tohoku
Rural hospital networks in Tohoku rely on volume aggregators and wholesalers where direct manufacturer presence remains thin, creating distribution inefficiencies for temperature-sensitive supplies. METI's industrial policy for critical medical goods prioritizes domestic sourcing for syringes and infusion sets in disaster-preparedness stockpiles. Sendai anchors regional logistics for JIS-certified warehousing and cold chain capabilities.
Kyushu
Fukuoka's expanding medical hub drives demand for patient care equipment supporting extended inpatient stays as regional bed capacity expands for aging populations. Prefectural procurement reform consolidates vendor lists, favoring suppliers offering comprehensive consumables-instruments-service packages. The island's distance from Tokyo-based distributors elevates the importance of regional medical distributors with certified cleanroom capabilities.
Japan Hospital Supplies Market Competitive Landscape
Capability concentration sits with domestic JIS-certified precision manufacturers; scale advantage sits with multinational conglomerates with established regulatory affairs infrastructure in Tokyo. The vendor base stratifies across three tiers: integrated conglomerates bundling diagnostic equipment with service contracts, mid-cap specialists in surgical instrument craftsmanship, and regional distributors with certified warehousing networks. Two competitive moves dominate: foreign suppliers establishing Japanese manufacturing joint ventures to satisfy METI domestic content thresholds, and prefectural procurement cooperatives consolidating vendor lists to extract multi-year framework pricing concessions.
Among the integrated conglomerates represented in this market, 3M and Medtronic exemplify archetypes with established regulatory pathways and service infrastructure. Becton Dickinson and Company occupies a position anchoring blood collection and specimen handling workflows in tertiary care centers. GE Healthcare sits within the diagnostic equipment tier, leveraging installed base scale to capture aftermarket service revenue through multi-year maintenance contracts across prefectural hospital networks.
| Leading Market Players |
|---|
| 3M |
| Medtronic |
| Cardinal Health |
| Boston Scientific Corporation |
| B. Braun SE |
| Baxter International |
| Becton Dickinson and Company |
| GE Healthcare |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
PMDA regulatory chokepoints for Class III and IV device clearance determine both tiered contract pricing spreads and supply chain configuration across Japan's hospital supply base. METI's domestic content mandates compress margins for importers lacking JIS-certified manufacturing partnerships while elevating local producers with pre-qualified regulatory infrastructure.
Pricing Analysis
Long-term framework agreements dominate procurement for consumables and diagnostic equipment maintenance across prefectural hospital networks. Pricing stratifies across premium JIS-certified domestic tiers, standard multinational import tiers, and economy generic tiers based on certification grade and volume scale. Cost compression in mid-tier surgical instruments is intensifying because nickel and chromium price volatility erodes margins for manufacturers without raw material hedging. Private clinics exhibit highest price sensitivity for capital equipment, while tertiary care centers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Tariff exposure between China and Japan dominates supply chain risk planning for stainless steel instrument components and electronic diagnostic subassemblies. Manufacturing concentration rests on Japan for precision surgical instruments, China for commodity consumables and raw materials, and Germany for advanced imaging modalities. Nickel and chromium feedstock dependencies, alongside specialized polymer resins for sterilization packaging, create input cost volatility. Single-source vulnerability persists for PMDA-audited cleanroom manufacturing capacity. Distribution runs through JIS-certified medical distributors with cold chain capabilities serving prefectural hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's hospital supplies market demands substitution defense as RFID-embedded single-use instruments displace reusable stainless steel sets and digital health-integrated platforms rewrite service revenue models.
For Market Incumbents: Entrench installed base relationships through multi-year diagnostic equipment service contracts that lock in prefectural hospital networks before renewal cycles. Deepen backward integration into JIS-certified cleanroom manufacturing to satisfy METI domestic content thresholds and exclude import-dependent competitors from vendor lists. For New Entrants and Emerging Players: Establish a beachhead in Kansai's underpenetrated Osaka-Kobe hospital networks where supplier consolidation lags Kanto and localized service capabilities command premium positioning. Target prefectural procurement cooperatives in Chubu and Tohoku with bundled consumables-instruments-service packages that match consolidated purchasing authority structures. For Investors and Strategic Acquirers: Domestic JIS-certified precision manufacturers with established PMDA regulatory affairs infrastructure represent the highest-conviction acquisition archetype for long-term viability across the next decade. Watch for inflection signals in PMDA priority review pathway designations for digital health-integrated supply categories that accelerate time-to-market for connected platforms.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Investment | PMDA factory audits and JIS sterilization standards compliance unlock prefectural hospital vendor list eligibility. |
| Domestic Manufacturing Joint Venture | METI resilience mandates redirect procurement toward local producers with certified cleanroom capabilities. |
| RFID Traceability Integration | Embedded chip instruments satisfy JIS instrument tracking mandates and displace legacy reusable sets. |
| Regional Service Hub Establishment | Localized maintenance capabilities capture diagnostic equipment contracts in Kansai and Chubu networks. |
| Prefectural Cooperative Contracting | Multi-year framework agreements with regional supply consortiums displace fragmented hospital-level procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and PMDA regulatory consultants; and secondary validation against hospital procurement databases, METI industrial policy filings, PMDA device approval records, and JIS standards documentation. Bottom-up demand modeling across prefectural hospital networks triangulated with top-down market sizing from trade flow data.
Forecast inputs considered product type segmentation across consumables, surgical instruments, diagnostic equipment, and medical devices; application segmentation spanning patient care, surgery, diagnostics, and infection control; and end-user segmentation across public hospitals, private clinics, research institutes, and home care settings. CAGRs were derived from volume trajectory modeling incorporating acute care bed expansion, aging population demographics, and METI domestic manufacturing policy implementation timelines.
Stress conditions across PMDA review timeline extensions, nickel and chromium price volatility bands, and prefectural procurement consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway efficiency and domestic manufacturing capacity scaling. Macroeconomic deviation, PMDA organizational capacity constraints, or accelerated digital health integration adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Blood Bags Market
Medical Supplies
Nursing Breast Pads Market