
 Crutch Pads Market | 2026-2036
Crutch Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Crutch Pads Market Intelligence
The margin differential between standalone aftermarket sales and pads bundled with original equipment is narrowing, shifting profit pools towards value-added accessories. Drive Medical leverages its extensive distribution network in the mobility aids sector. Medline Industries, Inc. specializes in supplying medical facilities, including hospitals and rehabilitation centers. Invacare Corporation competes through its focus on home and long-term care product lines, reaching a different customer base.
Crutch pads are accessory components designed to cushion the underarm and handgrip areas of crutches, mitigating pressure and friction for the user. These products are often manufactured from high-density foam, silicone, or gel through processes like injection molding to ensure durability and user comfort. While foam-based pads constitute the largest material segment by volume, ergonomic and contoured designs represent the fastest-growing category due to their enhanced comfort. Rehabilitation centers and orthopedic clinics remain critical end-user channels, prioritizing patient comfort and recovery outcomes.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and adherence to the European Union's Medical Device Regulation (MDR) are essential for market access. These frameworks mandate specific material safety, biocompatibility testing, and accurate labeling for products classified as Class I medical devices, influencing material sourcing. Consequently, vendor selection will increasingly hinge on the ability to navigate complex compliance demands while innovating in material science for improved patient outcomes.
Market Dynamics
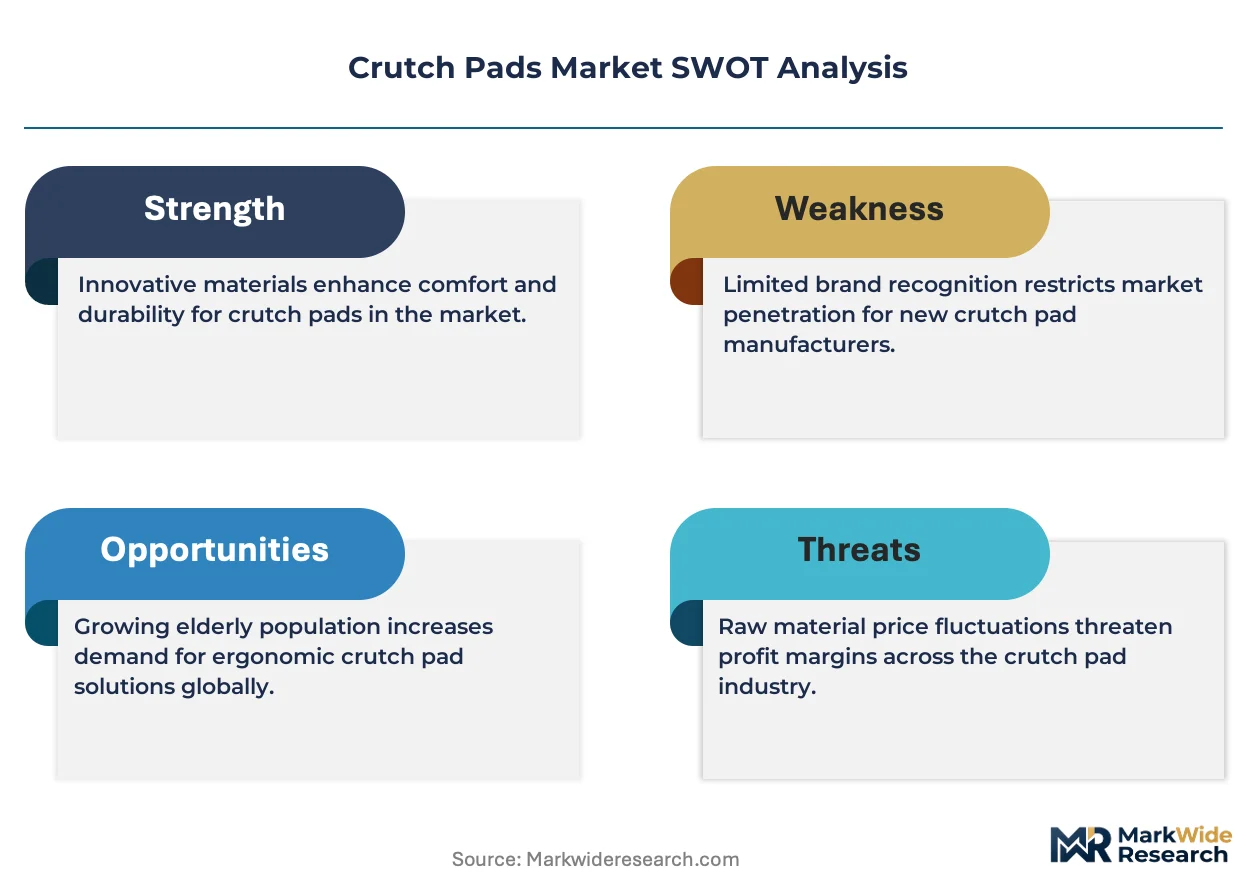
The central tension shaping the crutch pads market is the divergence between the institutional demand for low-cost, basic products and the patient-driven need for ergonomic, high-performance materials that improve comfort and clinical outcomes during rehabilitation.
Growth Catalysts
- Demographic Shifts:Aging populations in developed nations, particularly in countries like Germany and Japan, are expanding the core user base for mobility aids, directly stimulating demand for comfort-enhancing accessories like crutch pads.
- Post-Surgical Recovery:A rising volume of orthopedic surgeries, especially knee and hip replacements, creates consistent, short-term demand from patients in rehabilitation centers who require crutches and prioritize products that mitigate discomfort.
- Regulatory Up-Classification:Stricter frameworks like the EU's Medical Device Regulation (MDR) push manufacturers towards higher-grade, biocompatible materials, creating a catalyst for premium product segments with documented safety and performance characteristics.
Market Restraints
- Institutional Price Sensitivity:Large-scale purchasers such as hospitals and public health systems often prioritize cost containment, limiting their procurement to basic foam pads and slowing the adoption of higher-priced ergonomic or gel-based alternatives.
- Threat of Non-Compliant Imports:The proliferation of low-cost, uncertified crutch pads on global e-commerce platforms creates significant price pressure and erodes market share for manufacturers who invest in regulatory compliance and quality materials.
- Input Material Volatility:Fluctuations in the price of petrochemical-derived inputs for high-density foam and specialized silicone can compress manufacturer margins, particularly for those competing in the commoditized segment of the market.
Strategic Opportunities
- Emerging Market Penetration:Expanding healthcare infrastructure and rising disposable incomes in Latin American and Southeast Asian countries present untapped markets for crutch pads as access to orthopedic care improves.
- Product Line Extension:Manufacturers can leverage expertise in ergonomic design and material science to develop cushioning accessories for adjacent mobility aid categories, such as walkers, rollators, and knee scooters.
- Direct-to-Consumer Channels:Developing D2C e-commerce platforms allows brands to bypass traditional medical supply distributors, build a direct relationship with the end-user, and capture higher profit margins on value-added products.
Industry Challenges
- Complex Compliance Pathways:Navigating the documentation and testing requirements for medical device classification, such as for the FDA in the United States or CE marking under MDR in Europe, presents a significant time and cost barrier.
- Supply Chain Quality Assurance:Ensuring consistent quality and material traceability from a global network of raw material suppliers is a persistent operational challenge, especially with increasing regulatory scrutiny on biocompatibility and safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crutch Pads Market |
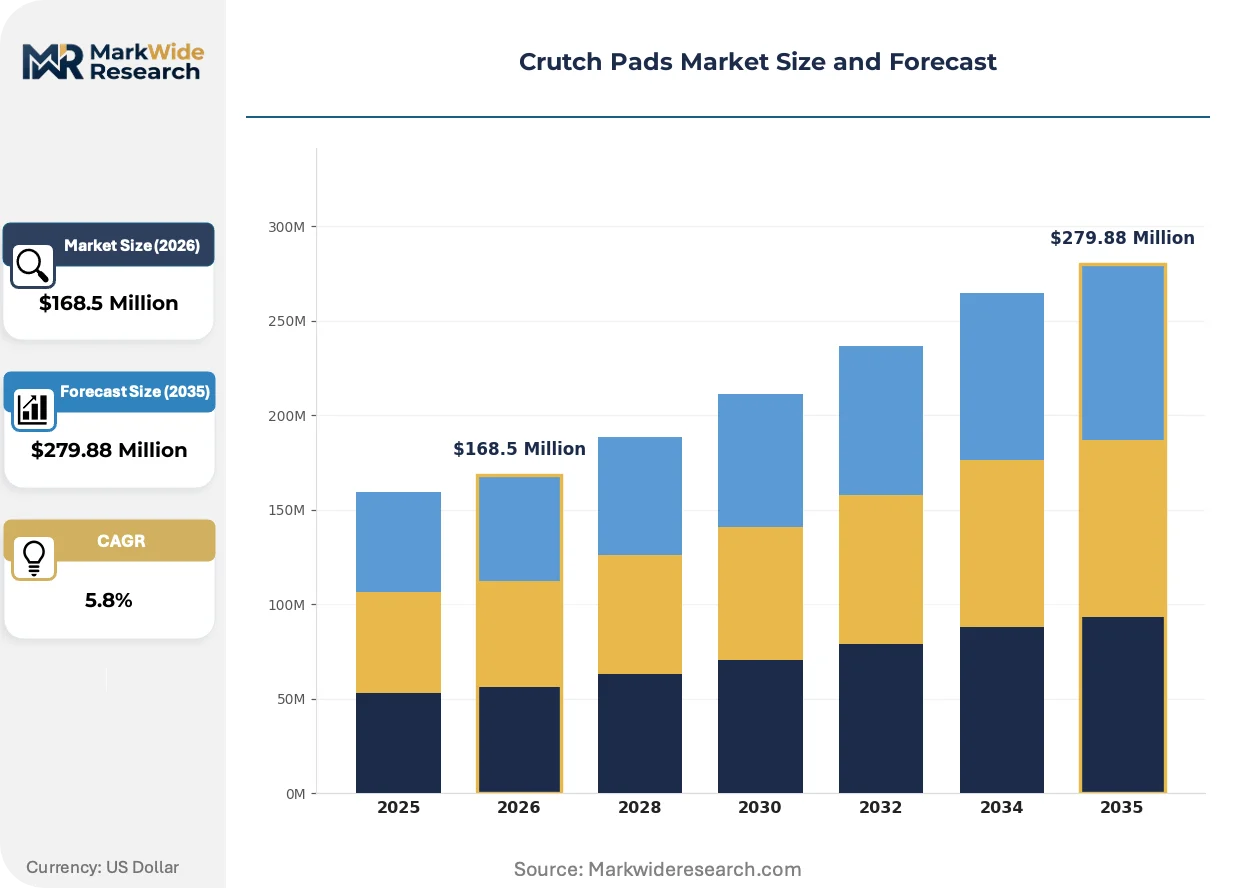
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $279.88 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Foam, Silicone, Rubber, Gel, Cork Design: Ergonomic, Contoured, Flat, Textured, Cushioned Application: Post-Surgery Recovery, Mobility Assistance, Injury Rehabilitation, Arthritis Relief, Pediatric Support End User: Orthopedic Clinics, Rehabilitation Centers, Elderly Care Facilities, Pediatric Care Centers |
| Companies Covered | Drive Medical, North Coast Medical Inc., Medline Industries, Inc., Apothecary Products, LLC., Patterson Medical, Alex Orthopaedics Inc., Invacare Corporation, Briggs Healthcare, Vive Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crutch Pads Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of material science innovation and a user-centric design philosophy. This shift prioritizes demonstrable patient benefits, moving crutch pads from a simple accessory to an integral component of the recovery experience, influenced by both clinical and consumer expectations.
Gel-infused and memory foam composites, often produced through injection molding, provide superior pressure distribution compared to traditional closed-cell foam. Rehabilitation clinics and long-term care facilities are adopting these advanced materials to enhance patient comfort and reduce the risk of friction-related skin irritation. This focus on clinical outcomes is collapsing the distinction between basic functional accessories and therapeutic medical components.
The European Union's Medical Device Regulation (MDR) imposes stringent requirements for biocompatibility, risk management, and material safety on products like crutch pads. This framework elevates these accessories to a formal medical device classification, mandating comprehensive technical documentation and post-market surveillance. Consequently, manufacturers targeting the EU must invest significantly in compliance, influencing material sourcing and favoring suppliers with robust quality management systems.
A pronounced shift towards patient-driven customization is evident, with users seeking products that meet specific anatomical and lifestyle needs. This trend moves some purchasing decisions away from institutional procurement by hospitals and towards direct-to-consumer channels where greater choice is available. This consumerization of medical accessories is most visible in North America, where patients increasingly research and buy their own equipment to improve comfort during recovery.
Crutch Pads Market Segmentation
Understanding the segmentation of the crutch pads market reveals the diverse needs across patient demographics and healthcare settings. This analysis distinguishes between material innovations, design preferences, specific applications, and various end-user channels. Each segment reflects unique demand drivers and procurement priorities within the mobility aids sector.
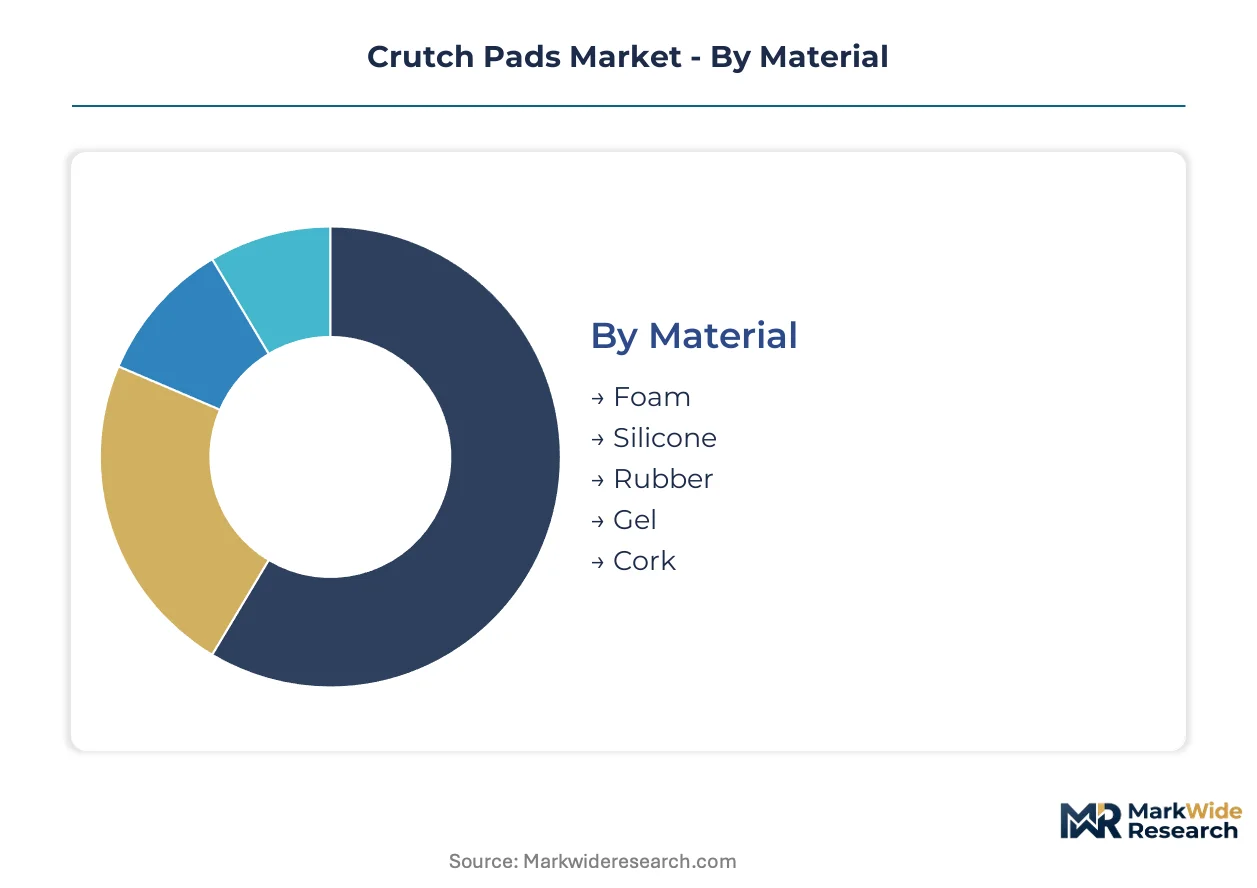
Material:
The material segment presents a spectrum from established, cost-effective options to advanced, performance-driven solutions.
- Foam:High-density foam pads, often manufactured from petrochemical-derived inputs, form the largest material segment by volume due to their low cost and adequate cushioning for basic use. Institutional purchasers in countries like Germany frequently procure foam pads for broad patient populations.
- Gel:Gel-infused composites offer superior pressure distribution and impact absorption, mitigating friction and enhancing user comfort during extended crutch use. Demand for gel pads is expanding rapidly, particularly among patients in North America seeking improved clinical outcomes.
- Silicone:Silicone materials provide excellent durability and biocompatibility, making them a preferred choice for reusable and hypoallergenic crutch pads.
- Rubber:Rubber pads offer robust grip and wear resistance, primarily used for handgrips where secure handling is critical.
- Cork:Cork provides a natural, lightweight, and breathable alternative, appealing to eco-conscious consumers and those with specific material sensitivities.
Foam retains volume leadership; Gel holds the steepest expansion curve.
Design:
Crutch pad designs are largely influenced by a trade-off between manufacturing complexity, cost, and patient comfort requirements.
- Ergonomic:Ergonomic designs are contoured to the natural shape of the human anatomy, providing optimal pressure relief and reducing nerve compression. This design is gaining traction in rehabilitation centers focused on long-term patient comfort.
- Contoured:Contoured pads feature specific shaping to better distribute weight and minimize friction, often incorporating specific curves for underarm or handgrip areas. Hospitals in countries with advanced healthcare infrastructure, such as Japan, increasingly adopt contoured designs.
- Flat:Flat pads represent the most basic design, offering simple cushioning without specialized anatomical shaping.
- Textured:Textured designs incorporate surface patterns to improve grip and airflow, particularly beneficial for handgrip pads.
- Cushioned:Cushioned designs prioritize general softness and padding, often using thicker layers of material for immediate comfort.
Ergonomic designs are driven by patient-centric outcomes, while flat designs maintain a strong position in basic institutional procurement.
Application:
The application segment reflects the various medical and daily living scenarios where crutch pads provide essential support and comfort.
- Post-Surgery Recovery:This segment includes patients recovering from orthopedic procedures like knee and hip replacements, who require crutches for a defined short-term period. Demand is consistent from rehabilitation centers focused on rapid patient mobilization.
- Injury Rehabilitation:Patients recovering from fractures, sprains, or other musculoskeletal injuries utilize crutch pads to alleviate discomfort during their healing process. Orthopedic clinics prioritize products that support effective recovery protocols.
- Mobility Assistance:Crutch pads assist individuals with chronic conditions or permanent mobility impairments, providing ongoing comfort for daily activities.
- Arthritis Relief:Patients with arthritis benefit from cushioned pads that reduce joint pressure and pain during ambulation.
- Pediatric Support:Specialized crutch pads for children address their unique anatomical needs and lighter body weights, ensuring proper fit and comfort.
Post-Surgery Recovery applications generate substantial short-term demand, with Mobility Assistance representing a consistent, long-term user base.
End User:
The end-user segment highlights the primary channels through which crutch pads are procured and distributed to patients.
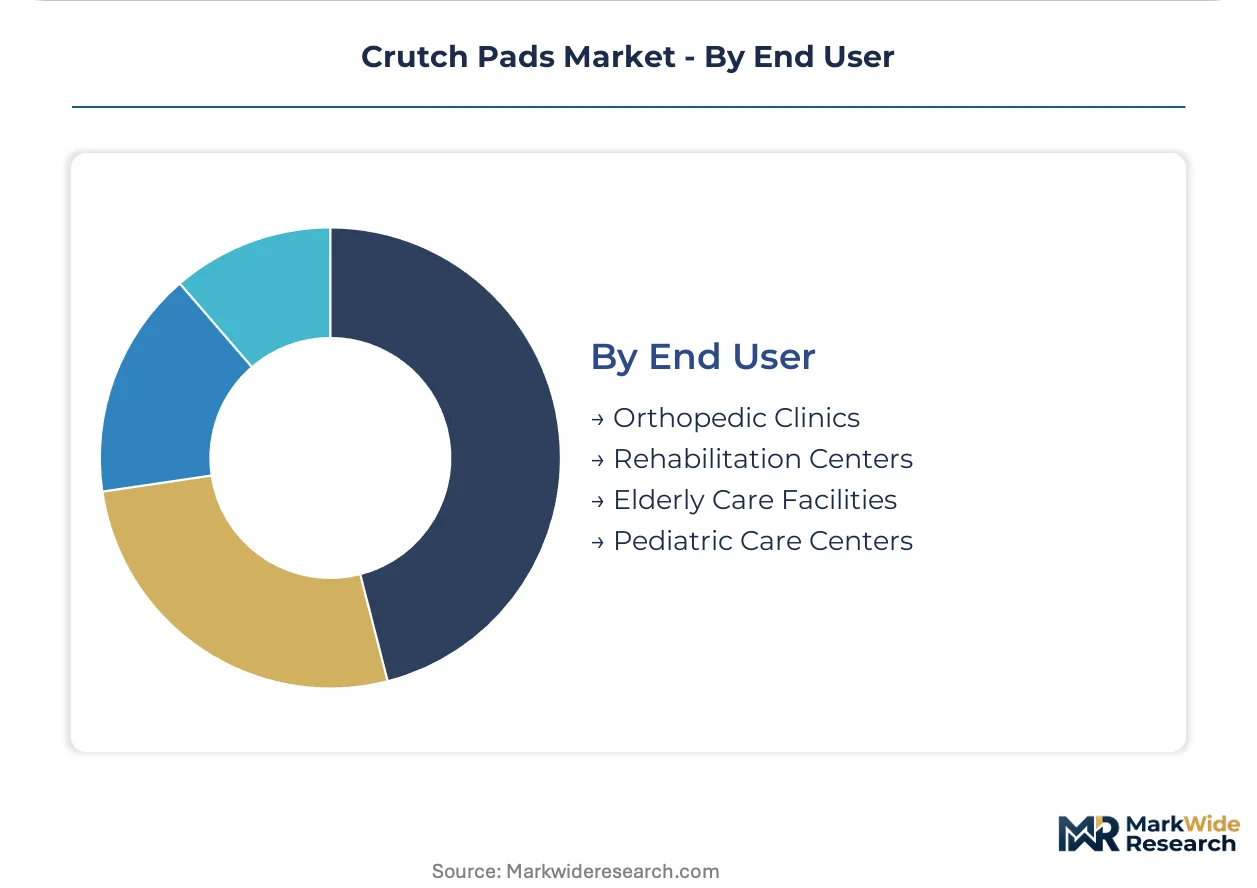
- Rehabilitation Centers:These facilities are critical purchasers, integrating crutch pads into comprehensive patient recovery programs to enhance comfort and improve clinical outcomes. They often seek advanced, ergonomic solutions for their patients.
- Orthopedic Clinics:Orthopedic clinics serve as direct points of contact for patients with musculoskeletal injuries, recommending and often supplying crutch pads as part of treatment plans. These clinics value both quality and regulatory compliance.
- Elderly Care Facilities:These facilities provide long-term care for aging populations who frequently require mobility aids, including crutches, for daily support.
- Pediatric Care Centers:Hospitals and clinics specializing in pediatric care procure crutch pads designed for younger patients, focusing on safety and appropriate sizing.
Rehabilitation Centers consistently drive demand for high-performance pads, while Orthopedic Clinics serve as a direct channel for patient-specific solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The crutch pads market exhibits a concentrated supply side, with established manufacturers often leveraging advanced production capabilities to serve diverse global demand. Demand patterns vary significantly by region, influenced by healthcare infrastructure, demographic shifts, and specific regulatory environments. Countries with aging populations and well-developed medical systems consistently drive demand for high-quality crutch pads.
Germany
Germany's aging population and robust healthcare system generate consistent demand for mobility aids, including crutch pads, particularly for post-surgical recovery. The European Union's Medical Device Regulation (MDR) mandates stringent material and safety standards, influencing procurement decisions towards compliant products. Major medical device clusters in regions like Bavaria and North Rhine-Westphalia focus on integrating advanced materials into patient care solutions.
Japan
Japan's rapidly aging demographic profile creates a substantial and sustained user base for crutch pads, with a strong emphasis on ergonomic and comfortable designs. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product safety and efficacy, ensuring high standards for medical accessories. Rehabilitation centers in urban centers like Tokyo and Osaka prioritize advanced cushioning technologies to support long-term patient comfort.
United States
The United States market is characterized by a high volume of orthopedic surgeries and a patient-driven demand for comfort-enhancing accessories. Regulatory oversight by the U.S. Food and Drug Administration (FDA) requires biocompatibility testing and accurate labeling for crutch pads. Direct-to-consumer channels, particularly in major metropolitan areas, allow patients to access a wider range of specialized and customizable products.
India
India presents an expanding market for crutch pads, driven by improving healthcare access and a growing middle class capable of affording better medical devices. The Central Drugs Standard Control Organization (CDSCO) is developing frameworks for medical device regulation, gradually formalizing market entry requirements. Major medical device manufacturing hubs in states like Gujarat and Karnataka are beginning to focus on domestic production of essential mobility aids.
Crutch Pads Market Key Industry Players
Specialized medical device manufacturers and broader mobility aid suppliers split the crutch pads market, each serving distinct procurement channels. Tiered pricing structures differentiate products based on material science and ergonomic design, catering to both institutional cost-containment and patient-driven premium demand. Strategic partnerships with rehabilitation centers and direct-to-consumer platform expansion represent dominant competitive moves.
Among the established players, Medline Industries, Inc. exemplifies a supplier focused on medical facilities, including hospitals and rehabilitation centers, leveraging its extensive catalog. Drive Medical, a U.S. company, represents a mobility aids specialist that utilizes broad distribution networks to reach a wide consumer base. Invacare Corporation, also based in the United States, anchors the home and long-term care segments, emphasizing product lines tailored for extended use.
| Leading Market Players |
|---|
| Drive Medical |
| North Coast Medical Inc. |
| Medline Industries, Inc. |
| Apothecary Products, LLC. |
| Patterson Medical |
| Alex Orthopaedics Inc. |
| Invacare Corporation |
| Briggs Healthcare |
| Vive Health |
| Others |
Cost & Logistics Intelligence
Petrochemical-derived inputs for high-density foam significantly influence manufacturer margins, particularly in the commoditized segment. This upstream concentration dictates where profit pools sit downstream, favoring value-added accessories.
Pricing Analysis
The European Union's Medical Device Regulation (MDR) dictates the pricing tier structure for compliant crutch pads. Pricing stratifies across premium, standard, and economy tiers, driven by material science advancements like gel and silicone, alongside ergonomic design features. Pricing pressure stems from institutional cost containment, particularly for basic foam pads. Individual patients, however, exhibit lower price sensitivity for comfort-enhancing, high-performance materials.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices for manufacturers sourcing raw materials. The crutch pads supply chain draws from petrochemical production in Asia for foam and specialized silicone. Input material volatility, particularly for petrochemical-derived components, represents a structural supply chain risk. Distribution runs through established medical supply distributors, increasingly supplemented by direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crutch pads market is in an early-cycle expansion, driven by the increasing penetration of advanced materials in rehabilitation settings. Patient-driven demand for enhanced comfort during recovery provides a strong tailwind.
For Market Incumbents:Entrench existing market share by investing heavily in regulatory compliance and quality management systems. Innovate continuously in material science, focusing on ergonomic designs and advanced composites to differentiate from low-cost, non-compliant imports. Control distribution channels, especially in institutional procurement, to maintain market presence. Leverage existing extensive distribution networks in mobility aids.
For New Entrants and Emerging Players:Pursue untapped markets in emerging economies where healthcare infrastructure is expanding. Develop product line extensions for adjacent mobility aids like walkers and knee scooters, leveraging material science expertise. The most penetrable segment is the patient-driven direct-to-consumer channel, allowing for higher margins on value-added products. Focus digital marketing on demonstrable patient benefits and improved recovery outcomes.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized medical device manufacturers with robust regulatory compliance and intellectual property in material science. The market exhibits long-term viability, driven by aging demographics and consistent orthopedic surgery volumes. Watch for increasing adoption rates of ergonomic and advanced material pads within rehabilitation centers as a key inflection indicator. Prioritize companies with established direct-to-consumer channels.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Ensures access to the European Union market by meeting stringent Medical Device Regulation standards. |
| Product Line Extension | Leverages existing material science expertise to develop cushioning for adjacent mobility aids. |
| Direct-to-Consumer Launch | Bypasses traditional distributors to capture higher margins and build direct patient relationships. |
| Hospital System Partnership | Secures procurement contracts and validates advanced product performance in clinical settings. |
| Material Science R&D | Develops next-generation composites for superior pressure distribution and user comfort. |
Research Approach
The analysis maps crutch pad material segments, design categories, and end-user channels, each validated through extensive interviews with clinicians and procurement specialists. Primary research involved orthopedic surgeons, rehabilitation therapists, and medical device engineers. This was triangulated with secondary sources including FDA filings, EU MDR guidance documents, and healthcare expenditure databases. A combination of bottom-up and top-down approaches ensured data accuracy.
Assumptions regarding healthcare spending and regulatory stability were held fixed, while material innovation and demographic shifts were varied across the analysis window. The analytical framework modeled segmentation dimensions including material, design, application, end-user, and geographic region. Compound annual growth rates were derived from historical trends and projected orthopedic surgery volumes. Aging population growth rates served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or raw material pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and technological advancement. Unforeseen changes in medical device regulations or supply chain disruptions could also impact projections. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Blood Bags Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Luer Plug Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Europe Ostomy Care and Accessories Market
Medical Supplies
Cryotubes Market