
 United States Intravenous Solutions Market | 2026-2036
United States Intravenous Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
United States Intravenous Solutions Market Intelligence
Asset-light leasing models for sterile manufacturing equipment are narrowing the capital barrier for mid-scale entrants. Baxter leverages its integrated supply chain to sustain national distribution reach. Fresenius Kabi AG anchors its position through captive production of active pharmaceutical ingredients. B. Braun Medical Inc. differentiates via specialized filling lines for electrolyte-balanced formulations.
United States intravenous solutions comprise sterile, pyrogen-free aqueous preparations administered directly into the venous circulation, typically formulated with sodium chloride, dextrose, lactated Ringer's, or electrolyte combinations at specific osmolarities ranging from 250 to 1100 mOsm/L. These solutions serve primarily to restore fluid volume, correct electrolyte imbalances, and deliver parenteral nutrition in acute and chronic care settings. Crystalloid formulations dominate hospital procurement due to standardized reimbursement and broad clinical utility, while specialty solutions command premium positioning in oncology and immunoglobulin therapy. Parenteral nutrition applications are expanding fastest among home care segments as discharge protocols shift toward outpatient management.
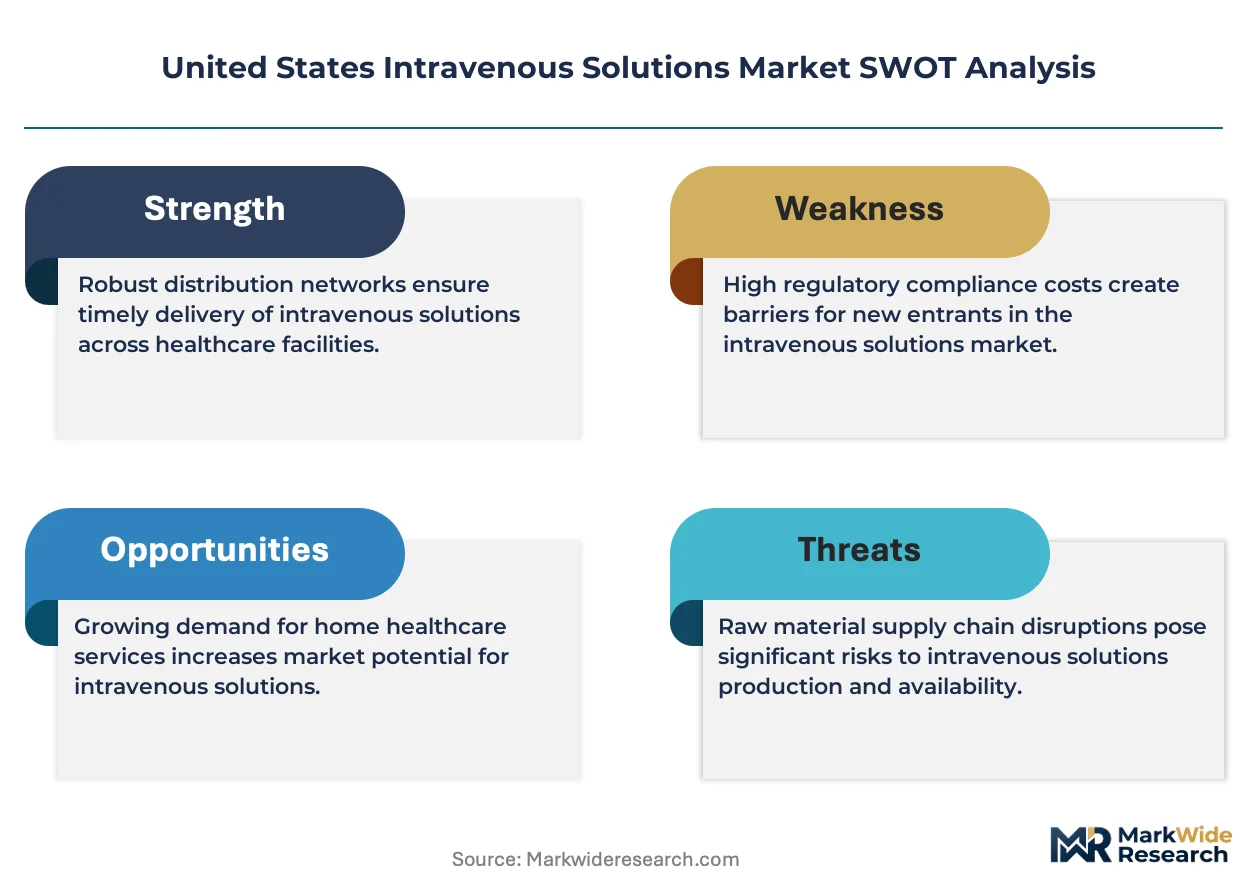
FDA oversight of Current Good Manufacturing Practice, USP Chapter 797 sterile compounding standards, and DEA controlled-substance tracking requirements collectively elevate compliance costs and consolidate purchasing toward validated suppliers. The FDA's quality metrics reporting program is reshaping supplier qualification timelines for hospital formularies. Stakeholders must monitor how CMS reimbursement adjustments for site-neutral payment affect channel economics between acute and ambulatory settings.
Market Dynamics
FDA's updated USP Chapter 797 sterile compounding standards are compressing supplier qualification timelines and forcing hospital systems to consolidate formularies around validated manufacturers with closed-system transfer device capabilities.
Growth Catalysts
- Ambulatory infusion center expansion:Hospital systems in Texas, Florida, and California are converting inpatient capacity to outpatient sites, multiplying IV solution touchpoints beyond traditional acute care.
- Home parenteral nutrition protocols:CMS reimbursement shifts toward site-neutral payment accelerate discharge-to-home programs for chronic patients requiring long-term intravenous feeding.
- USP Chapter 797 compliance mandates:The FDA's sterile compounding guidance drives replacement demand for legacy open-system equipment with closed-system transfer devices across hospital pharmacies.
Market Restraints
- Active pharmaceutical ingredient concentration:Captive API production by integrated manufacturers limits sourcing flexibility for mid-scale compounders dependent on external suppliers.
- Polypropylene resin volatility:Input costs for primary packaging materials fluctuate with petrochemical feedstock pricing, compressing margin stability for non-integrated filling operations.
- DEA controlled-substance tracking:Narcotic-containing IV formulations require serialized chain-of-custody documentation that extends production lead times and compliance overhead.
Strategic Opportunities
- Electrolyte-balanced oncology formulations:Specialized lines for chemotherapy hydration protocols command premium positioning as cancer centers expand infusion capacity.
- Asset-light equipment leasing:Third-party sterile manufacturing equipment financing narrows capital barriers for regional entrants targeting mid-volume hospital contracts.
- California aging demographic concentration:Population over-65 growth in Los Angeles and San Diego metro areas concentrates surgical volume and chronic care demand for crystalloid solutions.
Industry Challenges
- Pharmaceutical engineering talent scarcity:Qualified sterile process engineers command premium compensation in biologics hubs, draining available labor pools for IV solution manufacturing facilities.
- Legacy ERP integration friction:Hospital procurement systems require custom API connections to manufacturer ordering platforms, extending implementation timelines for new supplier onboarding.
- Quality metrics reporting standardization:The FDA's voluntary quality metrics program lacks uniform data formats, forcing redundant reporting investments for multi-site manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Intravenous Solutions Market |
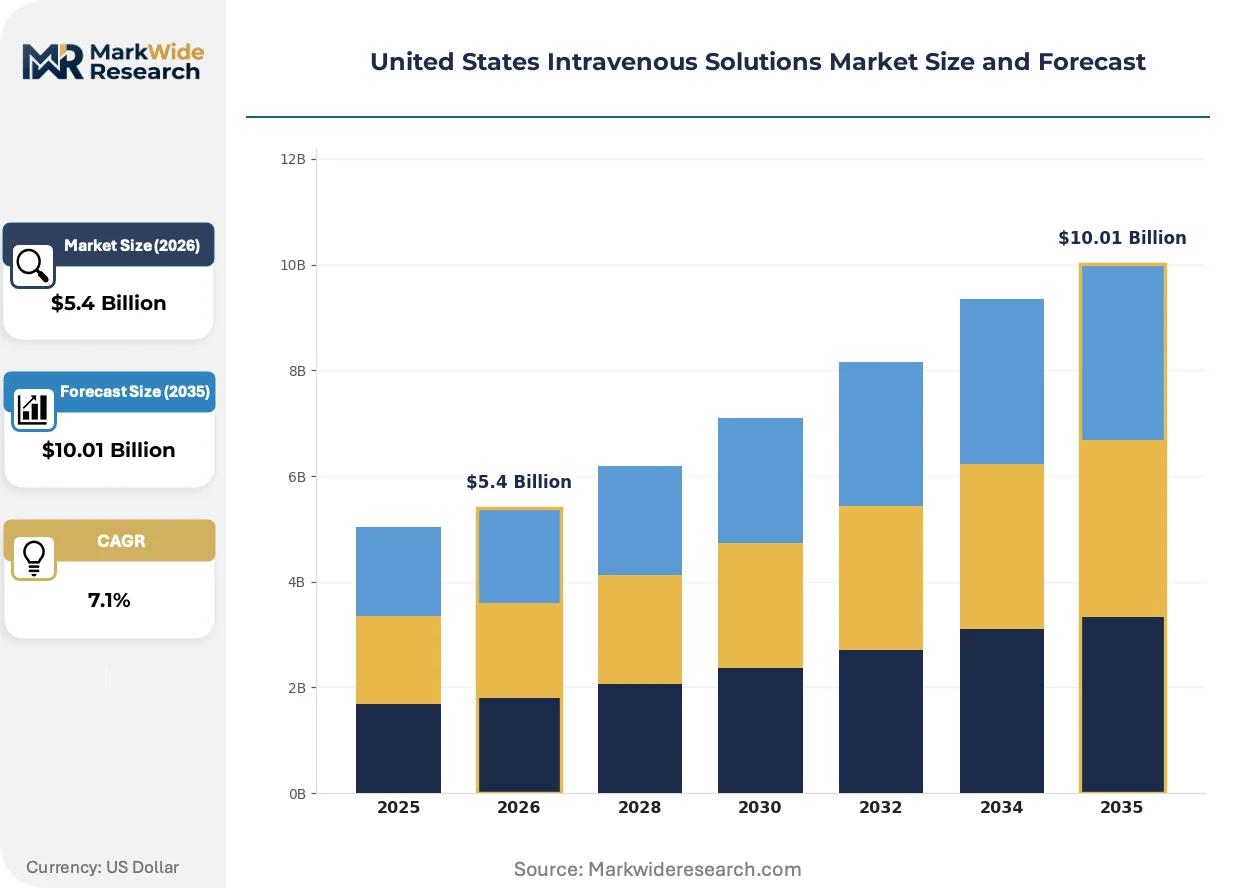
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $10.01 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalloids, Colloids, Specialty Solutions, Hypertonic Solutions Application: Parenteral Nutrition, Fluid Resuscitation, Medical Emergencies, Maintenance Hydration End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Distribution Channel: Direct Sales, Online Retail, Distributors, Pharmacies |
| Companies Covered | Baxter, Fresenius Kabi AG, B. Braun Medical Inc, ICU Medical, Pfizer Inc., JW Life Science, Grifols, Amphastar Pharmaceuticals, Inc., Otsuka Pharmaceutical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Intravenous Solutions Market Strategic Shifts & Innovations
Closed-system drug transfer devices are compressing contamination risk profiles while reshaping capital allocation patterns across hospital pharmacy infrastructure investments.
Closed-system transfer device technology is hybridizing mechanical barrier engineering with automated compounding workflow integration. Oncology and hazardous drug handling units in tertiary hospitals adopt these systems fastest to protect pharmacy technicians from exposure. The technology is hybridizing previously separate containment and automation markets into unified platform procurement decisions.
FDA's quality metrics reporting program is mandating standardized manufacturing performance disclosures from sterile compounders. The initiative compresses supplier qualification timelines by giving hospital formularies pre-validated performance baselines. IV solution manufacturers with multi-site networks face the steepest compliance burden as they harmonize data collection across legacy facilities.
Hospital procurement departments are unbundling IV solution contracts from traditional broadline distributor agreements. Direct manufacturer relationships are displacing intermediary markup structures for high-volume crystalloid categories. This pattern concentrates in California and Texas health systems with sufficient scale to justify dedicated logistics coordination.
United States Intravenous Solutions Market Segmentation
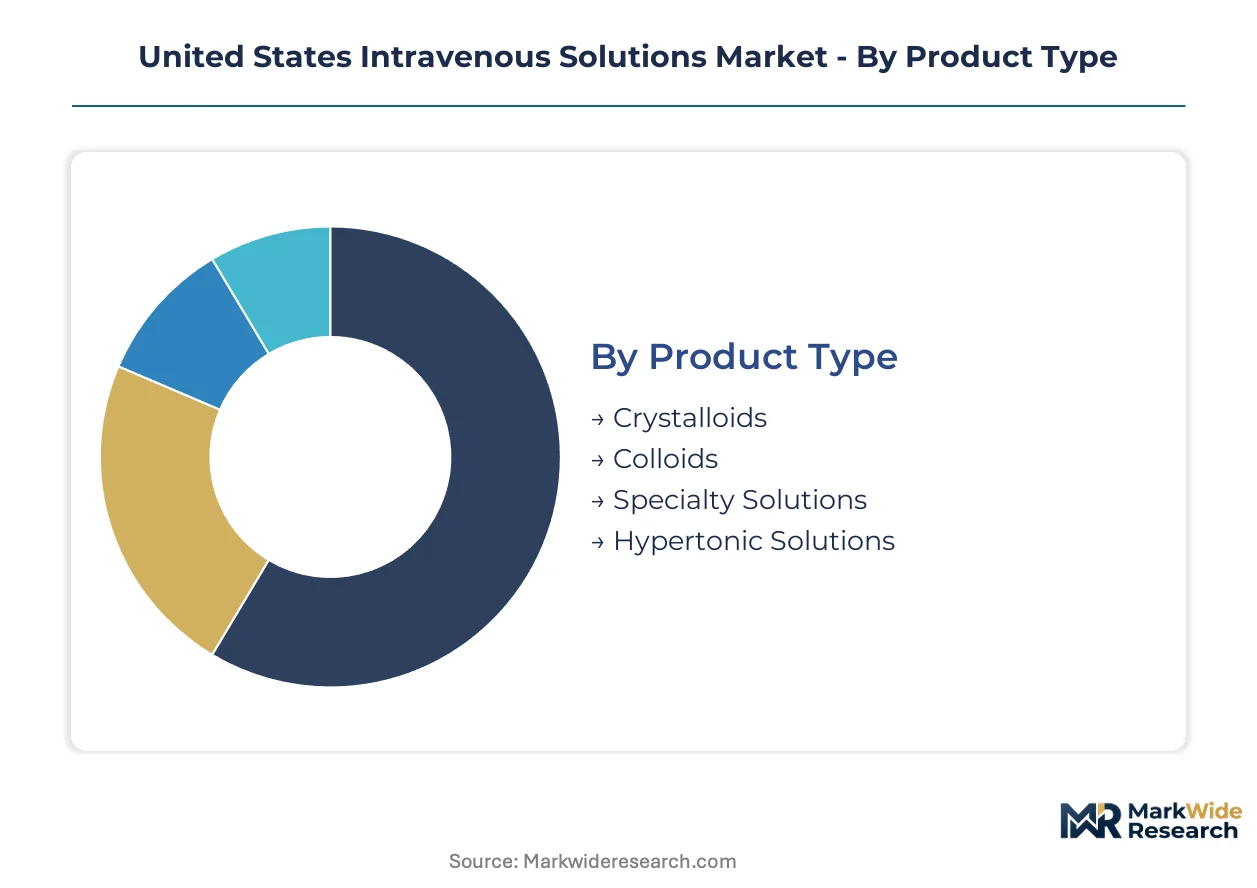
Segmentation in the United States intravenous solutions market reveals distinct procurement patterns across clinical settings. Crystalloid formulations dominate hospital formularies through standardized reimbursement, while specialty solutions command premium positioning in oncology and home care segments where clinical specificity drives selection criteria.
Product Type:
Crystalloid formulations turn over fastest through high-volume surgical and emergency protocols, while specialty solutions cycle slowly due to compounding complexity and narrow therapeutic indications.
- Crystalloids:Aqueous solutions containing sodium chloride, dextrose, or lactated Ringer's at osmolarities between 250-1100 mOsm/L. Demand concentrates in Texas and Florida hospital systems where ambulatory surgery expansion multiplies standard fluid resuscitation touchpoints. These formulations face margin pressure from direct manufacturer contracting that eliminates distributor markups.
- Specialty Solutions:Custom-compounded preparations for chemotherapy hydration, immunoglobulin therapy, and electrolyte-specific protocols. California cancer centers in Los Angeles and San Diego metro areas drive fastest expansion as infusion capacity expands beyond acute care. USP Chapter 797 compliance mandates favor validated manufacturers with closed-system transfer capabilities.
- Colloids:Albumin and synthetic plasma expanders for volume resuscitation in critical care settings. Blood bank partnerships and restricted formulary status limit penetration outside tertiary hospitals.
- Hypertonic Solutions:High-osmolarity preparations for hyponatremia correction and intracranial pressure management. Neurological intensive care units in academic medical centers represent primary demand concentration.
Crystalloids dominate installed base. Specialty solutions are where expansion concentrates.
Application:
Cost tier stratification separates commodity fluid replacement from premium parenteral nutrition, with reimbursement differentials shaping procurement concentration across acute versus chronic care settings.
- Fluid Resuscitation:Emergency and perioperative volume replacement using standardized crystalloid protocols. Hospital systems in Florida and Texas convert inpatient capacity to ambulatory sites, redistributing resuscitation demand across emergency departments and surgical centers.
- Parenteral Nutrition:Complete intravenous feeding for patients with non-functional gastrointestinal tracts. Home care segments in California climb the fastest as CMS site-neutral payment accelerates discharge-to-home programs for chronic patients requiring long-term nutritional support.
- Maintenance Hydration:Routine electrolyte and fluid balance management in medical-surgical units. Standardized protocols limit differentiation and compress margins toward commodity pricing.
- Medical Emergencies:Rapid infusion protocols for trauma, sepsis, and shock management. Emergency medical services and trauma centers require immediate availability with minimal supply chain friction.
Fluid resuscitation captures highest volume throughput. Parenteral nutrition is where margin expansion concentrates.
End User:
Customer type determines packaging specifications, with hospitals demanding bulk containers and home care requiring portable systems that accommodate patient mobility and caregiver training constraints.
- Hospitals:Acute care facilities with centralized pharmacy compounding and high-volume automated dispensing. Texas, Florida, and California health systems unbundle IV contracts from broadline distributors to secure direct manufacturer pricing on crystalloid categories.
- Home Care:Outpatient settings where patients or caregivers administer prolonged intravenous therapy. This segment gains share fastest as discharge protocols shift chronic parenteral nutrition and hydration to residential environments with remote monitoring support.
- Clinics:Ambulatory infusion centers for chemotherapy, hydration, and antibiotic administration. Oncology-focused facilities in California metro areas drive specialized solution demand.
- Rehabilitation Centers:Post-acute facilities managing transitional intravenous therapy. Lower acuity requirements limit formulation complexity compared to acute settings.
Hospitals anchor procurement volume. Home care is where patient touchpoint expansion concentrates.
Distribution Channel:
Supply concentration varies by channel control, with direct sales capturing high-volume hospital contracts while distributors retain fragmented clinic and pharmacy relationships.
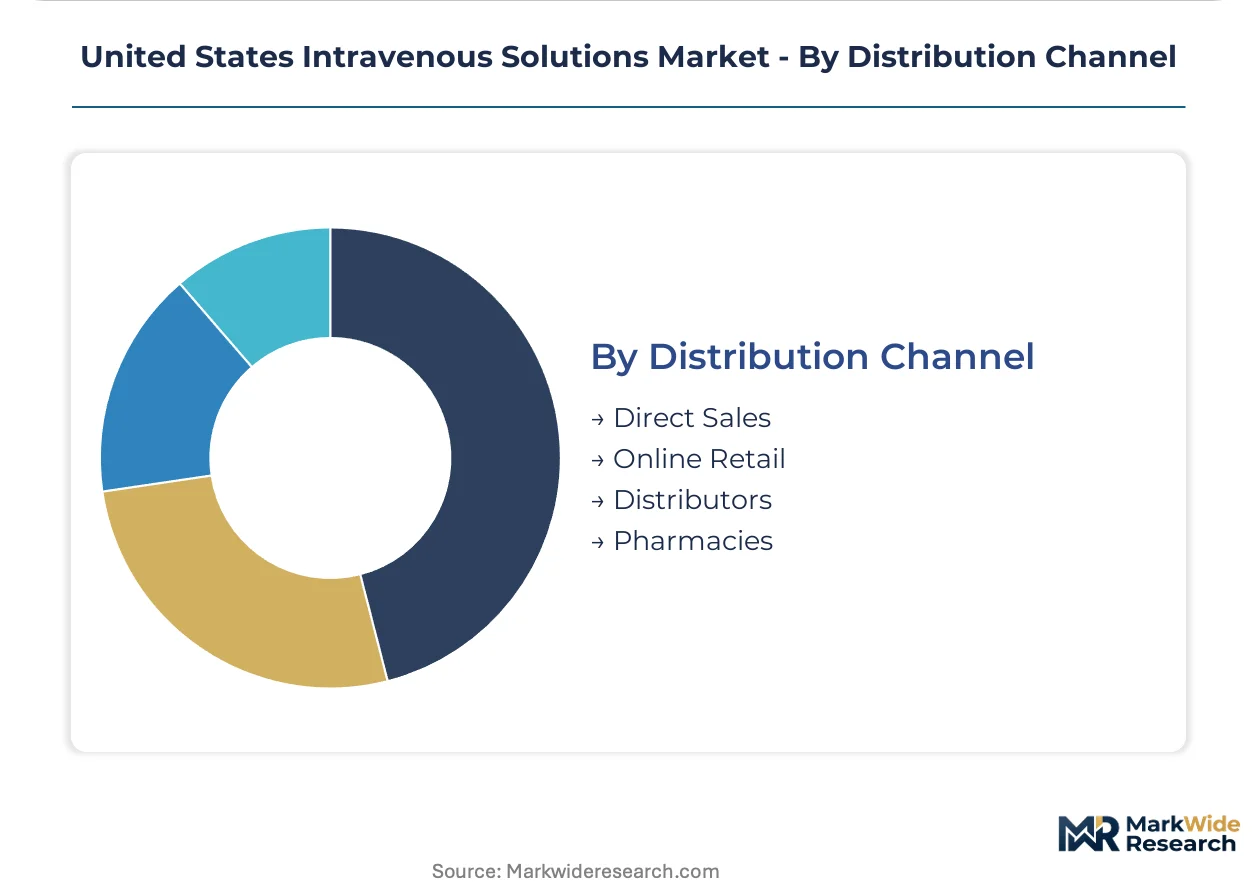
- Direct Sales:Manufacturer-to-hospital relationships eliminating intermediary margins. California and Texas health systems with sufficient procurement scale justify dedicated logistics coordination for crystalloid categories.
- Distributors:Broadline and specialty medical-surgical distributors serving mid-scale facilities. Regional warehousing networks address fragmentation across smaller hospital systems and independent clinics.
- Pharmacies:Retail and hospital outpatient pharmacies for home care patient pickup. Convenience positioning supports maintenance hydration and limited parenteral nutrition prescriptions.
- Online Retail:Emerging channel for home care supplies and patient-direct ordering. Regulatory constraints on sterile compounding limit expansion beyond ancillary equipment and accessories.
Direct sales dominate high-volume crystalloid movement. Distributors retain clinic and rehabilitation center concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's updated USP Chapter 797 sterile compounding standards are redistributing procurement concentration toward states with the densest hospital infrastructure and fastest-growing ambulatory networks.
California
Los Angeles and San Diego metro areas concentrate oncology infusion capacity expansion as cancer centers convert inpatient beds to outpatient sites. CMS site-neutral payment policies accelerate discharge-to-home parenteral nutrition programs across the state's aging coastal counties. Northern California's integrated health systems unbundle IV solution contracts from broadline distributors to secure direct manufacturer pricing on crystalloid categories.
Texas
Houston and Dallas-Fort Worth hospital systems lead ambulatory surgery center conversion, multiplying standard fluid resuscitation touchpoints beyond traditional acute care. State Medicaid expansion debates influence reimbursement stability for home infusion services in rural counties. The Texas Medical Center anchors demand for closed-system transfer devices as pharmacy compounding volumes scale.
Florida
Retirement corridor demographics from Tampa through Miami concentrate chronic parenteral nutrition demand as discharge protocols shift elderly patients to residential settings. Florida Hospital Association quality initiatives align formulary consolidation with USP Chapter 797 compliance timelines. Orlando's surgical tourism clusters drive crystalloid throughput for elective procedure volume.
New York Metro
Tertiary academic medical centers in Manhattan and Long Island maintain specialized hypertonic solution demand for neurological intensive care. New York State Department of Health regulations on sterile compounding facility licensing compress supplier qualification pools. Westchester and northern New Jersey suburban systems expand home infusion networks with remote monitoring infrastructure.
Illinois
Chicago's integrated delivery networks centralize pharmacy compounding across multi-hospital systems, favoring validated manufacturers with national distribution reach. Illinois Hospital Association group purchasing contracts consolidate crystalloid procurement around direct sales relationships. Downstate rural hospitals rely on distributor networks for fragmented clinic and rehabilitation center coverage.
United States Intravenous Solutions Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers: integrated pharmaceutical conglomerates with captive API production, mid-scale regional compounders leveraging asset-light equipment leasing, and niche oncology formulation specialists. Consolidation pressure intensifies as FDA quality metrics reporting forces multi-site manufacturers to harmonize data collection across legacy facilities. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic partnerships with closed-system transfer device manufacturers.
Among integrated pharmaceutical conglomerates, Baxter, Fresenius Kabi AG, and B. Braun Medical Inc. occupy positions defined by supply chain architecture rather than product differentiation alone. Baxter exemplifies the channel-control archetype through national distribution infrastructure. Fresenius Kabi AG anchors the captive-production tier with in-house active pharmaceutical ingredient capabilities. B. Braun Medical Inc. represents specialization within electrolyte-balanced formulation segments. These three entities collectively illustrate how vertical scope determines competitive position in a market where FDA compliance costs consolidate purchasing toward validated suppliers.
| Leading Market Players |
|---|
| Baxter |
| Fresenius Kabi AG |
| B. Braun Medical Inc |
| ICU Medical |
| Pfizer Inc. |
| JW Life Science |
| Grifols |
| Amphastar Pharmaceuticals, Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The North Carolina Research Triangle anchors sterile manufacturing capacity dynamics that translate directly into downstream pricing power for crystalloid categories. FDA-validated facilities in this cluster command premium positioning as hospital systems consolidate formularies around USP Chapter 797-compliant suppliers, while non-integrated compounders absorb margin compression from polypropylene resin volatility.
Pricing Analysis
Certification level creates the primary spread between premium FDA-validated manufacturers and regional compounders operating under transitional compliance timelines. Three-tier pricing structure separates closed-system transfer device portfolios from legacy open-system equipment from commodity crystalloid bulk contracts. Cost compression in standard crystalloid tiers is intensifying because direct manufacturer contracting eliminates distributor markups in Texas and California health systems. Hospital procurement committees demonstrate highest price sensitivity on maintenance hydration protocols, while oncology infusion centers show lowest sensitivity for chemotherapy hydration formulations.
Supply Chain Analysis
Polypropylene resin feedstock draws from petrochemical complexes along the US Gulf Coast, with secondary sourcing from Northeast Asian suppliers. Active pharmaceutical ingredients for electrolyte formulations rest on captive production by integrated manufacturers in Germany and Switzerland, plus contract manufacturing in India. Single-source vulnerability concentrates in DEA-controlled narcotic precursors subject to serialized chain-of-custody documentation. Distribution runs through direct sales relationships for high-volume hospital contracts, with regional distributors retaining fragmented clinic and home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense defines strategic priority as oral rehydration protocols and biosimilar infusion alternatives threaten standard crystalloid volume. Incumbents must navigate this displacement pressure while consolidating procurement relationships.
For Market Incumbents: Insulate market position through backward integration into active pharmaceutical ingredient supply and accelerated closed-system transfer device certification. Baxter and Fresenius Kabi demonstrate defensive value of captive electrolyte production. Channel control investments in direct logistics coordination with Texas and California health systems provide pricing power insulation against regional compounders.
For New Entrants and Emerging Players: Pursue asset-light equipment leasing models targeting mid-scale hospital systems in Florida's retirement corridor. California home parenteral nutrition expansion represents the most penetrable segment given CMS site-neutral payment acceleration. Go-to-market positioning through remote monitoring partnerships differentiates against incumbent distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core infusion therapy units. Long-term viability centers on FDA quality metrics reporting compliance as a consolidation catalyst. Watch for inflection signals in hospital formulary consolidation velocity across Texas Medical Center systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Transfer Device Certification | FDA USP Chapter 797 compliance mandates accelerate replacement demand across hospital pharmacies. |
| Backward Integration into API Supply | Captive electrolyte production insulates margin stability from external sourcing constraints. |
| Direct Hospital System Contracting | Unbundling from broadline distributors eliminates intermediary markups in high-volume crystalloid categories. |
| Home Infusion Network Expansion | CMS site-neutral payment policies accelerate discharge-to-home parenteral nutrition program growth. |
| Quality Metrics Reporting Harmonization | Multi-site manufacturers face steepest compliance burden as FDA standardizes performance disclosures. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with hospital pharmacy directors, sterile compounding supervisors, GPO contract managers, and home infusion coordinators; and secondary validation against FDA quality metrics disclosures, CMS reimbursement databases, hospital procurement records, and USP Chapter 797 implementation timelines. Bottom-up volume modeling triangulated against top-down expenditure analysis across acute care, ambulatory, and home care settings.
Forecast inputs incorporated product type segmentation across crystalloid, specialty solution, colloid, and hypertonic categories; application dimensions spanning fluid resuscitation, parenteral nutrition, maintenance hydration, and emergency protocols; and end-user stratification between hospitals, home care, clinics, and rehabilitation centers. CAGRs derived from regression analysis against surgical volume projections, aging demographic trajectories, and ambulatory conversion rates across the analysis window. Industry-specific inputs included polypropylene resin price indices and DEA controlled-substance tracking compliance costs.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, petrochemical feedstock pricing, or FDA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about ambulatory surgery expansion and sterile compounding regulatory adherence. Cross-checking against hospital capital expenditure surveys and GPO contract renewal patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
NPWT Canisters Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Global Surgical Masks Market