
 Premixed IV Minibags Market | 2026-2036
Premixed IV Minibags Market Size, Share, and Industry Trends Forecast 2026-2036
Premixed IV Minibags Market Analytics
Closed-system transfer technology is narrowing the gap between manual compounding and factory-premixed sterile delivery. Baxter International leverages its integrated plasma and IV solutions portfolio to sustain manufacturing scale across North American and European hospital networks. Fresenius Kabi anchors its position through specialized oncology and anesthesia premix lines, while B. Braun Melsungen competes on automated filling systems that reduce particle contamination risk.
Premixed IV minibags are sterile, single-use flexible containers prefilled with precisely dosed injectable solutions ranging from 50 mL to 250 mL, manufactured under aseptic blow-fill-seal or form-fill-seal processes to eliminate end-user compounding. Their primary purpose is to deliver immediate, error-free intravenous therapy in acute care settings where dosing accuracy and sterility assurance are critical. Electrolyte solutions dominate current volume due to routine perioperative and critical care consumption, while antibiotic solutions represent the fastest-expanding margin pool as antimicrobial stewardship programs restrict ward-level compounding. Flexible bag packaging leads unit demand because of compatibility with smart infusion pumps and reduced storage footprint versus glass alternatives.
The FDA enforces current Good Manufacturing Practice standards for sterile premixed products under 21 CFR Parts 210 and 211, while the EMA's Annex 1 revision mandates stricter barrier isolation for aseptic processing of ready-to-administer medicines. These frameworks elevate capital requirements for new entrants and reinforce incumbent quality systems. Stakeholders must monitor evolving USP <797> and <800> compounding exemptions that could either expand or constrain hospital purchase of factory-premixed alternatives.
Market Dynamics
Health system consolidation in the United States is concentrating purchasing power among integrated delivery networks, forcing manufacturers to negotiate multi-year supply agreements that prioritize standardization over product variety. This structural shift toward centralized procurement is compressing margins for regional compounders while rewarding scaled aseptic manufacturers with dedicated blow-fill-seal capacity.
Growth Catalysts
- USP <797> compounding exemptions:The revised United States Pharmacopeia standards for sterile compounding are narrowing the conditions under which hospitals may compound intravenous medications on-site, channeling volume toward factory-premixed alternatives that bypass ward-level quality risks.
- Closed-system transfer devices:Mechanical barrier technologies for hazardous drug handling are integrating with premixed minibag formats, creating closed-loop administration systems that reduce occupational exposure while streamlining nursing workflow in oncology units.
- Antimicrobial stewardship mandates:Hospital accreditation requirements for restricted antibiotic compounding are eliminating batch preparation of high-cost antimicrobials in pharmacy cleanrooms, accelerating conversion to manufacturer-prepared vancomycin and piperacillin-tazobactam minibags.
Market Restraints
- Polypropylene resin volatility:Flexible bag production depends on medical-grade polymer feedstocks whose pricing fluctuates with petrochemical cycles, compressing gross margins when resin costs spike without corresponding price pass-through to hospital purchasers.
- EMA Annex 1 barrier requirements:The European Medicines Agency's revised aseptic processing mandate demands isolator technology and continuous monitoring systems that elevate capital intensity for new production lines, deterring mid-scale entrants from European market participation.
- Glass vial substitution in biologics:Protein-based therapies requiring cold-chain stability continue to favor borosilicate glass containers over polymer minibags, limiting addressable market expansion in the fastest-growing injectable therapeutic category.
Strategic Opportunities
- Ambulatory surgery center expansion:Freestanding outpatient surgical facilities in Texas and Florida are converting from traditional compounding to ready-to-administer anesthesia and analgesia minibags, creating a distribution channel with higher per-unit margins and lower service requirements than acute care hospitals.
- Smart pump interoperability standards:The IEEE 11073 device communication protocol is enabling bidirectional data exchange between premixed minibag barcodes and infusion pump libraries, reducing programming errors and creating premium positioning for manufacturers with integrated informatics capabilities.
- Japan's GMP foreign manufacturer registration:The Pharmaceuticals and Medical Devices Agency pathway for overseas aseptic facilities is opening access to the world's third-largest hospital market for North American and European premixed suppliers with established blow-fill-seal expertise.
Industry Challenges
- Aseptic process engineer scarcity:Qualified personnel capable of validating blow-fill-seal lines under FDA current Good Manufacturing Practice standards command compensation premiums that inflate fixed costs for capacity expansion projects.
- Legacy pharmacy information system integration:Hospital electronic medication administration record platforms require customized interface development to recognize manufacturer-specific minibag nomenclature, delaying contract implementation and extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premixed IV Minibags Market |
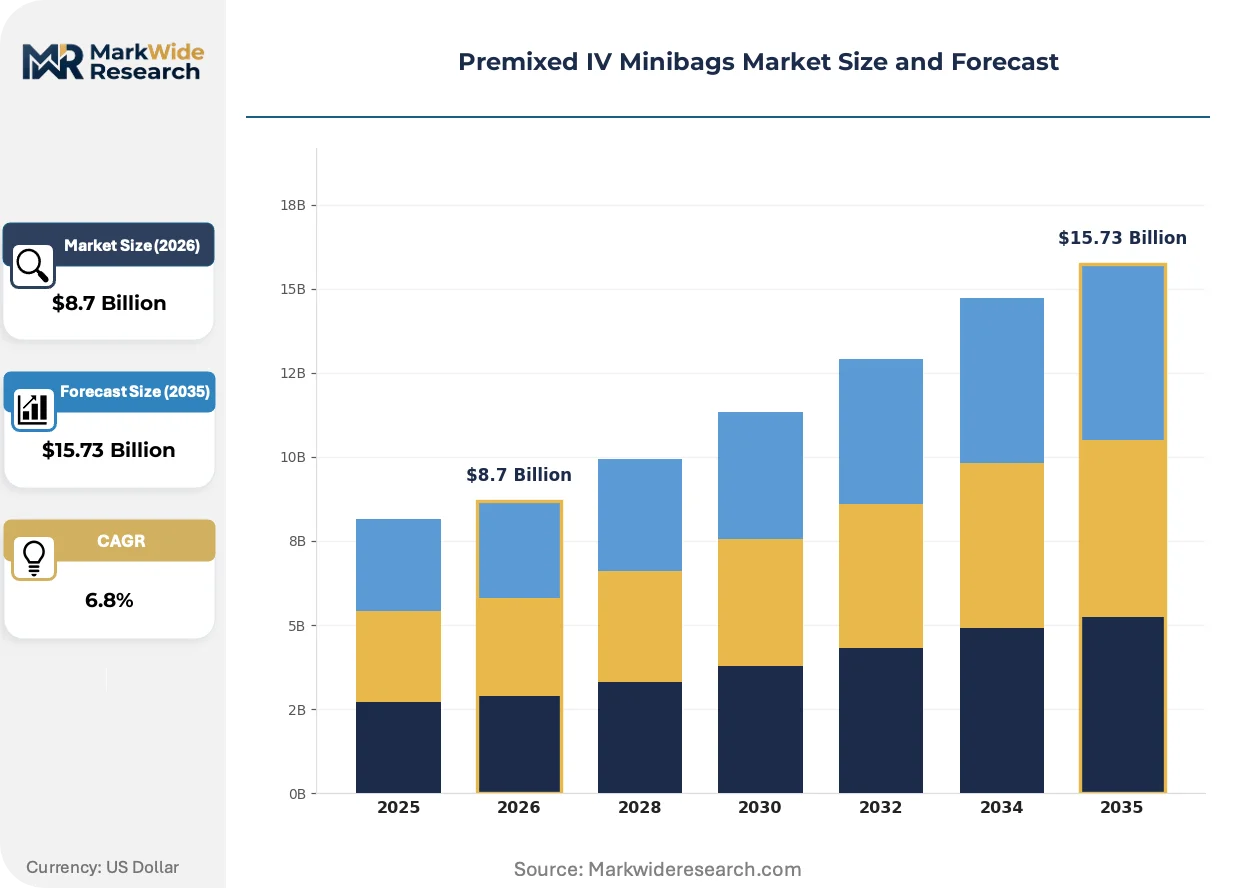
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Solutions, Nutrient Solutions, Antibiotic Solutions, Hormone Solutions End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Distribution Channel: Direct Sales, Online Retail, Pharmacies, Wholesalers Packaging Type: Flexible Bags, Vials, Bottles, Specialty Containers |
| Companies Covered | Baxter International, Fresenius Kabi, B. Braun Melsungen, ICU Medical, Sippex IV Bag Solutions, Renolit, Technoflex, JW Life Science, Polycine GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premixed IV Minibags Market Evolving Landscape
Digital integration across the medication use process is transforming premixed IV minibags from passive containers into data-enabled therapeutic delivery systems. Manufacturers are embedding traceability infrastructure and connectivity features that align with hospital quality imperatives.
Radio-frequency identification tagging is digitizing supply chain visibility for high-value premixed antibiotics and chemotherapy agents. Integrated delivery networks in California and Massachusetts are mandating RFID-enabled inventory at the point of care, enabling automated restocking and expiration management that reduces waste in pharmacy satellite locations. This connectivity infrastructure is digitizing the shift from periodic physical audits to continuous digital monitoring of medication availability.
The FDA's draft guidance on post-approval manufacturing changes for sterile products is tightening change-control requirements for formulation modifications and packaging material substitutions. Manufacturers must now conduct enhanced stability studies and leachable assessments before implementing process improvements, extending product lifecycle management timelines. Small-volume parenteral suppliers with limited regulatory affairs capacity are outsourcing compliance documentation to specialized consulting firms.
Hospital pharmacy directors are consolidating supplier relationships through sole-source agreements that bundle premixed minibags with complementary infusion devices and clinical education services. This procurement consolidation displaces fragmented multi-vendor purchasing that previously separated bag supply from pump acquisition. The trend is most pronounced in multi-hospital systems across the Midwestern United States, where standardization committees now evaluate total cost of therapy rather than unit price alone.
Premixed IV Minibags Market Segmentation
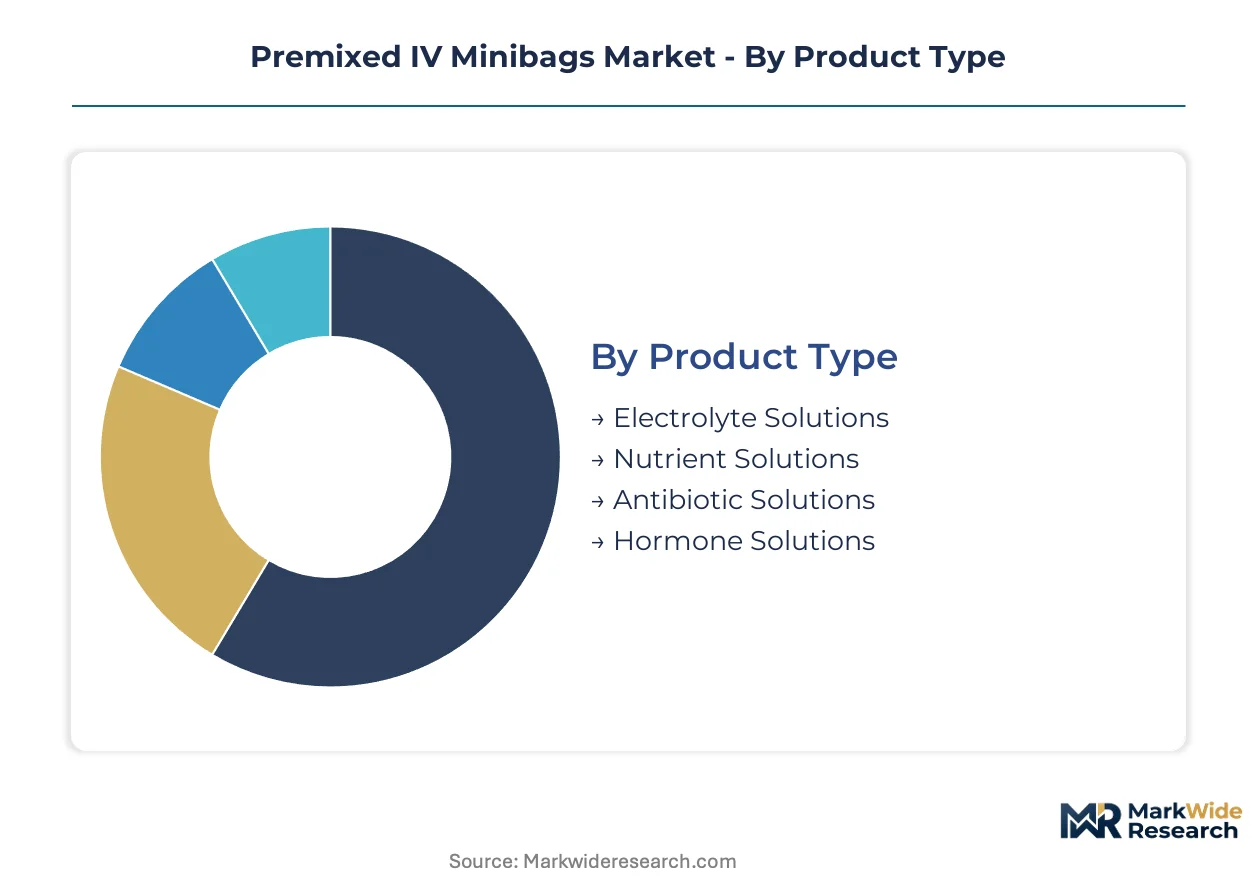
Premixed IV minibags segment across therapeutic purpose, care setting, procurement pathway, and container format. Each dimension shapes manufacturing priorities, regulatory pathways, and margin structures differently.
Product Type:
Cost tier differentiation separates commodity electrolyte formulations from premium antibiotic and hormone preparations.
- Electrolyte Solutions:Sodium chloride, potassium chloride, and balanced crystalloid formulations constitute high-volume, standardized products for perioperative fluid resuscitation and critical care maintenance. Demand concentrates in United States integrated delivery networks where centralized procurement favors single-source contracts for routine hydration therapy.
- Antibiotic Solutions:Manufacturer-premixed vancomycin, piperacillin-tazobactam, and cefepim eliminate ward-level compounding errors while satisfying Joint Commission antimicrobial stewardship requirements. Hospital pharmacy directors in California and Texas systems are converting high-cost antimicrobial batches to factory-premixed formats to reduce cleanroom labor and waste from expired batch preparations.
- Nutrient Solutions:Parenteral nutrition emulsions combining amino acids, dextrose, and lipids serve malabsorption patients requiring prolonged intravenous feeding.
- Hormone Solutions:Insulin and vasopressin premixes address narrow therapeutic index requirements in intensive care units.
Electrolyte Solutions command the established base. The steepest expansion runs through Antibiotic Solutions.
End User:
Customer type determines service intensity, with acute hospitals demanding technical support while ambulatory settings prioritize logistics efficiency.
- Hospitals:Tertiary medical centers and community hospitals generate the majority of premixed minibag consumption through emergency departments, operating suites, and intensive care units. United States health system consolidation is concentrating purchasing power among integrated delivery networks that negotiate multi-year supply agreements with blow-fill-seal manufacturers.
- Home Care:Infusion therapy providers administering parenteral antibiotics and nutrition in residential settings represent the fastest-climbing volume channel as hospital-at-home programs expand reimbursement eligibility.
- Clinics:Outpatient infusion centers for oncology and rheumatology rely on premixed chemotherapy and biologic support solutions.
- Long-term Care Facilities:Skilled nursing facilities utilize premixed hydration and antibiotic therapy for residents with limited venous access.
Hospitals anchor current procurement volume. Home Care registers the steepest upward trajectory.
Distribution Channel:
Supply concentration varies by channel control, with direct manufacturer relationships displacing intermediary layers in high-volume accounts.
- Direct Sales:Manufacturer field representatives negotiate enterprise contracts directly with hospital system pharmacy directors, bundling premixed minibags with infusion pumps and clinical education services. This channel captures the majority of United States acute care volume through sole-source agreements that standardize formularies across multi-hospital networks.
- Wholesalers:Cardinal Health, McKesson, and AmerisourceBergen distribute to smaller hospitals and regional systems lacking direct manufacturer relationships.
- Pharmacies:Retail and specialty pharmacy locations serve outpatient parenteral therapy patients with take-home antibiotic and nutrition minibags.
- Online Retail:Direct-to-consumer platforms support home infusion patients with recurring supply needs.
Direct Sales holds the dominant share. Wholesalers retain importance in fragmented regional markets.
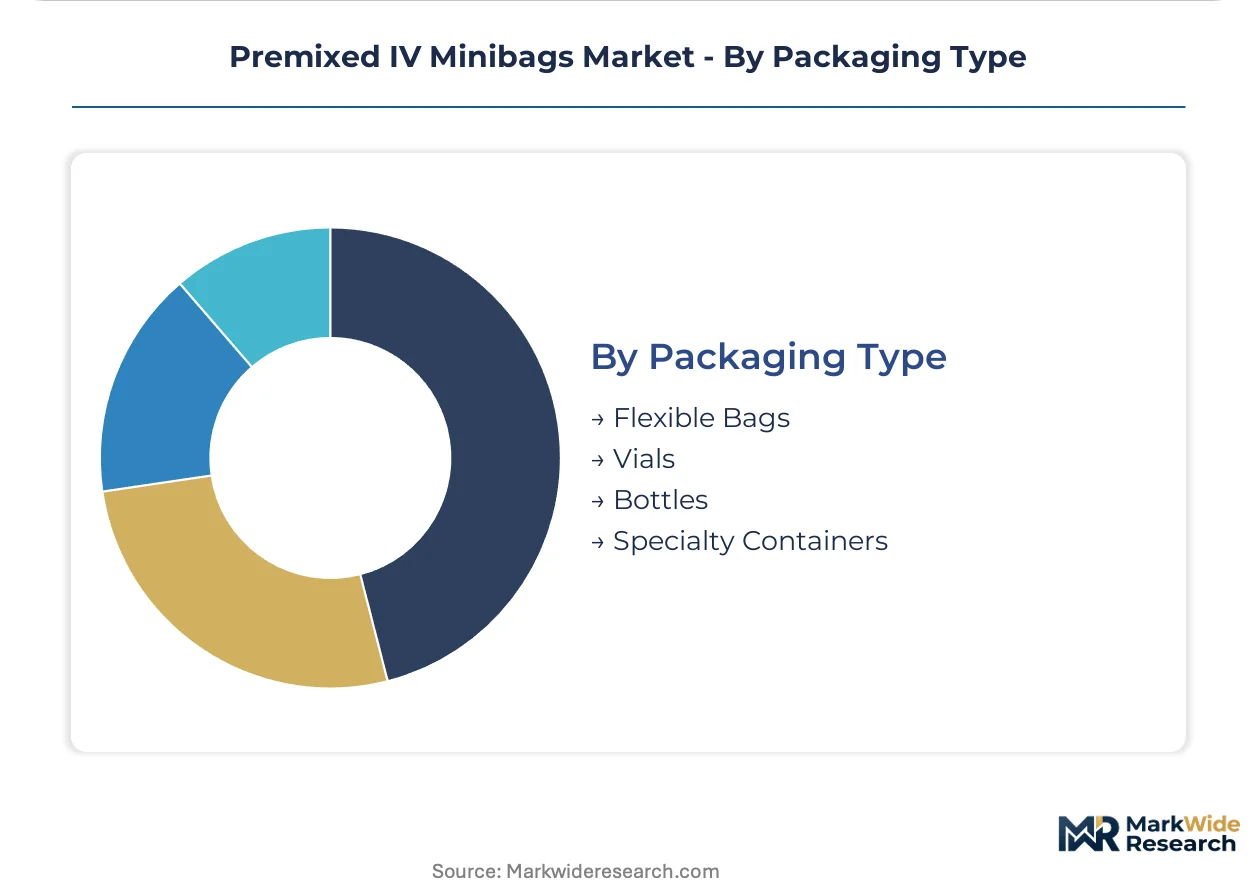
Packaging Type:
Volume and material specifications drive manufacturing capital allocation, with flexible polymer formats displacing rigid alternatives in most therapeutic categories.
- Flexible Bags:Polypropylene and multilayer film containers manufactured via blow-fill-seal or form-fill-seal processes dominate unit demand due to compatibility with smart infusion pumps, reduced storage footprint, and lower breakage rates versus glass. Baxter International and B. Braun Melsungen operate dedicated flexible bag capacity across North American and European manufacturing networks.
- Vials:Borosilicate glass containers persist for protein-based biologics requiring cold-chain stability and oxygen barrier properties that polymer films cannot replicate.
- Bottles:Rigid plastic containers serve select irrigation and diagnostic contrast applications.
- Specialty Containers:Closed-system transfer device-integrated bags for hazardous drug handling address oncology nursing safety requirements.
Flexible Bags generate the established volume base. Specialty Containers post the most rapid share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export blow-fill-seal machinery and flexible polymer films to United States hospital networks, while Japanese regulators certify foreign aseptic facilities for Asia-Pacific market entry.
United States
Integrated delivery networks in Texas and California are consolidating premixed minibag procurement through sole-source agreements that standardize formularies across multi-hospital systems. FDA enforcement of USP <797> compounding exemptions is narrowing ward-level preparation permissions, channeling antibiotic and electrolyte volume toward factory-premixed formats. The Midwest hospital corridor spanning Illinois, Michigan, and Ohio represents the densest concentration of automated dispensing cabinet installations.
Germany
Baden-Württemberg and Bavaria host specialized machinery fabricators supplying blow-fill-seal lines to North American and European aseptic manufacturers. EMA Annex 1 barrier isolation mandates are elevating capital requirements for new entrants, reinforcing incumbent quality systems among established producers. The Rhine-Main industrial cluster around Frankfurt anchors polymer resin processing and medical-grade film extrusion capacity.
Japan
PMDA foreign manufacturer registration pathways are opening access for North American and European premixed suppliers with established aseptic expertise. Hospital pharmacy directors in Tokyo and Osaka are converting high-cost antimicrobial batches to ready-to-administer formats to reduce cleanroom labor. The Kansai region's medical device manufacturing base supports integrated infusion pump and minibag system development.
China
NMPA regulatory harmonization is accelerating for imported sterile premixed products as domestic hospital groups upgrade to international GMP standards. Yangtze River Delta health systems in Shanghai and Jiangsu are piloting smart pump interoperability with barcode-enabled minibag traceability. The Pearl River Delta's polymer processing capacity supplies medical-grade films for regional flexible container production.
India
CDSCO import licensing reforms are streamlining entry for factory-premixed antibiotics and parenteral nutrition emulsions into tertiary hospital networks. Maharashtra and Karnataka hospital chains are expanding ambulatory surgery center networks that favor ready-to-administer anesthesia minibags. The Delhi-NCR corridor's pharmacy wholesale distribution infrastructure supports cold-chain logistics for temperature-sensitive premixed formulations.
Premixed IV Minibags Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market structure concentrates among scaled aseptic manufacturers with dedicated blow-fill-seal capacity and integrated delivery network contracts. Three archetypes dominate: diversified medical technology conglomerates with plasma and IV solution portfolios, specialized parenteral drug manufacturers with oncology and anesthesia premix lines, and flexible packaging specialists with automated filling systems. Competitive moves center on multi-year supply agreement negotiations and backward integration into polymer resin processing.
Within the diversified conglomerate tier, Baxter International and Fresenius Kabi represent channel-controlling positions through integrated hospital network relationships. B. Braun Melsungen occupies a product-specialist position with emphasis on automated manufacturing systems. These three entities exemplify the scale-driven archetype that dominates procurement consolidation trends among United States integrated delivery networks.
| Leading Market Players |
|---|
| Baxter International |
| Fresenius Kabi |
| B. Braun Melsungen |
| ICU Medical |
| Sippex IV Bag Solutions |
| Renolit |
| Technoflex |
| JW Life Science |
| Polycine GmbH |
| Others |
Value Network & Pricing Analysis
German blow-fill-seal machinery fabricators and North American medical-grade polymer resin suppliers anchor upstream concentration, directing margin pools toward manufacturers with captive aseptic filling capacity and multi-year hospital system contracts.
Pricing Analysis
Blow-fill-seal line generation gaps separate pricing tiers, with legacy form-fill-seal equipment producing standard electrolyte minibags at commodity margins while next-generation isolator-integrated systems command premium positioning for antibiotic and oncology formulations. Three-tier pricing structure across premium isolator-certified, standard aseptic, and economy non-hazardous tiers reflects FDA compliance grade and closed-system transfer device integration. Pricing pressure stems from polypropylene resin volatility compressing gross margins during petrochemical cycle spikes. Integrated delivery networks exhibit lowest price sensitivity due to standardization mandates, while regional ambulatory surgery centers negotiate aggressively on per-unit costs.
Supply Chain Analysis
Extended payment terms from United States integrated delivery networks now stretch to 90-120 days, forcing manufacturers to deploy supply-chain finance facilities backed by polymer resin inventory. Production concentrates in the United States, Germany, and Japan, with Baden-Württemberg machinery exports feeding North American flexible bag lines. Medical-grade polypropylene resin, multilayer barrier films, and blow-fill-seal equipment constitute critical input dependencies. Single-source vulnerability runs through German isolator technology suppliers for EMA Annex 1 compliance. Distribution runs through direct manufacturer field representatives for acute care volume, with Cardinal Health and McKesson serving fragmented regional hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health system consolidation is fragmenting procurement authority between centralized pharmacy committees and satellite facility managers, creating niche entry points for specialized premix suppliers with rapid formulary customization capabilities.
For Market Incumbents: Pre-empt biosimilar and personalized medicine formats by acquiring blow-fill-seal capacity with isolator technology for cell therapy diluents. Lock in backward integration into medical-grade polymer resin processing to defend margin position against petrochemical volatility. Secure sole-source agreements with emerging hospital-at-home programs before regional compounders establish service relationships.
For New Entrants and Emerging Players: Pursue Japan's PMDA foreign manufacturer registration pathway to access the third-largest hospital market with limited incumbent competition. Target Texas and Florida ambulatory surgery center expansion with ready-to-administer anesthesia minibags carrying higher per-unit margins than acute care contracts. Deploy RFID-enabled inventory management as a differentiated service bundle to bypass entrenched wholesaler relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed flexible packaging specialists lacking integrated infusion pump partnerships, creating rollup opportunities for hospital system bundling strategies. Five-to-ten year viability hinges on antimicrobial stewardship mandate expansion and smart pump interoperability certification. Watch USP <797> compounding exemption enforcement intensity as the signal for factory-premixed volume inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Certification | EMA Annex 1 compliance elevates barrier isolation requirements for European market participation. |
| RFID-Enabled Inventory Integration | California and Massachusetts IDN mandates drive automated restocking and expiration management adoption. |
| Backward Resin Integration | Captive polypropylene processing insulates gross margins from petrochemical cycle volatility. |
| Hospital-at-Home Partnership | Expanding reimbursement eligibility for residential parenteral therapy creates new distribution channels. |
| Smart Pump Interoperability | IEEE 11073 protocol compliance reduces programming errors and enables premium positioning. |
Research Methodology
The analysis maps electrolyte solution, antibiotic solution, nutrient solution, and hormone solution sub-sectors, each validated through hospital pharmacy directors, GPO contracts managers, blow-fill-seal equipment engineers, and regulatory affairs specialists. Primary interviews with integrated delivery network procurement committees and aseptic manufacturing operations heads combined with secondary validation from FDA 483 inspection databases, EMA GMP certificates, USP compounding exemption guidance documents, and hospital procurement database filings. Bottom-up volume modeling across therapeutic categories triangulated against top-down health system expenditure estimates.
Assumptions held USP <797> enforcement trajectory, EMA Annex 1 implementation timeline, and smart pump interoperability adoption rates fixed across the projection horizon, while varying polymer resin pricing scenarios and health system consolidation pace. Segmentation dimensions modeled include therapeutic purpose, care setting acuity, procurement pathway control, and container format technology. CAGRs derived from facility-level volume buildups weighted by IDN market share concentration, with antibiotic premix conversion rates and ambulatory surgery center expansion serving as key forecast inputs.
Sensitivities concentrate around FDA guidance finalization on post-approval manufacturing changes, PMDA foreign manufacturer registration processing timelines, and polypropylene resin supply disruptions. Forecasts reflect documented assumptions on regulatory enforcement intensity and hospital capital expenditure cycles. Macroeconomic contraction, regulatory enforcement deviation, or breakthrough compounding automation technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Sterile Container Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Medical Procedure Tray Market