
 Europe Surgical Glue Market | 2026-2036
Europe Surgical Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Surgical Glue Market Insights
CE-marked Class III biocompatibility standards is rotating the Europe surgical glue market toward higher-validation product tiers. Baxter International leverages its hemostasis portfolio to sustain leadership in fibrin-based formulations. Johnson & Johnson anchors its position through broad surgical channel control across Continental Europe. Medtronic competes with concentrated R&D intensity in cardiovascular application segments.
Surgical glue comprises sterile tissue adhesives formulated from cyanoacrylate esters, fibrinogen-thrombin complexes, or silicone polymers, designed to achieve hemostasis or wound closure without suture mechanical fixation. These materials polymerize upon tissue contact to form flexible or rigid bonds depending on monomer composition, with set times ranging from ten seconds to two minutes. Fibrin-based variants command premium positioning in neurological and cardiovascular surgery where bioresorbability limits inflammatory response. Cyanoacrylate formulations dominate general surgery volume through rapid polymerization and lower per-unit cost. Albumin-derived sealants occupy a narrower niche serving specialized orthopedic procedures requiring extended adhesion duration.
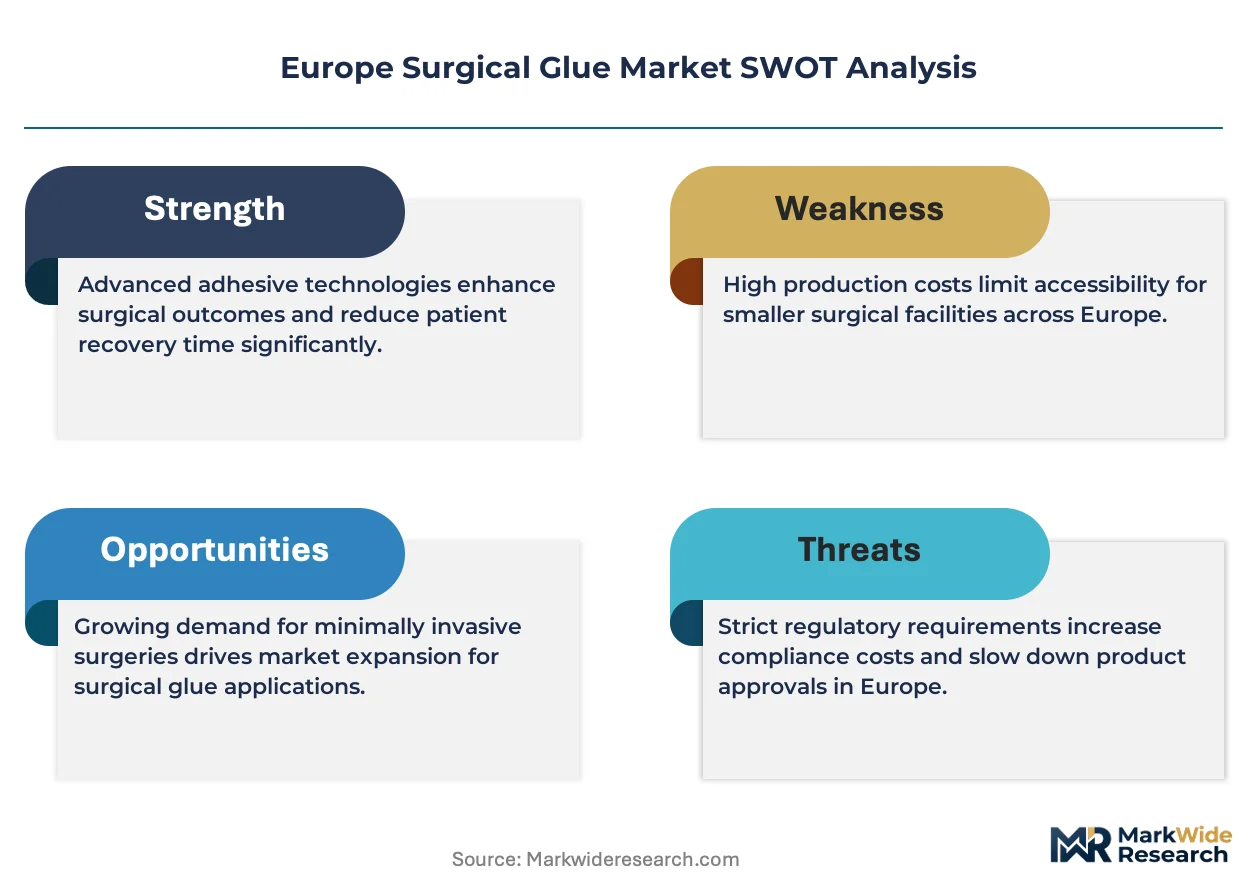
The EU Medical Device Regulation and EMA biocompatibility frameworks now mandate expanded clinical evidence for implantable adhesive classifications, extending approval timelines and elevating compliance costs for market entrants. REACH chemical safety protocols additionally govern cyanoacrylate monomer sourcing and manufacturing waste streams across European production facilities. Germany's national pharmaceutical regulator enforces supplementary post-market surveillance requirements that shape regional competitive dynamics. Stakeholders must monitor evolving notified body designation patterns and preemptively align quality management systems with anticipated MDR enforcement intensification.
Market Dynamics
MDR biocompatibility validation timelines are compressing competitive timelines across Europe's surgical adhesive sector, forcing manufacturers to front-load clinical evidence generation before notified body submissions.
Growth Catalysts
- EU Medical Device Regulation Class III pathways:Elevated biocompatibility standards for implantable sealants create tiered market access that rewards pre-validated portfolios.
- Minimally invasive cardiac surgery:German hospital networks are expanding fibrin-based adhesive protocols to reduce sternal wound complications and bypass graft anastomosis times.
- Cyanoacrylate polymerization speed:Ten-second set times enable ambulatory surgical center throughput gains that suture-based closure cannot match.
Market Restraints
- Notified body capacity bottlenecks:MDR designation delays extend approval timelines for novel adhesive formulations seeking CE marking.
- Bovine-derived fibrinogen sourcing:Supply concentration in South American plasma collection exposes European manufacturers to BSE-related import restrictions.
- Suture-subsistence in cost-sensitive settings:Mechanical closure retains dominance in Eastern European public procurement where per-procedure adhesive premiums face budget scrutiny.
Strategic Opportunities
- Poland and Czech Republic orthopedic expansion:Underpenetrated arthroscopy volumes create first-mover positioning for albumin-derived sealants requiring extended adhesion duration.
- EMA pediatric investigation plans:Regulatory incentives for neonatal cardiac adhesive applications open specialized indication pathways with orphan-like exclusivity potential.
- Silicone-polymer hybrid convergence:Combining bioresorbability with elastic modulus matching enables neurosurgical dural sealant applications beyond current cyanoacrylate rigidity limits.
Industry Challenges
- Polymer chemistry specialization scarcity:Formulation scientists with cyanoacrylate kinetics expertise command premium compensation that mid-cap entrants struggle to match.
- Legacy ERP integration with UDI compliance:European manufacturers face capex burdens retrofitting traceability systems for MDR unique device identifier mandates.
- ISO 10993-6 implantation study timelines:Extended histopathology evaluation periods delay product launches even after technical validation completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Surgical Glue Market |
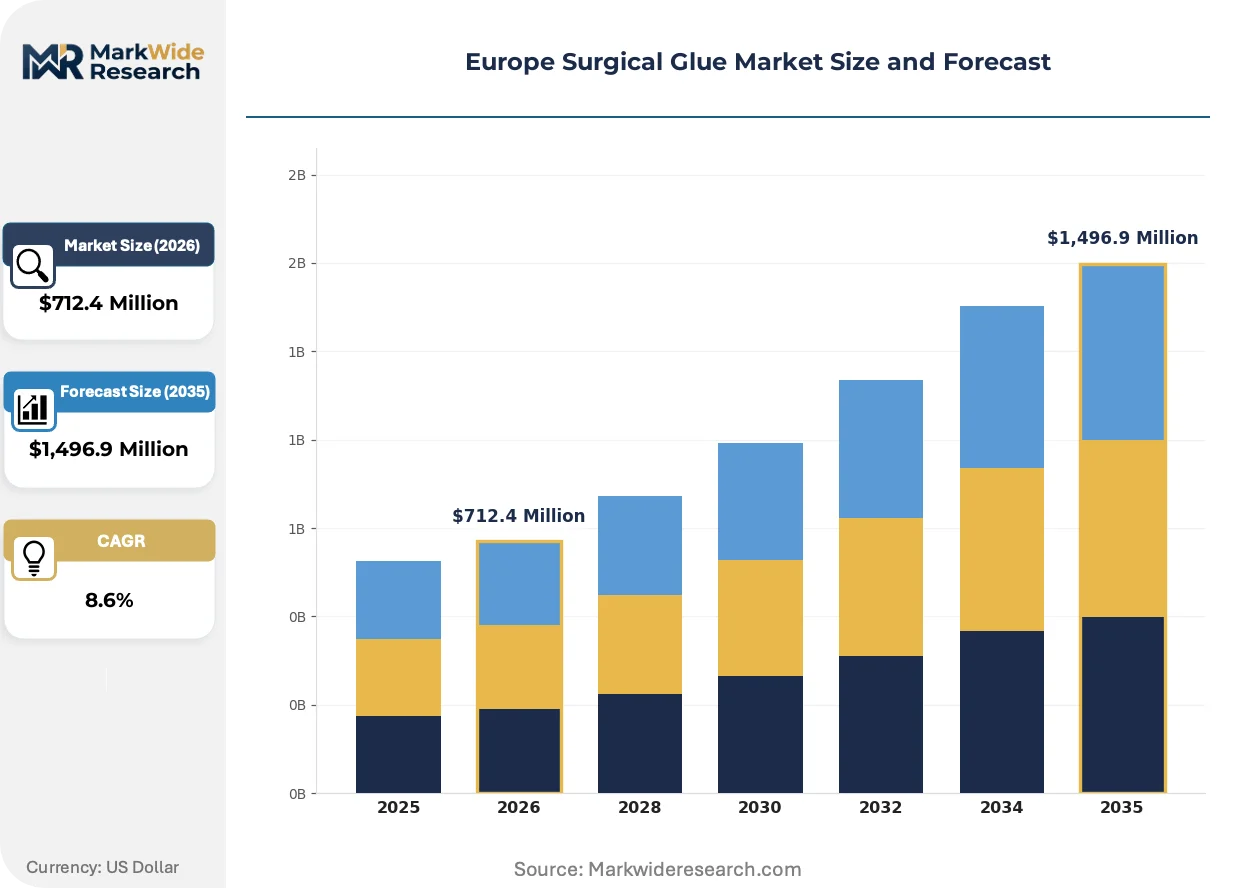
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,496.9 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyanoacrylate, Fibrin, Silicone, Albumin End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Centers Application: Orthopedic Surgery, Cardiovascular Surgery, Neurological Surgery, General Surgery Distribution Channel: Direct Sales, Retail Pharmacies, Online Sales, Distributors |
| Companies Covered | B. Braun Melsungen AG, Johnson & Johnson, Medtronic, Baxter International, Advanced Medical Solutions Group plc, Artivion, Cardinal Health, Integra LifeSciences Holdings Corporation, Adhesys Medical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Surgical Glue Market Trends and Innovations
Bioresorbable polymer engineering is compressing the performance gap between synthetic adhesives and biological sealants, redirecting R&D investment toward hybrid material architectures.
Photocurable cyanoacrylate variants are supplanting conventional moisture-activated formulations in German microvascular surgery suites. University hospital procurement committees in Berlin and Munich specify light-triggered polymerization for procedures requiring precise adhesion zone control. This shift is compressing demand for traditional high-viscosity cyanoacrylates in premium cardiovascular applications.
REACH chemical safety protocols now mandate full monomer supply chain disclosure for cyanoacrylate manufacturers operating European production facilities. ECHA substance of very high concern listings threaten raw material access for non-compliant formulators. German producers are responding by securing captive ethyl-2-cyanoacrylate supply through backward integration into monomer synthesis.
Hospital buying consortiums in France and Italy are consolidating surgical adhesive procurement through framework agreements that bundle sealants with hemostasis portfolios. Independent distributors lose shelf access as direct manufacturer-contractor relationships displace traditional medical supply intermediaries. This concentration is most visible in Lombardy and Ile-de-France where regional health authorities centralize purchasing for multiple facility networks.
Europe Surgical Glue Market Segmentation
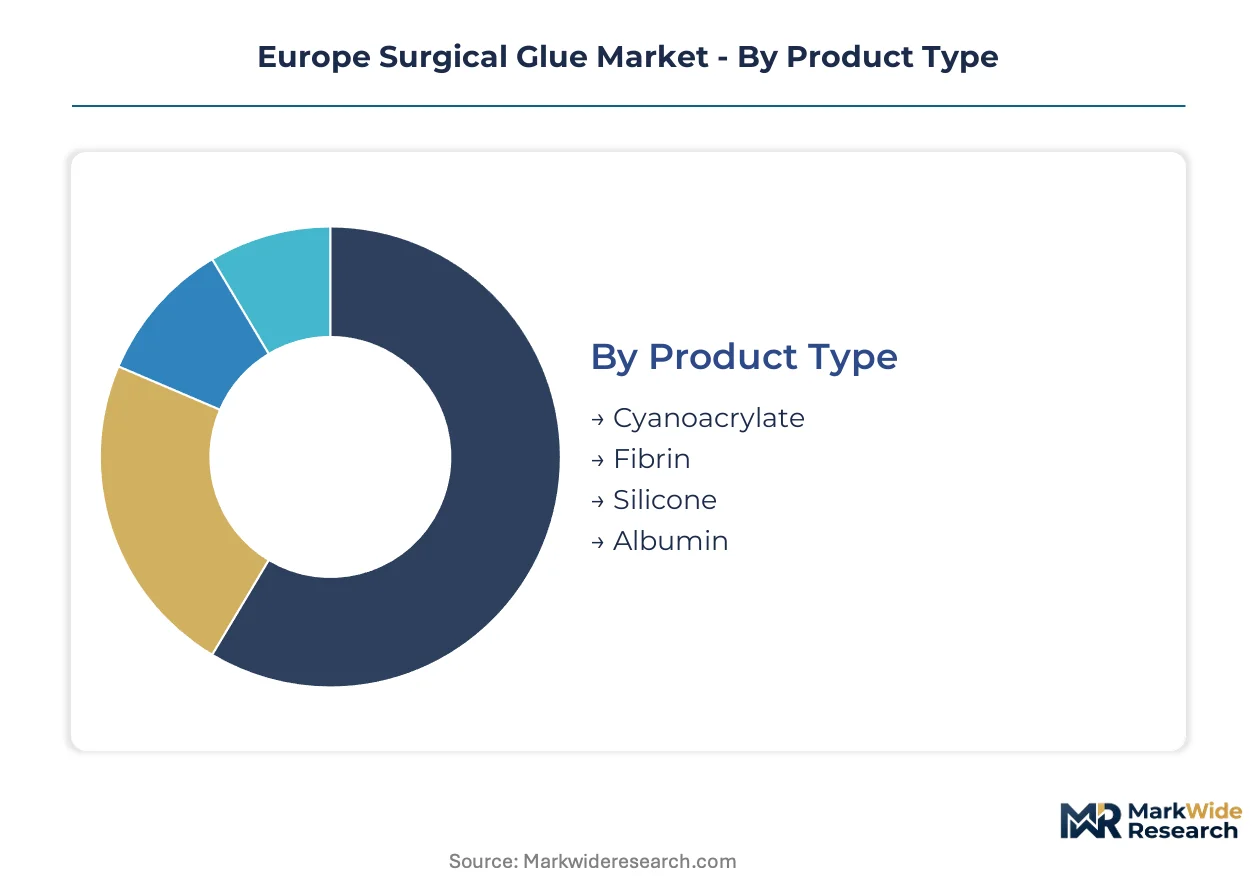
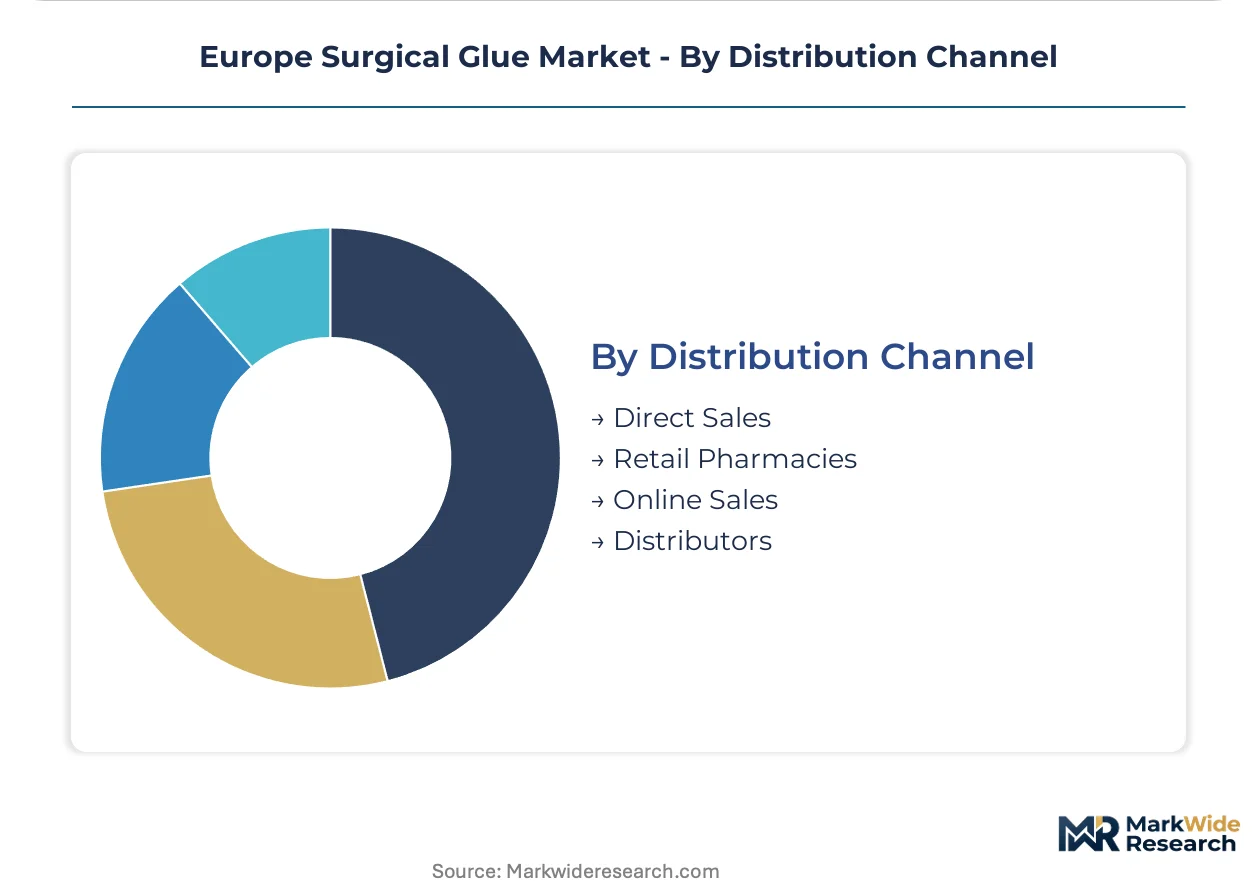
Surgical glue segmentation in Europe reflects divergent margin economics across material chemistries and procurement channels. Product type and distribution channel splits reveal where manufacturers capture premium pricing versus where volume throughput dominates revenue.
Product Type:
Premium margin pools concentrate in bioresorbable formulations where MDR Class III validation creates regulatory moats.
- Fibrin:Derived from pooled human plasma, fibrin sealants polymerize through thrombin-mediated clotting cascades to achieve hemostasis in wet surgical fields. German cardiac surgery networks specify fibrin for internal mammary artery anastomosis, where biocompatibility limits graft occlusion risk. REACH protocols on bovine-derived raw materials constrain South American plasma sourcing, elevating European-manufactured fibrin pricing power.
- Cyanoacrylate:Synthetic esters polymerize on tissue contact through anionic initiation, achieving ten-second set times that enable ambulatory throughput. French and Italian general surgery volumes drive cyanoacrylate demand, though ECHA substance of high concern listings threaten ethyl-2-cyanoacrylate supply security for non-integrated producers.
- Silicone:Cross-linked polydimethylsiloxane formulations provide elastic adhesion for dural closure applications. The segment serves narrow neurosurgical indications requiring modulus matching with native tissue.
- Albumin:Denatured serum protein adhesives deliver extended adhesion duration for orthopedic procedures. Czech and Polish arthroscopy expansion is rotating demand toward albumin variants.
Fibrin holds installed capacity. Cyanoacrylate is rotating up the share rankings.
End User:
Procurement concentration determines pricing leverage, with hospital consortiums extracting volume discounts unavailable to fragmented buyers.
- Hospitals:Tertiary centers in Germany, France, and Italy bundle surgical adhesive procurement with hemostasis portfolios through framework agreements. Lombardy and Ile-de-France regional health authorities centralize purchasing across multiple facility networks, compressing distributor margins.
- Ambulatory Surgical Centers:German outpatient cardiac and orthopedic volumes favor rapid-set cyanoacrylates that enable same-day discharge protocols. Ten-second polymerization eliminates suture time burdens that constrain hourly case throughput.
- Clinics:Independent dermatology and plastic surgery practices in Spain and Portugal source lower-volume cyanoacrylate units through retail pharmacy channels.
- Specialty Centers:Concentrated neurosurgical and cardiovascular facilities in Berlin and Munich specify light-curable adhesive variants for microvascular precision.
Hospitals command procurement scale. Ambulatory Surgical Centers are expanding most quickly.
Application:
Procedure reimbursement intensity shapes adhesive specification, with cardiac and neurological surgery supporting premium bioresorbable pricing.
- Cardiovascular Surgery:German hospital networks are expanding fibrin-based protocols to reduce sternal wound complications and bypass graft anastomosis times. MDR biocompatibility validation requirements elevate barriers for novel sealant entrants in implantable cardiac applications.
- Neurological Surgery:Photocurable cyanoacrylate variants are supplanting moisture-activated formulations in Berlin and Munich university hospitals. Light-triggered polymerization enables precise adhesion zone control for dural closure.
- Orthopedic Surgery:Arthroscopy volumes in Poland and Czech Republic create positioning for albumin-derived sealants requiring extended adhesion duration.
- General Surgery:Cyanoacrylate dominates volume through rapid polymerization and lower per-unit cost. French and Italian procurement committees specify synthetic adhesives for routine closure.
Cardiovascular Surgery holds installed capacity. Neurological Surgery is climbing the fastest.
Distribution Channel:
Channel structure is consolidating around direct manufacturer relationships that displace traditional medical supply intermediaries.
- Direct Sales:Hospital buying consortiums in France and Italy consolidate procurement through framework agreements bundling sealants with hemostasis portfolios. Independent distributors lose shelf access as manufacturers establish direct contractor relationships.
- Distributors:Regional medical supply intermediaries retain relevance in Eastern European markets where hospital network fragmentation prevents centralized purchasing.
- Retail Pharmacies:Spanish and Portuguese clinics source low-volume cyanoacrylate units through pharmacy channels for outpatient procedures.
- Online Sales:E-commerce penetration remains limited by MDR unique device identifier traceability requirements and cold-chain logistics for biological sealants.
Direct Sales holds installed capacity. Distributors are defending position in Eastern European fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European production of surgical adhesives clusters in Germany and Switzerland where fibrinogen processing capabilities and notified body proximity concentrate manufacturing investment. MDR compliance costs and REACH chemical governance favor incumbents with established quality systems.
Germany
Cardiac surgery volumes at Berlin Charité and Munich university hospitals drive fibrin sealant consumption for internal mammary artery grafting. The Federal Institute for Drugs and Medical Devices enforces supplementary post-market surveillance that extends validation timelines for novel entrants. Bavaria's medical technology corridor hosts concentrated adhesive manufacturing alongside hemostasis portfolio producers.
France
Île-de-France regional health authorities centralize procurement across Paris hospital networks, compressing distributor margins through framework agreements. ANSM pharmacovigilance requirements shape biocompatibility documentation standards for implantable sealants. The Lyon-Grenoble cluster sustains cyanoacrylate formulation expertise serving ambulatory surgical centers.
Italy
Lombardy's orthopedic arthroscopy expansion rotates demand toward albumin-derived sealants requiring extended adhesion duration. AIFA pricing negotiations constrain premium bioresorbable penetration in public procurement channels. Milan's procurement consortiums bundle sealants with hemostasis portfolios, displacing independent distributors.
Switzerland
Swissmedic's streamlined Class III pathways attract manufacturers seeking faster CE marking for novel polymer architectures. The Basel-Zurich corridor concentrates R&D investment in silicone-polymer hybrid formulations for neurosurgical applications. Geneva university hospitals specify photocurable variants for microvascular precision procedures.
Poland
Underpenetrated arthroscopy volumes in Warsaw and Kraków create positioning opportunities for extended-duration sealants. The national health fund's reimbursement constraints favor cost-effective cyanoacrylate volumes over premium bioresorbables. Silesian medical device distributors retain relevance where hospital network fragmentation prevents centralized purchasing.
Europe Surgical Glue Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Europe's surgical adhesive sector. The market structure consolidates around diversified medical device conglomerates with hemostasis portfolio breadth, while mid-cap specialists occupy narrower polymer chemistry niches. Three archetypes dominate: integrated surgical portfolio holders, fibrinogen supply specialists, and synthetic adhesive formulators. Competitive dynamics center on MDR validation speed and backward integration into monomer or plasma supply.
Within the integrated surgical portfolio tier, Baxter International and Johnson & Johnson anchor market presence through channel control and hemostasis bundling. Baxter exemplifies the fibrin-based validation leader, while Johnson & Johnson represents broad surgical access consolidation. Medtronic occupies a position concentrated in cardiovascular application R&D intensity. Among European specialists, B. Braun Melsungen AG and Advanced Medical Solutions Group plc sit within regional manufacturing and distribution archetypes serving fragmented procurement channels.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Medtronic |
| Baxter International |
| Advanced Medical Solutions Group plc |
| Artivion |
| Cardinal Health |
| Integra LifeSciences Holdings Corporation |
| Adhesys Medical |
| Others |
Pricing and Supply Chain Analysis
Installed fibrinogen processing capacity in Bavaria and Basel generates scale economies that simultaneously concentrate supply-side power and establish price floors for bioresorbable sealants. REACH chemical governance and MDR validation timelines amplify these effects by elevating fixed-cost thresholds that exclude marginal producers from premium tier participation.
Pricing Analysis
MDR Class III biocompatibility standards dictate the pricing tier structure across Europe's surgical adhesive sector. Three-tier pricing separates validated fibrin sealants from standard cyanoacrylates and economy-grade suture alternatives. Certification level and volume scale drive price differentiation, with hospital consortiums extracting discounts unavailable to fragmented clinic buyers. Cost compression in cyanoacrylate tiers is intensifying because ECHA substance of high concern listings threaten raw material access for non-integrated producers. Eastern European public procurement channels exhibit greatest price sensitivity, while German cardiac surgery networks demonstrate lowest elasticity due to outcome-linked reimbursement protocols.
Supply Chain Analysis
Just-in-time inventory preferences dominate biological sealant procurement, constraining manufacturers to maintain cold-chain buffer stocks at regional distribution hubs. Raw material sourcing concentrates in Germany, Switzerland, and South American plasma collection zones. European production draws from bovine-derived fibrinogen, ethyl-2-cyanoacrylate monomers, and pharmaceutical-grade albumin. Single-source vulnerability in South American plasma supply exposes formulators to BSE-related import restrictions. Distribution runs through direct manufacturer-hospital framework agreements in Western Europe, while regional distributors retain relevance in fragmented Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer chemistry expertise functions as the critical scarce capability in Europe's surgical adhesive sector, with formulation scientists commanding compensation premiums that reshape competitive access economics.
For Market Incumbents: Shield validated fibrin portfolios by accelerating backward integration into plasma sourcing and preemptively securing captive monomer synthesis capacity. Consolidate channel control through hemostasis bundling that displaces independent distributors from hospital consortium procurement. MDR enforcement intensification threatens margin compression for non-compliant legacy SKUs. For New Entrants and Emerging Players: Lead with albumin-derived sealant formulations targeting Poland and Czech Republic arthroscopy expansion where extended adhesion duration commands positioning premiums. Czech hospital network fragmentation creates accessible entry points outside consolidated Western European procurement structures. Partner with Silesian medical device distributors to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors synthetic-polymer hybrid specialists with silicone-cyanoacrylate convergence capabilities. Long-term viability hinges on regulatory validation speed rather than raw R&D throughput. Target acquisition archetypes include mid-cap formulators with notified body relationships and captive monomer supply. Watch EMA pediatric investigation plan approvals as inflection signals for specialized indication exclusivity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class III Validation Acceleration | Compressed approval timelines capture premium tier positioning before notified body capacity constraints intensify. |
| Backward Integration into Monomer Synthesis | Captive ethyl-2-cyanoacrylate supply insulates margins from ECHA substance of high concern listing disruptions. |
| Hospital System Partnership | Direct framework agreements with Lombardy and Ile-de-France authorities displace distributor intermediaries from procurement. |
| Silicone-Polymer Hybrid Development | Elastic modulus matching enables neurosurgical dural sealant applications beyond cyanoacrylate rigidity limits. |
| Pediatric Investigation Plan Submission | EMA incentives for neonatal cardiac applications open orphan-like exclusivity pathways with reduced competitive density. |
Research Methodology
Operator-level perspectives from cardiac surgeons, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EMA submission databases, notified body designation records, hospital procurement contract registries, and REACH chemical safety filings. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation generated convergent market size estimates.
Sensitivity analysis tested forecast robustness across MDR enforcement intensity scenarios and plasma supply disruption assumptions. Segmentation dimensions modeled include product chemistry, end-user facility type, surgical application, and distribution channel structure across the analysis window. CAGRs derived from procedure volume elasticity coefficients and pricing trajectory assumptions. Industry-specific inputs incorporated cardiac surgery admission trends and arthroscopy penetration rates in Central European markets.
Underlying assumptions cover stable REACH chemical governance and notified body capacity expansion, with deviation risk concentrated in South American plasma sourcing disruptions and MDR audit backlog accumulation. Practitioners should keep alternative scenarios live as EMA pediatric pathway incentives and photocurable adhesive adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Earwax Removal Aid Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Microcarrier Market