
 Cryotubes Market | 2026-2036
Cryotubes Market Size, Share, and Industry Trends Forecast 2026-2036
Cryotubes Market Analysis
Maintenance contracts for ultra-low temperature validation is decoupling hardware sales from recurring revenue streams. Thermo Fisher Scientific leverages its service infrastructure to lock in biobank clients. Corning Incorporated anchors its position through proprietary polypropylene formulations. DWK Life Sciences specializes in diagnostic-grade cryotubes with certified DNase-free ratings.
Cryotubes are cylindrical vessels engineered from polypropylene or borosilicate glass, designed to withstand thermal cycling between ambient and cryogenic temperatures while maintaining sample integrity. Storage cryotubes dominate institutional procurement due to biorepository expansion, while DNA storage applications outpace cell preservation in growth velocity. Polypropylene commands the material segment through cost-efficient injection molding and chemical inertness.
FDA 21 CFR Part 820, ISO 10993 biocompatibility standards, and EMA Annex 1 sterile manufacturing guidelines shape material selection and validation protocols. These frameworks elevate barrier-to-entry for uncertified suppliers while accelerating replacement cycles for legacy inventory. Stakeholders must weigh automation compatibility against material traceability when specifying next-generation cryotube procurement standards.
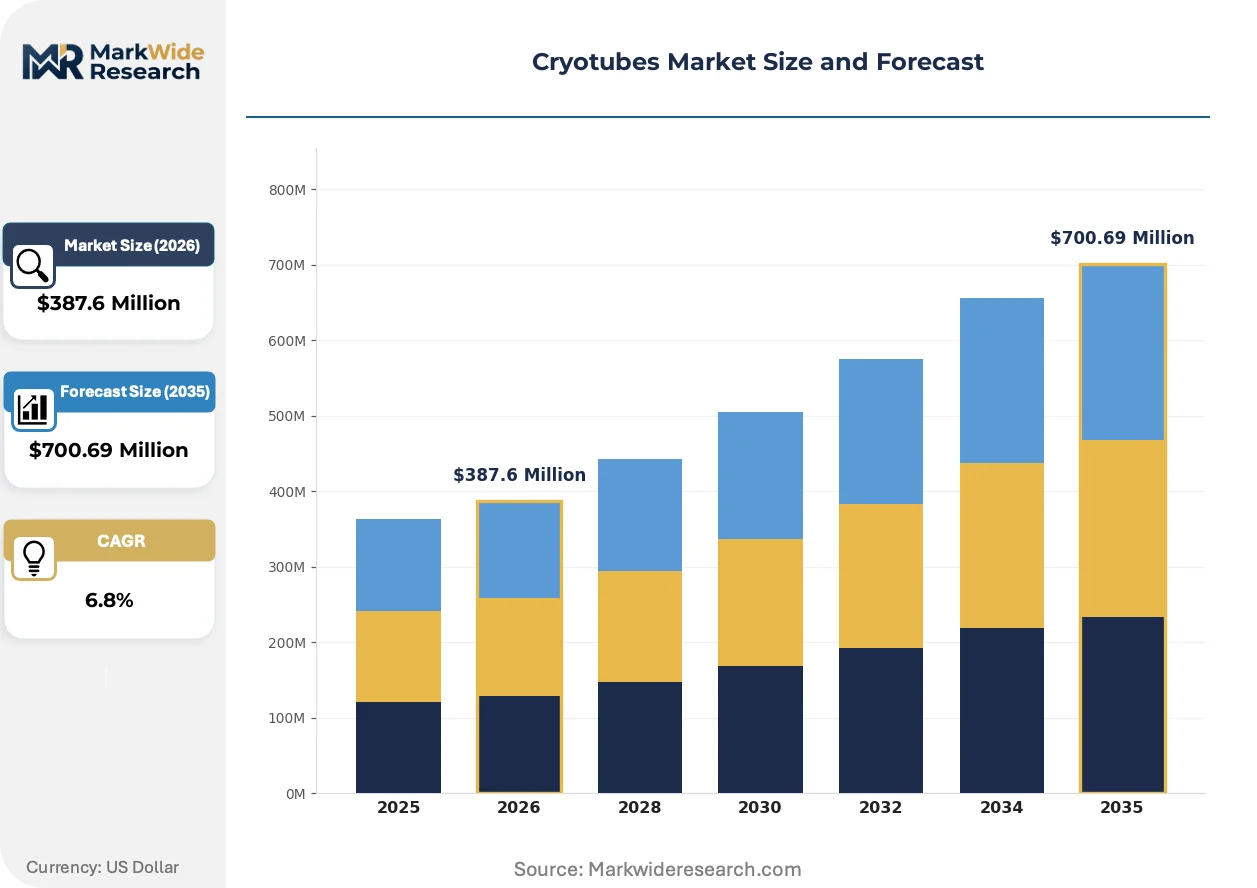
Market Dynamics
The biobank infrastructure buildout is compressing procurement cycles while elevating material traceability requirements, forcing cryotube suppliers to decouple hardware margins from validation service revenues.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:Pharmaceutical manufacturers in Germany and France are accelerating replacement of legacy cryotube inventories to meet tightened contamination control standards, creating sustained upgrade demand.
- Cell therapy manufacturing:Commercial-scale allogeneic cell production facilities require cryotube systems capable of automated handling at cryogenic temperatures, pulling specialized product development.
- China's NMPA biologics registration pathway:Streamlined approval processes for biological products are expanding domestic clinical trial infrastructure, concentrating cryotube procurement in Beijing and Shanghai clusters.
Market Restraints
- Polypropylene resin concentration:Medical-grade polymer supply chains concentrate among Asian petrochemical producers, exposing cryotube manufacturers to input cost volatility and geographic concentration risk.
- FDA 21 CFR Part 820 device master record requirements:Comprehensive documentation burdens extend validation timelines for new cryotube designs, creating regulatory friction for product line extensions.
- Pre-filled cryopreservation media systems:Integrated sample preparation platforms threaten standalone cryotube demand by bundling containment with preservation chemistry.
Strategic Opportunities
- India's CDSCO medical device rule harmonization:Convergence with IMDRF standards is lowering import barriers for certified cryotube suppliers, opening underpenetrated biorepository markets in Hyderabad and Bengaluru.
- DNA data storage:Synthetic biology archives require ultra-stable cryogenic containment for oligonucleotide libraries, emerging as a specialized application segment distinct from biological specimen preservation.
- ISO 20387 biobanking standard adoption:Quality management certification mandates are creating procurement preference shifts toward suppliers offering documented chain-of-custody capabilities.
Industry Challenges
- Automated biorepository integration:Cryotube dimensional tolerances must align with robotic liquid handling systems and barcode scanners, requiring cross-functional coordination between hardware and consumables engineering teams.
- DNase-free certification timelines:Diagnostic-grade validation protocols extend production release cycles, compressing margin recovery windows for specialized product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryotubes Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transport Cryotubes, Storage Cryotubes, Sample Cryotubes, Collection Cryotubes Material: Polypropylene, Glass, Polyethylene, Silicone End User: Hospitals, Research Laboratories, Biobanks, Diagnostic Centers Application: Cell Preservation, DNA Storage, Tissue Banking, IVF |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, DWK Life Sciences, Greiner Bio-One, Sumitomo Bakelite, Azenta Life Sciences, BIOLOGIX Group, Merck KGaA, Globe Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryotubes Market Emerging Trajectories
Modular cryotube architectures are displacing fixed-format designs as biobanks reconfigure storage densities to accommodate heterogeneous sample types. Automation compatibility now precedes material specifications in procurement evaluations.
Two-dimensional barcoded cryotubes are modularizing sample tracking infrastructure by decoupling identification from manual data entry. High-throughput biobanks in the United States and Germany are adopting these formats for automated retrieval systems. The technology is compressing labor costs while enabling real-time inventory reconciliation across distributed repository networks.
REACH Annex XVII restrictions on persistent organic pollutants are reshaping additive formulations in polypropylene cryotube production. European manufacturers are reformulating stabilizer packages to maintain cryogenic performance without restricted substances. Diagnostic OEMs sourcing from EU-based molders are requiring updated material safety data sheets as compliance documentation.
Biobank procurement committees are consolidating vendor relationships to reduce qualification overhead, favoring suppliers offering integrated hardware-service-validation packages. Academic medical centers in the United States are shifting from transactional purchasing to multi-year framework agreements. This concentration is visible most acutely in the National Cancer Institute-designated comprehensive cancer center network.
Cryotubes Market Segmentation
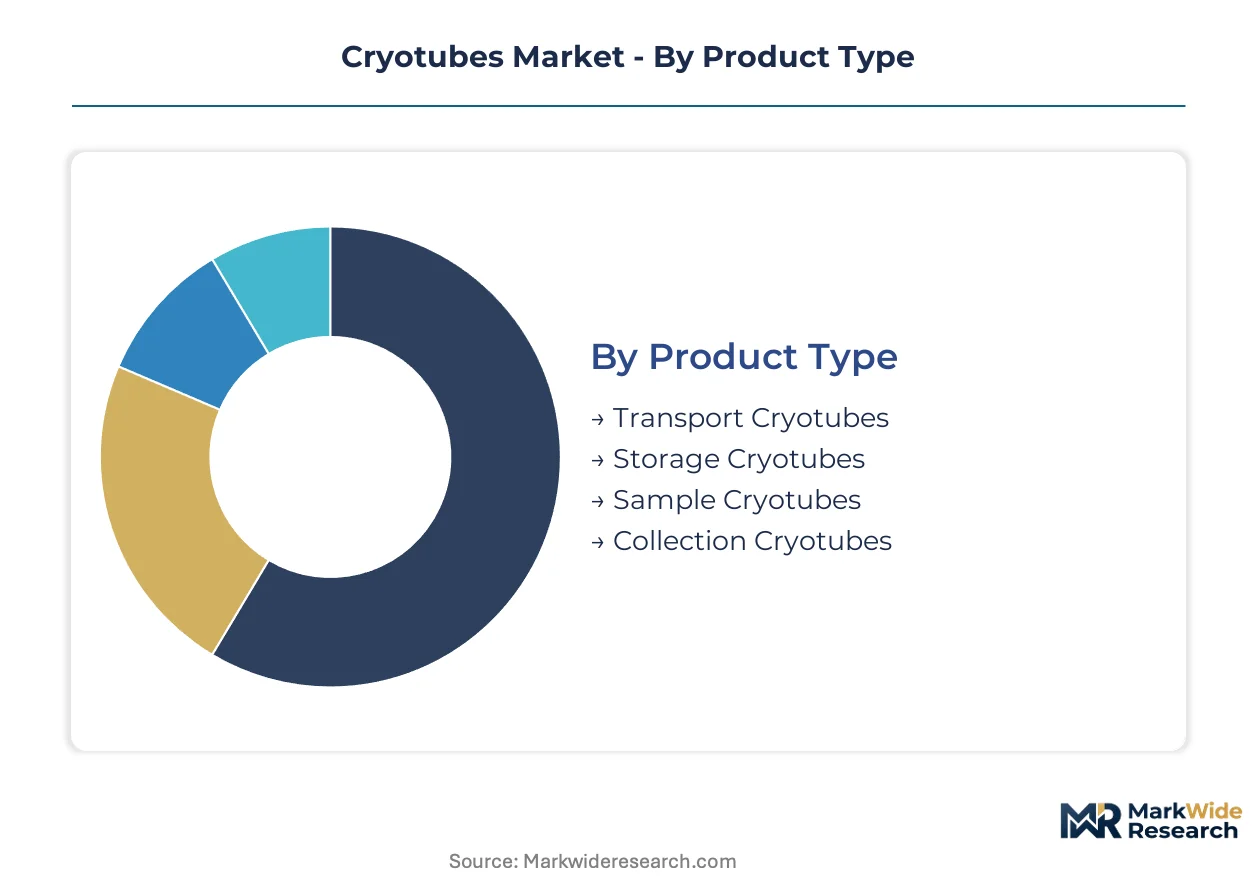
Cryotube procurement varies sharply across use cases, with biobanks prioritizing automation compatibility while diagnostic centers emphasize regulatory certification. Material selection and dimensional tolerances diverge meaningfully between research and clinical applications.
Product Type:
Buyers differentiate primarily by thermal cycling frequency and handling automation requirements.
- Storage Cryotubes:Engineered for static ultra-low temperature containment in biorepository racks, these vessels emphasize dimensional uniformity for robotic retrieval systems. Demand concentrates in the United States among National Cancer Institute-designated comprehensive cancer centers scaling automated inventory management.
- Transport Cryotubes:Designed for active cold-chain logistics with reinforced sealing mechanisms and impact-resistant geometries. Pharmaceutical manufacturers in Germany source these for cell therapy distribution under EMA Annex 1 contamination control mandates.
- Sample Cryotubes:Configured for aliquoting and subdivision workflows in diagnostic laboratories.
- Collection Cryotubes:Optimized for primary specimen acquisition at point-of-care sites.
Volume sits with Storage Cryotubes; growth tilts toward Transport Cryotubes.
Material:
Cost tiers separate medical-grade certified polymers from commodity alternatives.
- Polypropylene:Injection-molded homopolymer dominates through chemical inertness, thermal shock resistance, and cost-efficient high-volume production. Biobanks in China specify medical-grade grades under NMPA biologics registration pathways for domestic clinical trial infrastructure.
- Glass:Borosilicate formulations serve specialized applications requiring absolute gas impermeability and optical clarity for content verification. Research laboratories in Germany retain glass for legacy protocol compatibility and solvent resistance beyond polymer capabilities.
- Polyethylene:Lower-cost alternative for non-critical cold storage with reduced thermal performance envelopes.
- Silicone:Flexible formulations for specialized sealing components and gasket integration.
Polypropylene captures procurement volume; Glass maintains premium positioning for analytical applications.
End User:
Customer maturity and validation burden shape specification complexity.
- Biobanks:Institutional repositories demand ISO 20387-certified quality management systems with documented chain-of-custody capabilities. Facilities in the United States are consolidating vendor relationships into multi-year framework agreements to reduce qualification overhead.
- Hospitals:Clinical procurement prioritizes FDA 21 CFR Part 820 device master record compliance and immediate availability through distribution partnerships.
- Research Laboratories:Academic and government facilities balance performance specifications against grant-funded budget constraints.
- Diagnostic Centers:Commercial testing operations require DNase-free certification and lot-to-lot consistency for regulatory assay validation.
Biobanks drive specification advancement; Diagnostic Centers represent the steepest expansion trajectory for certified consumables.
Application:
Sample stability requirements and preservation duration determine material and design selection.
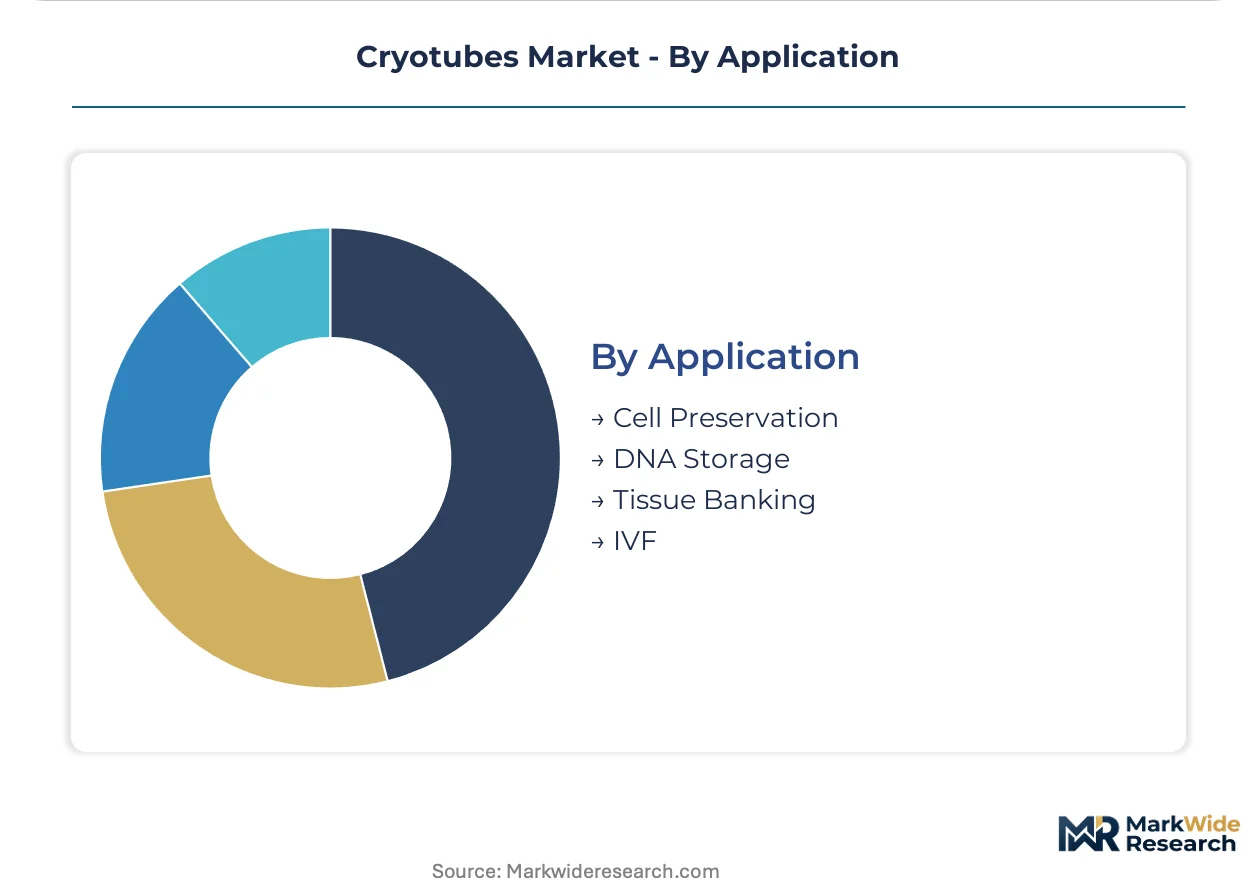
- DNA Storage:Synthetic biology archives and genomic biobanks require ultra-stable containment for oligonucleotide libraries with decades-long integrity horizons. Emerging data storage applications in the United States are pulling specialized product development distinct from biological specimen preservation.
- Cell Preservation:Allogeneic cell therapy manufacturing demands cryotube systems capable of automated handling at cryogenic temperatures with validated thermal profiles. Commercial-scale facilities in Germany and China are specifying formats compatible with robotic liquid handling systems.
- Tissue Banking:Solid specimen containment with larger volume capacities and specialized rack geometries.
- IVF:Reproductive medicine applications emphasizing rapid thaw recovery and minimal thermal mass.
Cell Preservation anchors current procurement volume; DNA Storage is gaining share fastest among emerging application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Asia while consumption concentrates in North American and European biobanking hubs. This geographic split creates distinct procurement patterns across regulatory jurisdictions.
United States
National Cancer Institute-designated comprehensive cancer centers are consolidating vendor relationships into multi-year framework agreements. FDA 21 CFR Part 820 device master record requirements extend validation timelines for new cryotube designs. The Greater Boston biotech corridor drives specification advancement for automated biorepository integration.
Germany
Commercial-scale allogeneic cell production facilities require cryotube systems capable of automated handling at cryogenic temperatures. EMA Annex 1 sterile manufacturing guidelines are accelerating replacement of legacy inventories. The Rhine-Ruhr pharmaceutical manufacturing belt concentrates procurement for contamination-controlled transport applications.
China
Streamlined NMPA biologics registration pathways are expanding domestic clinical trial infrastructure. Beijing and Shanghai clusters concentrate demand for medical-grade polypropylene cryotubes under tightened material traceability mandates. The Yangtze River Delta biopharma corridor is scaling automated biorepository capacity.
India
CDSCO medical device rule harmonization with IMDRF standards is lowering import barriers for certified suppliers. Hyderabad and Bengaluru biorepository markets remain underpenetrated relative to sample volume growth. The country's national pharmaceutical regulator is accelerating quality management certification timelines.
Cryotubes Market Vendor Landscape
Top-tier vendors anchor the premium certification segment, while mid-scale specialists occupy regional niches. The vendor base stratifies across three tiers: integrated life science conglomerates with service infrastructure, material science specialists with proprietary formulations, and regional fabricators competing on cost. Two strategic archetypes dominate: validation-service bundlers and material-grade differentiators. Competitive moves concentrate on multi-year framework agreements and DNase-free certification expansion.
Among integrated life science conglomerates, Thermo Fisher Scientific and Corning Incorporated exemplify the validation-service archetype, leveraging global service infrastructure to lock in institutional procurement committees. DWK Life Sciences occupies a specialist position in diagnostic-grade certification, representing the material-grade differentiation vector for DNase-free rated consumables.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| DWK Life Sciences |
| Greiner Bio-One |
| Sumitomo Bakelite |
| Azenta Life Sciences |
| BIOLOGIX Group |
| Merck KGaA |
| Globe Scientific |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in cryogenic consumables have compressed supplier margins while enforcing pricing discipline through consolidated procurement committees at major biobanks. Their ownership structures favor long-term service contracts over transactional hardware sales, reshaping how manufacturers recover costs across validation and certification investments.
Pricing Analysis
Cost compression in standard-grade polypropylene cryotubes traces to Asian petrochemical oversupply and automated injection-molding scale economies. Three-tier pricing structure across premium, standard, and economy levels separates DNase-free certified diagnostic grades from research-use-only variants. Pricing pressure intensifies in the standard tier as Chinese molders expand medical-grade capacity under NMPA registration pathways. Academic biobanks exhibit highest price sensitivity; commercial cell therapy manufacturers prioritize automation compatibility over unit cost.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific to North American biobanking hubs has elevated regional molding investments near consumption centers. Medical-grade polypropylene supply concentrates in China, South Korea, and Saudi Arabia; borosilicate glass feedstock draws from German and Czech specialty chemical producers. Single-source vulnerability persists in medical-grade resin additives subject to REACH Annex XVII reformulation mandates. Distribution runs through authorized life science distributors with cold-chain validation capabilities rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryotubes market sits in a technology-transition phase as two-dimensional barcoded formats displace legacy single-parameter identification systems, forcing procurement committee requalification cycles.
For Market Incumbents: Extend service infrastructure depth to capture multi-year framework agreements before biobank vendor consolidation hardens. Lock in diagnostic OEMs with certified DNase-free supply agreements to defend against specialty entrants. Vertical integration into medical-grade polypropylene compounding reduces exposure to Asian resin price volatility. For New Entrants and Emerging Players: Mid-tier diagnostic laboratories in India and Southeast Asia represent the most penetrable buyer archetype, as CDSCO harmonization lowers import barriers without entrenched incumbent relationships. Target automated biorepository integrators with dimensional tolerance guarantees that exceed legacy specifications. Lead with ISO 20387 chain-of-custody documentation as a qualification shortcut. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional molders with dormant medical-grade certifications in Germany and the eastern United States, where EMA and FDA validation timelines have stranded smaller competitors. Long-term viability hinges on automation compatibility rather than material cost position. Watch NMPA biologics registration volume as the inflection signal for China demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| DNase-Free Certification Expansion | Diagnostic OEMs in Germany and the United States require validated consumables for regulatory assay submissions. |
| Automated Biorepository Integration | Robotic liquid handling systems at NCI-designated centers demand dimensional tolerances below legacy specifications. |
| Medical-Grade Polypropylene Backward Integration | Captive resin compounding insulates margins from Asian petrochemical price volatility and REACH reformulation cycles. |
| Multi-Year Framework Agreements | Academic medical centers in the United States are consolidating vendor relationships to reduce qualification overhead. |
| Two-Dimensional Barcode Platform Launch | High-throughput biobanks require real-time inventory reconciliation across distributed repository networks. |
Methodological Framework
Regulatory filings, customs trade databases, and ISO certification registries formed the secondary backbone, cross-referenced with primary interviews across biobank operations directors, diagnostic laboratory procurement managers, cryogenic equipment engineers, and pharmaceutical cold-chain logistics specialists. Bottom-up and top-down triangulation validated consumption estimates against production capacity disclosures and import-export flows.
Bottom-up modeling built from product-type, material-grade, end-user, and application segmentations, with automation-readiness scoring as an industry-specific overlay. Top-down constraints applied GDP-healthcare spending elasticities and biologics clinical trial registration trends across the analysis window. CAGRs derived from segment-level growth rate distributions anchored to documented procurement cycle compressions and replacement demand from regulatory guideline updates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA approval pathway volatility, REACH additive restriction expansions, and cell therapy manufacturing scale-out delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Drainage Bottles Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Earwax Removal Aid Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Hemodialysis Consumables Market