
 Medical Equipment Management Software Market | 2026-2036
Medical Equipment Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Equipment Management Software Market Foresight
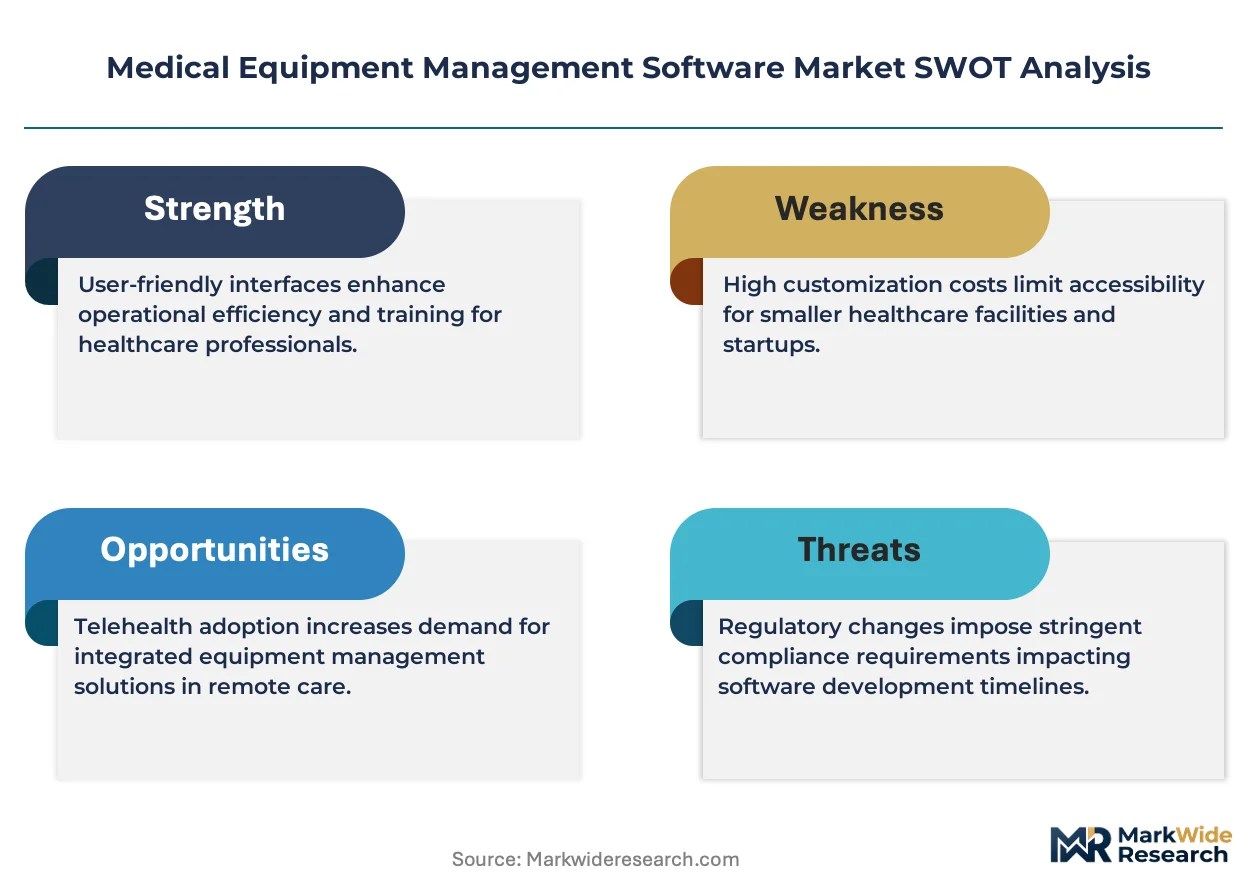
A shortage of biomedical equipment technicians is unwinding maintenance backlogs across health systems. ETQ Reliance leverages cloud-native quality infrastructure to compete for enterprise hospital contracts. MasterControl anchors its position in FDA-regulated device manufacturing workflows. Greenlight Guru specializes in design-history-file traceability for emerging medtech startups.
Medical equipment management software orchestrates the procurement, calibration, preventive maintenance, and regulatory documentation of clinical and diagnostic devices through centralized digital platforms. Systems typically integrate work-order automation, parts inventory databases, and audit-trail logging to ensure Joint Commission readiness and minimize unplanned downtime. Cloud-based deployment is capturing the fastest expansion as health systems retire legacy client-server installations. AI Analytics is reshaping how predictive failure models prioritize technician dispatch schedules. Maintenance Management retains the deepest margin pools due to recurring service-contract attach rates.
FDA 21 CFR Part 820, EU MDR, and ISO 13485 collectively mandate device-history records and corrective-action traceability that software platforms must encode. The EU AI Act adds algorithmic transparency requirements for predictive maintenance modules deployed in European facilities. Stakeholders should monitor how interoperability standards between equipment management and electronic health record systems evolve before committing to platform architectures.
Market Dynamics
Predictive maintenance algorithms are restructuring how hospital networks allocate technician labor and capital budgets, compressing traditional reactive service models into condition-based intervention cycles.
Growth Catalysts
- FDA 21 CFR Part 820:Quality system documentation mandates force device manufacturers to adopt automated audit-trail platforms for corrective-action traceability.
- Cloud-native architectures:Health systems in the United States are retiring client-server installations to enable real-time equipment telemetry across distributed facilities.
- Aging device fleets:Diagnostic imaging systems installed during the 2000s expansion wave now require lifecycle oversight modules to manage obsolescence risk.
Market Restraints
- Biomedical technician shortage:Workforce gaps in the United States and Germany extend maintenance backlogs and delay platform deployment timelines.
- Legacy system integration costs:Proprietary protocols from Siemens, GE, and Philips equipment require expensive middleware development for unified dashboards.
- Cybersecurity compliance burden:HIPAA technical safeguards and EU GDPR data localization rules add implementation complexity for cloud-hosted platforms.
Strategic Opportunities
- EU AI Act transparency requirements:Predictive maintenance modules deployed in European facilities must encode explainable failure models, creating first-mover advantage for compliant vendors.
- Interoperability standards evolution:HL7 FHIR integration with electronic health record systems opens new data monetization channels for equipment utilization analytics.
- Japan's METI digital health infrastructure:Hospital digitization subsidies accelerate adoption of centralized device management in Tokyo and Osaka metropolitan clusters.
Industry Challenges
- ISO 13485 certification timelines:Software-as-a-service vendors face extended quality management system audits to serve FDA-regulated device manufacturers.
- Skill convergence requirements:Field engineering teams must now combine mechanical repair expertise with data science literacy for algorithm-assisted diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Equipment Management Software Market |
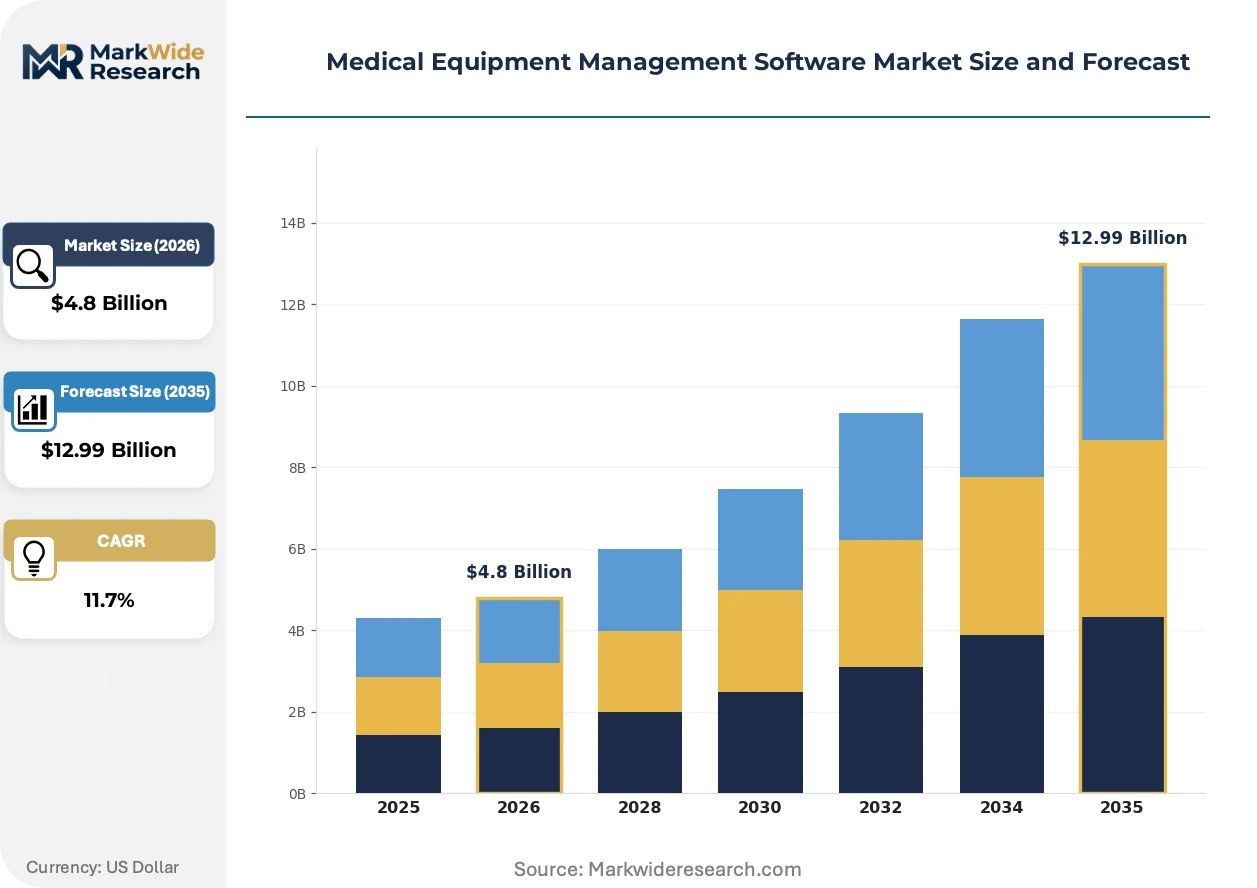
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asset Tracking, Maintenance Management, Inventory Control, Compliance Management End User: Hospitals, Clinics, Diagnostic Labs, Rehabilitation Centers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Application Technology: IoT Integration, AI Analytics, Data Visualization, Barcode Scanning |
| Companies Covered | ETQ Reliance, Cognidox, QT9 QMS, Coast, Qualio, Greenlight Guru, ComplianceQuest, eMaint, MasterControl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Equipment Management Software Market Shifts & Advancements
Artificial intelligence inference at the network edge is redefining maintenance dispatch protocols, shifting decision latency from hours to minutes and collapsing traditional tiered escalation workflows.
Edge-deployed machine learning models are supplanting cloud-centralized predictive analytics in critical care settings. Hospital networks in Germany and Japan prioritize sub-50-millisecond failure alerts for ventilator and anesthesia systems. This architecture compresses vendor cloud revenue per endpoint while expanding hardware-attach margins.
EU MDR device tracking mandates now require unique device identification linkage across the full lifecycle. Manufacturers serving European markets must encode software version traceability into design-history files. Sterile processing and surgical equipment categories face the steepest compliance recertification burdens.
Consolidated procurement by multi-hospital networks is compressing vendor sales cycles and standardizing platform requirements. United States-based integrated delivery networks now mandate API-first architectures for all new equipment management contracts. This behavior concentrates purchasing power among ten to fifteen national systems while marginalizing point-solution vendors.
Medical Equipment Management Software Market Segmentation
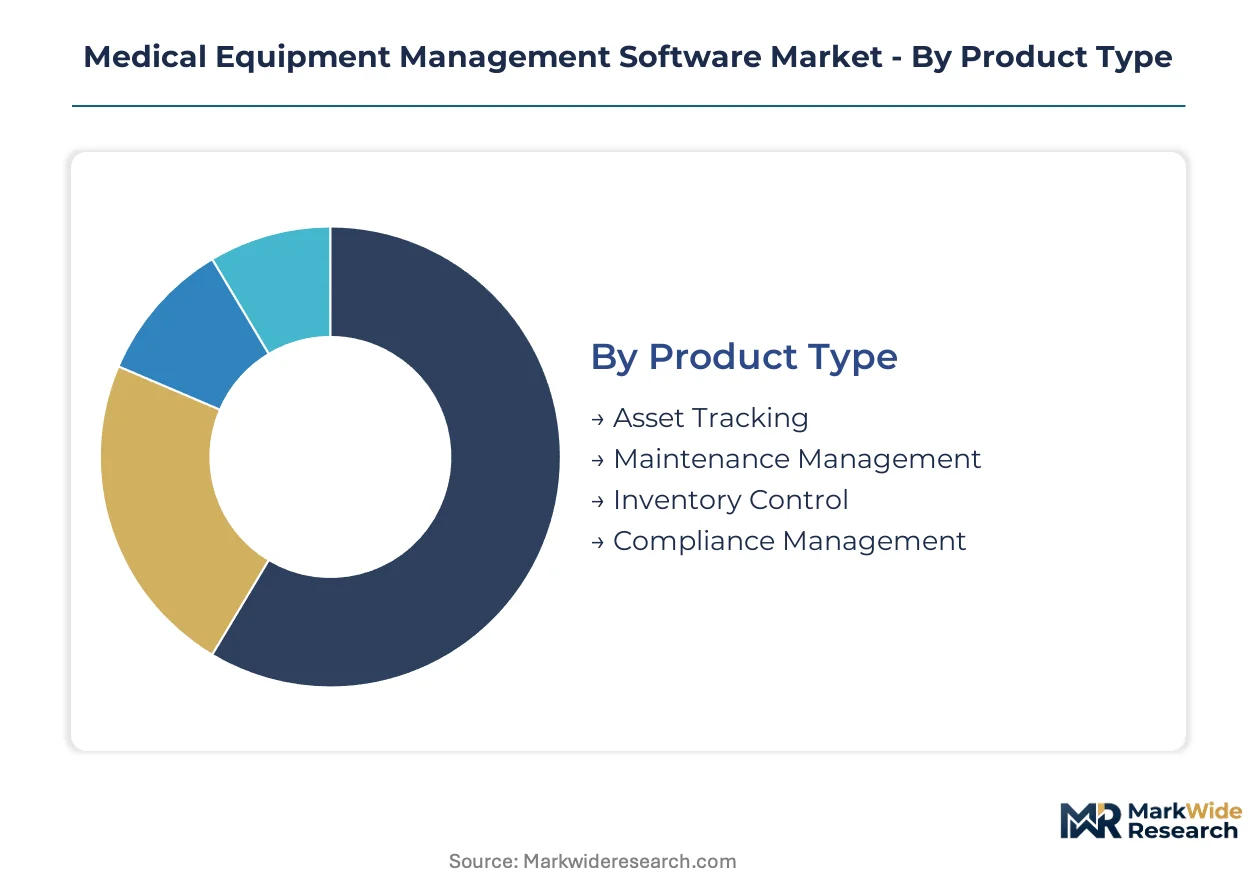
Segmentation in medical equipment management software reveals how regulatory complexity, infrastructure maturity, and clinical risk tolerance shape purchasing decisions across health systems. Vendors must align product architectures with distinct compliance burdens and capital deployment patterns.
Product Type:
FDA 21 CFR Part 820 and EU MDR impose divergent documentation requirements that favor certain modules over others in regulated manufacturing versus hospital operations.
- Maintenance Management:Work-order automation, preventive scheduling, and technician dispatch systems form the operational core for hospital biomedical departments. United States health systems prioritize this module to address workforce shortages and Joint Commission readiness. Recurring service-contract attach rates sustain the deepest margin pools across deployment models.
- Compliance Management:Audit-trail logging, corrective-action traceability, and design-history-file repositories encode FDA, EU MDR, and ISO 13485 mandates. Device manufacturers in Germany and Japan deploy this module to manage UDI linkage across sterile processing and surgical equipment lifecycles. Regulatory recertification burdens accelerate replacement cycles for legacy paper-based systems.
- Asset Tracking:Real-time location systems and utilization analytics monitor device movement across distributed facilities.
- Inventory Control:Parts databases and procurement workflows integrate with ERP systems to minimize stockouts during critical repairs.
Maintenance Management handles the majority of throughput; Compliance Management is gaining share fastest as EU MDR enforcement tightens.
End User:
Capital availability and clinical complexity determine software sophistication requirements across care settings.
- Hospitals:Multi-facility networks require centralized platforms integrating predictive analytics, work-order automation, and regulatory documentation across thousands of devices. United States integrated delivery networks now mandate API-first architectures for all new contracts, concentrating purchasing power among national systems. Cloud-native deployments dominate new installations.
- Diagnostic Labs:High-throughput imaging and laboratory equipment demand calibration traceability and uptime guarantees. Facilities in Japan's Tokyo and Osaka metropolitan clusters leverage METI digitization subsidies to accelerate centralized device management adoption. AI-assisted failure prediction prioritizes dispatch for revenue-critical analyzers.
- Clinics:Smaller device fleets and limited IT staff favor simplified, mobile-first solutions with lower implementation overhead.
- Rehabilitation Centers:Durable medical equipment tracking and patient-assignment workflows dominate functional requirements.
Hospitals command the largest contract values; Diagnostic Labs are expanding most quickly as outpatient imaging volumes rise.
Deployment:
Data sovereignty rules and cybersecurity postures create geographic variation in architecture preferences.
- Cloud-Based:Real-time telemetry across distributed facilities enables predictive maintenance algorithms and reduces on-site IT burden. United States health systems retiring client-server installations drive fastest expansion, though EU GDPR localization requirements add implementation complexity for vendors serving European facilities.
- Hybrid:Critical care systems maintain on-premise processing for sub-50-millisecond alerts while non-urgent analytics flow to cloud infrastructure. German and Japanese hospital networks prioritize this architecture for ventilator and anesthesia system monitoring.
- On-Premise:Air-gapped installations persist in defense and certain research hospital environments with strict data control requirements.
- Mobile Application:Field technician apps extend platform reach beyond fixed workstations for bedside device servicing.
Cloud-Based deployments capture the steepest expansion trajectory; Hybrid architectures are climbing fastest in critical care settings.
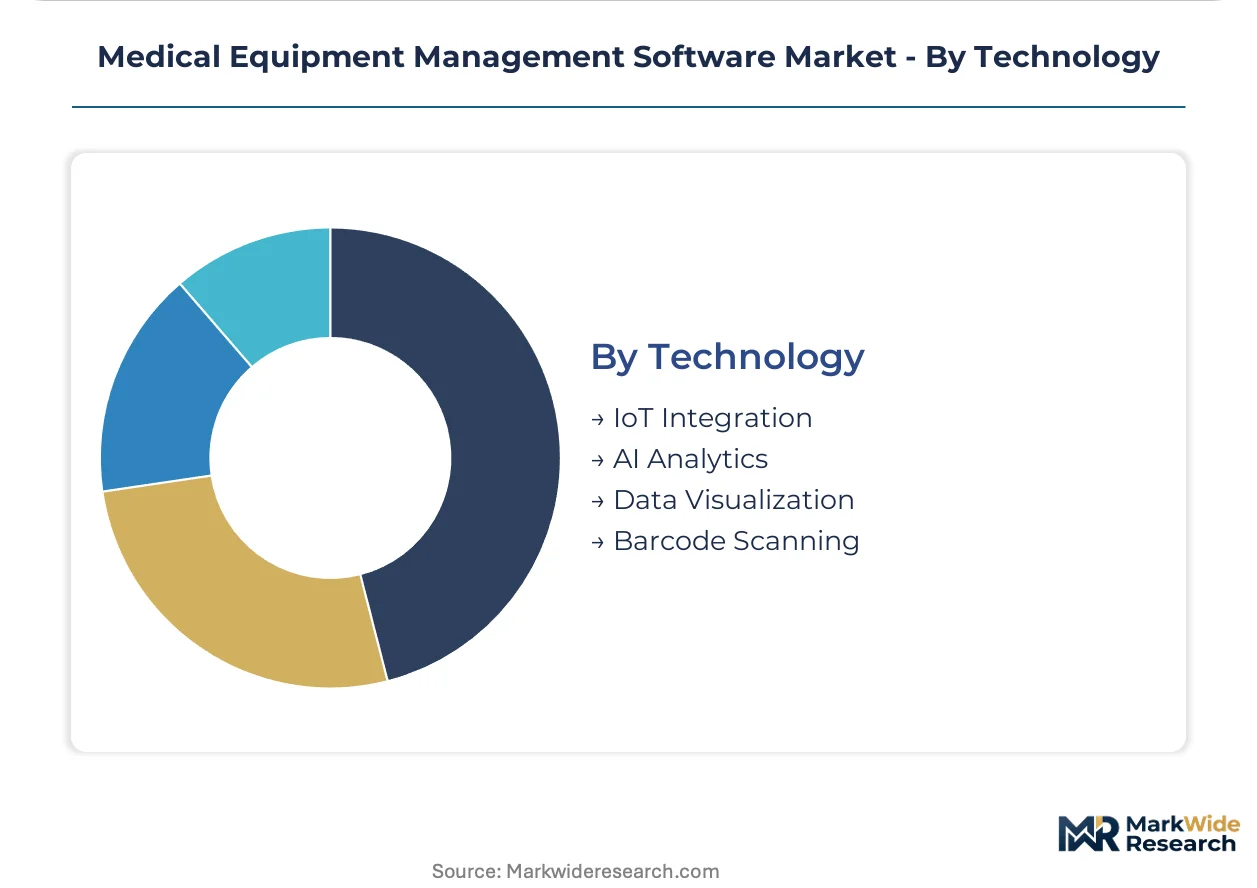
Technology:
Edge computing maturation and algorithmic transparency mandates are restructuring R&D investment priorities.
- AI Analytics:Predictive failure models prioritize technician dispatch schedules and compress traditional reactive service into condition-based intervention cycles. EU AI Act explainability requirements for European deployments create first-mover advantage for vendors encoding transparent decision logic. Edge inference at the network edge reduces latency from hours to minutes.
- IoT Integration:Sensor telemetry from Siemens, GE, and Philips equipment feeds unified dashboards through expensive middleware development. Proprietary protocol translation remains a persistent integration cost burden for health systems.
- Data Visualization:Utilization heat maps and downtime analytics support capital planning conversations with hospital executives.
- Barcode Scanning:UDI compliance and physical asset verification rely on mature, low-cost identification infrastructure.
AI Analytics commands premium pricing; IoT Integration is expanding most quickly as device OEMs open telemetry interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 820 quality system regulations anchor the United States as the dominant geography for medical equipment management software adoption. Hospital networks across the country are retiring legacy client-server installations to enable predictive maintenance algorithms and real-time equipment telemetry.
United States
Integrated delivery networks now mandate API-first architectures for all new equipment management contracts, concentrating purchasing power among ten to fifteen national systems. HIPAA technical safeguards and FDA quality system documentation requirements shape platform implementation timelines. The Greater Boston and Pacific Northwest metropolitan clusters drive early adoption of cloud-native deployments for aging diagnostic imaging fleets.
Germany
EU MDR device tracking mandates and the EU AI Act algorithmic transparency requirements are accelerating replacement cycles for legacy paper-based compliance systems. German hospital networks prioritize hybrid architectures delivering sub-50-millisecond failure alerts for critical care equipment. The Munich and Hamburg metropolitan areas anchor adoption of predictive maintenance modules for ventilator and anesthesia system monitoring.
Japan
METI digital health infrastructure subsidies are accelerating centralized device management adoption in Tokyo and Osaka metropolitan clusters. PMDA quality system regulations and aging device fleets installed during the 2000s diagnostic imaging expansion wave drive lifecycle oversight module procurement. The Kansai region leads deployment of AI-assisted failure prediction for high-throughput laboratory analyzers.
United Kingdom
NHS procurement consolidation and MHRA post-Brexit regulatory alignment efforts are reshaping vendor selection criteria for hospital network contracts. GDPR data localization rules and cybersecurity compliance burdens add implementation complexity for cloud-hosted platform deployments. The London-Southeast corridor dominates contract values for multi-facility equipment management integrations.
India
CDSCO medical device rules and hospital digitization initiatives in Maharashtra and Karnataka are expanding addressable market opportunity for simplified, mobile-first solutions. The country's national pharmaceutical regulator is tightening traceability requirements for imported diagnostic equipment. The Delhi-NCR and Hyderabad technology corridors concentrate emerging health system deployments of cloud-based asset tracking platforms.
Medical Equipment Management Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the medical equipment management software market. Enterprise hospital contracts concentrate among cloud-native quality infrastructure vendors while specialized compliance modules serve emerging medtech startups. Three strategic archetypes dominate: FDA-regulated workflow specialists, predictive maintenance algorithm developers, and design-history-file traceability providers. Competitive intensity manifests through strategic partnerships for interoperability standards development and portfolio diversification into adjacent regulatory documentation segments.
Within the quality management tier, ETQ Reliance and MasterControl occupy positions reflecting divergent infrastructure philosophies. ETQ Reliance exemplifies cloud-native architectural approaches competing for enterprise hospital contracts, while MasterControl anchors FDA-regulated device manufacturing workflow segments. Greenlight Guru sits within the emerging medtech specialist archetype, representing design-history-file traceability positioning for startup customer segments.
| Leading Market Players |
|---|
| ETQ Reliance |
| Cognidox |
| QT9 QMS |
| Coast |
| Qualio |
| Greenlight Guru |
| ComplianceQuest |
| eMaint |
| MasterControl |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 820 quality system documentation mandates gate both vendor qualification and subscription tier differentiation in the medical equipment management software market, compressing price spreads between compliant and non-compliant platforms while elevating certification premiums for EU MDR and ISO 13485 audited systems.
Pricing Analysis
United States health systems pay subscription premiums averaging forty percent above German hospital networks for equivalent predictive maintenance modules, reflecting HIPAA technical safeguard implementation costs and domestic cloud infrastructure pricing. Three-tier pricing structure across premium, standard, and economy levels separates enterprise API-first deployments from mid-market SaaS bundles and basic work-order automation tools. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting legacy client-server migration pricing. Diagnostic labs exhibit the lowest price sensitivity due to revenue-critical uptime guarantees, while small rehabilitation centers face acute budget constraints.
Supply Chain Analysis
The United States and Germany anchor cloud infrastructure provisioning for hospital network deployments, with Ireland and Singapore serving as GDPR-compliant data localization nodes for European and Asia-Pacific facilities. Platform development draws from specialized labor pools in machine learning engineering, biomedical device expertise, and regulatory affairs consulting. Single-source vulnerability concentrates in middleware development for Siemens, GE, and Philips proprietary protocol translation. Distribution runs through direct enterprise sales teams for hospital network contracts and channel partnerships for emerging medtech startup segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical equipment management software represents a service-attach opportunity where predictive maintenance algorithm subscriptions are expanding faster than base platform licensing, rewarding vendors who embed recurring analytics layers into initial hardware procurement cycles.
For Market Incumbents: Fortify API-first architecture investments against emerging cloud-native quality infrastructure competitors by deepening ISO 13485 certification coverage for sterile processing equipment modules. Acquire specialized design-history-file traceability capabilities to defend margin position in the EU MDR compliance segment against startup entrants. For New Entrants and Emerging Players: Lead with explainable AI maintenance modules targeting Japan's METI-subsidized hospital digitization programs, where algorithmic transparency requirements create first-mover advantage before incumbent adaptation. Pursue mobile-first asset tracking for India's CDSCO-regulated diagnostic equipment imports, leveraging simplified deployment overhead against enterprise platform complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native quality infrastructure segments as containerized deployment reduces per-customer infrastructure provisioning costs. Target acquisition profiles should emphasize vendors with embedded predictive maintenance algorithm revenue exceeding thirty percent of total contract value. The signal to watch is EU AI Act enforcement timelines accelerating replacement cycles for non-explainable legacy systems.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Explainable algorithm documentation opens German and French hospital procurement channels ahead of enforcement deadlines. |
| HL7 FHIR Integration Partnership | Electronic health record interoperability enables equipment utilization data monetization through analytics licensing. |
| Edge Inference Hardware Co-Development | Sub-50-millisecond alert capabilities capture critical care premium pricing in Tokyo and Munich metropolitan clusters. |
| Biomedical Technician Training Program | Workforce development partnerships with United States community colleges accelerate platform deployment timelines. |
| Middleware Protocol Acquisition | Siemens, GE, and Philips telemetry translation capabilities reduce customer integration friction and implementation costs. |
Research Methodology
The analysis maps maintenance management, compliance management, asset tracking, and inventory control modules, each validated through biomedical engineering directors, hospital procurement committee members, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Primary interview findings were cross-referenced against FDA 510(k) filings, EU MDR notified body audit records, hospital procurement database extracts, and CMS Medicare equipment reimbursement schedules. Bottom-up deployment estimates across health system facilities were triangulated with top-down software vendor revenue segmentation.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler healthcare vertical revenue disclosures and medical device OEM service contract growth rates. The analytical framework modeled deployment architecture, end-user facility type, regulatory compliance tier, and integration complexity across the projection horizon. CAGRs were derived from equipment fleet aging curves, regulatory enforcement phase-in schedules, and cloud migration adoption patterns. Forecast inputs incorporated biomedical technician workforce gap projections and METI digitization subsidy allocation trajectories.
The analysis sits within stated boundaries; outcomes outside FDA 21 CFR Part 820 enforcement continuity, EU MDR implementation timelines, or sustained cloud infrastructure cost curves would require recalibration. Forecasts reflect assumptions about regulatory stability, interoperability standard adoption, and health system capital availability. Recalibration cycles align with material shifts in FDA inspection frequency, EU AI Act guidance publication, or Japan METI subsidy renewal schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Medical Automation Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Medical Cart Battery Market