
 Anti-Adhesion Barrier Gels Market | 2026-2036
Anti-Adhesion Barrier Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Adhesion Barrier Gels Market Outlook
Market Context with Strategic Players
The FDA's 510(k) premarket notification framework for absorbable surgical barriers is realigning the cost-of-entry calculus for new entrants. Johnson & Johnson leverages its broad surgical portfolio to sustain dominance across hospital procurement networks. Baxter International anchors its position through integrated distribution into ambulatory surgical centers. Hangzhou Singclean Medical Products competes on manufacturing scale for hyaluronic acid derivatives serving cost-sensitive markets.
Technical Definition and Structural Segments
Anti-adhesion barrier gels are viscous, bioresorbable formulations—typically hyaluronic acid, carboxymethylcellulose, or polyethylene glycol-based—applied intraoperatively to separate tissue planes during wound healing and prevent fibrous scar formation. These gels function by creating a mechanical barrier that persists through the critical seven-to-fourteen-day peritoneal healing window before enzymatic degradation. Gel formulations command the largest share among product types due to surgeon familiarity and ease of laparoscopic application, while spray delivery modes are gaining traction in minimally invasive procedures where precise anatomical coating proves challenging with viscous materials. General surgery applications represent the most mature segment with established reimbursement pathways, whereas orthopedic surgery is emerging as a faster-growing area driven by joint revision procedures where adhesion-related complications carry substantial cost burdens.
Regulatory Frame and Forward-Looking Close
The FDA's Quality System Regulation, the EU Medical Device Regulation (MDR), and ISO 10993 biocompatibility standards collectively shape product development timelines, clinical evidence requirements, and market access pathways for barrier gel manufacturers. The MDR's heightened scrutiny of absorbable implantables has extended conformity assessment durations for European market entry, while FDA post-market surveillance mandates are intensifying adverse event reporting obligations. Stakeholders must monitor evolving reimbursement decisions for adhesion prevention in outpatient settings, as ambulatory surgical center expansion hinges on clear procedural coding and payer coverage determinations.
Market Dynamics
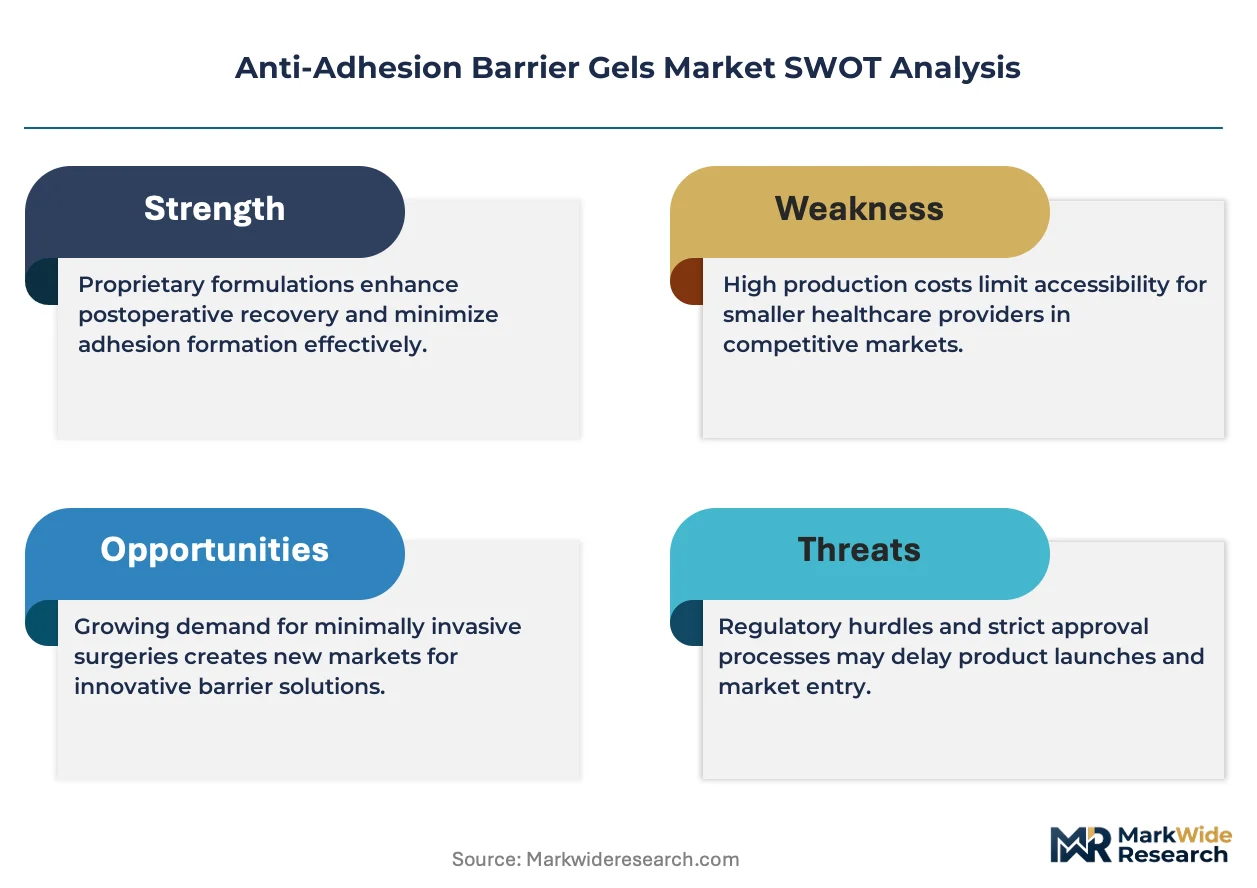
The FDA's updated biocompatibility testing mandates for absorbable surgical materials are compressing development timelines and elevating capital requirements for new barrier gel entrants. Manufacturers must now demonstrate enzymatic degradation profiles and tissue response data before 510(k) clearance, favoring incumbents with established clinical dossiers.
Growth Catalysts
- Hyaluronic acid derivative innovation:Advanced cross-linking chemistries extend barrier residence time through the critical peritoneal healing window. Academic medical centers in Germany and Japan are validating these formulations in multi-center efficacy trials.
- ASC volume expansion:Ambulatory surgical centers in the United States are formalizing adhesion prevention protocols for laparoscopic hernia and gynecologic procedures. Medicare reimbursement clarity for outpatient barrier application is accelerating protocol adoption.
- EU MDR transition completion:The Medical Device Regulation's full implementation has cleared backlog uncertainty, enabling notified bodies to process conformity assessments for absorbable barriers. Manufacturers with MDR certificates are securing hospital tenders across France, Italy, and Spain.
Market Restraints
- Raw material concentration:Pharmaceutical-grade hyaluronic acid supply concentrates among three fermentation specialists in China. Quality variability and export licensing delays create formulation batch inconsistencies for Western manufacturers.
- Reimbursement fragmentation:CMS, private payers, and hospital systems maintain divergent coding for adhesion prevention in orthopedic revision surgery. This administrative friction delays commercial traction in the fastest-growing application segment.
- Mechanical substitute persistence:Sheet-based barriers (oxidized regenerated cellulose, expanded polytetrafluoroethylene) retain preference in open abdominal procedures. Surgeons cite tactile feedback and staple fixation as decisive advantages over gel flow characteristics.
Strategic Opportunities
- Orthopedic adhesion prevention:Knee and shoulder revision procedures in the United States carry substantial complication costs from arthrofibrosis. Gel barriers targeting tenolysis and capsular release applications represent underdeveloped white space.
- Robotic surgery integration:Precision spray applicators compatible with da Vinci and Versius platforms enable consistent anatomical coating in confined pelvic spaces. Device-agnostic gel delivery systems are capturing procurement attention from integrated health networks.
- India's surgical infrastructure buildout:The country's PLI scheme for medical devices is attracting contract manufacturing investment. Cost-optimized hyaluronic acid formulations can penetrate tier-2 and tier-3 hospital markets where adhesion prevention remains nascent.
Industry Challenges
- ISO 10993-6 implantation study execution:Histopathological evaluation of tissue reaction requires specialized contract research organizations with absorbable polymer expertise. Qualified laboratory capacity constraints extend preclinical timelines by 8-14 months.
- Laparoscopic application training:Gel viscosity and flow rate optimization demands hands-on surgical education. Device companies must deploy clinical specialists to convert open-procedure surgeons to minimally invasive barrier techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Adhesion Barrier Gels Market |
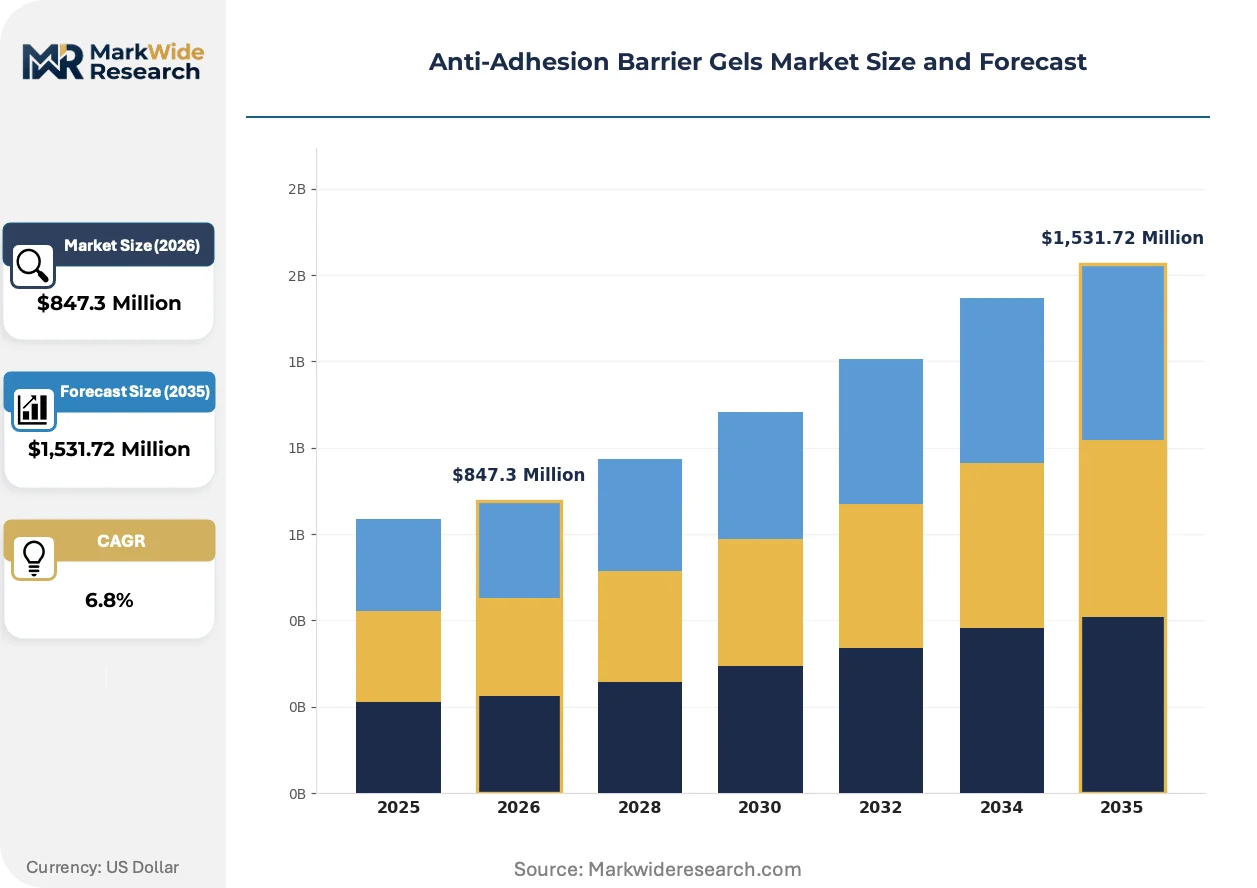
| Market Size in 2026 | $847.3 Million |
| Market Size in 2035 | $1,531.72 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Film, Spray, Solution Application: General Surgery, Gynecological Surgery, Orthopedic Surgery, Urological Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Surgical Centers Delivery Mode: Injectable, Topical, Intraperitoneal, Intravenous |
| Companies Covered | Anika Therapeutics, Hangzhou Singclean Medical Products, Johnson & Johnson, Sanofi, PlantTec Medical GmbH, Baxter International, FzioMed, LG Chem Life Sciences, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Adhesion Barrier Gels Market Strategic Shifts
Barrier gel formulation science is converging with precision delivery engineering to address anatomical coating challenges in confined surgical spaces. These developments are compressing the gap between mechanical and flowable barrier performance while reshaping procurement criteria.
Multifunctional gel platforms is unifying adhesion prevention with localized drug delivery capabilities. Antibiotic-loaded and hemostatic-modified hyaluronic acid matrices are advancing through clinical validation. Orthopedic and cardiovascular surgeons are piloting these formulations in procedures where infection prophylaxis and bleeding control compound adhesion risk. The technology is unifying previously separate product categories into single-application platforms, forcing manufacturers to restructure R&D portfolios around combination device pathways.
REACH authorization requirements for polymer raw materials are elevating supply chain documentation burdens for European market access. Manufacturers must now submit full substance dossiers for hyaluronic acid fermentation byproducts and cross-linking agent residuals. Small and mid-cap gel producers without dedicated regulatory affairs functions are outsourcing compliance to specialized consultancies, while larger competitors are absorbing these costs through captive regulatory infrastructure.
Hospital value analysis committees are consolidating vendor relationships for surgical supplies across adhesion prevention categories. Integrated delivery networks in Texas, Florida, and Ohio are awarding sole-source contracts covering gel barriers, mechanical sheets, and spray applicators. This concentration is displacing fragmented purchasing by individual surgeons or service lines, compressing the addressable supplier base and elevating scale requirements for market participation.
Anti-Adhesion Barrier Gels Market Segmentation
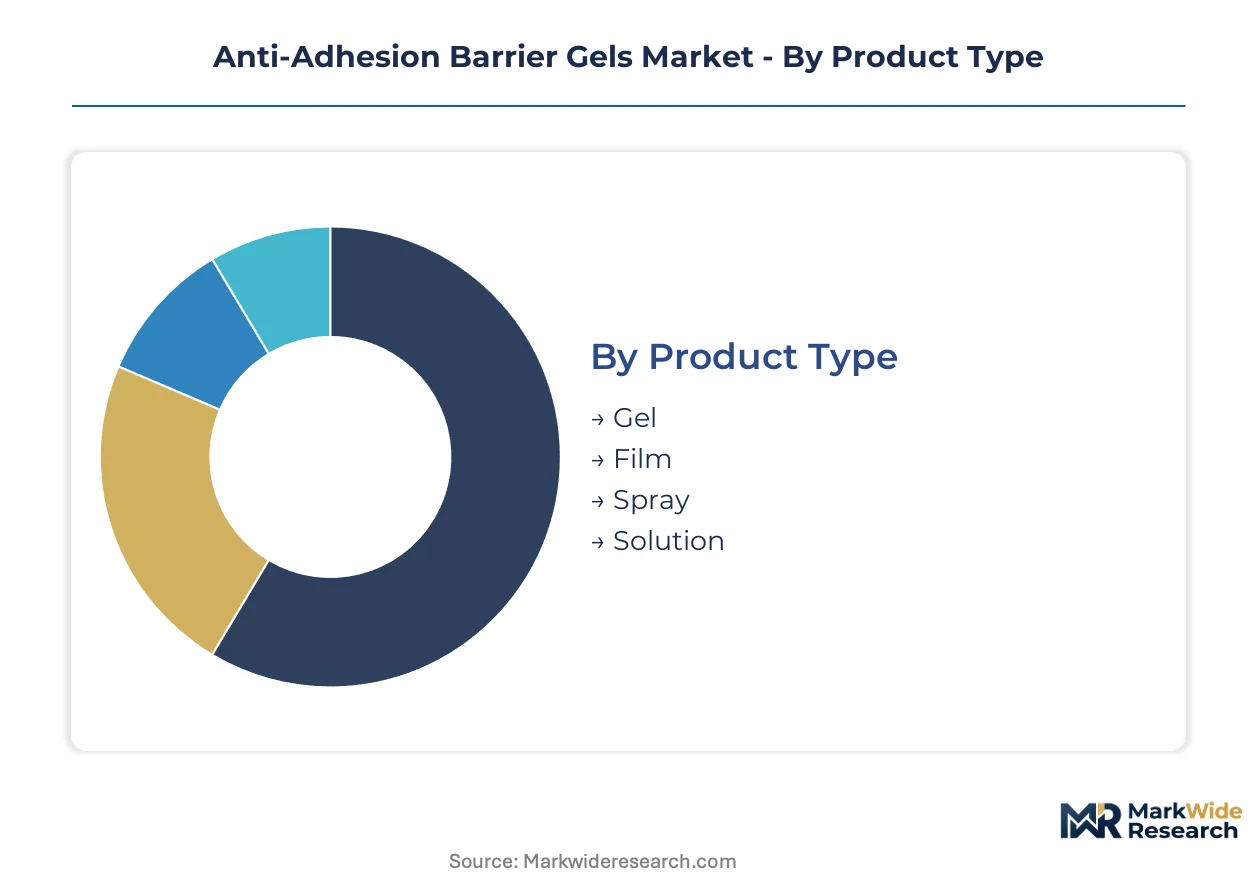
Product configuration in the Anti-Adhesion Barrier Gels Market determines surgical workflow integration and reimbursement positioning. Formulation viscosity, application method, and institutional procurement protocols create distinct competitive arenas across each segmentation dimension.
Product Type:
Upgrade cycles from sheet-based barriers to flowable formulations are shortening as laparoscopic adoption accelerates in tertiary hospitals.
- Gel:Viscous hyaluronic acid or carboxymethylcellulose formulations create mechanical separation through the critical seven-to-fourteen-day healing window. Demand concentrates in United States ambulatory surgical centers where Medicare reimbursement clarity for outpatient gel application is accelerating protocol adoption.
- Spray:Atomized delivery systems enable anatomical coating in confined pelvic spaces during robotic-assisted procedures. German and Japanese academic medical centers are validating advanced cross-linking chemistries that extend barrier residence time in multi-center efficacy trials.
- Film:Sheet-based oxidized regenerated cellulose barriers retain preference in open abdominal procedures where tactile feedback and staple fixation matter.
- Solution:Low-viscosity liquid formulations suit irrigation-based application during arthroscopic joint procedures.
Volume placements concentrate in gel formulations; the faster expansion belongs to spray delivery systems.
Application:
Procedure reimbursement tiers and complication cost burdens create divergent margin profiles across surgical specialties.
- General Surgery:Laparoscopic hernia and colorectal procedures represent the most mature segment with established hospital procurement pathways and surgeon familiarity with gel application techniques.
- Orthopedic Surgery:Knee and shoulder revision procedures carry substantial cost burdens from arthrofibrosis, driving hospital value analysis committee interest in adhesion prevention protocols. United States joint revision volumes are climbing fastest where gel barriers targeting tenolysis and capsular release applications remain underdeveloped.
- Gynecological Surgery:Pelvic adhesive disease prevention in laparoscopic hysterectomy and endometriosis excision commands consistent hospital formulary placement.
- Urological Surgery:Prostatectomy and pyeloplasty applications require precision coating around delicate neurovascular structures.
General surgery maintains the largest installed base; orthopedic surgery is gaining share fastest on revision procedure growth.
End User:
Capital intensity and case volume thresholds determine which institutional categories can sustain dedicated adhesion prevention protocols.
- Hospitals:Tertiary academic medical centers with integrated surgical departments anchor procurement through multi-year vendor contracts covering barrier gels, mechanical sheets, and spray applicators.
- Ambulatory Surgical Centers:United States outpatient facilities are formalizing adhesion prevention protocols as Medicare reimbursement clarity accelerates adoption for laparoscopic hernia and gynecologic procedures.
- Clinics:Office-based surgical suites with limited procedure volumes rely on distributor-mediated purchasing rather than direct manufacturer relationships.
- Specialty Surgical Centers:Orthopedic-focused facilities in Texas, Florida, and Ohio are consolidating vendor relationships across adhesion prevention categories.
Hospital systems dominate current purchasing volume; ambulatory surgical centers are climbing the fastest on outpatient migration.
Delivery Mode:
Application technique compatibility with minimally invasive platforms is reshaping device-agnostic gel delivery system procurement.
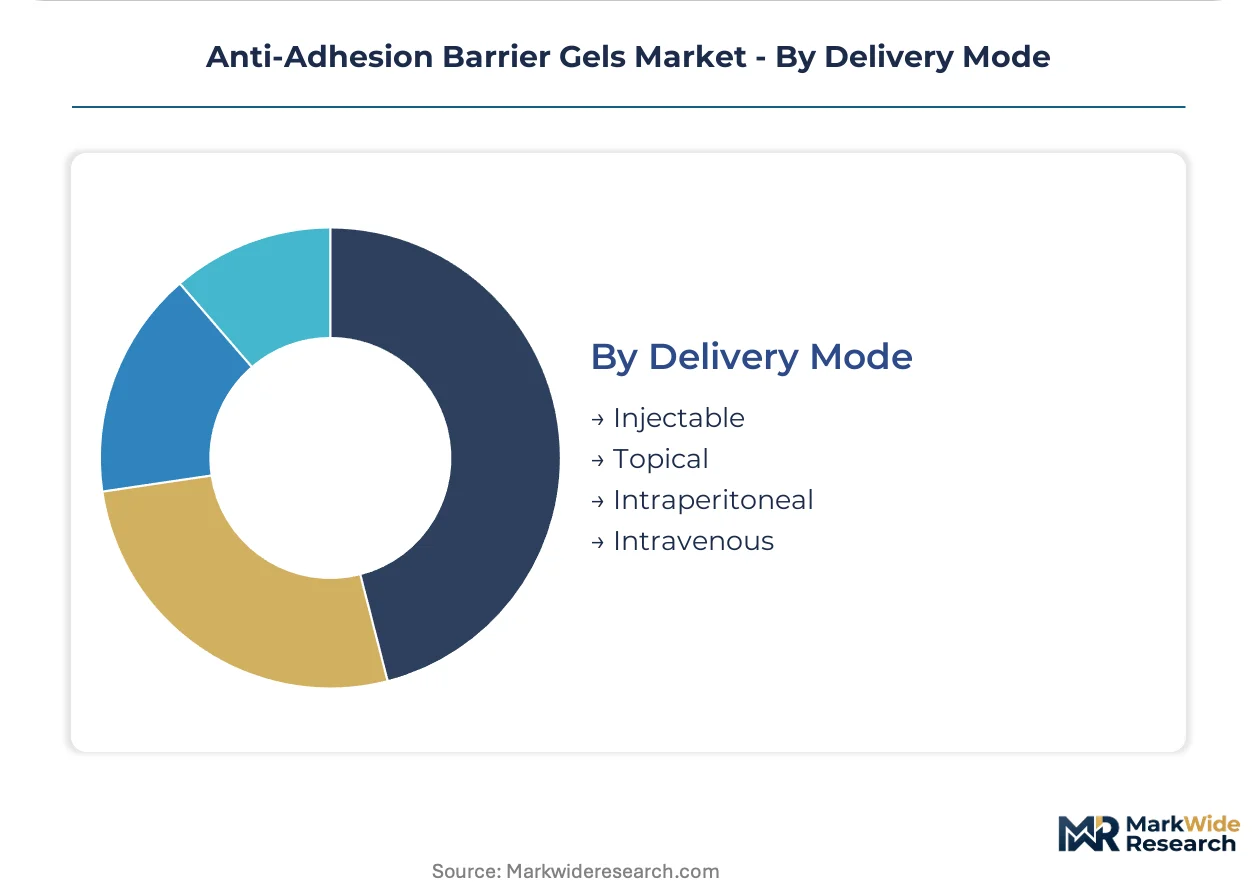
- Injectable:Syringe-based application through laparoscopic ports represents the standard workflow for hyaluronic acid derivative deployment in peritoneal procedures.
- Topical:Surface coating methods suit open procedures where direct visualization enables manual distribution.
- Intraperitoneal:Instillation techniques for broad anatomical coverage are gaining traction in robotic surgery where precision spray applicators compatible with da Vinci and Versius platforms enable consistent coating.
- Intravenous:Systemic administration routes remain experimental for adhesion prevention, with no established clinical protocols.
Injectable methods retain the largest procedure volume; intraperitoneal delivery is expanding most quickly on robotic platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and India's pharmaceutical corridors are concentrating contract manufacturing investment for medical-grade hyaluronic acid fermentation. These tax-advantaged clusters anchor raw material supply chains serving Western barrier gel formulators.
United States
Ambulatory surgical center volumes in Texas, Florida, and Ohio are formalizing adhesion prevention protocols for laparoscopic hernia and gynecologic procedures. The FDA's updated 510(k) biocompatibility testing mandates are compressing development timelines for new entrants. Hospital value analysis committees in integrated delivery networks are consolidating vendor relationships across barrier gel, mechanical sheet, and spray applicator categories.
Germany
Academic medical centers in Berlin and Munich are validating advanced cross-linking chemistries for hyaluronic acid derivatives in multi-center efficacy trials. The EU Medical Device Regulation's full implementation has cleared backlog uncertainty, enabling notified bodies to process conformity assessments for absorbable barriers. Manufacturers with MDR certificates are securing hospital tenders across Bavaria and North Rhine-Westphalia.
China
Pharmaceutical-grade hyaluronic acid supply concentrates among three fermentation specialists serving cost-sensitive markets. The country's PLI scheme for medical devices is attracting contract manufacturing investment into tier-2 and tier-3 hospital markets. Zhengzhou and Hangzhou medical device clusters are scaling production of cost-optimized formulations for domestic consumption and export.
Japan
PMDA regulatory pathways for combination device gels are advancing antibiotic-loaded and hemostatic-modified matrices through clinical validation. Tokyo and Osaka metropolitan hospital systems are piloting multifunctional platforms in orthopedic and cardiovascular procedures. METI industrial policy is supporting precision spray applicator development compatible with da Vinci and Versius robotic platforms.
India
Maharashtra and Gujarat pharmaceutical corridors are building surgical infrastructure for adhesion prevention in tier-2 and tier-3 cities. CDSCO medical device regulations are aligning with international standards to facilitate import substitution. Mumbai and Ahmedabad medical device parks are attracting Korean and European joint ventures for localized barrier gel manufacturing.
Anti-Adhesion Barrier Gels Market Competitive Environment
United States producers anchor one tier; Chinese and Korean specialists hold manufacturing scale positions in raw material supply. The market structures around three tiers: diversified surgical conglomerates with broad hospital procurement networks, mid-cap hyaluronic acid derivative specialists with fermentation advantages, and regional contract manufacturers serving cost-sensitive markets. Strategic moves concentrate on M&A for clinical dossier acquisition and capacity expansion into Indian special economic zones.
Within the diversified surgical tier, Johnson & Johnson and Baxter International exemplify incumbents with established FDA clinical dossiers and integrated distribution into ambulatory surgical centers. Hangzhou Singclean Medical Products occupies a position among fermentation-scale specialists competing on manufacturing economics for hyaluronic acid derivatives. These three anchors represent distinct competitive archetypes: portfolio breadth, regulatory depth, and production scale.
| Leading Market Players |
|---|
| Anika Therapeutics |
| Hangzhou Singclean Medical Products |
| Johnson & Johnson |
| Sanofi |
| PlantTec Medical GmbH |
| Baxter International |
| FzioMed |
| LG Chem Life Sciences |
| Integra LifeSciences |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade hyaluronic acid spot indices in China cascade through fermentation tolling, cross-linking chemistry, and sterile fill-finish to stratify Western barrier gel pricing across premium MDR-certified, standard FDA-cleared, and economy-tier contract-manufactured tiers.
Pricing Analysis
Short lead-time premiums of four-to-six weeks command twenty-to-thirty percent markups over twelve-week standard procurement cycles in the United States hospital sector. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 10993-6 study completion status and MDR certificate possession. Cost compression in economy tiers is intensifying because Indian contract manufacturers are absorbing REACH documentation burdens to capture European volume. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with sole-source contracts demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from United States integrated delivery networks, while distributor-mediated flows serve tier-2 and tier-3 clinics. Supply concentrates in China for pharmaceutical-grade hyaluronic acid fermentation, the United States for carboxymethylcellulose refinement, and Germany for precision spray applicator engineering. Raw material dependencies rest on bacterial fermentation feedstocks, cross-linking agent chemistries, and sterile barrier packaging. Single-source vulnerability in Chinese hyaluronic acid specialists creates formulation batch inconsistency risks for Western formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier gel manufacturers are racing to secure captive hyaluronic acid fermentation capacity or long-term offtake agreements with Chinese specialists to defend margin structures against raw material volatility.
For Market Incumbents: To counter mechanical sheet substitute persistence in open abdominal procedures, Johnson & Johnson and Baxter International should deepen clinical education deployments converting surgeons to laparoscopic gel techniques while securing multi-year sole-source contracts with Texas and Florida integrated delivery networks that bundle barriers, applicators, and spray systems. For New Entrants and Emerging Players: Cost-sensitive tier-2 hospitals in Maharashtra and Gujarat represent the most penetrable buyer archetype for MDR-certified economy-tier formulations. Korean and European joint ventures with Ahmedabad medical device parks can leverage PLI scheme incentives to undercut incumbent pricing while building CDSCO-compliant clinical dossiers for domestic tender participation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap hyaluronic acid derivative specialists with incomplete MDR transitions in Germany and Japan. Long-term viability over the next decade hinges on combination device platform development merging adhesion prevention with antibiotic delivery. The signal to watch is PMDA approval velocity for multifunctional matrices in orthopedic applications.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certificate Acquisition | EU notified body clearance enables hospital tender participation across France, Italy, and Spain. |
| Robotic Spray Applicator Development | da Vinci and Versius compatibility captures procurement attention from United States integrated health networks. |
| Indian Contract Manufacturing Scale-Up | PLI scheme utilization penetrates tier-2 and tier-3 hospital markets where adhesion prevention remains nascent. |
| Combination Device Pathway Advancement | Antibiotic-loaded hyaluronic acid matrices unify previously separate product categories into single-application platforms. |
| Ambulatory Surgical Center Protocol Formalization | Medicare reimbursement clarity accelerates outpatient gel adoption for laparoscopic hernia and gynecologic procedures. |
Study Parameters
Independent corroboration across hospital purchasing committee interviews, GPO contract databases, and CMS Medicare reimbursement filings underwrites the qualitative findings. Primary fieldwork engaged surgical department heads, biomedical engineers, regulatory affairs specialists at barrier gel manufacturers, and ambulatory surgical center administrators. Secondary validation drew from FDA 510(k) premarket notification databases, EUDAMED MDR certificate registries, ISO 10993 biocompatibility standard documentation, and hospital procurement platform records. Bottom-up demand modeling across procedure volumes and top-down market sizing through manufacturer revenue triangulation anchored value estimates.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and post-MDR implementation recovery informed projection anchor points across the analysis window. Segmentation dimensions modeled include product type viscosity grades, application specialty reimbursement tiers, end-user capital intensity thresholds, and delivery mode robotic compatibility. CAGRs derived from logarithmic trend fitting of validated historical data points. Forecast inputs incorporated ambulatory surgical center migration rates and orthopedic revision procedure volume trajectories.
Revisions become necessary when FDA biocompatibility testing mandates expand, Chinese export licensing regimes tighten, or REACH authorization requirements for polymer raw materials escalate. Forecasts reflect documented assumptions regarding reimbursement clarity maintenance and MDR notified body processing capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Global Adhesive Bandages Market