
 Global Urgent Care Apps Market | 2026-2036
Global Urgent Care Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urgent Care Apps Market Foresight
Shortages of emergency medicine physicians are rotating hospital systems toward digital triage tools that extend clinical capacity without adding headcount. Twiage Solutions Inc. leverages real-time emergency alert routing to reduce ambulance-to-bed handoff delays. PatientSafe Solutions anchors its position through secure clinical communication workflows that integrate with existing EHR infrastructure. Medisafe competes by sustaining high medication adherence engagement rates among chronic disease populations.
Urgent care apps are software platforms that deliver real-time symptom assessment, care navigation, and clinical communication through mobile and web interfaces, typically requiring HL7 FHIR interoperability and HIPAA-grade encryption for health data exchange. Their primary purpose is to reduce unnecessary emergency department utilization while accelerating appropriate care escalation. Teleconsultation segments dominate revenue generation as health systems seek reimbursable virtual visit pathways that replace low-acuity physical encounters. Wearable platforms represent the fastest-growing category, with Apple Watch and Android-compatible health sensors enabling passive vital streaming that triggers automated emergency alerts before patient awareness.
The FDA regulates these apps as Software as a Medical Device when diagnostic algorithms exceed low-risk thresholds, while HIPAA mandates encryption standards that shape vendor architecture decisions. The EU AI Act imposes additional conformity requirements on symptom checkers that classify patient risk autonomously. Stakeholders must monitor evolving reimbursement parity laws that determine whether teleconsultation minutes receive equivalent payment to in-person evaluation codes.
Market Dynamics
Emergency physician shortages are compressing clinical capacity across hospital systems, forcing administrators toward digital triage platforms that extend existing workforce reach without proportional headcount expansion. This structural pressure is reconfiguring vendor priorities toward HL7 FHIR interoperability and real-time alert routing.
Growth Catalysts
- EU AI Act compliance mandates:The European Union's risk-classification framework for autonomous symptom checkers accelerates clinical validation investments among platform developers seeking CE marking access.
- Apple Watch passive vital streaming:Wearable sensor integration enables automated emergency detection before patient awareness, expanding addressable use cases beyond active symptom reporting.
- United States reimbursement parity legislation:State-level mandates for equivalent teleconsultation payment to in-person evaluation codes unlock sustainable revenue models for health system deployments.
Market Restraints
- HIPAA encryption architecture costs:Mandatory technical safeguards for protected health information impose substantial infrastructure expenditure on smaller platform vendors.
- FDA Software as a Medical Device classification uncertainty:Diagnostic algorithm risk stratification creates prolonged pre-market clearance timelines that delay commercialization.
- Health system EHR integration complexity:Proprietary data formats from Epic Systems and Cerner Corporation fragment interoperability efforts and extend implementation cycles.
Strategic Opportunities
- Rural United States primary care deserts:Geographic clinician scarcity creates immediate demand for asynchronous triage tools that substitute for physical access.
- Japan's aging population emergency response:METI incentives for preventive health technology adoption open public-sector procurement channels for fall-detection wearables.
- AI-ECG convergence for arrhythmia screening:Machine learning classification of single-lead electrocardiograms enables population-scale cardiovascular risk stratification.
Industry Challenges
- HL7 FHIR implementation expertise scarcity:Health data exchange standard proficiency remains concentrated among specialized integration vendors, constraining deployment velocity.
- Clinical workflow reconfiguration resistance:Emergency department staff require sustained training investment to trust algorithmic triage recommendations over traditional protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urgent Care Apps Market |
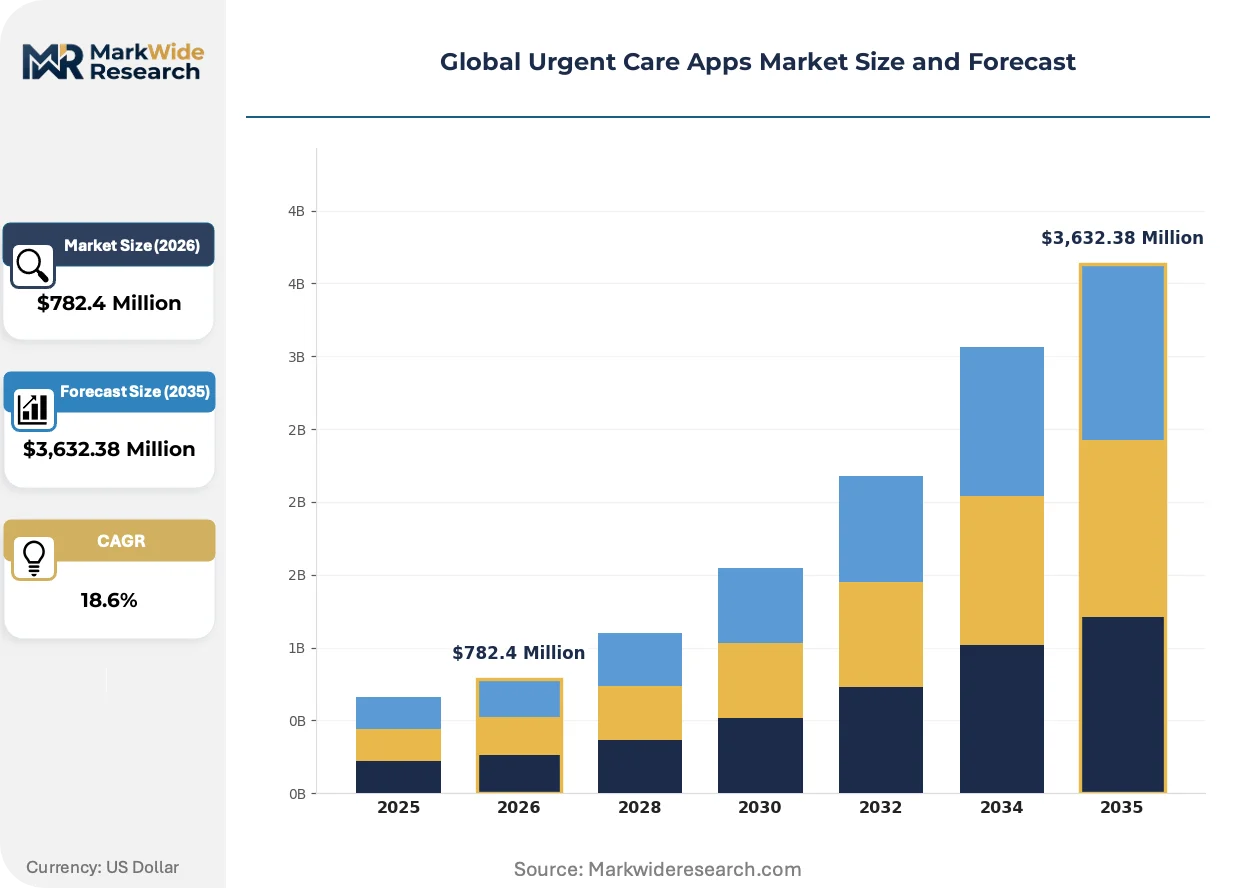
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $3,632.38 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Symptom Checker, Appointment Booking, Teleconsultation, Emergency Alerts, Prescription Management Platform: iOS, Android, Web-Based, Hybrid, Wearable Platforms End User: Patients, Healthcare Providers, Pharmacies, Insurance Companies, Caregivers Monetization Model: Subscription, Pay-Per-Use, Advertisement, Freemium, Commission-Based |
| Companies Covered | Allm Inc., Johnson & Johnson Services, Inc., PatientSafe Solutions, AlayaCare, TigerConnect, Imprivata, Inc., Medisafe, Twiage Solutions Inc., Hospify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urgent Care Apps Market Shifts & Advancements
Passive biometric monitoring is displacing active patient-reported symptom entry as the dominant data acquisition mode. This shift compresses time-to-intervention metrics and redefines the competitive basis from user interface design to sensor fusion accuracy.
Photoplethysmography sensor arrays embedded in consumer wearables are miniaturizing to enable continuous blood oxygen and heart rate variability tracking without dedicated medical devices. Hospital systems in the United States are piloting these platforms for post-discharge monitoring of congestive heart failure patients. The technology is miniaturizing the boundary between consumer wellness and clinical-grade monitoring, forcing regulatory frameworks to adapt classification thresholds.
The EU AI Act's high-risk system requirements for autonomous patient risk classification impose conformity assessment obligations on symptom checker algorithms. Developers must now maintain quality management systems and post-market monitoring protocols equivalent to physical medical devices. European health technology procurement specifications increasingly embed these compliance attestations as mandatory bid criteria.
Health system purchasing committees are consolidating vendor selection authority under centralized digital health governance offices. Decentralized department-level app procurement is yielding to enterprise architecture review that prioritizes EHR-native integration over standalone functionality. This concentration is most advanced in United States integrated delivery networks with mature chief digital officer functions.
Global Urgent Care Apps Market Segmentation
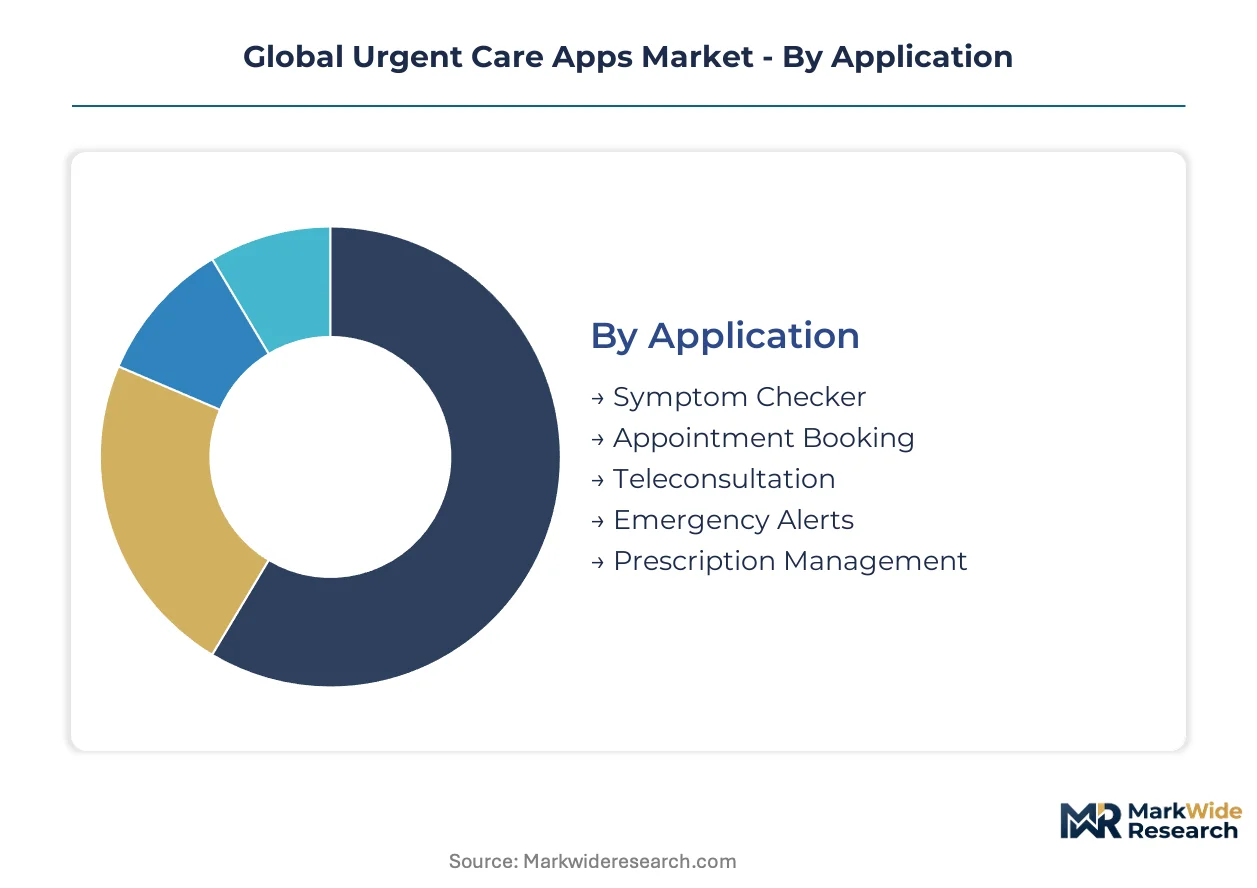
Segmentation in urgent care apps determines vendor architecture decisions and reimbursement pathway eligibility. Platform choice shapes sensor integration capabilities, while monetization models dictate health system procurement cycles versus direct-to-consumer scalability.
Application:
Margin pools concentrate in teleconsultation workflows where health systems secure reimbursable virtual visit codes, while symptom checkers face regulatory compliance cost pressures that compress profitability.
- Symptom Checker:Algorithmic triage engines classify patient acuity through natural language processing and body-map interfaces. Demand concentrates in United States primary care deserts where physician scarcity pushes patients toward autonomous assessment tools, though FDA Software as a Medical Device classification uncertainty extends commercialization timelines.
- Teleconsultation:Real-time video and audio consultation platforms integrate with EHR systems for documentation continuity. Health systems in Germany and France deploy these for reimbursable virtual visits under national telehealth expansion mandates, capturing sustainable revenue streams absent in purely consumer-facing segments.
- Appointment Booking:Scheduling middleware connecting patients to available clinical capacity.
- Emergency Alerts:Automated escalation protocols triggered by vital threshold breaches or patient-activated distress signals.
- Prescription Management:Medication adherence tracking with pharmacy integration for refill automation.
The dominant share belongs to Teleconsultation, while Emergency Alerts is closing the gap fastest through wearable sensor integration.
Platform:
Volume distribution tracks smartphone OS market penetration, though wearable platforms command premium pricing through continuous biometric streaming capabilities.
- iOS:Native applications leveraging Apple's HealthKit framework for standardized data exchange with clinical systems. United States health systems prioritize iOS deployments for Apple Watch passive monitoring integration, particularly in post-discharge congestive heart failure programs.
- Android:Open-source flexibility enables custom sensor drivers for regional device ecosystems. India's fragmented device landscape drives Android-first development among domestic urgent care app vendors targeting price-sensitive patient populations.
- Web-Based:Browser-accessible platforms eliminating download friction for one-time users.
- Hybrid:Cross-platform frameworks balancing development efficiency against native performance.
- Wearable Platforms:Dedicated smartwatch and sensor-native applications.
iOS retains the largest installed base, though Wearable Platforms is expanding most quickly through photoplethysmography sensor miniaturization.
End User:
Customer type determines contract structure, with healthcare providers demanding enterprise SLAs while patients drive volume through direct-to-consumer channels.
- Patients:Direct consumers seeking symptom assessment and care navigation without intermediary referral. Demand clusters in United States metropolitan areas with fragmented insurance networks, where out-of-pocket costs for unnecessary emergency department visits create immediate willingness-to-pay for triage certainty.
- Healthcare Providers:Hospitals and physician groups deploying platforms for workforce extension. Japan's Ministry of Economy, Trade and Industry incentivizes provider adoption of preventive health technologies, opening public procurement channels for fall-detection and emergency response systems.
- Pharmacies:Retail chains integrating medication management and telepharmacy services.
- Insurance Companies:Payers deploying triage tools to steer members toward appropriate care settings.
- Caregivers:Family members and professional aides monitoring dependent populations.
Healthcare Providers command the highest contract values, while Insurance Companies are gaining share fastest through value-based care incentive alignment.
Monetization Model:
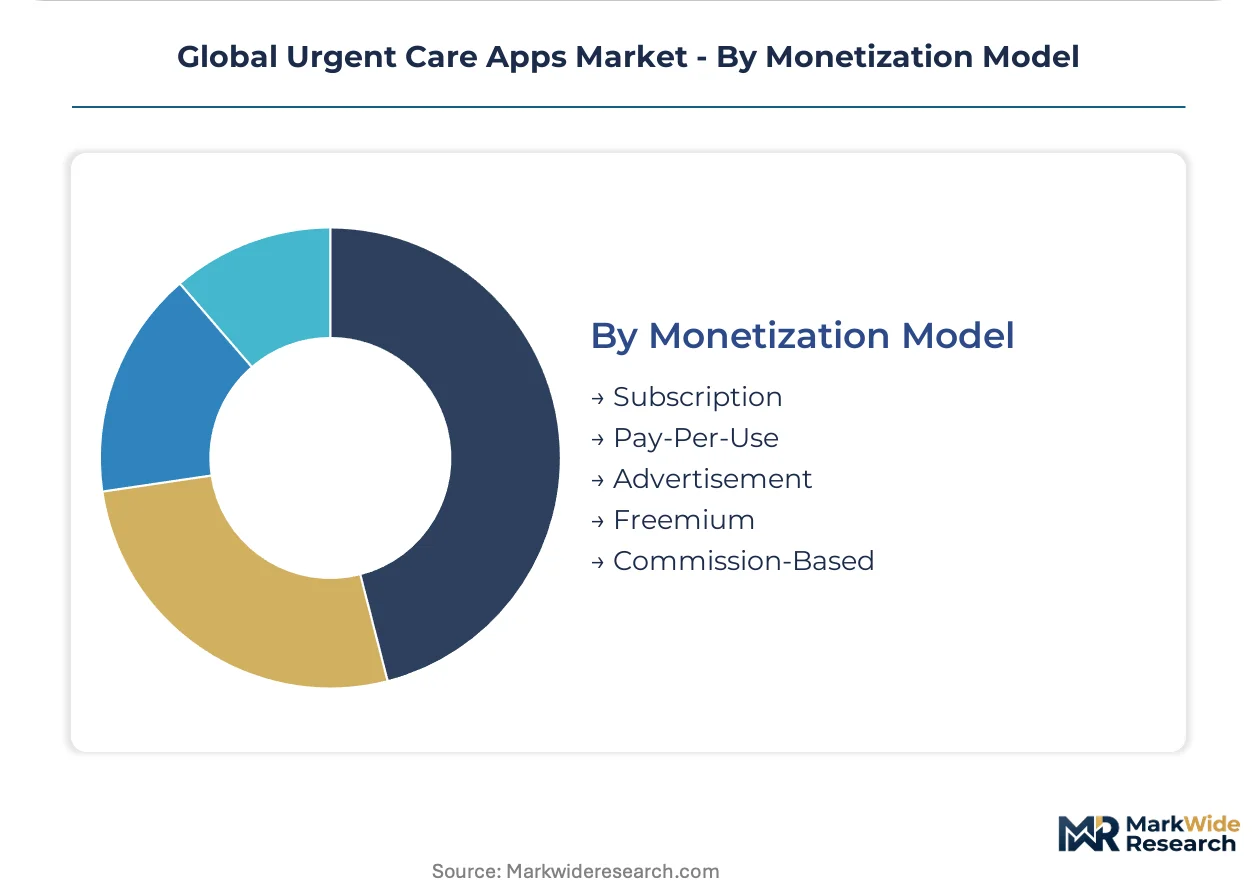
Revenue predictability varies dramatically, with subscription models favored by enterprise health systems and freemium structures dominating consumer acquisition.
- Subscription:Recurring license fees for platform access with tiered feature entitlements. United States integrated delivery networks with mature chief digital officer functions consolidate vendor selection under centralized governance, preferring subscription contracts with guaranteed uptime SLAs over transactional alternatives.
- Pay-Per-Use:Per-consultation or per-assessment transactional pricing. Brazil's private health insurance market favors this model for occasional users unwilling to commit to recurring payments, though revenue volatility constrains vendor infrastructure investment.
- Advertisement:Sponsored placement of healthcare services and pharmaceutical products.
- Freemium:Basic functionality at no cost with premium feature unlocks.
- Commission-Based:Revenue share on care referrals and prescription fulfillment.
Subscription generates the most stable cash flows, while Commission-Based models are climbing the fastest through pharmacy and specialty care referral network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys urgent care apps predominantly for emergency department diversion and workforce extension, while Germany and Japan emphasize preventive monitoring and aging-population emergency response, creating fundamentally different consumption profiles across major markets.
United States
Fragmented primary care access and high out-of-pocket emergency costs drive patient willingness-to-pay for triage certainty. FDA Software as a Medical Device classification shapes vendor commercialization timelines and risk management investments. Hospital systems in Texas and Florida pilot wearable-integrated post-discharge monitoring for congestive heart failure populations.
Germany
National telehealth expansion mandates establish reimbursable virtual visit pathways that sustain platform revenue models. The EU AI Act imposes conformity assessment obligations on autonomous symptom checkers seeking CE marking. Berlin and Munich health technology clusters concentrate clinical validation expertise and quality management system providers.
Japan
METI incentives for preventive health technology adoption open public-sector procurement channels for fall-detection and emergency response systems. PMDA consultation frameworks guide developers through software medical device registration requirements. The Kanto region around Tokyo anchors health system purchasing committee consolidation under centralized digital health governance offices.
United Kingdom
NHS Long Term Plan commitments to digital-first primary care create institutional demand for asynchronous triage tools. MHRA guidance on software as a medical device aligns with evolving EU regulatory frameworks post-Brexit. London's integrated care systems consolidate vendor selection authority under mature chief digital officer functions.
India
Price-sensitive patient populations and fragmented device ecosystems drive Android-first development strategies among domestic vendors. CDSCO medical device rules apply to diagnostic algorithms exceeding low-risk thresholds. Bangalore and Hyderabad clusters concentrate health data exchange integration expertise for HL7 FHIR implementation.
Global Urgent Care Apps Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding enterprise health system contracts through EHR-native integration capabilities while specialists compete on sensor fusion accuracy and clinical workflow customization. The market structure favors vendors with proven HIPAA-grade encryption architecture and real-time alert routing infrastructure. Three archetypes dominate: integrated platform providers spanning teleconsultation through emergency alerts, wearable-native specialists leveraging passive biometric streaming, and communication workflow optimizers embedding secure messaging into existing clinical systems. Competitive moves concentrate on strategic partnerships with EHR vendors and geographic expansion into primary care desert regions.
Within the integrated platform tier, Johnson & Johnson Services, Inc. and Allm Inc. exemplify enterprise-scale positioning through comprehensive care navigation capabilities. PatientSafe Solutions occupies a position among communication workflow specialists, anchoring secure clinical messaging integration. Twiage Solutions Inc. represents the emergency alert routing archetype, sitting within the real-time escalation protocol segment. These three companies illustrate the strategic divergence between breadth-focused platform consolidation and depth-focused clinical communication specialization.
| Leading Market Players |
|---|
| Allm Inc. |
| Johnson & Johnson Services, Inc. |
| PatientSafe Solutions |
| AlayaCare |
| TigerConnect |
| Imprivata, Inc. |
| Medisafe |
| Twiage Solutions Inc. |
| Hospify |
| Others |
Supply & Pricing Matrix
Long-term enterprise subscription contracts with health systems lock in both platform access and price visibility, insulating vendors from spot-market volatility while committing buyers to multi-year HL7 FHIR integration roadmaps. These arrangements concentrate pricing power with EHR-native vendors capable of delivering HIPAA-grade encryption and real-time alert routing as bundled capabilities.
Pricing Analysis
Subscription SaaS-tiered contracts dominate health system procurement, with pricing stratifying across enterprise, mid-market, and departmental tiers based on integration complexity and SLA guarantees. Price differentiation centers on FDA Software as a Medical Device certification status and Epic Systems native integration depth. Cost compression in the mid-market tier is intensifying because smaller vendors struggle to amortize compliance investments across limited subscriber bases. Direct-to-consumer segments show highest price sensitivity, while integrated delivery networks with mature chief digital officer functions demonstrate lowest sensitivity due to budget consolidation under centralized governance.
Supply Chain Analysis
The United States and Germany anchor clinical validation expertise and quality management system providers, while India concentrates health data exchange integration talent for HL7 FHIR implementation. Cloud infrastructure draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform data center networks. Single-source vulnerability sits with Epic Systems and Cerner Corporation proprietary EHR formats that fragment interoperability efforts. Distribution runs through health system purchasing committees consolidating vendor selection authority under centralized digital health governance offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of HL7 FHIR implementation expertise constrains deployment velocity across health systems, creating defensive moats for vendors with proven integration track records and opening acquisition premiums for specialized talent pools.
For Market Incumbents: Secure EHR-native integration capabilities through targeted capability acquisitions, prioritizing Epic Systems and Cerner Corporation workflow certification depth. Lock in health system purchasing committee relationships before centralized digital health governance offices complete vendor consolidation, as committee consolidation threatens to displace point-solution vendors lacking enterprise architecture review standing. For New Entrants and Emerging Players: Rural United States primary care deserts represent the most penetrable geography, where physician scarcity creates immediate demand for asynchronous triage tools without incumbent saturation. Target Japan's aging population emergency response segment, where METI incentives for preventive health technology adoption open public-sector procurement channels. Lead with wearable-native fall-detection capabilities and PMDA consultation framework navigation as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Wearable-native specialists with proven photoplethysmography sensor fusion accuracy offer the strongest acquisition target archetype, as passive biometric monitoring displaces active symptom entry across clinical workflows. Long-term viability hinges on EU AI Act conformity assessment completion and post-market monitoring protocol maturity. Watch for state-level reimbursement parity legislation expansion as the critical inflection signal for teleconsultation revenue model sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR Native Integration | Epic Systems and Cerner Corporation workflow certification unlocks health system purchasing committee access. |
| FDA Software as a Medical Device Submission | Diagnostic algorithm clearance extends commercialization timelines but enables premium pricing in risk-stratified segments. |
| EU AI Act Conformity Assessment | CE marking access for autonomous symptom checkers requires quality management systems equivalent to physical medical devices. |
| Wearable Sensor Partnership | Apple Watch HealthKit framework integration enables passive vital streaming for congestive heart failure post-discharge monitoring. |
| Hospital System Pilot Expansion | Texas and Florida health system deployments generate referenceable outcomes for congestive heart failure population management. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with chief digital officers, hospital purchasing committee chairs, HL7 FHIR integration specialists, and biomedical engineers; and secondary validation through FDA 510(k) filings, CMS Medicare telehealth reimbursement data, hospital procurement databases, and GPO contracts. Bottom-up and top-down triangulation cross-checked platform deployment counts against health system IT expenditure surveys.
Across the projection horizon, the analytical framework modeled segmentation dimensions including application type, platform architecture, end user category, and monetization model, with regional adoption patterns as an industry-specific overlay. CAGRs were derived from installed base growth trajectories and average revenue per user expansion rates, incorporating wearable sensor penetration curves and teleconsultation reimbursement parity legislation status as forecast inputs.
Material uncertainties — FDA Software as a Medical Device classification timeline shifts, EU AI Act enforcement interpretation changes, and health system EHR vendor consolidation patterns — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory clarity and reimbursement policy continuity that could revise trajectory if federal or state-level mandates accelerate or stall. Recalibration cycles align with material shifts in HIPAA enforcement guidance and telehealth parity legislation adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Digiceuticals Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
US Digital Therapeutics Market