
 Medical Instruments Disinfection Market | 2026-2036
Medical Instruments Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Instruments Disinfection Market Insights
Buyer concentration among hospital networks is hardening as integrated delivery systems consolidate purchasing decisions across multiple facilities. STERIS leverages its installed base of automated washers to sustain long-term service contracts with major health systems. Getinge AB anchors its position through R&D intensity in low-temperature sterilization platforms for heat-sensitive endoscopes.
Medical instruments disinfection encompasses validated processes and equipment designed to eliminate microbial contamination from reusable clinical devices, typically achieving sporicidal efficacy through steam, chemical, or radiation modalities measured by sterility assurance levels. The primary purpose centers on preventing healthcare-associated infections while preserving instrument functionality across thousands of use cycles. Chemical disinfectants occupy mature margin pools in high-volume settings where rapid turnaround dominates, while UV sterilizers represent the fastest-growing technology segment as facilities seek residue-free alternatives for delicate electronics. Thermal methods retain structural dominance in central sterile supply departments where steam autoclaves handle the bulk of surgical instrument loads.
FDA enforces premarket notification requirements for sterilization equipment through 510(k) pathways, directly shaping product development timelines and validation costs for manufacturers seeking US market access. EPA regulates chemical disinfectant efficacy claims under FIFRA, creating compliance barriers that favor established formulators with robust antimicrobial testing infrastructure. The Joint Commission accreditation standards further amplify demand by mandating documented sterilization quality assurance in accredited facilities. Stakeholders must monitor evolving sustainability mandates as healthcare systems begin weighing water consumption and chemical waste metrics alongside traditional efficacy benchmarks in procurement decisions.
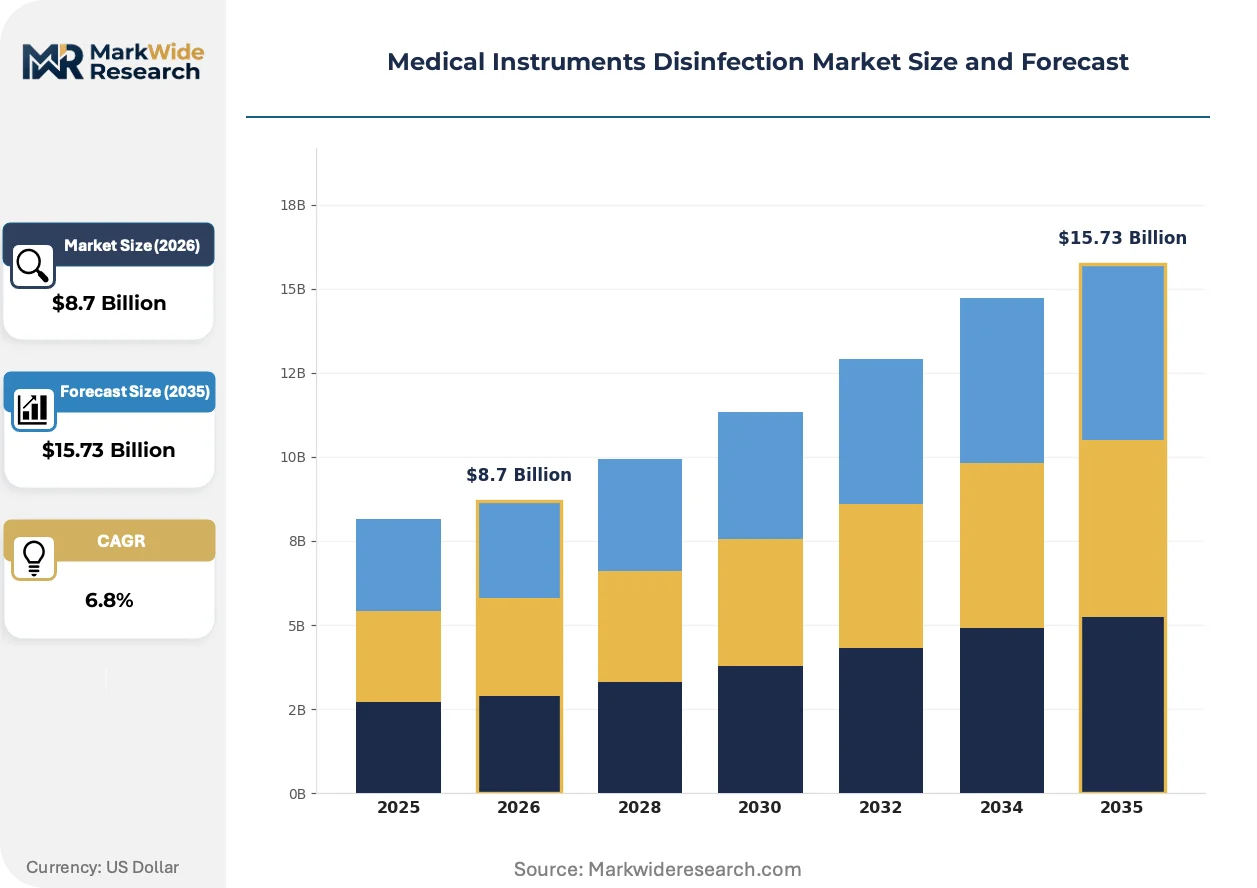
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing sterilization equipment manufacturers to restructure pricing models around total-cost-of-ownership metrics rather than upfront capital expenditure.
Growth Catalysts
- FDA 510(k) pathway refinement:Streamlined premarket notification for automated reprocessing systems accelerates manufacturer time-to-market for next-generation sterilizers targeting ambulatory surgical centers.
- Ambulatory surgical center expansion:United States outpatient facility construction is driving instrument turnover velocity and creating sustained demand for rapid-cycle disinfection equipment.
- Steam autoclave technology maturation:Central sterile supply departments in integrated delivery networks are standardizing on validated thermal protocols that reduce reprocessing variability across multi-site operations.
Market Restraints
- Stainless steel and specialty alloy input volatility:Autoclave chamber fabrication depends on commodity metal markets subject to supply disruption from concentrated mining jurisdictions.
- EPA FIFRA compliance barriers:Chemical disinfectant efficacy claim validation requires extensive antimicrobial testing infrastructure that excludes smaller formulators from premium hospital contracts.
- Heat-sensitive endoscope limitation:Flexible endoscope construction materials cannot tolerate standard steam sterilization, fragmenting reprocessing workflows and requiring parallel capital investment in low-temperature platforms.
Strategic Opportunities
- UV-C LED convergence with robotics:Automated ultraviolet sterilization systems for delicate electronics represent untapped white space as surgical instruments incorporate increasing sensor density.
- United States rural hospital network penetration:Critical access facilities remain underpenetrated by automated reprocessing technology, creating channel expansion potential for mid-capacity system vendors.
- Joint Commission accreditation mandate amplification:Documented sterilization quality assurance requirements are extending beyond accredited hospitals into outpatient surgery centers and diagnostic imaging facilities.
Industry Challenges
- Biomedical technician certification scarcity:Automated washer-disinfector maintenance requires specialized training programs that hospital systems struggle to staff across distributed facility networks.
- Legacy steam infrastructure integration:Central sterile supply departments face workflow disruption when retrofitting older facilities with connected monitoring systems for real-time sterility assurance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Instruments Disinfection Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autoclaves, Chemical Disinfectants, UV Sterilizers, Heat-based Sterilizers End User: Hospitals, Clinics, Labs, Dental Practices Technology: Chemical Methods, Thermal Methods, Radiation Methods, Hybrid Methods Application: Operating Rooms, Emergency Units, Patient Rooms, Equipment Reprocessing |
| Companies Covered | STERIS, 3M, Ecolab, Getinge AB, Steelco S.p.A., Schülke & Mayr GmbH, Sotera Health, Cantel Medical, O&M Halyard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Instruments Disinfection Market Trends and Innovations
Reprocessing technology is converging around data-enabled traceability systems that document sterilization parameters at the individual instrument level, replacing batch-level recordkeeping with unit-specific digital twins.
Hydrogen peroxide vapor sterilization is unifying low-temperature efficacy with reduced cycle times for heat-sensitive surgical instruments. Academic medical centers in Germany and the United States are adopting these platforms for complex endoscope reprocessing. This convergence is compressing capital allocation trade-offs between central sterile supply throughput and specialty procedure volume.
EU MDR Article 10 technical documentation requirements are mandating enhanced clinical evidence for reusable device validation. Sterilization equipment manufacturers must now generate performance data under simulated use conditions. European notified bodies are extending review timelines for washer-disinfector certifications, compressing product launch windows.
Integrated delivery networks are unbundling equipment procurement from long-term service agreements, forcing sterilization vendors to compete on discrete maintenance contract terms. Hospital supply chain executives in the United States are consolidating vendor panels and mandating interoperability with existing enterprise asset management platforms. This behavioral shift is most visible in multi-state health systems standardizing reprocessing protocols across fifty-plus facility footprints.
Medical Instruments Disinfection Market Segmentation
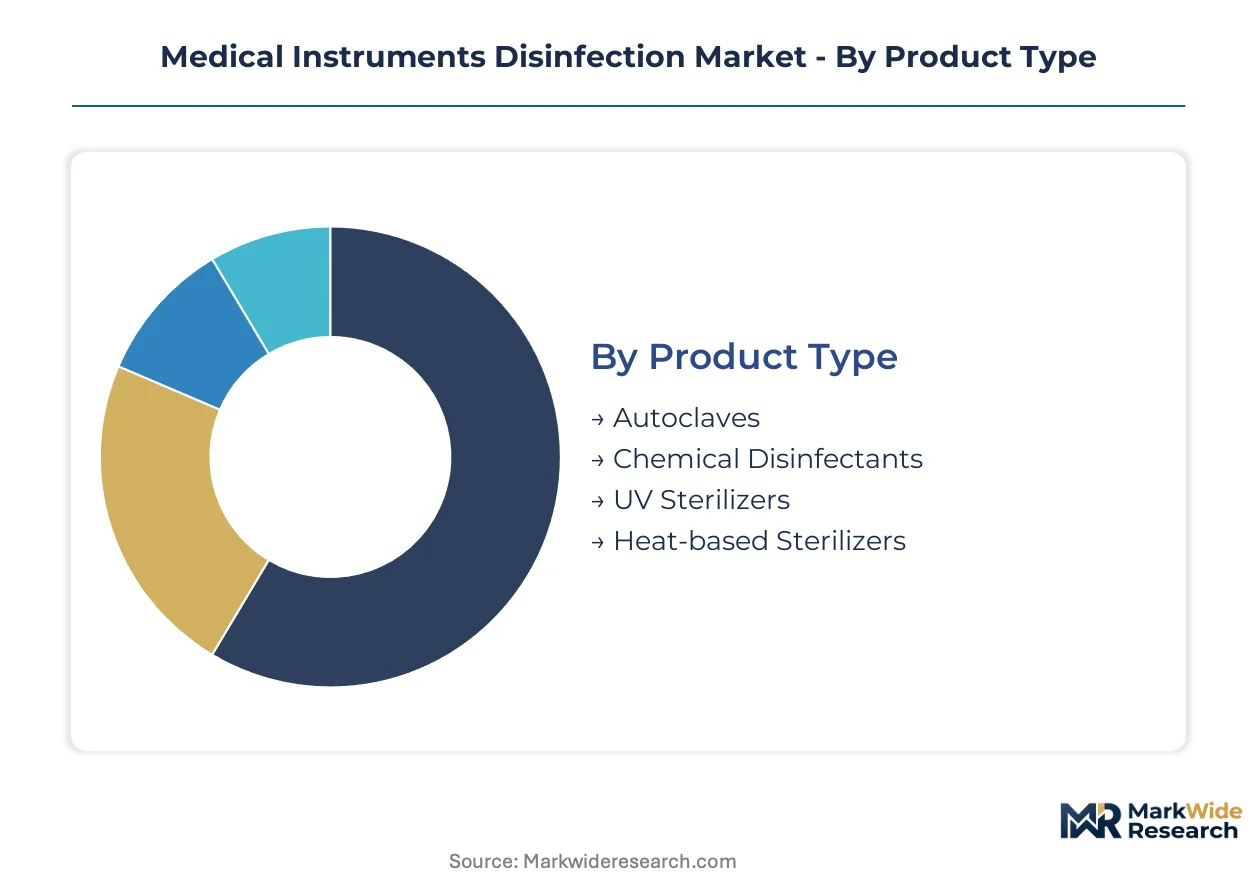
Segmentation in medical instruments disinfection reveals how procurement decisions bifurcate between high-throughput central sterile supply departments and distributed point-of-care settings. Equipment specifications, chemical compatibility requirements, and regulatory validation pathways vary sharply across these divides, forcing vendors to maintain parallel product architectures.
Product Type:
Thermal efficacy specifications and cycle throughput requirements differentiate equipment categories for central versus distributed reprocessing environments.
- Autoclaves:Saturated steam sterilization chambers operating at 121-134°C achieve SAL 10^-6 sporicidal kill for surgical instrument loads. United States hospital networks standardize on gravity-displacement and pre-vacuum configurations for central sterile supply throughput. Demand concentrates in integrated delivery systems consolidating multi-site reprocessing protocols.
- Chemical Disinfectants:Liquid formulations including glutaraldehyde, ortho-phthalaldehyde, and hydrogen peroxide achieve high-level disinfection for heat-sensitive devices. Ambulatory surgical centers in the United States prioritize rapid turnaround chemistries with reduced contact times. EPA FIFRA registration requirements favor established formulators with antimicrobial testing infrastructure.
- UV Sterilizers:Ultraviolet-C emission systems deliver residue-free surface disinfection for delicate electronics.
- Heat-based Sterilizers:Dry heat ovens address moisture-sensitive instruments incompatible with steam exposure.
Autoclaves lead on scale; UV Sterilizers lead on momentum.
End User:
Facility scale and infection control budget allocation determine equipment procurement authority and technology selection criteria.
- Hospitals:Acute care institutions with centralized sterile processing departments manage the highest instrument turnover volumes. United States health systems with fifty-plus facility footprints mandate enterprise asset management integration for new equipment procurement. The Joint Commission accreditation standards drive documented quality assurance investments.
- Clinics:Outpatient facilities require compact, rapid-cycle systems for same-day procedure support. United States ambulatory surgical center expansion accelerates demand for automated washer-disinfectors with validated thermal protocols. FDA 510(k) pathway refinement streamlines premarket notification for these mid-capacity platforms.
- Labs:Research and diagnostic facilities prioritize biosafety containment compatibility.
- Dental Practices:Small-scale settings favor tabletop autoclaves with simplified operation protocols.
Hospitals dominate capital deployment; Clinics are expanding most quickly.
Technology:
Microbial kill mechanism selection hinges on instrument material compatibility, cycle time constraints, and regulatory validation burden.
- Chemical Methods:Liquid and vapor-phase chemistries achieve sterilization through protein denaturation and oxidative damage at ambient temperatures. Heat-sensitive endoscope reprocessing in academic medical centers drives hydrogen peroxide vapor platform adoption. EU MDR Article 10 technical documentation requirements now mandate enhanced clinical evidence for reusable device validation.
- Thermal Methods:Steam and dry heat modalities leverage coagulation kinetics for sporicidal efficacy without chemical residue. Central sterile supply departments retain structural dominance for standard surgical instrument loads. Steam autoclave technology maturation reduces reprocessing variability across multi-site operations.
- Radiation Methods:Gamma and electron beam sterilization serve single-use device manufacturing.
- Hybrid Methods:Combined thermal-chemical or UV-ozone systems address complex device geometries.
Thermal Methods anchor installed capacity; Hybrid Methods gain share fastest.
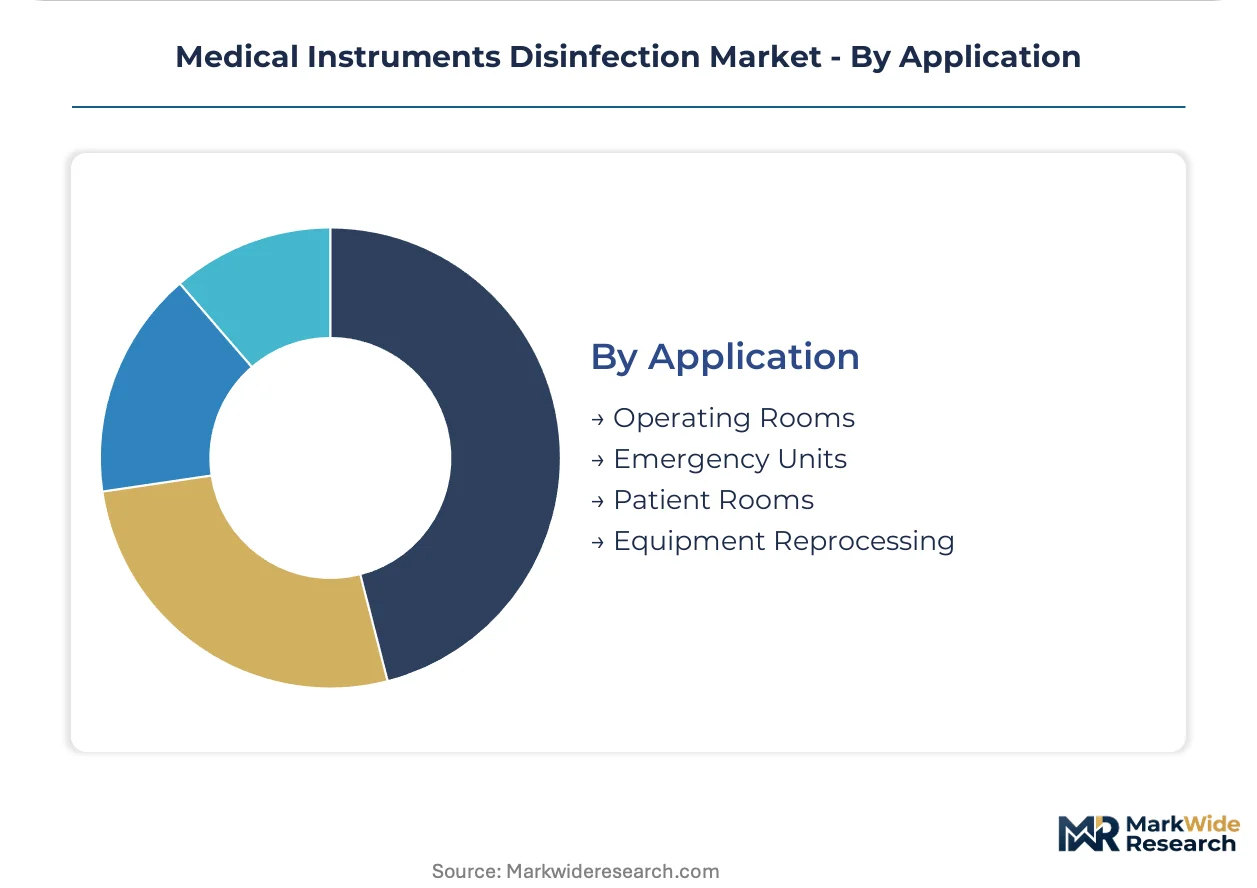
Application:
Clinical workflow urgency and contamination risk profile shape reprocessing protocol selection and equipment placement decisions.
- Operating Rooms:Surgical suites demand immediate instrument availability with validated sterility assurance. United States hospital networks prioritize automated reprocessing systems with real-time monitoring for critical procedure support. Infection control budget prioritization accelerates procurement of connected sterility verification platforms.
- Emergency Units:Trauma and urgent care settings require rapid-turnaround disinfection for unpredictable patient volumes. Point-of-care sterilization capacity reduces dependency on central sterile supply logistics. Equipment reprocessing workflow fragmentation creates demand for compact, validated systems.
- Patient Rooms:Environmental surface disinfection dominates over instrument reprocessing.
- Equipment Reprocessing:Centralized sterile supply departments handle bulk instrument volumes.
Operating Rooms command premium equipment specifications; Emergency Units show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ambulatory surgical center expansion outpaces German hospital consolidation, yet both markets prioritize automated reprocessing systems as infection control budgets gain procurement authority.
United States
Ambulatory surgical center construction accelerates instrument turnover velocity, driving sustained demand for rapid-cycle disinfection equipment. FDA 510(k) pathway refinement streamlines premarket notification for next-generation sterilizers targeting outpatient facilities. Integrated delivery networks in Texas and California consolidate fifty-plus facility footprints around enterprise asset management integration.
Germany
Academic medical centers adopt hydrogen peroxide vapor platforms for complex endoscope reprocessing workflows. EU MDR Article 10 technical documentation requirements mandate enhanced clinical evidence for reusable device validation. Industrial clusters in Baden-Württemberg concentrate washer-disinfector manufacturing and notified body certification services.
Japan
Central sterile supply departments standardize on validated thermal protocols as hospital networks consolidate procurement decisions. METI guidance on medical device software interoperability shapes connected monitoring system adoption. Tokyo-Osaka medical device corridors anchor automated reprocessing equipment distribution channels.
India
Private hospital chains expand infection control infrastructure as healthcare-associated infection awareness rises among payers. CDSCO medical device rules classify sterilization equipment under regulated import and manufacturing frameworks. Maharashtra and Karnataka medical device manufacturing zones attract contract sterilization service investments.
United Kingdom
NHS procurement frameworks prioritize total-cost-of-ownership metrics over upfront capital expenditure for sterilization equipment. MHRA post-Brexit regulatory alignment maintains CE marking recognition while introducing UKCA conformity requirements. London and Greater Manchester health systems pilot data-enabled traceability systems for instrument-level sterilization documentation.
Medical Instruments Disinfection Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment, chemical, and service segments. The market structure tilts toward consolidation as hospital procurement authority concentrates in integrated delivery networks. Three archetypes dominate: full-line sterilization system vendors, chemical disinfectant formulators with EPA FIFRA registrations, and contract sterilization service operators. Competitive moves center on long-term service agreement restructuring and interoperability certification with enterprise asset management platforms.
Among diversified industrial conglomerates, 3M and Ecolab occupy positions spanning chemical disinfectant formulation and healthcare service integration. STERIS anchors the pure-play sterilization equipment archetype through its installed base of automated washers. Getinge AB represents the European specialist model with R&D intensity concentrated in low-temperature platforms. These three entities exemplify how geographic origin and corporate structure map to distinct strategic positioning within procurement-consolidated health systems.
| Leading Market Players |
|---|
| STERIS |
| 3M |
| Ecolab |
| Getinge AB |
| Steelco S.p.A. |
| Schülke & Mayr GmbH |
| Sotera Health |
| Cantel Medical |
| O&M Halyard |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks with fifty-plus facility footprints command procurement authority that compresses vendor margins toward total-cost-of-ownership frameworks. Hospital supply chain executives unbundle equipment capital expenditure from long-term service agreements, forcing sterilization manufacturers to compete on discrete maintenance contract terms rather than upfront pricing.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for automated washer-disinfector platforms. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) validation tier and enterprise asset management interoperability. Cost compression in mid-capacity systems is intensifying because ambulatory surgical center procurement panels consolidate vendor selection. Clinics exhibit highest price sensitivity due to constrained infection control budgets, while academic medical centers prioritize validated low-temperature platforms regardless of premium positioning.
Supply Chain Analysis
Ocean freight volatility from stainless steel suppliers in China and specialty alloy fabricators in Germany elevates landed costs for autoclave chamber components. Autoclave manufacturing draws from concentrated mining jurisdictions for nickel-chromium alloys and precision valve assemblies from Japanese industrial corridors. Single-source vulnerability persists in EPA FIFRA-registered chemical disinfectant active ingredient supply. Distribution runs through GPO contracts and direct hospital system agreements with limited independent dealer penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
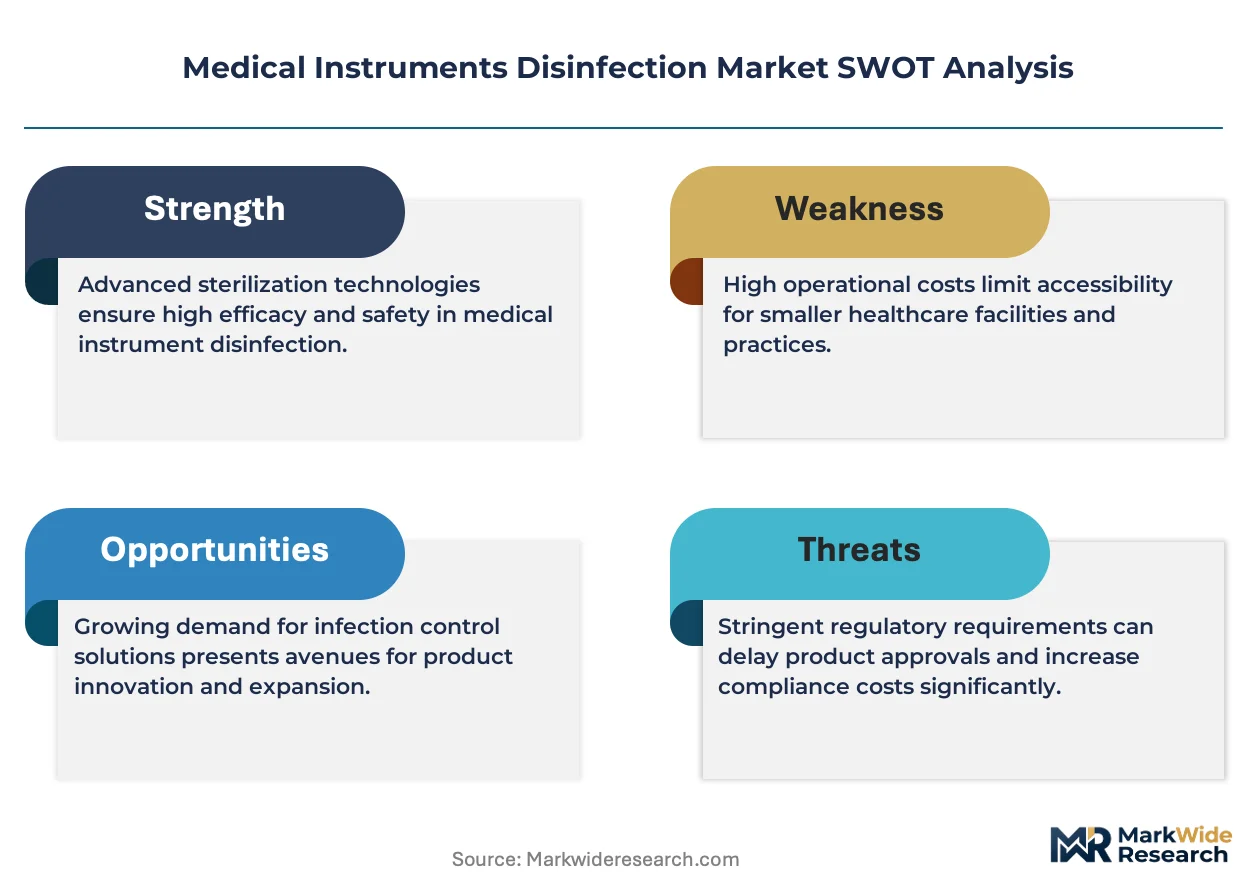
Analyst Recommendations
This market operates as a regulatory compounder where FDA 510(k) pathway refinement and EU MDR Article 10 technical documentation requirements perpetually reset competitive barriers. Compliance investment thresholds escalate faster than organic demand growth, advantaging scaled incumbents with dedicated regulatory affairs infrastructure.
For Market Incumbents: Extend service contract restructuring to capture recurring revenue streams as hospital procurement unbundles capital and maintenance spend. Deepen backward integration into stainless steel alloy supply through captive sourcing arrangements with German and Chinese metal fabricators. Counter emerging UV-C LED platform entrants by accelerating hydrogen peroxide vapor cycle time improvements for heat-sensitive endoscope reprocessing.
For New Entrants and Emerging Players: Enter via critical access hospital networks in rural United States markets where automated reprocessing technology remains underpenetrated and procurement panels lack enterprise asset management integration mandates. Target mid-capacity washer-disinfector segments with simplified operation protocols that reduce biomedical technician certification dependency. Pursue FDA 510(k) pre-submission pathways for rapid-cycle platforms specifically dimensioned for ambulatory surgical center instrument turnover velocity.
For Investors and Strategic Acquirers: Diversified healthcare conglomerates with existing hospital service footprints represent the most active acquirer category in this space. Long-term viability hinges on recurring service revenue attachment rates exceeding equipment replacement cycles. Acquisition target archetype: pure-play sterilization equipment vendors with installed base density in integrated delivery networks but underoptimized service contract pricing. Monitor EPA FIFRA registration renewal timelines for chemical disinfectant formulators as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates premarket notification for automated reprocessing systems targeting ambulatory surgical centers. |
| CE Marking Pathway | EU MDR Article 10 compliance enables washer-disinfector certification for German academic medical center procurement. |
| Hospital System Partnership | Enterprise asset management integration secures long-term vendor panel positioning in fifty-plus facility networks. |
| Software Companion Development | Data-enabled traceability systems replace batch-level recordkeeping with instrument-level digital twins. |
| Reimbursement Strategy | Joint Commission accreditation alignment amplifies documented sterilization quality assurance mandate coverage. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each geography weighted by hospital procurement volume. The analysis combines structured interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and sterilization equipment service technicians with secondary validation from FDA 510(k) filings, EPA FIFRA registration databases, hospital procurement contract repositories, and EU MDR notified body certification records. Bottom-up facility-level equipment installation data triangulates against top-down manufacturer revenue segmentation.
Rate-of-change decomposition separates volume expansion from price mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user facility scale, sterilization technology modality, and clinical application workflow urgency. CAGRs derive from instrument turnover velocity assumptions tied to ambulatory surgical center construction pipelines and central sterile supply department standardization mandates. Industry-specific forecast inputs incorporate FDA premarket notification approval timelines and EU notified body review period extensions for washer-disinfector certifications.
The model holds under steady regulatory enforcement intensity and continued hospital network consolidation; deviation in EPA FIFRA registration suspension events or stainless steel commodity supply disruption would shift equipment availability and pricing trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Lumbar Puncture Trays and Needles Market