
 Forensic Medicine Market | 2026-2036
Forensic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Forensic Medicine Market Foresight
Private investigation firms are unwinding their historical reliance on outsourced laboratory services and building in-house digital forensics capabilities. Thermo Fisher Scientific leverages its mass spectrometry portfolio to anchor high-throughput toxicology screening for coroner offices across North America. QIAGEN sustains leadership in DNA extraction chemistries through backward integration into reagent manufacturing, while Eurofins competes on geographic density with accredited forensic laboratories in twelve countries.
Forensic medicine applies medical and scientific expertise to legal investigations, encompassing postmortem examination, biological evidence analysis, and injury interpretation using standardized protocols such as chain-of-custody documentation and validated analytical thresholds. DNA analysis kits command the largest product segment share due to judicial precedents establishing genetic evidence as admissibility benchmarks, while digital forensics instruments represent the fastest-expanding category as ransomware and financial fraud investigations multiply. Among applications, criminal investigations absorb the majority of procurement budgets, though cybercrime analysis is displacing traditional caseload allocations in metropolitan police departments.
The FBI's Quality Assurance Standards for DNA Testing Laboratories and the EU's Data Protection Regulation constrain how biometric evidence crosses jurisdictional boundaries, directly shaping vendor certification requirements and market access timelines. ISO 17025 accreditation functions as a non-negotiable filter for laboratory equipment suppliers seeking contracts with law enforcement agencies. Stakeholders must monitor whether emerging AI-driven evidence interpretation tools trigger new evidentiary admissibility hearings that could reshape competitive positioning in analytical instrumentation.
Market Dynamics
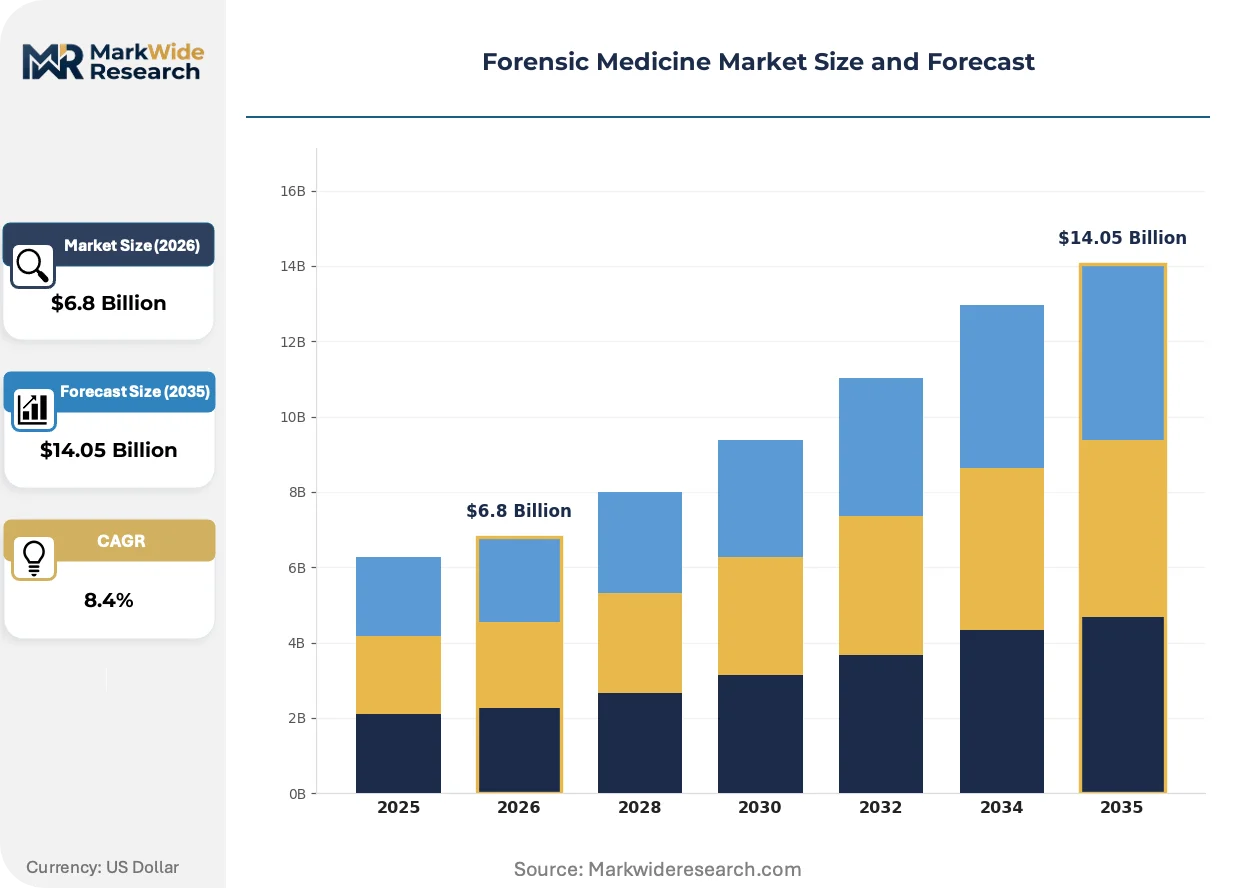
Forensic medicine markets face structural pressure from jurisdictional data-sharing mandates that force standardization upon historically fragmented laboratory procurement. The FBI's CODIS database standards and the EU's Prüm Treaty create compliance cascades requiring equipment vendors to achieve multi-territory certification before contract eligibility.
Growth Catalysts
- Cross-border DNA data protocols:The EU's Prüm Treaty mandates interoperable genetic databases, compelling member-state police forces to upgrade extraction and analysis infrastructure to common technical specifications.
- Private investigation firms:These entities are building in-house digital forensics capabilities, creating direct equipment demand previously captured by outsourced laboratory services.
- Mass spectrometry throughput gains:Coroner offices across North America are replacing chromatography-based toxicology panels with high-resolution mass spec platforms to clear backlogged caseloads.
Market Restraints
- ISO 17025 certification timelines:Equipment suppliers face eighteen-to-twenty-four-month accreditation cycles that delay market entry and freeze procurement decisions.
- Reagent supply concentration:DNA extraction chemistries rely on polymerase enzymes manufactured at three dominant bioproduction facilities, creating single-source vulnerability.
- Judicial admissibility uncertainty:Courts in multiple jurisdictions have excluded AI-generated evidence interpretation, chilling investment in automated analytical tools.
Strategic Opportunities
- Ransomware investigation units:Metropolitan police departments are establishing dedicated cybercrime laboratories requiring mobile digital forensics instrumentation.
- German federal police modernization:Berlin and Munich forensic research clusters are driving kit adoption through university-police partnership programs.
- CE-IVD regulatory pathway:The EU's In Vitro Diagnostic Regulation creates first-mover advantage for manufacturers achieving notified-body certification ahead of enforcement deadlines.
Industry Challenges
- Forensic bioinformatics talent scarcity:Laboratories struggle to hire analysts proficient in both molecular biology and computational pipeline validation.
- Legacy LIMS integration:New instrumentation must interface with decades-old laboratory information management systems, extending deployment timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forensic Medicine Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Analysis Kits, Toxicology Panels, Fingerprint Analysis Tools, Ballistics Equipment, Digital Forensics Instruments Application: Criminal Investigations, Death Investigations, Cybercrime Analysis, Accident Reconstruction, Fraud Detection End User: Law Enforcement Agencies, Legal Firms, Coroner Offices, Research Institutions, Private Investigation Firms Technology: Mass Spectrometry, Chromatography, Next-Generation Sequencing, Imaging Techniques, Chemical Profiling |
| Companies Covered | QIAGEN, Eurofins, Thermo Fisher Scientific, SPEX Forensics, Belkasoft, Agilent Technologies, Bode Cellmark Forensics, LGC Limited, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forensic Medicine Market Shifts & Advancements
Artificial intelligence is penetrating evidence interpretation workflows, forcing vendors to navigate between automation promise and judicial skepticism. Regulatory bodies are drafting evidentiary standards for machine-generated conclusions while laboratories weigh efficiency gains against admissibility risk.
Rapid DNA analysis instrumentation is fragmenting the traditional laboratory value chain. Portable amplification systems now permit booking-station genetic screening within ninety minutes, displacing centralized crime laboratory processing for time-sensitive detention decisions. County sheriff departments in Texas and Florida are deploying these units to comply with statutory detention windows, compressing the addressable market for high-throughput batch systems.
The EU's Data Protection Regulation constrains biometric evidence transfer across member-state borders, reshaping vendor certification requirements. Equipment manufacturers must demonstrate GDPR-compliant data handling architectures to qualify for law enforcement tenders, adding compliance engineering costs that favor established suppliers with dedicated regulatory affairs divisions. German and French procurement offices are enforcing these standards most stringently.
Service unbundling is disrupting traditional reagent rental contracts. Coroner offices and police laboratories are negotiating reagent-only supply agreements while retaining capital equipment ownership, reversing the bundled consumables model that dominated forensic procurement for two decades. This shift is most pronounced in California and New York state facilities with independent purchasing authority.
Forensic Medicine Market Segmentation
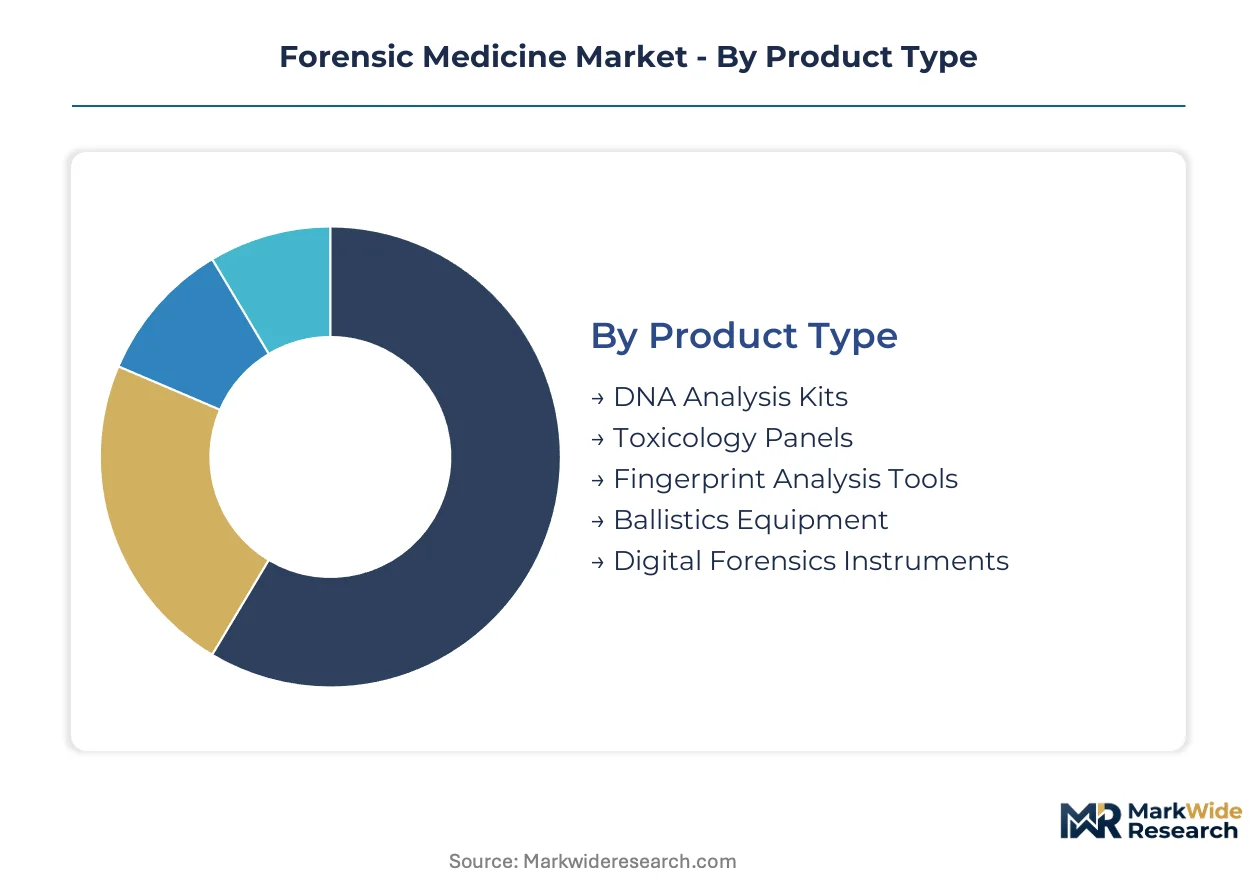
Forensic medicine procurement follows distinct technical and jurisdictional logics that reshape vendor priorities across equipment categories. Laboratories prioritize interoperability certifications over raw performance specifications, while end-user budget authority increasingly fragments between centralized crime labs and decentralized coroner offices.
Product Type:
Margin pools concentrate in consumable-heavy segments where reagent rental contracts and per-test pricing generate recurring revenue streams.
- DNA Analysis Kits:These extraction and amplification chemistries integrate polymerase enzymes, buffer systems, and validated primer sets for CODIS-compatible genetic profiling. German federal police modernization programs and university forensic clusters in Berlin and Munich are driving kit adoption through standardized procurement frameworks. The dominant share belongs to DNA Analysis Kits, while Digital Forensics Instruments is closing the gap fastest.
- Toxicology Panels:Multi-analyte screening arrays detect pharmaceuticals, illicit substances, and environmental toxins in postmortem biological matrices. Coroner offices across North America are replacing chromatography-based workflows with high-resolution mass spec platforms to clear backlogged caseloads.
- Fingerprint Analysis Tools:Automated latent print identification systems deploy optical, capacitive, and chemical visualization methods for tenprint and palm print matching.
- Ballistics Equipment:Integrated comparison microscopes and 3D imaging systems document firearm and toolmark evidence for courtroom presentation.
- Digital Forensics Instruments:Mobile device extraction tools, network packet analyzers, and blockchain tracing software support ransomware and financial fraud investigations.
Reagent rental economics favor consumable-intensive segments, though capital equipment categories command higher upfront contract values.
Application:
Procurement volume skews toward investigative functions with statutory evidence-handling requirements and judicial admissibility thresholds.
- Criminal Investigations:Homicide, sexual assault, and property crime casework consumes the majority of forensic laboratory capacity through DNA, fingerprint, and firearms analysis. Metropolitan police departments in Texas and Florida are deploying rapid DNA instrumentation at booking stations to comply with statutory detention windows.
- Cybercrime Analysis:Ransomware investigation units require mobile digital forensics instrumentation for encrypted device extraction and cryptocurrency tracing. This segment is expanding most quickly as law enforcement establishes dedicated cybercrime laboratories.
- Death Investigations:Postmortem toxicology and pathology services support coroner and medical examiner determinations of cause and manner of death.
- Accident Reconstruction:Biomechanical analysis and vehicular telemetry interpretation inform civil litigation and criminal prosecution of traffic fatalities.
- Fraud Detection:Document examination, signature verification, and financial record analysis support white-collar criminal proceedings.
Criminal Investigations retains the largest budget allocation, though Cybercrime Analysis is capturing incremental funding fastest.
End User:
Budget authority fragmentation is accelerating as independent purchasing power disperses from centralized state laboratories.
- Law Enforcement Agencies:Federal, state, and municipal police forces operate crime laboratories with ISO 17025 accreditation requirements and CODIS database connectivity mandates. The FBI's Quality Assurance Standards constrain equipment procurement to certified vendors with multi-territory compliance documentation.
- Private Investigation Firms:These entities are building in-house digital forensics capabilities, creating direct equipment demand previously captured by outsourced laboratory services.
- Coroner Offices:County-level death investigation facilities prioritize toxicology throughput and rapid toxicant screening for overdose surveillance.
- Legal Firms:Defense attorneys and civil litigators commission independent forensic analysis to challenge prosecution evidence or support tort claims.
- Research Institutions:University forensic science programs in Berlin and Munich maintain research clusters that validate emerging analytical methods and train laboratory personnel.
Law Enforcement Agencies command the dominant procurement volume, while Private Investigation Firms are expanding equipment ownership most aggressively.
Technology:
Platform selection hinges on validation burden versus analytical throughput tradeoffs in accredited laboratory environments.
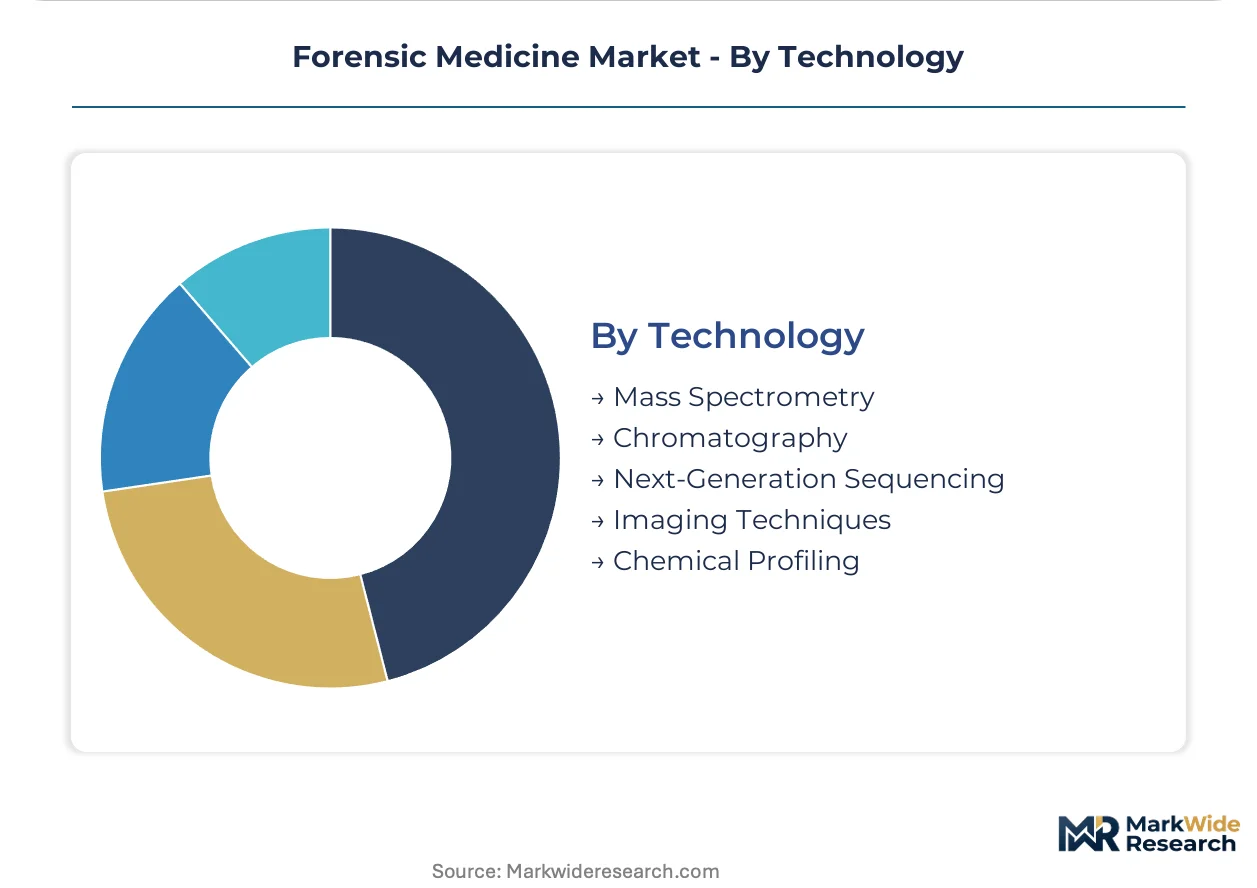
- Mass Spectrometry:High-resolution accurate mass platforms enable untargeted toxicological screening with retrospective data mining capabilities. These systems are displacing chromatography-based panels in coroner offices seeking to clear backlogged caseloads.
- Next-Generation Sequencing:Massively parallel DNA analysis generates full genomic profiles for complex mixture deconvolution and investigative genetic genealogy. The EU's Data Protection Regulation constrains biometric evidence transfer across member-state borders, reshaping vendor certification requirements for GDPR-compliant data handling architectures.
- Chromatography:Gas and liquid chromatography systems remain foundational for targeted toxicology and controlled substance identification.
- Imaging Techniques:Digital radiography, CT scanning, and 3D surface documentation support virtual autopsy and wound pattern analysis.
- Chemical Profiling:Spectroscopic and spectrometric methods characterize trace evidence including fibers, paints, and explosive residues.
Mass Spectrometry anchors the largest installed base, while Next-Generation Sequencing is climbing the fastest as forensic genetic genealogy expands casework applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FBI's CODIS database infrastructure underwrites the United States' central role in forensic medicine standardization, while Germany's federal police modernization programs and the EU's Prüm Treaty data-sharing architecture anchor European demand concentration.
United States
County sheriff departments in Texas and Florida deploy rapid DNA instrumentation at booking stations to comply with statutory detention windows. The FBI's Quality Assurance Standards for DNA Testing Laboratories constrain equipment procurement to certified vendors with multi-territory compliance documentation. Greater Boston and the Pacific Northwest host university forensic research clusters that validate emerging analytical methods and train laboratory personnel.
Germany
Federal police modernization programs and university forensic research clusters in Berlin and Munich are driving kit adoption through standardized procurement frameworks. The EU's Prüm Treaty mandates interoperable genetic databases, compelling member-state police forces to upgrade extraction and analysis infrastructure to common technical specifications. Bavaria's forensic laboratories anchor toxicology panel volumes through partnership programs with Munich research institutions.
United Kingdom
Metropolitan police departments are establishing dedicated cybercrime laboratories requiring mobile digital forensics instrumentation for ransomware investigations. The EU's Data Protection Regulation constrains biometric evidence transfer across member-state borders, reshaping vendor certification requirements for GDPR-compliant data handling architectures. London and the Southeast concentrate private investigation firms building in-house digital forensics capabilities.
France
Procurement offices in Paris enforce GDPR-compliant data handling standards most stringently, adding compliance engineering costs that favor established suppliers with dedicated regulatory affairs divisions. The EU's In Vitro Diagnostic Regulation creates first-mover advantage for manufacturers achieving notified-body certification ahead of enforcement deadlines. Île-de-France hosts coroner offices replacing chromatography-based toxicology panels with high-resolution mass spec platforms.
Canada
Health Canada and the PMRA regulate forensic toxicology standards for coroner offices prioritizing overdose surveillance through rapid toxicant screening. Ontario's provincial crime laboratories maintain ISO 17025 accreditation requirements that function as non-negotiable filters for equipment suppliers seeking law enforcement contracts. Toronto and Vancouver anchor digital forensics demand from private investigation firms unwinding outsourced laboratory dependencies.
Forensic Medicine Market Competitive Landscape
Listed leaders compete with private specialists across certification and geographic coverage dimensions. The vendor base separates into three tiers: diversified life science conglomerates with mass spectrometry portfolios, forensic-focused laboratories competing on geographic density, and digital forensics specialists serving private investigation demand. Strategic archetypes include consumables-heavy reintegrators, service-unbundling laboratories, and rapid-deployment instrumentation developers. Competitive moves concentrate on backward integration into reagent manufacturing and multi-territory accreditation achievement.
Among diversified conglomerates, Thermo Fisher Scientific and QIAGEN exemplify contrasting approaches to consumable intensity and backward integration into reagent manufacturing. Eurofins occupies a position as a geographic density specialist with accredited forensic laboratories spanning multiple European jurisdictions. Agilent Technologies sits within the analytical instrumentation tier serving coroner office toxicology modernization programs across North America.
| Leading Market Players |
|---|
| QIAGEN |
| Eurofins |
| Thermo Fisher Scientific |
| SPEX Forensics |
| Belkasoft |
| Agilent Technologies |
| Bode Cellmark Forensics |
| LGC Limited |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month ISO 17025 accreditation cycles concentrate supply-side leverage among established vendors with dedicated regulatory affairs divisions, compressing pricing power for new entrants while amplifying margin capture for incumbents with multi-territory certification documentation. This lead-time band directly shapes how procurement offices in Germany and France weight total cost of ownership against sticker price, privileging suppliers with proven compliance engineering capabilities over low-bid alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CODIS-certified DNA analysis systems from CE-IVD compliant mid-tier platforms and uncertified research-grade instrumentation. Price differentiation hinges on ISO 17025 documentation depth and FBI Quality Assurance Standards compliance tier, with German federal police modernization programs demonstrating lowest price sensitivity due to statutory interoperability mandates. Cost compression in the economy tier is intensifying because county coroner offices with independent purchasing authority are negotiating reagent-only supply agreements, reversing bundled consumables models. Metropolitan police departments in Texas and Florida show highest price sensitivity as rapid DNA instrumentation procurement competes with general operational budgets.
Supply Chain Analysis
Container availability constraints on trans-Atlantic trade lanes elevate inbound logistics costs for polymerase enzymes manufactured at bioproduction facilities concentrated in the United States, Germany, and Singapore. DNA extraction chemistries rest on polymerase enzymes, validated primer sets, and high-purity buffer systems, with reagent manufacturing backward integration determining supplier resilience. Single-source vulnerability at three dominant bioproduction facilities constitutes the primary structural risk, amplified by EU Data Protection Regulation constraints on cross-border reagent shipments. Distribution runs through direct vendor-laboratory contracts for capital equipment, while consumables flow via specialized forensic supply distributors with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The forensic medicine market sits at a platform-economics inflection where the EU's Prüm Treaty data-sharing architecture and FBI CODIS interoperability standards are consolidating procurement around ecosystem-compatible vendors, privileging suppliers with multi-territory certification documentation over point-solution specialists.
For Market Incumbents: Secure multi-territory ISO 17025 accreditation ahead of EU In Vitro Diagnostic Regulation enforcement deadlines to lock in German federal police modernization contracts, while acquiring digital forensics capabilities to counter private investigation firms building in-house expertise. Backward integration into polymerase enzyme manufacturing hedges single-source supply risk and defends margin position against reagent-only procurement trends. For New Entrants and Emerging Players: CE-IVD notified-body certification fast-track offers the most penetrable entry path for rapid DNA analysis instrumentation targeting county sheriff departments in Texas and Florida with statutory detention compliance needs. Cybercrime analysis laboratories in metropolitan police departments present white-space demand for mobile digital forensics tools, with ransomware investigation units prioritizing speed of deployment over established vendor relationships. Go-to-market through university forensic research clusters in Berlin and Munich validates performance claims for downstream law enforcement procurement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because ISO 17025 accreditation timelines and multi-jurisdictional compliance engineering create durable barriers to entry that concentrate value capture among established suppliers. Acquisition targets should display forensic bioinformatics talent pipelines bridging molecular biology and computational pipeline validation, with installed base expansion potential in coroner office toxicology modernization. The signal to watch is judicial admissibility hearings for AI-driven evidence interpretation tools, which could reshape competitive positioning in analytical instrumentation if courts establish precedent for machine-generated conclusions.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Territory ISO 17025 Accreditation | Unlocks FBI CODIS database connectivity and EU Prüm Treaty procurement eligibility simultaneously. |
| Backward Integration into Reagent Manufacturing | Captures recurring revenue streams and insulates against polymerase enzyme supply concentration. |
| Digital Forensics Capability Acquisition | Addresses displacement threat from private investigation firms building in-house expertise. |
| Rapid DNA Instrumentation Development | Targets statutory detention window compliance in Texas and Florida booking stations. |
| University Research Cluster Partnership | Validates emerging methods through Berlin and Munich forensic science programs for downstream adoption. |
Research Methodology
A spread of perspectives from forensic laboratory directors, law enforcement procurement officers, coroner office administrators, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork with these stakeholders combined with secondary validation against FBI Quality Assurance Standards documentation, EU Prüm Treaty technical specifications, ISO 17025 accreditation body records, and customs data on forensic equipment trade flows. Bottom-up instrumentation shipment tracking and top-down law enforcement budget appropriation analysis triangulated market sizing.
Segmentation dimensions modeled span product type, application, end user, technology platform, and regional regulatory cluster across the projection horizon. CAGRs derive from weighted probability scenarios incorporating accreditation timeline delays, judicial admissibility rulings on AI-generated evidence, and reagent supply disruption frequencies. Forensic genetic genealogy expansion rates and ransomware investigation unit establishment paces serve as industry-specific demand inputs.
Decision-makers should treat outputs as directional under assumptions of sustained Prüm Treaty enforcement and stable FBI CODIS infrastructure investment; material deviation would warrant model refresh. Specific risks that could revise forecasts include judicial exclusion of AI-driven interpretation tools, polymerase enzyme manufacturing facility disruptions, or GDPR enforcement variations affecting cross-border biometric data transfer. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Metabolomics Market
Medical Research
Placenta Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Epigenetics Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Clinical Genomics Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Cancer Mouse Models Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
North America Biobanks Market
Medical Research
Precision Medicine Market