
 Casting and Splints Market | 2026-2036
Casting and Splints Market Size, Share, and Industry Trends Forecast 2026-2036
Casting and Splints Market Outlook
China is narrowing its dependence on imported orthopedic consumables through domestic manufacturing expansion for casting and splinting materials. Stryker Corporation leverages its integrated trauma portfolio to sustain hospital supply contracts across North America and Europe. BSN Medical GmbH anchors its position through specialized plaster and synthetic cast formulations that dominate European clinical procurement channels.
Casting and splints comprise rigid or semi-rigid external immobilization systems fabricated from plaster of Paris, fiberglass, thermoplastic resins, or aluminum, designed to stabilize bone fractures, soft tissue injuries, or post-operative sites by restricting movement and distributing mechanical load. Synthetic casts manufactured from polyurethane-impregnated fiberglass now lead product type volumes due to their water resistance and radiolucency, while splinting materials represent the fastest-expanding category as emergency departments prioritize adjustable, removable stabilization for acute injuries. Home care end users are capturing growing margin pools as remote patient monitoring and telehealth protocols extend post-acute recovery outside institutional settings.
The FDA enforces Class I and Class II medical device controls over casting materials, while the EU MDR mandates clinical evidence and post-market surveillance for orthopedic immobilization products entering European distribution channels. ISO 13485 certification shapes supplier qualification for direct sales to hospital systems, creating compliance barriers for unqualified manufacturers. Stakeholders must monitor evolving biodegradability mandates and reimbursement shifts toward outpatient fracture management as determinants of portfolio prioritization and channel investment.
Market Dynamics
The Casting and Splints Market pivots on a fundamental tension between legacy plaster formulations and synthetic immobilization systems. Hospital procurement committees now mandate water-resistant, radiolucent alternatives that reduce cast change frequency and enable MRI compatibility without removal.
Growth Catalysts
- EU MDR Biocompatibility Mandates:Stricter clinical evidence requirements for orthopedic immobilization devices accelerate hospital adoption of pre-certified synthetic materials over unverified imports.
- Polyurethane-Impregnated Fiberglass:Emergency departments prioritize this material for its superior strength-to-weight ratio and patient comfort during extended wear periods.
- Japan's Aging Demographics:Fracture treatment volumes in metropolitan Tokyo and Osaka trauma networks drive consistent demand for adjustable splinting systems in geriatric care pathways.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic cast production depends on polyurethane and fiberglass resin inputs whose pricing fluctuates with crude oil indices.
- Plaster of Paris Cost Advantage:Traditional materials retain dominance in price-sensitive institutional procurement channels across developing healthcare systems.
- FDA Class II Device Controls:Premarket notification requirements for novel immobilization materials extend commercialization timelines by 12-18 months.
Strategic Opportunities
- Home Care Channel Expansion:Telehealth protocols for post-fracture monitoring create direct-to-patient distribution pathways for removable splint systems.
- India's Domestic Manufacturing Push:Local production incentives under PLI schemes reduce import dependence for orthopedic consumables in tier-2 hospital networks.
- Biodegradable Thermoplastic Resins:Convergence of sustainable material science and immobilization engineering opens premium positioning in environmentally certified procurement frameworks.
Industry Challenges
- ISO 13485 Certification Bottlenecks:Quality management system audits for medical device suppliers create 6-9 month qualification delays for contract manufacturing partnerships.
- Legacy Cast Removal Equipment Integration:Electric cast saws and vacuum systems in established trauma centers require retrofitting to accommodate newer synthetic material densities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casting and Splints Market |
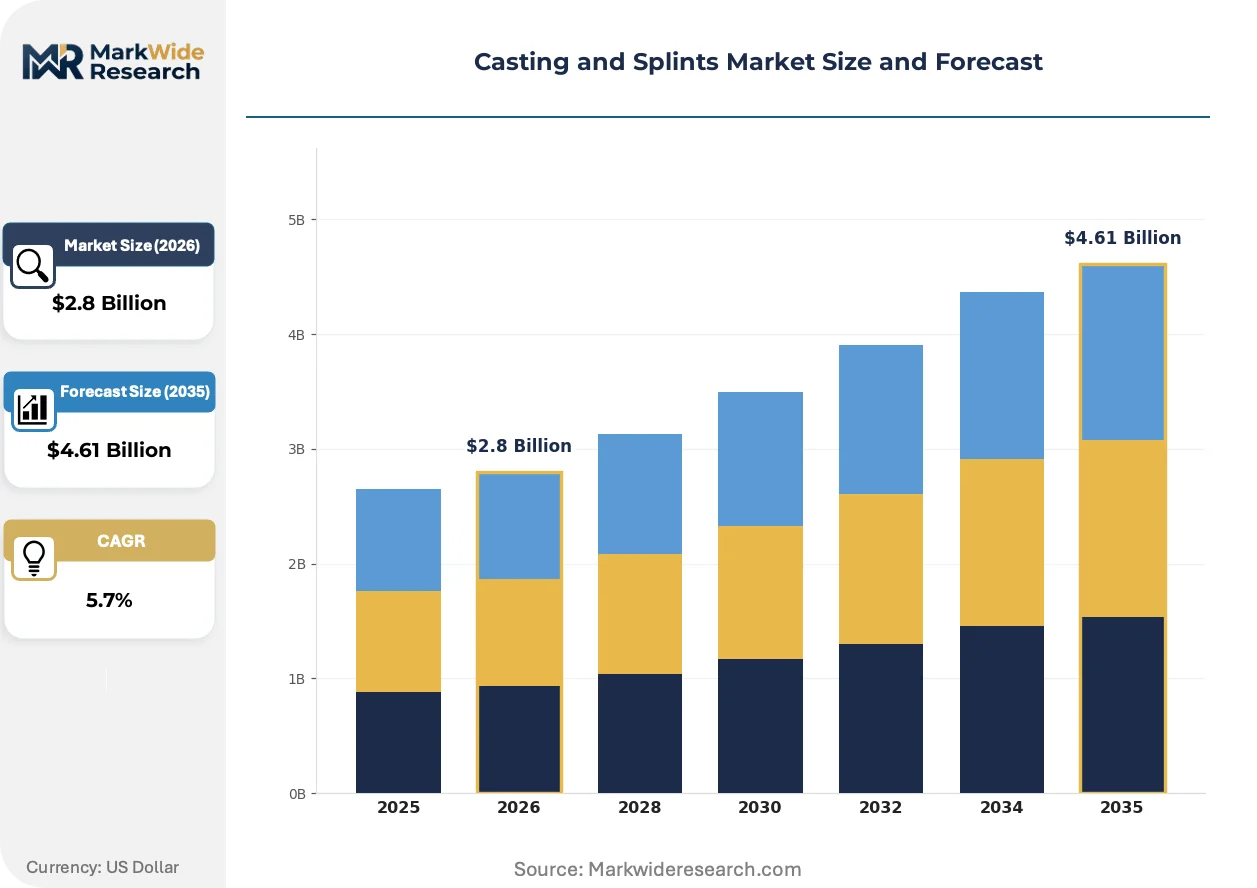
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plaster Casts, Synthetic Casts, Splinting Materials, Orthopedic Devices Therapy Area: Fractures, Sports Injuries, Post-Surgery, Chronic Pain Management End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Distribution Channel: Direct Sales, Medical Distributors, Online Retail, Pharmacies |
| Companies Covered | Stryker Corporation, 3M Healthcare, BSN Medical GmbH, Zimmer Biomet Holdings Inc., Prime Medical Inc., DeRoyal Industries, AliMed, Össur, Bird & Cronin Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casting and Splints Market Strategic Shifts
Material science advances and regulatory harmonization are compressing product lifecycles across immobilization device categories. Stakeholders must align R&D roadmaps with evolving clinical evidence standards and sustainability mandates.
Polyurethane-impregnated fiberglass is migrating from trauma center emergency departments to outpatient orthopedic clinics and sports medicine practices. Ambulatory surgery centers adopt these systems for same-day fracture stabilization procedures. The technology is migrating from acute care settings toward community-based fracture management, compressing traditional hospital admission volumes for minor bone injuries.
REACH substance restrictions and EU MDR post-market surveillance requirements force reformulation of legacy casting materials containing phthalate plasticizers. Manufacturers must submit clinical performance data for existing product lines to maintain CE marking. Synthetic cast suppliers with pre-validated biocompatibility dossiers capture procurement share in German, French, and Dutch hospital systems.
Hospital supply chain managers now unbundle after-sales cast removal services from material purchase contracts, selecting third-party equipment vendors independently. This purchasing pattern disrupts traditional full-service agreements between cast manufacturers and trauma departments. The shift concentrates in United States integrated delivery networks and United Kingdom National Health Service trust procurement frameworks.
Casting and Splints Market Segmentation
Casting and splinting technologies serve divergent clinical workflows across emergency stabilization, surgical recovery, and chronic condition management. Understanding how product specifications align with therapy intensity and care setting economics enables precise portfolio positioning against reimbursement and procurement constraints.
Product Type:
Material composition dictates water resistance, radiolucency, and removal mechanics across the clinical use-case spectrum from acute trauma to pediatric applications.
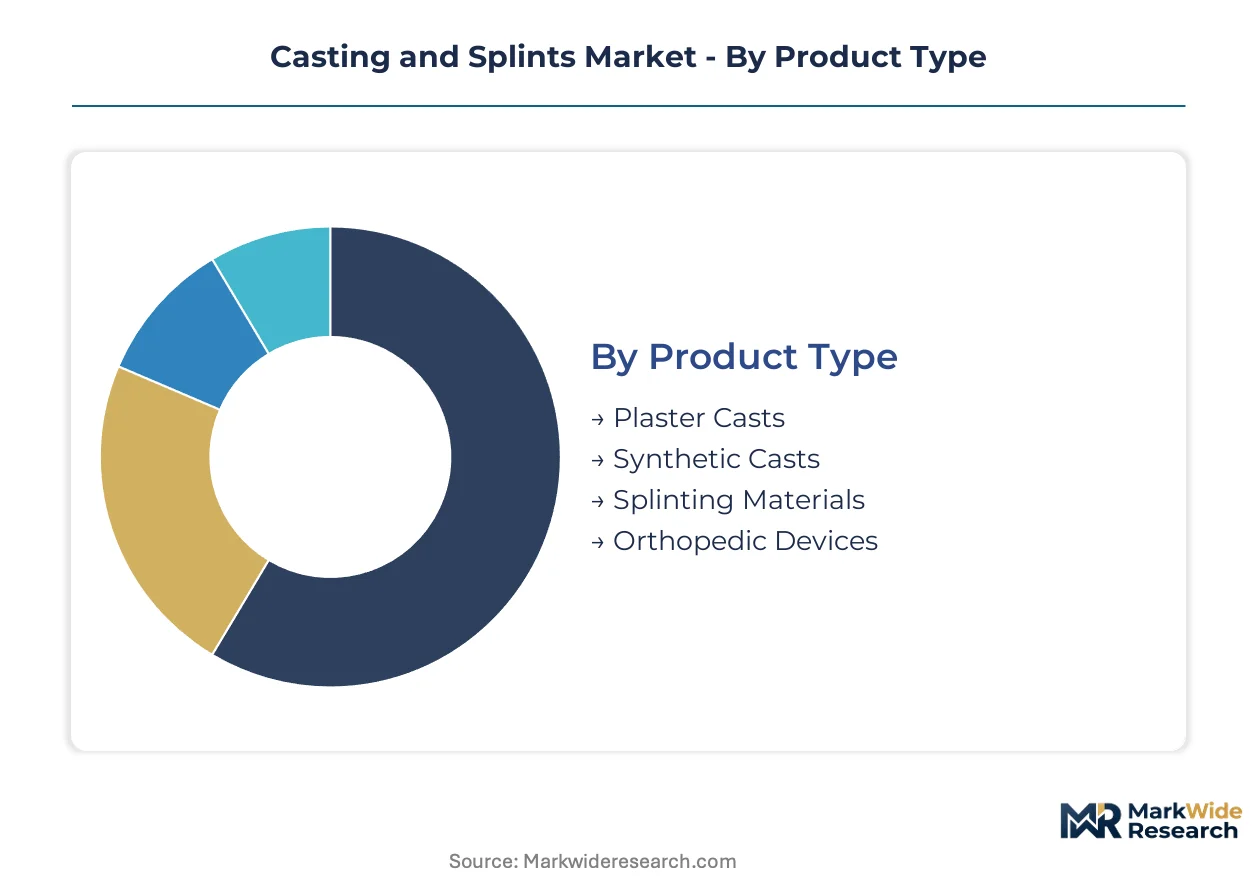
- Synthetic Casts:Polyurethane-impregnated fiberglass systems deliver superior strength-to-weight ratios and MRI compatibility without removal. Hospital procurement committees in Germany and the United States now mandate these specifications for emergency department contracts.
- Splinting Materials:Thermoplastic and aluminum-based adjustable systems enable removable stabilization for acute soft tissue injuries. Emergency departments in Japan's metropolitan trauma networks prioritize these for geriatric fracture protocols where cast changes complicate recovery.
- Plaster Casts:Traditional plaster of Paris formulations retain cost advantages in price-sensitive procurement channels across India's tier-2 hospital networks and other developing healthcare systems.
- Orthopedic Devices:Specialized immobilization hardware including traction systems and external fixation interfaces serve complex multi-trauma cases in Level I trauma centers.
The dominant share belongs to Synthetic Casts, while Splinting Materials is closing the gap fastest.
Therapy Area:
Clinical indication intensity shapes reimbursement coding and material durability requirements across institutional and home-based recovery pathways.
- Fractures:Acute bone stabilization demands rigid immobilization systems with load-bearing specifications calibrated to anatomical site and patient weight. Trauma centers in the United States and Japan drive volume concentration for long-arm and long-leg cast configurations.
- Sports Injuries:Athletic trauma protocols prioritize lightweight, removable splinting for rapid return-to-play assessment. Sports medicine clinics in Germany and Australia represent high-margin demand for premium synthetic materials.
- Post-Surgery:Orthopedic procedure follow-up requires graduated immobilization transitioning from rigid casts to adjustable splints during rehabilitation phases.
- Chronic Pain Management:Long-term neuromuscular stabilization employs custom-molded thermoplastic orthoses for degenerative conditions in aging populations.
Fracture treatment commands the largest volume position, though Sports Injuries delivers the steepest expansion trajectory among therapy categories.
End User:
Care setting economics determine whether procurement prioritizes capital equipment integration, disposable material turnover, or direct-to-patient distribution models.
- Hospitals:Integrated trauma centers and orthopedic departments negotiate enterprise contracts bundling cast materials with removal equipment and staff training. These institutions in the United States, Germany, and Japan anchor procurement volume for premium synthetic systems.
- Home Care:Telehealth-enabled post-fracture monitoring extends recovery outside institutional settings, creating direct-to-patient channels for removable splint systems and self-application kits.
- Rehabilitation Centers:Post-acute facilities manage cast-to-splint transitions and custom orthotic fitting for complex recovery pathways.
- Clinics:Ambulatory surgery centers and urgent care networks perform same-day fracture stabilization with compressed material inventories.
Hospitals retain the core revenue base, while Home Care is accelerating most quickly as remote patient monitoring protocols mature.
Distribution Channel:
Channel structure reflects whether procurement authority rests with hospital supply chain managers, specialized medical distributors, or individual patient purchasing decisions.
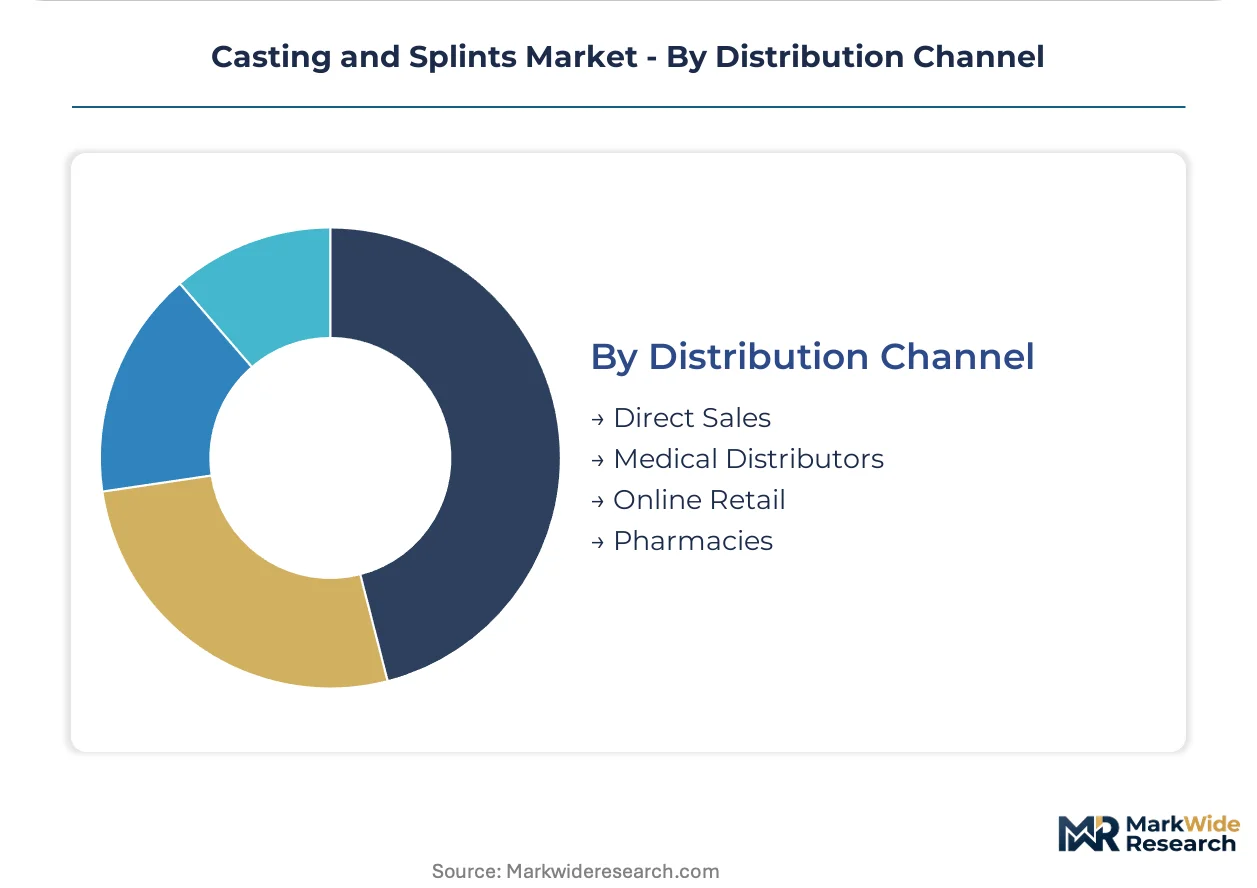
- Direct Sales:Manufacturers maintain dedicated contract teams for integrated delivery networks and national health systems, securing multi-year supply agreements with price-volume commitments. This channel dominates in the United States and United Kingdom procurement frameworks.
- Medical Distributors:Regional wholesalers stock broad orthopedic consumable portfolios for mid-sized hospital systems and independent clinics across European and Asia-Pacific markets.
- Online Retail:E-commerce platforms serve home care patients and small-practice clinicians with standardized splinting kits and replacement supplies.
- Pharmacies:Community pharmacy chains in select European markets dispense basic splinting materials for minor injury self-management.
Direct Sales holds the dominant procurement share, though Online Retail is expanding most quickly as patient-directed purchasing grows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for synthetic casting materials concentrates in industrial clusters across Germany, the United States, and Japan, where integrated chemical processing and medical device fabrication capabilities coexist. Hospital procurement networks in these markets enforce stringent biocompatibility standards that filter supplier access. Emerging production bases in China and India are capturing domestic volume through localized resin compounding and thermoplastic molding investments.
United States
Integrated delivery networks in Texas, Florida, and California drive enterprise contracting for water-resistant synthetic systems. FDA Class II device controls extend commercialization timelines for novel immobilization materials entering distribution. The Minneapolis-St. Paul corridor anchors Midwestern supply chain coordination for hospital system procurement.
Germany
EU MDR clinical evidence requirements accelerate hospital adoption of pre-certified polyurethane-impregnated fiberglass over unverified imports. REACH substance restrictions force reformulation of legacy casting materials containing phthalate plasticizers. The Rhine-Ruhr industrial cluster concentrates resin manufacturing and medical device finishing operations for European distribution.
Japan
Metropolitan Tokyo and Osaka trauma networks generate consistent demand for adjustable splinting systems in geriatric fracture protocols. PMDA post-market surveillance mandates shape supplier qualification for orthopedic immobilization products. The Kansai region hosts specialized thermoplastic processing facilities serving domestic hospital procurement channels.
China
Domestic manufacturing expansion narrows import dependence for casting and splinting materials in tier-2 hospital networks. NMPA medical device registration requirements create compliance barriers for unqualified foreign manufacturers. The Yangtze River Delta cluster concentrates polymer compounding and disposable medical supply production.
India
Local production incentives under PLI schemes reduce procurement costs for orthopedic consumables in government hospital systems. CDSCO medical device rules enforce quality management system standards for domestic and imported suppliers. The Maharashtra-Gujarat industrial corridor anchors thermoplastic resin molding and medical consumable fabrication capacity.
Casting and Splints Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin formulation and substrate fabrication. The vendor base organizes around three archetypes: diversified medical technology conglomerates with trauma portfolios, specialized orthopedic consumable manufacturers with regional distribution depth, and chemical processors supplying raw materials to finished goods fabricators. Consolidation pressures concentrate among mid-scale European specialists seeking geographic scale, while capacity expansion dominates Asian market entries.
Among diversified medical technology conglomerates, Stryker Corporation and Zimmer Biomet Holdings Inc. exemplify platform integrators with integrated trauma portfolios sustaining hospital supply contracts. BSN Medical GmbH occupies a position within the specialized orthopedic consumable tier, anchoring European clinical procurement channels through plaster and synthetic cast formulation expertise. These three entities represent distinct competitive archetypes: the full-system vendor, the orthopedic-focused specialist, and the regional formulation leader.
| Leading Market Players |
|---|
| Stryker Corporation |
| 3M Healthcare |
| BSN Medical GmbH |
| Zimmer Biomet Holdings Inc. |
| Prime Medical Inc. |
| DeRoyal Industries |
| AliMed |
| Össur |
| Bird & Cronin Inc. |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape across synthetic cast manufacturing, compressing margins for polyurethane-impregnated fiberglass producers while forcing hospital procurement committees toward longer-term volume commitments with pre-qualified suppliers.
Pricing Analysis
FDA Class II device controls dictate the pricing tier structure across the United States market, separating premium synthetic systems with premarket notification clearance from standard-grade alternatives lacking radiolucency certification. Price differentiation centers on biocompatibility dossier completeness and ISO 13485 quality management tier, with German and Japanese hospital systems commanding the least price sensitivity due to bundled procurement frameworks. Cost compression in economy-tier plaster formulations is intensifying because India's domestic manufacturing expansion under PLI schemes floods tier-2 hospital networks with localized supply. Developing healthcare systems in South Asia and Southeast Asia exhibit the highest price sensitivity, driving volume concentration toward traditional plaster of Paris despite inferior clinical performance.
Supply Chain Analysis
Contract manufacturing for synthetic casting materials concentrates among specialized medical device fabricators in Germany's Rhine-Ruhr industrial cluster and thermoplastic processors in Japan's Kansai region, with limited qualified capacity expansion in China's Yangtze River Delta. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks for polyurethane resin, Chinese fiberglass substrate production, and Indian aluminum smelting for splinting hardware. Single-source vulnerability concentrates in European resin compounding, where REACH substance restrictions on phthalate plasticizers have eliminated multiple legacy suppliers without replacement qualification. Distribution runs through direct sales teams for integrated delivery networks in North America, regional medical distributors across Europe, and third-party logistics providers serving Asia-Pacific hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Casting and Splints Market sits in early-cycle expansion as telehealth-enabled home care protocols extend fracture recovery outside institutional settings, creating direct-to-patient distribution pathways that bypass traditional hospital supply contracts.
For Market Incumbents: Insulate enterprise supply relationships through backward integration into polyurethane resin compounding and captive certification investment for EU MDR clinical evidence requirements. Synthetic cast manufacturers must lock multi-year price-volume agreements with United States integrated delivery networks before India's PLI-subsidized entrants achieve ISO 13485 qualification and bid for hospital procurement share. For New Entrants and Emerging Players: India's tier-2 hospital networks present the most penetrable white-space target, where government procurement tenders favor domestic manufacturers with CDSCO registration over established European suppliers lacking local production. New entrants should anchor initial positioning through biodegradable thermoplastic resin formulations that satisfy emerging sustainability mandates in German and Dutch hospital systems, then leverage that certification for premium positioning in adjacent European markets. For Investors and Strategic Acquirers: EU MDR post-market surveillance mandates reshape the acquisition landscape toward targets with pre-validated biocompatibility dossiers and established CE marking pathways, as clinical evidence gaps now require 18-24 month remediation timelines that destroy near-term revenue viability. Acquisition candidates should demonstrate specialized orthopedic consumable expertise with regional distribution depth rather than diversified medical technology conglomerate complexity. The signal to watch is hospital procurement committee unbundling of cast removal equipment from material purchase contracts, which concentrates margin capture with third-party equipment vendors and fragments supplier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Pre-validated biocompatibility dossiers secure German hospital procurement share against unverified imports. |
| Biodegradable Thermoplastic Resin Development | Sustainable material science convergence opens premium positioning in environmentally certified Dutch procurement frameworks. |
| Home Care Direct-to-Patient Distribution | Telehealth protocol integration captures margin pools from remote fracture monitoring outside institutional settings. |
| India PLI Manufacturing Scale-Up | Localized resin compounding reduces import dependence for tier-2 hospital network government tenders. |
| Hospital System Partnership Expansion | Enterprise contracting with United States integrated delivery networks locks multi-year synthetic cast volume commitments. |
Study Parameters
The analysis maps synthetic cast formulation, splinting material fabrication, plaster of Paris production, and orthopedic device assembly, each validated through trauma center procurement managers, hospital biomedical engineers, GPO contracts specialists, and regulatory affairs leads at medical device manufacturers. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and customs trade data for orthopedic consumable imports. Bottom-up volume estimates from product-type segmentation triangulated against top-down market sizing from national health expenditure databases and fracture treatment epidemiology.
The analytical framework held constant regulatory enforcement intensity and reimbursement coding stability across the projection horizon, while varying raw material cost indices and domestic manufacturing incentive penetration by geography. Segmentation dimensions modeled include material composition grade, clinical indication intensity, care setting economics, and distribution channel structure. CAGRs derived from weighted average of historical volume trajectories and forward-looking adoption curves for synthetic material substitution, with specific inputs from aging demographic fracture incidence projections and telehealth protocol diffusion rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-subsidized resin compounders or accelerated biodegradable material adoption by European hospital systems would shift outcomes beyond modeled ranges. Quarterly review of EU MDR certification timelines, India PLI scheme disbursement rates, and United States hospital procurement unbundling indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Plastic Syringes Market