
 Cast Polypropylene (CPP) Films Market | 2026-2036
Cast Polypropylene (CPP) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Polypropylene (CPP) Films Market Analysis
Software-defined barrier tuning is broadening what converters purchase, shifting contracts from commodity roll volumes to performance-guaranteed specifications. Profol GmbH leverages coextrusion depth to sustain premium positioning in medical-grade films. Mitsui Chemicals Tohcello anchors Asian supply through integrated resin-to-film operations. Uflex Limited competes on cost-optimized metallized variants for emerging-market snack brands.
Cast polypropylene films are thermoplastic sheets produced by extruding molten polypropylene through a flat die onto a chilled roll, yielding gauges from below 20 microns to above 40 microns with controlled crystallinity and heat-seal latitude. These films serve primarily as printable, heat-sealable layers in laminated flexible packaging where moisture barrier and optical clarity govern shelf appeal. Transparent films dominate volume but face margin compression from commoditization, while barrier films command premium positioning as brands convert to mono-material structures for recyclability. Metallized films occupy the fastest-expanding niche, driven by oxygen and light protection needs in retort and extended-shelf-life applications.
REACH registration requirements in Europe and FDA food-contact regulations in the United States constrain additive formulations and migration limits, pushing producers toward certified raw material streams. China's GB standards and SAMR food packaging directives enforce thickness tolerances and solvent residue thresholds that filter smaller extrusion houses from certified supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional compliance investments or strategic partnerships with locally certified converters.
Market Dynamics
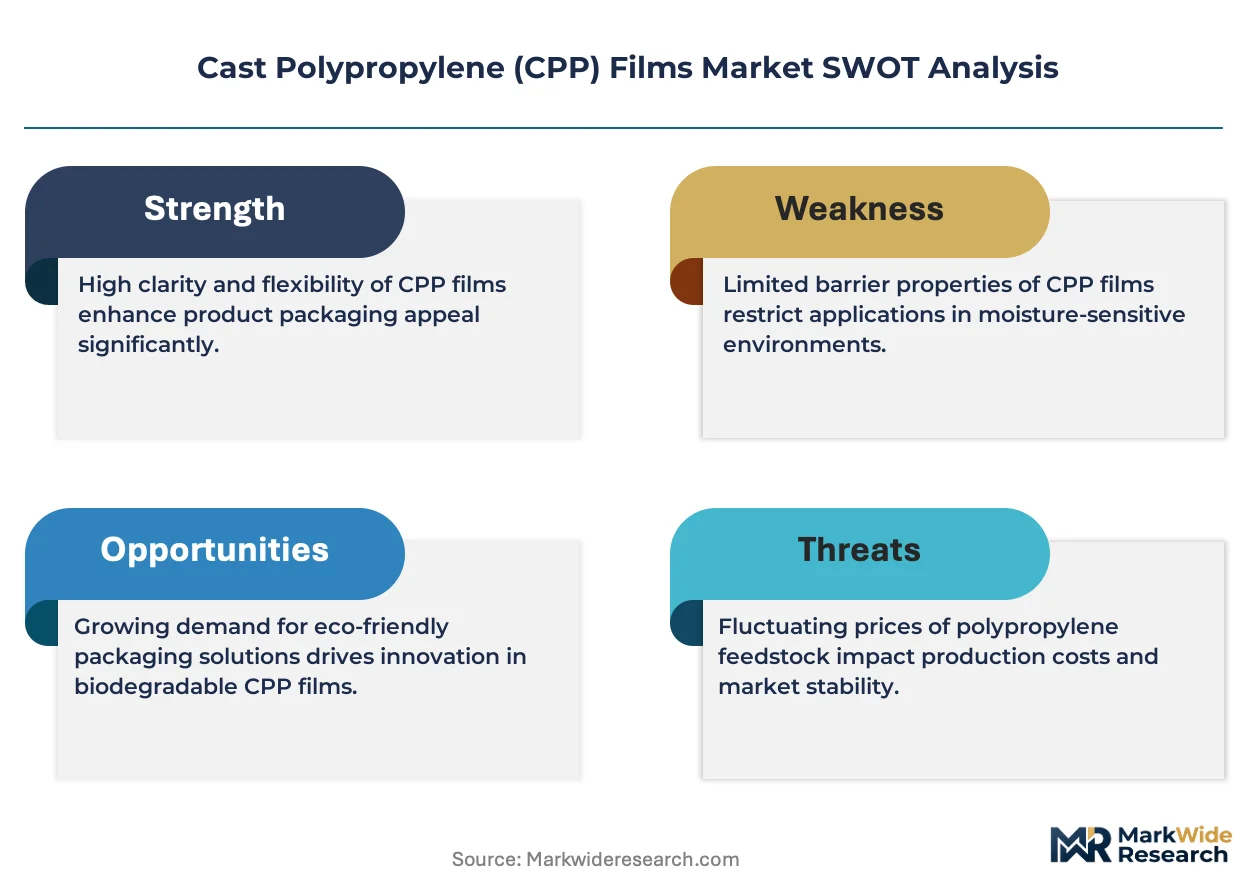
Modified atmosphere packaging specifications are pulling converters away from commodity roll contracts toward performance-guaranteed supply agreements that specify oxygen transmission rates and seal integrity thresholds.
Growth Catalysts
- EU Green Deal compliance:REACH registration deadlines are accelerating mono-material laminate adoption across European food brands seeking recyclable flexible packaging structures.
- Retort pouch expansion:Metallized CPP films are capturing extended-shelf-life applications previously served by aluminum foil laminates in Asian ready-meal segments.
- China domestic output scaling:SAMR-certified extrusion capacity in Zhejiang and Guangdong provinces is displacing import dependency for snack packaging converters.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in Middle Eastern petrochemical complexes transmit directly to CPP resin pricing.
- Barrier coating substitution:Ethylene vinyl alcohol copolymers and silicon oxide depositions are capturing oxygen-barrier specifications in premium pharmaceutical blister packs.
- Thickness tolerance enforcement:China's GB/T 10003 standard filters sub-scale extruders from certified pharmaceutical supply chains.
Strategic Opportunities
- India FSSAI harmonization:Food-contact migration testing alignment with EU standards is opening export pathways for domestic flexible packaging converters.
- Digital printing substrate demand:Corona-treated high-clarity CPP grades are capturing short-run flexible packaging workflows from rotogravure.
- Extended producer responsibility frameworks:Germany's VerpackG and France's AGEC law are mandating mono-material designs that favor heat-sealable PP structures.
Industry Challenges
- Coextrusion die engineering scarcity:Five-layer manifold design expertise concentrates among a narrow cohort of European and Japanese equipment specialists.
- Migration testing timeline compression:FDA food-contact notification cycles and EFSA re-evaluations are extending new additive qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Polypropylene (CPP) Films Market |
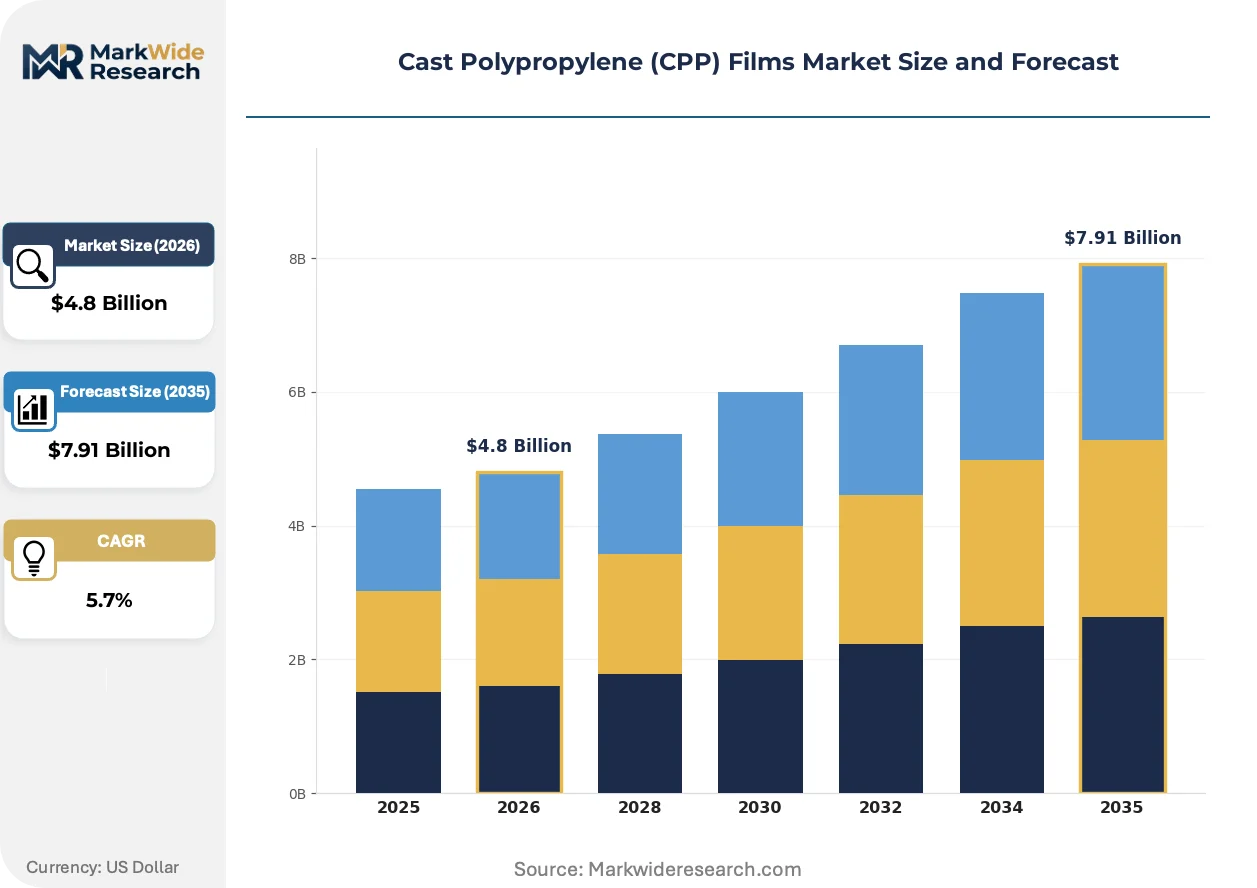
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Metallized Films, Coated Films, Barrier Films End User: Food Packaging, Medical Packaging, Consumer Goods, Industrial Applications Thickness: Below 20 Microns, 20-30 Microns, 30-40 Microns, Above 40 Microns Application: Wraps, Bags, Labels, Overwraps |
| Companies Covered | Profol GmbH, Manuli Stretch, Uflex Limited, Tri-Pack Films, Polibak, Jindal Poly Films, Polyplex Corporation, Copol International, Mitsui Chemicals Tohcello, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Polypropylene (CPP) Films Market Emerging Trajectories
Software-defined barrier tuning is rewriting converter procurement specifications, replacing gauge-based purchasing with transmission-rate-guaranteed supply contracts that span multiple performance tiers.
Multi-layer coextrusion with nano-clay dispersion is electrifying moisture and oxygen barrier performance in transparent CPP films. Pharmaceutical blister pack manufacturers in Germany and Switzerland are qualifying these grades for humidity-sensitive APIs. The technology is compressing metallization dependency in mid-barrier applications while preserving optical clarity for patient compliance packaging.
REACH SVHC candidate list expansion is forcing reformulation of slip agents and anti-static additives across European CPP supply chains. ECHA registration dossier updates are constraining erucamide and oleamide migration limits in food-contact laminates. Converters in Italy and Spain are accelerating certified raw material stream qualification to maintain EU market access.
Brand-led sustainability scorecards are reshaping converter supplier selection criteria. Nestlé and Unilever procurement teams in Western Europe are mandating mass-balance-certified polypropylene feedstock with ISCC PLUS chain-of-custody documentation. This behavioral shift is concentrating volume among extruders with integrated resin-to-film certification rather than toll-coating operations.
Cast Polypropylene (CPP) Films Market Segmentation
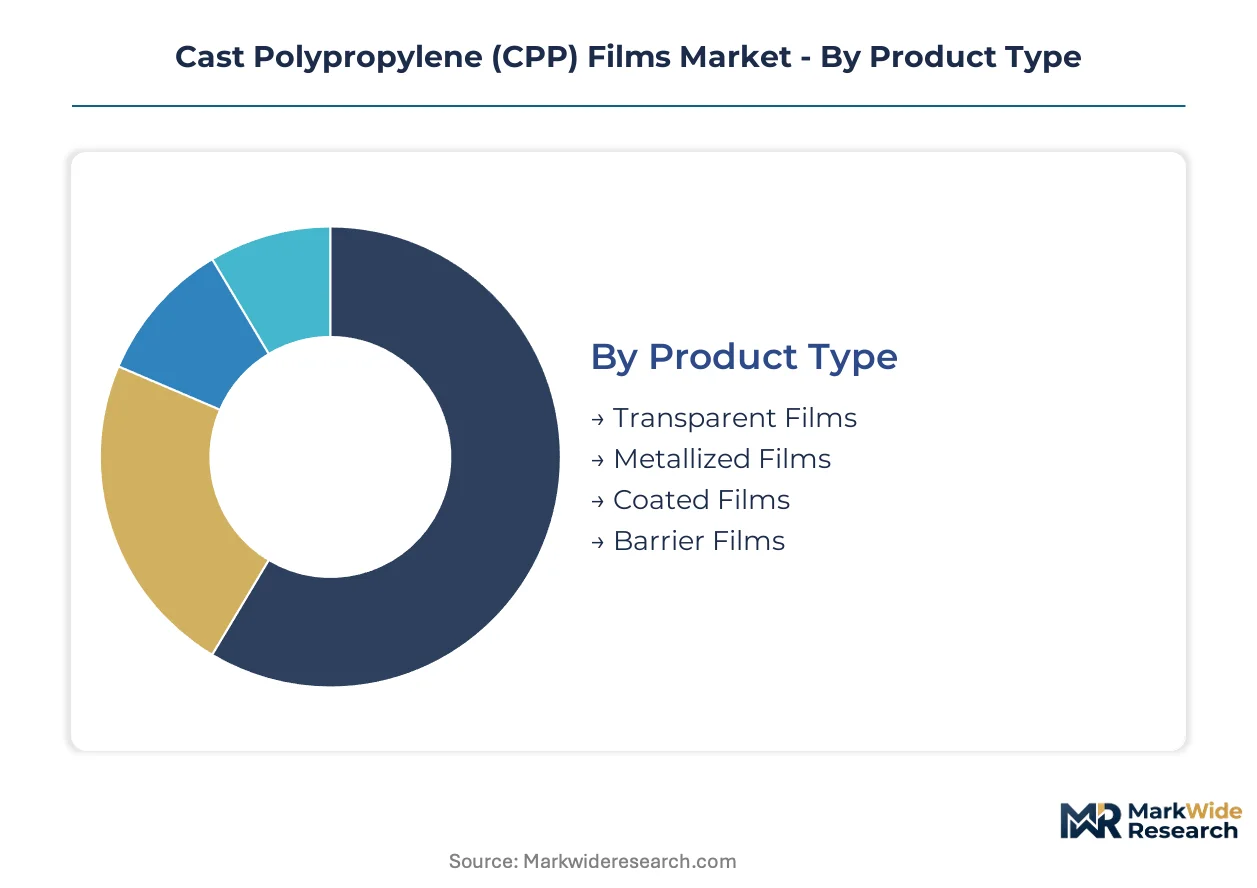
CPP film procurement has shifted from commodity gauge-based purchasing to performance-specified sourcing. Converters now segment supply by barrier transmission rates and seal integrity thresholds rather than roll dimensions alone. This reclassification is compressing margin pools for undifferentiated extruders while concentrating volume among certified mono-material suppliers.
Product Type:
Volume concentrates in transparent commodity grades while premium capture belongs to barrier-engineered variants. The split reflects diverging converter requirements between cost-optimized snack packaging and regulated pharmaceutical applications.
- Transparent Films:Standard coextruded grades without metallization or coating dominate flexible packaging volume for snack and bakery segments. Chinese converters in Zhejiang province are displacing import dependency with SAMR-certified domestic output for these specifications.
- Metallized Films:Vacuum-deposited aluminum layers deliver oxygen transmission rates below 0.1 cc/m²/day for retort pouch applications. Asian ready-meal manufacturers are substituting these CPP grades for aluminum foil laminates in extended-shelf-life formats.
- Coated Films:Acrylic or PVDC surface treatments enhance heat-seal response and print receptivity for high-speed form-fill-seal lines.
- Barrier Films:Nano-clay dispersions and coextruded tie layers target humidity-sensitive pharmaceutical blister packs in German and Swiss manufacturing clusters.
Mature deployment sits with transparent commodity grades. Newer deployment is concentrated in metallized barrier variants for retort applications.
End User:
Food packaging commands the dominant share of CPP film offtake, though medical-grade specifications generate disproportionate margin contribution. The customer base fragments between high-volume brand owners and specialized pharmaceutical contract packers with diverging certification requirements.
- Food Packaging:Modified atmosphere specifications for fresh produce and processed meats are pulling converters toward oxygen transmission rate-guaranteed supply contracts. EU Green Deal compliance deadlines are accelerating mono-material laminate adoption across European brand portfolios.
- Medical Packaging:Sterilizable grades with validated bioburden control command premium positioning for device and pharmaceutical applications. Profol GmbH sustains positioning here through coextrusion depth and medical-grade cleanroom certification.
- Consumer Goods:Corona-treated clarity grades serve personal care overwraps where shelf aesthetics drive specification.
- Industrial Applications:Heavy-gauge films with enhanced puncture resistance protect automotive components and textile rolls during distribution.
Food packaging absorbs volume at scale. Medical packaging delivers margin expansion through qualification barriers.
Thickness:
Gauge selection directly correlates with barrier load and mechanical protection requirements. Thinner specifications reduce material intensity but constrain seal latitude and puncture resistance.
- Below 20 Microns:Ultra-thin grades minimize material cost for high-volume biscuit and confectionery overwraps. China's GB/T 10003 standard enforces thickness tolerances that filter sub-scale extruders from certified supply chains at this gauge.
- 20-30 Microns:Mid-range specifications balance seal strength and material efficiency for standard pillow pouch formats.
- 30-40 Microns:Enhanced gauge provides puncture resistance for frozen food and industrial textile packaging.
- Above 40 Microns:Heavy-duty grades serve retort and deep-draw thermoforming applications where structural integrity under thermal stress is critical.
Below 20 micron specifications dominate volume throughput. Above 40 micron grades capture premium for thermal processing applications.
Application:
Format requirements dictate surface treatment, stiffness, and seal initiation temperature specifications. Each application imposes distinct constraints on converter equipment compatibility.
- Wraps:High-clarity grades with balanced orientation serve twist-wrap and flow-wrap formats for confectionery. Digital printing substrate demand is expanding for short-run flexible packaging workflows.
- Bags:Gusseted and wicketed formats require controlled coefficient of friction for high-speed packaging line efficiency.
- Labels:In-mold and pressure-sensitive label stocks demand specific surface energy profiles for adhesive anchorage.
- Overwraps:collation shrink and bundle wrap applications prioritize optical clarity and tear propagation resistance.
Bag formats absorb the highest tonnage. Wrap specifications are climbing fastest on digital printing conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global CPP film tonnage while European and North American converters absorb premium grades for regulated applications. This production-consumption divide shapes trade flows and certification requirements across major economies.
China
Domestic snack packaging expansion drives CPP film consumption in Zhejiang and Guangdong provinces. SAMR enforces GB/T 10003 thickness tolerances that filter sub-scale extruders from certified supply chains. The Yangtze River Delta cluster hosts integrated resin-to-film operations displacing import dependency for regional converters.
Germany
Pharmaceutical blister pack demand pulls high-barrier CPP grades into Baden-Württemberg and Bavaria manufacturing corridors. ECHA REACH registration deadlines accelerate mono-material laminate adoption across food brand portfolios. The VerpackG extended producer responsibility law mandates recyclable flexible packaging structures favoring heat-sealable PP designs.
United States
Modified atmosphere packaging specifications for fresh produce drive CPP film procurement from Midwest food processing hubs. FDA food-contact notification cycles constrain new additive qualification timelines for domestic extruders. The Southeast packaging corridor concentrates toll-coating operations serving national snack brand distribution networks.
India
Flexible packaging converters in Maharashtra and Gujarat scale CPP film adoption for biscuit and confectionery overwraps. FSSAI harmonization with EU migration testing standards opens export pathways for domestic manufacturers. The Delhi-NCR region concentrates metallization capacity serving emerging-market snack brand requirements.
Japan
Retort pouch applications for ready-meal segments sustain premium CPP film demand in the Kanto and Kansai industrial belts. METI guidelines on plastic resource circulation push converters toward mono-material structures. The Chubu region hosts coextrusion equipment specialists supplying five-layer manifold technology across Asia-Pacific.
Cast Polypropylene (CPP) Films Market Vendor Landscape
Top-tier vendors anchor premium medical and barrier-grade segments, while mid-scale converters compete on cost-optimized metallized variants for emerging-market snack brands. The vendor base stratifies across integrated resin-to-film operators, toll-coating specialists, and regional extrusion houses. Three archetypes dominate: certification-heavy European specialists, integrated Asian petrochemical-backed producers, and India-based cost-optimized metallizers. Competitive moves concentrate on backward integration into resin supply and geographic expansion through distribution partnerships.
Among European specialists, Profol GmbH exemplifies the premium-tier archetype through coextrusion depth and medical-grade cleanroom positioning. Mitsui Chemicals Tohcello anchors the integrated Asian model with captive resin-to-film operations. Uflex Limited occupies the cost-optimized metallization tier serving emerging-market volume requirements.
| Leading Market Players |
|---|
| Profol GmbH |
| Manuli Stretch |
| Uflex Limited |
| Tri-Pack Films |
| Polibak |
| Jindal Poly Films |
| Polyplex Corporation |
| Copol International |
| Mitsui Chemicals Tohcello |
| Others |
Supply Flow & Price Mechanics
Petrochemical-backed integrated producers anchor supply discipline through captive resin operations, compressing margin pools for toll-coating converters while sustaining premium capture among certified medical-grade specialists. This ownership pattern concentrates pricing power among resin-to-film operators in China and Japan, forcing independent extruders toward performance-guaranteed contract structures to defend position.
Pricing Analysis
Margin tightening in transparent commodity grades reflects naphtha-cracker output fluctuations from Middle Eastern petrochemical complexes transmitting directly to CPP resin pricing. Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS-certified medical grades from SAMR-certified food-contact specifications and undifferentiated snack packaging rolls. Price differentiation hinges on barrier transmission rate guarantees and cleanroom certification status. Cost-down pressure on standard grades accelerates because Chinese domestic output scaling in Zhejiang province displaces import volumes. Emerging-market snack brand converters exhibit highest price sensitivity, while pharmaceutical contract packers in Germany and Switzerland prioritize seal integrity thresholds over unit economics.
Supply Chain Analysis
REACH registration dossier updates and FDA food-contact notification cycles are filtering sub-scale extruders from certified pharmaceutical supply chains, concentrating qualified volume among resin-integrated operators with dedicated regulatory affairs functions. Manufacturing gravity centers on China, Japan, and Germany, with raw material supply drawing from propylene monomer streams tethered to naphtha cracking and PDH units. Supply chain risk manifests as single-source vulnerability in five-layer coextrusion die engineering, where European and Japanese equipment specialists control manifold design expertise. Distribution runs through regional converter hubs in the Yangtze River Delta, Baden-Württemberg manufacturing corridors, and Midwest food processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH SVHC candidate list expansion and FDA notification timeline compression force smaller extruders toward strategic exit or partnership. Regulatory qualification barriers are accelerating volume concentration among integrated resin-to-film operators with dedicated compliance infrastructure.
For Market Incumbents: Anticipate barrier coating substitution threats from ethylene vinyl alcohol copolymers and silicon oxide depositions in premium pharmaceutical blister packs by deepening coextrusion expertise and securing medical-grade cleanroom certification. Defend margin position through backward integration into propylene supply and geographic expansion into India FSSAI-harmonized export corridors. Priority investment targets five-layer manifold capability and mass-balance-certified feedstock qualification. For New Entrants and Emerging Players: Nano-clay dispersion technology for transparent moisture barrier applications offers a technology-first wedge into mid-tier pharmaceutical packaging previously served by metallized grades. Target white-space opportunities in digital printing substrate demand for short-run flexible packaging workflows and India FSSAI-certified export production for European brand supply chains. Go-to-market positioning should emphasize corona-treated high-clarity grades with guaranteed surface energy profiles for ink adhesion. For Investors and Strategic Acquirers: ISCC PLUS certification adoption among Nestlé and Unilever procurement teams is the leading indicator that sustainability-linked volume will concentrate among certified extruders over the projection horizon. Long-term viability favors integrated resin-to-film operators with medical-grade cleanroom infrastructure and established ECHA registration dossiers. Acquisition target archetype: mid-scale European specialists with coextrusion depth and pending FDA food-contact notifications. Signal to monitor: FSSAI-EU harmonization completion enabling India-based export pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive resin operations insulate margin from naphtha-cracker volatility in Middle Eastern feedstock markets. |
| Medical-Grade Cleanroom Certification | Validated bioburden control unlocks sterilizable device packaging contracts with German pharmaceutical manufacturers. |
| Mass-Balance Feedstock Qualification | ISCC PLUS chain-of-custody documentation satisfies Nestlé and Unilever procurement sustainability scorecards. |
| Five-Layer Coextrusion Capability Expansion | Multi-layer manifold expertise addresses nano-clay dispersion demand for humidity-sensitive API blister packs. |
| India FSSAI-Certified Production Footprint | Harmonized migration testing standards open EU export pathways for Maharashtra and Gujarat manufacturing clusters. |
Methodological Framework
Multi-period observation of propylene feedstock pricing, extrusion capacity utilization rates, and regulatory registration timelines anchored the trend analysis, supplemented by interviews with plant managers at integrated resin-to-film operations, procurement leads at European food brand owners, technical R&D directors at coextrusion equipment specialists, and distribution channel partners in Asian flexible packaging markets. Secondary validation drew from customs and trade data, ECHA registration dossier updates, FDA food-contact notification filings, and SEC 10-K disclosures from listed petrochemical producers. Bottom-up volume estimates from extruder capacity and utilization rates were triangulated against top-down demand aggregation from end-use segment consumption patterns.
Segment-weighting across product type, thickness gauge, end-use industry, and regional regulatory cluster shaped the analytical framework, with value outputs derived from average selling price bands specific to each performance tier. CAGRs were computed from fitted trend lines across the projection horizon, incorporating propylene monomer cost pass-through assumptions, REACH registration deadline impacts on mono-material adoption velocity, and retort pouch substitution rates for aluminum foil laminates in Asian ready-meal segments.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to GB/T 10003 thickness tolerance enforcement, abrupt propylene supply disruptions from geopolitical events in Middle Eastern petrochemical corridors, and breakthrough barrier coating technologies achieving cost parity with metallized CPP. Forecasts reflect assumptions about sustained brand-led sustainability procurement mandates and continued ECHA SVHC candidate list expansion. A model refresh is warranted upon material change in FDA food-contact notification cycle duration or FSSAI-EU harmonization implementation timeline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Primary Packaging Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Printed Aluminium Foil Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
MDO Films Market
Packaging Materials
Plastic Strapping Materials Market