
 Cargo Moisture Control Products Market | 2026-2036
Cargo Moisture Control Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Moisture Control Products Market Analytics
Pharmaceutical cold chain logistics is rotating toward advanced desiccant systems as temperature-sensitive biologics expand. Multisorb Technologies leverages its sorbent engineering heritage to dominate North American pharmaceutical packaging. Clariant AG anchors European supply through its controlled-atmosphere packaging division. Absortech Group specializes in container-dry solutions for maritime freight corridors.
Cargo moisture control products encompass desiccants, humidity indicators, absorbents, and dehumidifiers engineered to maintain sub-critical relative humidity levels typically below 60% RH during transit and storage. Silica gel and clay-based desiccants retain the largest installed base due to cost-efficiency, though polymer-based superabsorbent formats are displacing legacy materials in pharmaceutical applications where extractables control matters. The logistics end-user segment commands the deepest procurement volumes, while pharmaceutical demand generates the highest margin pools due to validation requirements and regulatory documentation burdens.
FDA pharmaceutical packaging guidelines, EU MDR device labeling rules, and REACH chemical restrictions collectively shape material selection and supplier qualification protocols across major trade lanes. ISO 11607 sterilization barrier standards further constrain design freedom for medical device shippers. Stakeholders must monitor evolving pharmacopeial chapters on desiccant performance testing, as harmonization between USP, EP, and JP methods remains incomplete and drives regional sourcing fragmentation.
Market Dynamics
Regulatory pressure on cobalt-based humidity indicators under REACH and EU MDR is decomposing legacy material supply chains, forcing rapid substitution toward polymer-based and clay alternatives while fragmenting supplier qualification protocols across pharmaceutical corridors.
Growth Catalysts
- Biologics expansion:Temperature-sensitive monoclonal antibodies and cell therapies require validated desiccant systems with extractables documentation, pulling advanced sorbent formats into cold chain protocols.
- REACH chemical restrictions:ECHA's tightening cobalt chloride classifications are eliminating traditional humidity indicators from European pharmaceutical packaging, opening substitution demand for safer alternatives.
- Port-centric distribution clusters:Concentrated pharmaceutical logistics hubs in Germany and the Netherlands are standardizing integrated moisture management protocols across multimodal freight corridors.
Market Restraints
- Silica gel price volatility:Feedstock energy costs and freight rates for containerized bentonite clay are compressing margins for commodity desiccant producers serving bulk logistics.
- Supplier concentration risk:Controlled-atmosphere packaging capabilities cluster among three European chemical conglomerates, creating single-source vulnerability for validated pharmaceutical formats.
- Harmonization gaps:Incomplete alignment between USP, EP, and JP desiccant performance testing chapters forces redundant regional validation studies, extending time-to-market.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightening cold chain guidelines for export-oriented biologics production are creating first-mover openings for validated desiccant system providers.
- IoT-integrated monitoring:Convergence of wireless humidity sensors with active desiccant canisters enables real-time cargo condition verification, unlocking premium service tiers.
- EU MDR device labeling mandates:Stricter moisture exposure documentation requirements for Class II and III medical devices are expanding the addressable market for indicator-integrated packaging.
Industry Challenges
- Extractables chemist scarcity:Pharmaceutical sorbent validation requires specialized analytical toxicology expertise that outpaces current training pipeline output in both North America and Europe.
- ISO 11607 sterilization barrier integration:Medical device shippers face complex redesign cycles when combining moisture control with sterile packaging validation, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Moisture Control Products Market |
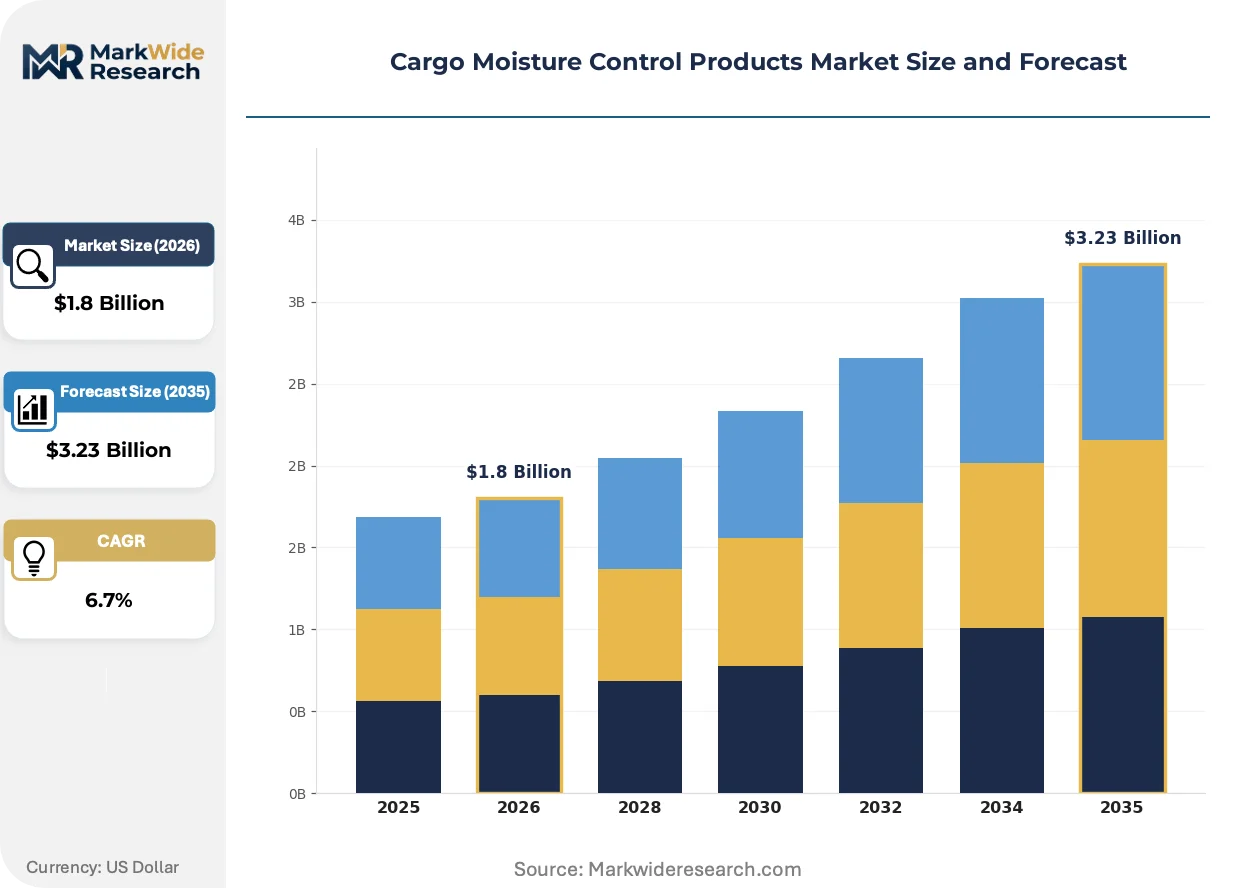
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desiccants, Humidity Indicators, Absorbents, Dehumidifiers Application: Transport, Warehousing, Storage, Packaging End User: Logistics, Retail, Pharmaceuticals, Food & Beverage Material Type: Silica Gel, Clay, Calcium Oxide, Polymer |
| Companies Covered | Multisorb Technologies, Clariant AG, Foshan Weller Moisture Proof Technology Co., Ltd, Absortech Group, Dow Chemical Company, Honeywell, Sealed Air, Amcor, Stream Peak International Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Moisture Control Products Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are simultaneously pulling the cargo moisture control market toward higher-performance formats while compressing the viable supplier base through qualification burden escalation.
Polymer-based superabsorbent desiccants are decomposing the installed base of silica gel in pharmaceutical applications. Biologics manufacturers at Merck's Darmstadt cluster and Roche's Basel operations have accelerated validation timelines for these formats. The shift is compressing commodity sorbent margins while elevating polymer engineering capabilities to tier-one supplier status.
EU MDR device labeling rules and REACH cobalt restrictions are jointly eliminating legacy humidity indicator chemistries from European pharmaceutical corridors. ECHA's 2023 reclassification of cobalt dichloride as a Category 1B carcinogen forced immediate formulation changes. Medical device exporters to Germany and the Netherlands now face dual compliance burdens that favor suppliers with integrated regulatory documentation teams.
Buyer consolidation among contract logistics providers is compressing procurement cycles and unbundling after-sales technical support. DHL Supply Chain and Kuehne+Nagel are centralizing moisture control specification authority at regional hubs. Pharmaceutical manufacturers in Switzerland and Belgium are responding by pre-qualifying fewer, larger-format suppliers capable of direct-to-dock integrated service delivery.
Cargo Moisture Control Products Market Segmentation
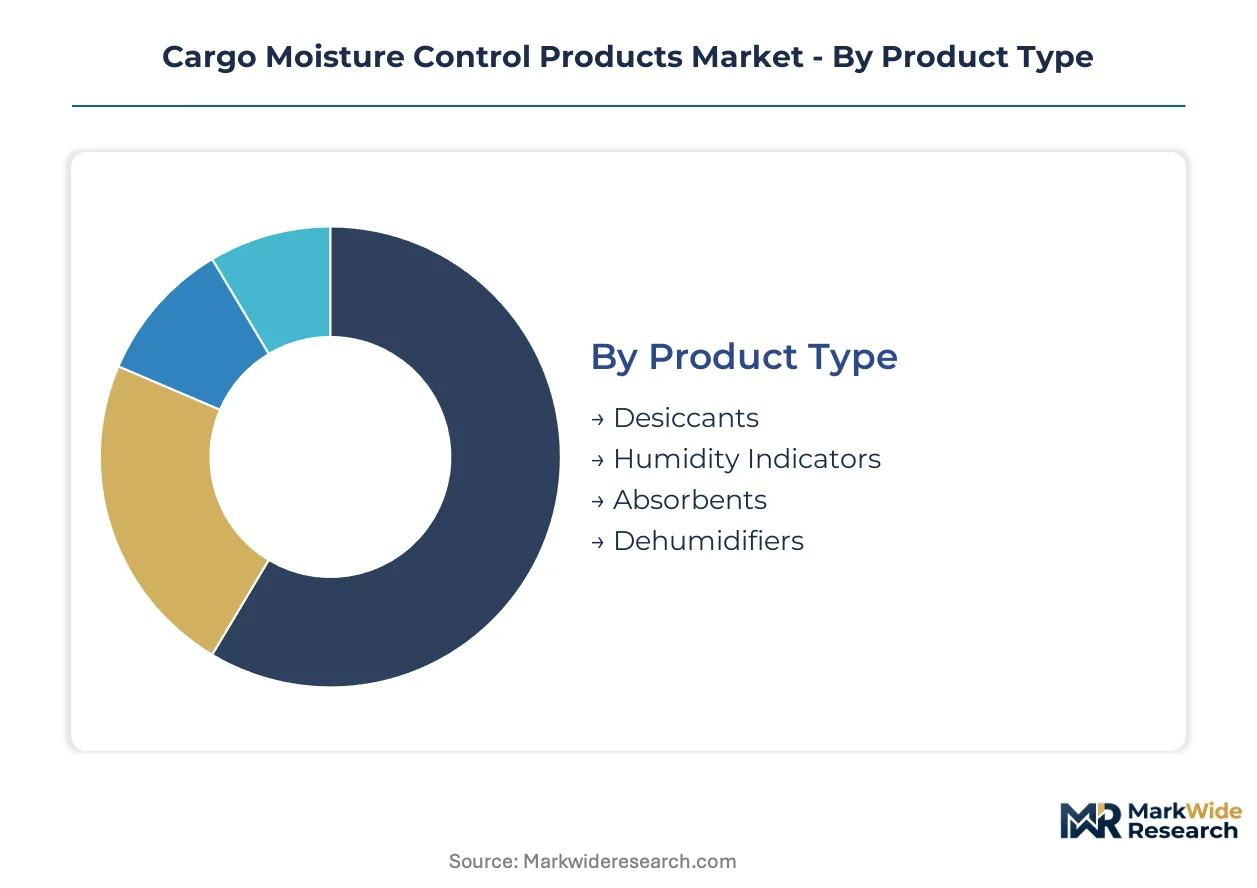
Product differentiation in cargo moisture control tracks closely with validation burden and regulatory exposure. Margin pools concentrate where extractables documentation and sterilization barrier integration create qualification moats.
Product Type:
Desiccants command the deepest margin pools due to pharmaceutical validation requirements and recurring consumption in cold chain protocols.
- Desiccants:Silica gel and clay-based formats retain the largest installed base across logistics corridors. Pharmaceutical cold chains in Germany and the Netherlands are pulling polymer-based superabsorbent formats into validated protocols as ECHA cobalt restrictions intensify scrutiny of extractables profiles.
- Humidity Indicators:Color-change cards and electronic sensors monitor relative humidity thresholds during transit. REACH reclassifications of cobalt dichloride as a Category 1B carcinogen are forcing immediate substitution toward polymer-based and clay indicator chemistries in European medical device packaging.
- Absorbents:Bulk sorbent blankets and pads target containerized maritime freight with lower unit margins.
- Dehumidifiers:Active mechanical systems serve fixed warehousing infrastructure rather than mobile cargo applications.
Desiccants hold installed capacity. Humidity indicators are rotating up the share rankings.
Application:
Transport applications generate the steepest expansion trajectory as multimodal pharmaceutical corridors standardize moisture management protocols.
- Transport:Container-dry solutions and trailer-mounted desiccant systems protect temperature-sensitive cargo across maritime and road freight. Port-centric distribution clusters in Rotterdam and Hamburg are mandating integrated humidity control for biologics shipments.
- Packaging:Primary and secondary moisture barriers for medical devices and pharmaceuticals require ISO 11607 sterilization validation. Swiss and Belgian manufacturers are consolidating procurement around fewer suppliers capable of direct-to-dock integrated service delivery.
- Warehousing:Fixed-installation dehumidification serves bulk commodity storage with cyclical demand patterns.
- Storage:Long-term archival and strategic stockpile applications favor low-cost silica gel formats with minimal monitoring requirements.
Transport leads volume growth. Packaging captures the highest value per unit.
End User:
Pharmaceutical demand concentrates margin pools where FDA and EU MDR documentation burdens elevate supplier qualification thresholds.
- Pharmaceuticals:Monoclonal antibodies and cell therapies require validated desiccant systems with full extractables documentation. Merck's Darmstadt cluster and Roche's Basel operations have accelerated validation timelines for polymer-based formats.
- Logistics:Contract providers including DHL Supply Chain and Kuehne+Nagel are centralizing moisture control specifications at regional hubs, compressing procurement cycles and unbundling after-sales technical support.
- Food & Beverage:Commodity desiccant consumption for packaged goods faces margin pressure from silica gel price volatility.
- Retail:Consumer electronics and apparel applications favor low-cost clay-based solutions with minimal regulatory overhead.
Pharmaceuticals anchor premium tier pricing. Logistics commands aggregate procurement volume.
Material Type:
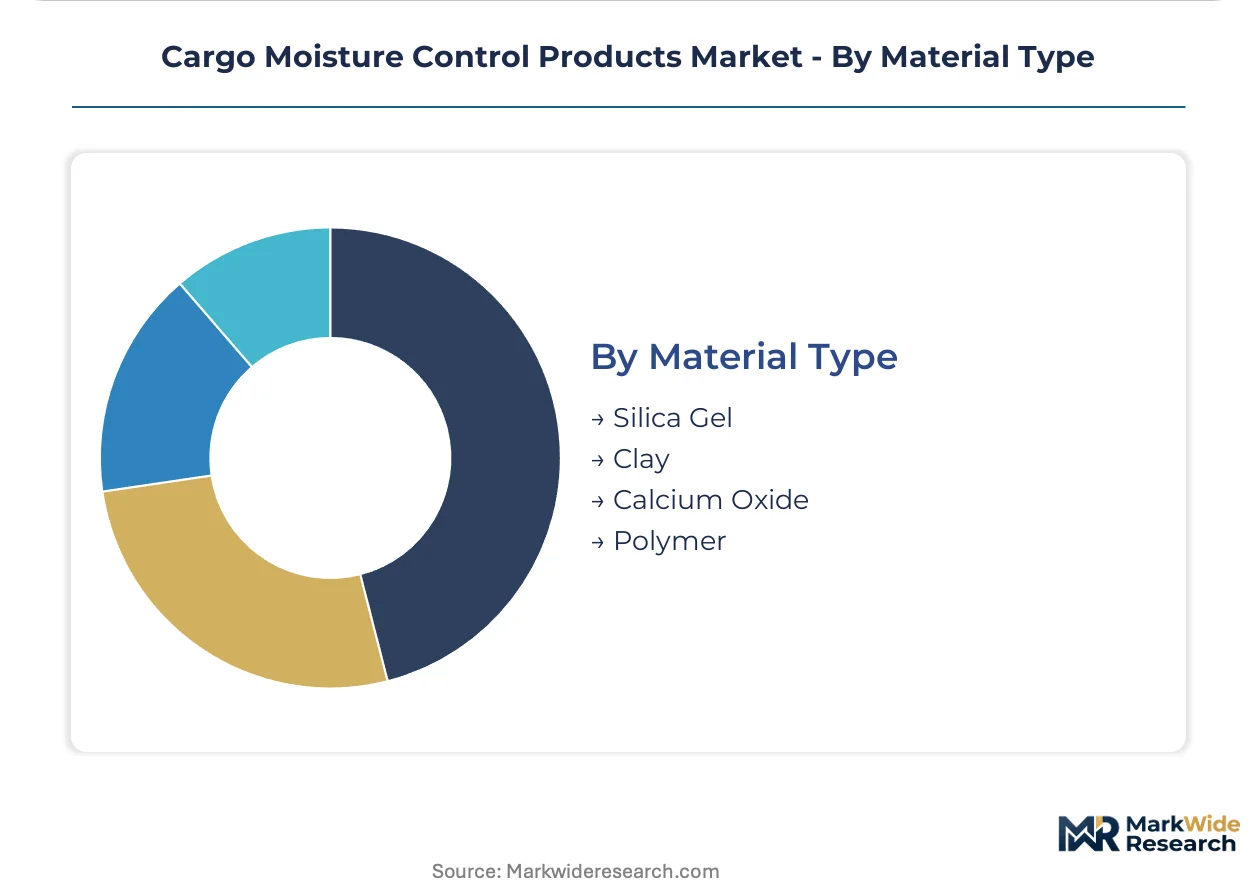
Material selection tracks regulatory chemistry restrictions and extractables control requirements across major trade lanes.
- Silica Gel:Amorphous silicon dioxide dominates commodity logistics applications through cost efficiency. Feedstock energy costs and containerized bentonite clay freight rates are compressing margins for bulk producers.
- Polymer:Superabsorbent polymer formats are displacing legacy materials in pharmaceutical applications where USP and EP extractables testing matters. CDSCO's tightening cold chain guidelines for Indian export-oriented biologics production are creating first-mover openings for validated polymer system providers.
- Clay:Natural bentonite serves cost-sensitive warehousing and retail applications with moderate humidity control requirements.
- Calcium Oxide:High-capacity quicklime formats target specialized maritime bulk cargo with extreme moisture loads.
Silica gel retains volume leadership. Polymer is climbing the fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites the Netherlands' dominance in European pharmaceutical logistics corridors. Hamburg's deep-water terminals anchor Germany's parallel distribution network for temperature-sensitive biologics.
Germany
Merck's Darmstadt biologics cluster and Bayer's Leverkusen operations drive validated desiccant procurement. ECHA's REACH cobalt restrictions are eliminating legacy humidity indicators from medical device packaging. The Hamburg-Frankfurt pharmaceutical freight corridor is standardizing polymer-based superabsorbent formats across cold chain protocols.
United States
FDA pharmaceutical packaging guidelines and biologics manufacturing expansion in Massachusetts and North Carolina pull advanced sorbent systems into cold chains. The Boston-Cambridge cell therapy cluster is accelerating validation timelines for extractables-documented formats. UPS and FedEx pharmaceutical hubs in Louisville and Memphis are mandating integrated moisture management for temperature-controlled shipments.
India
CDSCO's tightening cold chain guidelines for export-oriented biologics production are creating first-mover openings for validated desiccant providers. The Hyderabad-Bengaluru pharmaceutical manufacturing belt is consolidating procurement around suppliers with USP and EP documentation capabilities. Serum Institute of India's Pune operations are driving regional adoption of polymer-based formats.
Netherlands
EU MDR device labeling rules and REACH compliance are forcing material substitutions in Rotterdam's port-centric distribution clusters. DSM's Heerlen operations and the Leiden biotech corridor are pulling indicator-integrated packaging into medical device shipments. Schiphol's air freight pharmaceutical hub is standardizing real-time humidity monitoring across multimodal corridors.
Switzerland
Swissmedic's stringent device packaging requirements and Roche's Basel biologics operations anchor premium desiccant demand. The country's sterilization barrier integration standards are elevating supplier qualification thresholds. Novartis's Stein manufacturing complex is consolidating procurement around direct-to-dock integrated service providers.
Cargo Moisture Control Products Market Competitive Landscape
Listed leaders compete with private specialists across regulatory documentation capabilities. The supplier base clusters around three strategic tiers: integrated chemical conglomerates with controlled-atmosphere packaging divisions, sorbent engineering specialists with pharmaceutical validation heritage, and regional container-dry providers serving maritime freight corridors. Consolidation is accelerating through backward integration into polymer resin production and strategic partnerships with contract logistics providers.
Within the integrated chemical tier, Clariant AG and Dow Chemical Company exemplify scale-driven positioning through controlled-atmosphere packaging divisions. Among sorbent engineering specialists, Multisorb Technologies occupies a position anchored by pharmaceutical heritage. These archetypes represent the competitive spectrum from commodity logistics to validated biologics cold chains.
| Leading Market Players |
|---|
| Multisorb Technologies |
| Clariant AG |
| Foshan Weller Moisture Proof Technology Co., Ltd |
| Absortech Group |
| Dow Chemical Company |
| Honeywell |
| Sealed Air |
| Amcor |
| Stream Peak International Pte Ltd |
| Others |
Value Network & Pricing Analysis
REACH cobalt chloride reclassifications and EU MDR compliance protocols gate both supplier qualification and price differentiation simultaneously, forcing pharmaceutical buyers to pay premiums for validated documentation while commodity logistics segments face relentless cost compression.
Pricing Analysis
Volume-discount tiering structures separate validated pharmaceutical formats from commodity logistics supply. Three-tier pricing stratification across premium, standard, and economy levels reflects certification burden divergence: polymer-based superabsorbent desiccants with full extractables documentation command the top tier, silica gel formats with basic humidity control occupy the mid-market, and unvalidated clay-based bulk absorbents anchor the economy segment. Pricing pressure stems from silica gel feedstock energy costs and containerized bentonite freight volatility, which compress margins for bulk producers. Logistics providers at DHL Supply Chain and Kuehne+Nagel regional hubs exhibit acute price sensitivity, while Swiss and Belgian pharmaceutical manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
China and India anchor raw material extraction and polymer resin production for superabsorbent formats, while Germany and the Netherlands concentrate finished-goods manufacturing around pharmaceutical corridor demand. The supply chain draws from containerized bentonite clay shipments, specialized polymer engineering capabilities, and cobalt-free indicator chemistry development. Single-source vulnerability clusters among three European chemical conglomerates with controlled-atmosphere packaging divisions, creating qualification bottlenecks for validated pharmaceutical formats. Distribution runs through port-centric logistics hubs in Rotterdam and Hamburg, with direct-to-dock integrated service delivery consolidating around fewer qualified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of extractables chemists and regulatory documentation specialists constrains market expansion, creating asymmetric returns for stakeholders who secure scarce analytical toxicology capabilities before competitor qualification timelines extend further.
For Market Incumbents: Secure backward integration into polymer resin production to insulate margin pools from feedstock volatility and accelerate validation timelines for biologics applications. Invest in captive extractables testing laboratories to address the talent pipeline gap that delays pharmaceutical customer onboarding. Defend against emerging polymer engineering specialists by pre-qualifying integrated service protocols at Roche's Basel operations and Merck's Darmstadt cluster before contract logistics centralization completes. For New Entrants and Emerging Players: CDSCO certification fast-track pathways for Indian export-oriented biologics production represent the most penetrable white-space opportunity, as domestic validated desiccant capacity lags behind pharmaceutical manufacturing expansion. Target the Hyderabad-Bengaluru pharmaceutical manufacturing belt with USP and EP documentation capabilities that incumbent European suppliers cannot deploy with equivalent responsiveness. Pursue strategic partnerships with Serum Institute of India's Pune operations to establish reference-account credibility before regional procurement consolidation hardens. For Investors and Strategic Acquirers: ECHA's 2023 cobalt dichloride reclassification reshapes the acquisition landscape toward polymer-based indicator chemistry platforms with immediate REACH substitution revenue visibility. Over the projection horizon, vertically integrated specialists combining resin production with pharmaceutical validation heritage present superior viability against pure-play commodity desiccant manufacturers exposed to silica gel price volatility. Monitor CDSCO guideline implementation velocity as the signal indicating when Indian pharmaceutical corridor demand inflects toward premium-tier pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captive supply of superabsorbent raw materials insulates margins from energy cost volatility at Chinese feedstock producers. |
| Extractables Testing Laboratory Capacity Expansion | In-house analytical toxicology capabilities compress pharmaceutical customer validation timelines against scarce external chemist supply. |
| CDSCO Pre-Qualification Investment | Early regulatory documentation alignment captures first-mover revenue from India's export-oriented biologics manufacturing expansion. |
| IoT-Integrated Monitoring Platform Development | Wireless humidity sensor convergence with active desiccant canisters unlocks premium service tiers at Schiphol's air freight pharmaceutical hub. |
| Direct-to-Dock Integrated Service Deployment | Consolidated procurement authority at Swiss and Belgian manufacturers favors suppliers with unified logistics-protocol capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and pharmacopeial documentation standards across USP, EP, and JP chapters. Primary interviews engaged pharmaceutical packaging engineers, regulatory affairs specialists at EMA-notified bodies, contract logistics procurement directors, and extractables testing laboratory managers. Secondary validation drew from FDA packaging guideline publications, ECHA substance restriction databases, CDSCO cold chain advisories, and ISO 11607 sterilization barrier standards. Bottom-up demand modeling across desiccant consumption units triangulates against top-down pharmaceutical cold chain infrastructure investment assessments.
Segmentation dimensions modeled span product type, application, end-user industry, material chemistry, and regional regulatory cluster across the projection horizon. The analytical framework derives expansion trajectories from biologics manufacturing capacity additions, REACH substitution timelines, and port-centric distribution cluster standardization. Forecast inputs incorporate pharmaceutical validation burden escalation rates, polymer engineering capability diffusion patterns, and contract logistics procurement centralization velocity. CAGRs emerge from regression analysis against historical pharmaceutical packaging spend correlations with biologics approval volumes.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory chemistry restriction tightening and stable pharmaceutical cold chain infrastructure investment; material deviation in ECHA enforcement intensity or CDSCO guideline implementation would warrant model refresh. Recalibration cycles align with material shifts in cobalt substitution velocity, extractables chemist training pipeline output, and biologics manufacturing geographic dispersion patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
PET Packaging Market
Packaging Materials
Foam Trays Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
VCI Films Market
Packaging Materials
China Packaging Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Europe Consumer Packaging Market