
 Twist Tie Market | 2026-2036
Twist Tie Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Tie Market Analytics
Food-grade specification upgrades is redrawing competitive boundaries across the twist tie landscape. Bedford Industries leverages its vertically integrated wire-coating capabilities to sustain premium positioning in North American fresh produce channels. Plas-Ties anchors European supply relationships through specialized biodegradable formulations that comply with advancing compostability standards. Zhenjiang Hongda Commodity dominates cost-engineered volume tiers, competing on manufacturing scale for private-label supermarket programs.
A twist tie is a flexible fastening device consisting of a metal wire core encased in a thin polymer or paper sheath, typically measuring 3–6 inches in length and rated for tensile loads of 5–15 pounds depending on gauge. Its primary commercial purpose is to create temporary yet resealable closures for bags, cables, and bundled goods across retail, industrial, and consumer applications. Plastic twist ties still occupy the largest share of material-type volume, though paper-sheathed variants are gaining fastest as brand owners eliminate polyolefin coatings to meet retailer sustainability scorecards. Heavy-duty ties command the strongest margin pools within form-factor segmentation, serving industrial cable management and construction bundling where breakage tolerance justifies price premiums over standard consumer grades.
The FDA regulates direct food-contact twist ties through 21 CFR compliance for coating migration limits, while the EPA oversees wire-core manufacturing emissions under Clean Air Act metal finishing standards. REACH restrictions in Europe further constrain phthalate-based plasticizers, compelling reformulation investments that reshape supplier qualification timelines. Stakeholders must monitor evolving state-level extended producer responsibility laws, as California and New York advance packaging waste frameworks that could mandate recycled-content minimums without grandfathering existing product lines.
Market Dynamics
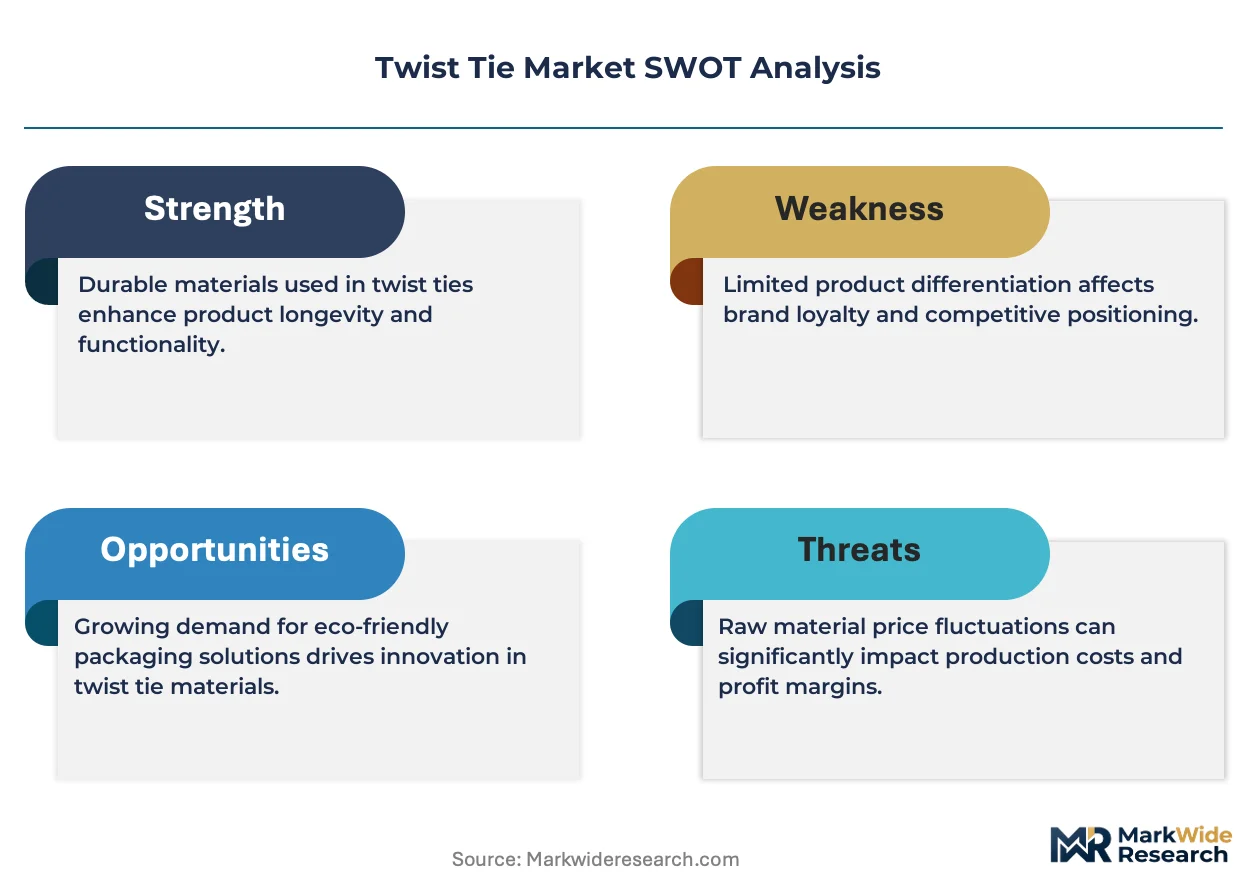
The EU Single-Use Plastics Directive is forcing material reformulation across the entire twist tie supply base, compelling wire-coating suppliers to abandon conventional polyolefin sheaths ahead of mandated phase-out timelines. This regulatory compression is reshaping competitive positioning as compliance investments separate qualified suppliers from legacy manufacturers.
Growth Catalysts
- Fresh produce packaging automation:Retailers in Germany and the Netherlands are integrating twist ties into high-speed bagging lines, driving specification upgrades for tensile consistency and food-contact certification.
- REACH phthalate restrictions:ECHA constraints on plasticizer migration are accelerating adoption of bio-based coating alternatives that meet compostability standards without grandfathered exemptions.
- Biodegradable material R&D:PLA and starch-blend sheaths are achieving cost parity with conventional plastics in pilot programs across Scandinavian retail supply chains.
Market Restraints
- Steel wire price volatility:Galvanized wire cores face input cost pressure from energy-intensive zinc coating processes, compressing margins for standard-grade producers.
- Supply concentration in East Asian coating capacity:Over 60% of global polymer-sheath extrusion sits in concentrated manufacturing zones, creating vulnerability to regional logistics disruptions.
- Adhesive clip substitutes:Resealable adhesive tabs on bread and produce bags are capturing closure applications where one-time sealing suffices.
Strategic Opportunities
- Industrial cable management expansion:Heavy-duty twist ties rated for 15+ pound loads are penetrating data center and renewable energy installation markets in the United States and Germany.
- Extended producer responsibility frameworks:California and New York packaging waste laws are creating first-mover advantage for suppliers with certified recycled-content and take-back programs.
- E-commerce fulfillment bundling:Corrugated box compression and cable organization applications are emerging as volume channels through third-party logistics providers.
Industry Challenges
- Compostability certification timelines:TÜV and BPI approval processes for biodegradable variants extend 18-24 months, delaying product launches behind regulatory deadlines.
- Legacy equipment retrofit costs:Food-packaging lines require tooling modifications to handle paper-sheathed ties without breakage, demanding capital allocation from tier-two manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Tie Market |
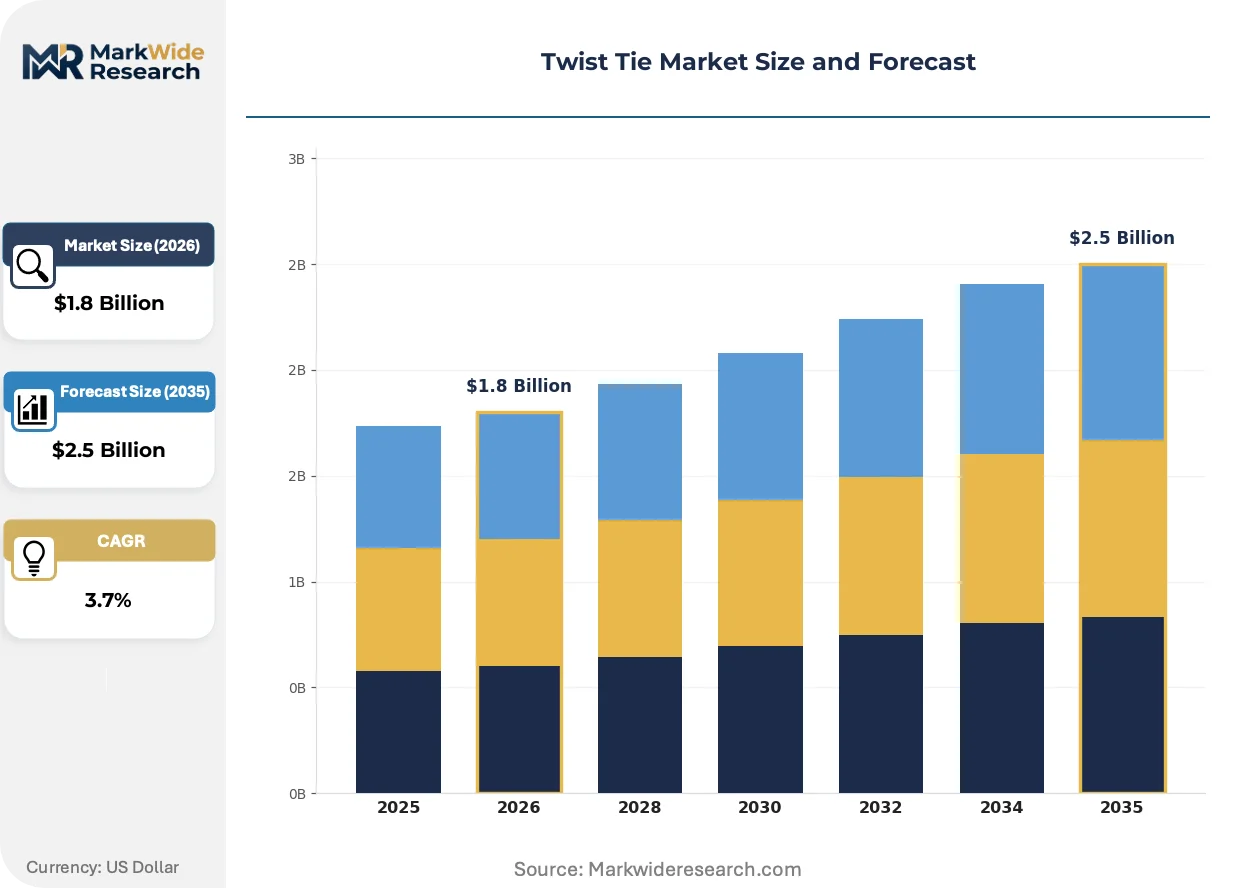
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Paper, Fabric Application: Food Packaging, Cable Management, Gardening, Industrial Use Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Form Factor: Standard Ties, Decorative Ties, Heavy-Duty Ties, Mini Ties |
| Companies Covered | Bedford Industries, Plas-Ties, Twist-Ease, AndFel Corporation, Felins USA, Multi-Pak USA, Allied Plastics, Zhenjiang Hongda Commodity, AmeriTwist, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Tie Market Evolving Landscape
Material science breakthroughs and regulatory enforcement timelines are compressing product development cycles across the twist tie category. Suppliers are racing to commercialize viable alternatives before mandated plastic phase-outs take effect.
Water-soluble PVOH coatings are displacing conventional polyethylene sheaths in European fresh produce applications. Retailers in Germany and France are specifying these variants to meet retailer sustainability scorecards. The technology is displacing incumbent suppliers lacking coating chemistry expertise, consolidating procurement toward qualified vendors with in-house polymer development capabilities.
REACH Annex XVII restrictions on microplastic release are tightening enforcement across EU member states. The regulation is compelling reformulation of all plastic-sheathed ties intended for home composting or agricultural disposal. Food-contact applications face the steepest compliance burden, with EFSA migration limit testing now mandatory for coating approval.
Centralized procurement by supermarket chains is consolidating supplier relationships and compressing switching cycles. Buyers are bundling twist tie contracts with broader flexible packaging agreements, favoring vendors with multi-product portfolios. This concentration is most visible in German and Dutch retail networks, where three buying groups control the majority of fresh produce packaging specifications.
Twist Tie Market Segmentation
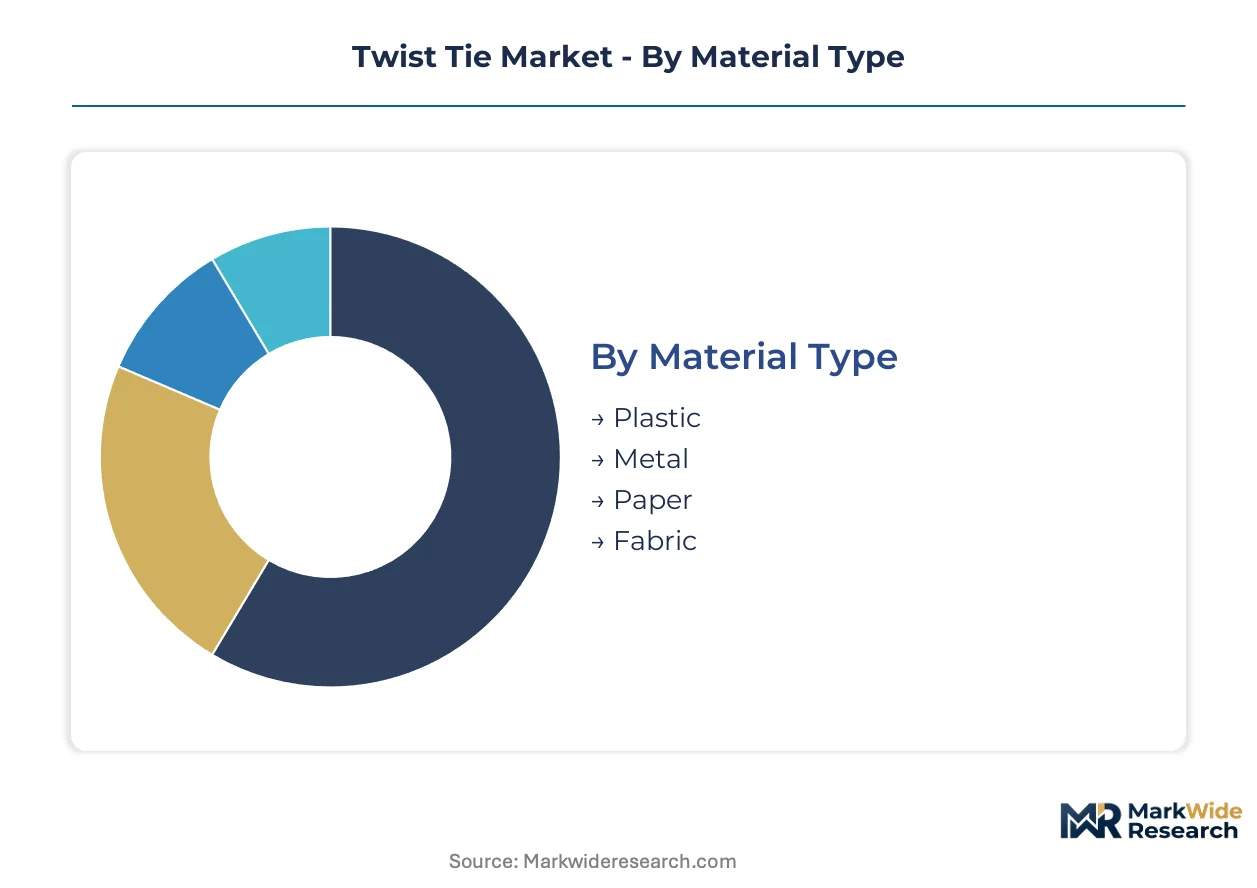
Twist tie procurement decisions hinge on regulatory compliance tiers, application-specific performance thresholds, and channel economics that reshape supplier qualification requirements. Material specifications and form factor ratings determine entry barriers across food-contact, industrial, and consumer segments.
Material Type:
REACH phthalate restrictions and FDA migration limits create divergent compliance pathways for coating chemistries across food-contact and industrial applications.
- Plastic:Polyolefin and PVC sheaths dominate volume through cost-engineered fresh produce bundling. ECHA plasticizer constraints are accelerating reformulation toward bio-based alternatives in German and Dutch retail supply chains.
- Paper:Kraft and coated paper variants eliminate synthetic polymer layers to meet retailer sustainability scorecards. Scandinavian supermarkets are specifying these for compostable packaging lines ahead of mandated phase-outs.
- Metal:Bare galvanized wire serves industrial cable management where tensile strength requirements exceed polymer-sheathed alternatives.
- Fabric:Woven textile sheaths provide reusable closure solutions for premium consumer and gift packaging applications.
Established volume favors Plastic; emerging adoption favors Paper.
Application:
End-use specifications separate food-grade certification requirements from industrial performance ratings.
- Food Packaging:FDA 21 CFR compliance for coating migration limits governs direct-contact fresh produce and bakery applications. German retailers are integrating these into high-speed bagging automation with tensile consistency mandates.
- Industrial Use:Heavy-duty ratings for 15+ pound loads penetrate data center cable management and renewable energy installation markets in the United States.
- Cable Management:Residential and commercial wire organization drives standard-grade consumption through hardware and e-commerce channels.
- Gardening:UV-resistant variants support plant staking and trellis applications in seasonal retail cycles.
Food Packaging commands procurement consolidation; Industrial Use is climbing the fastest on infrastructure buildouts.
Distribution Channel:
Channel economics stratify around volume scale and technical specification complexity.
- Supermarkets:Centralized buying groups in Germany and the Netherlands bundle twist tie contracts with flexible packaging agreements, favoring multi-product vendors.
- Wholesale:Industrial distributors serve construction and data center contractors with heavy-duty specification tiers.
- Online Retail:E-commerce fulfillment bundling for corrugated box compression and cable organization is emerging through third-party logistics providers.
- Specialty Stores:Garden centers and hardware independents stock decorative and seasonal variants with higher margin profiles.
Supermarkets concentrate food-grade volume; Online Retail is gaining share fastest on fulfillment automation.
Form Factor:
Load rating and dimensional specifications align with end-use durability requirements and equipment compatibility.
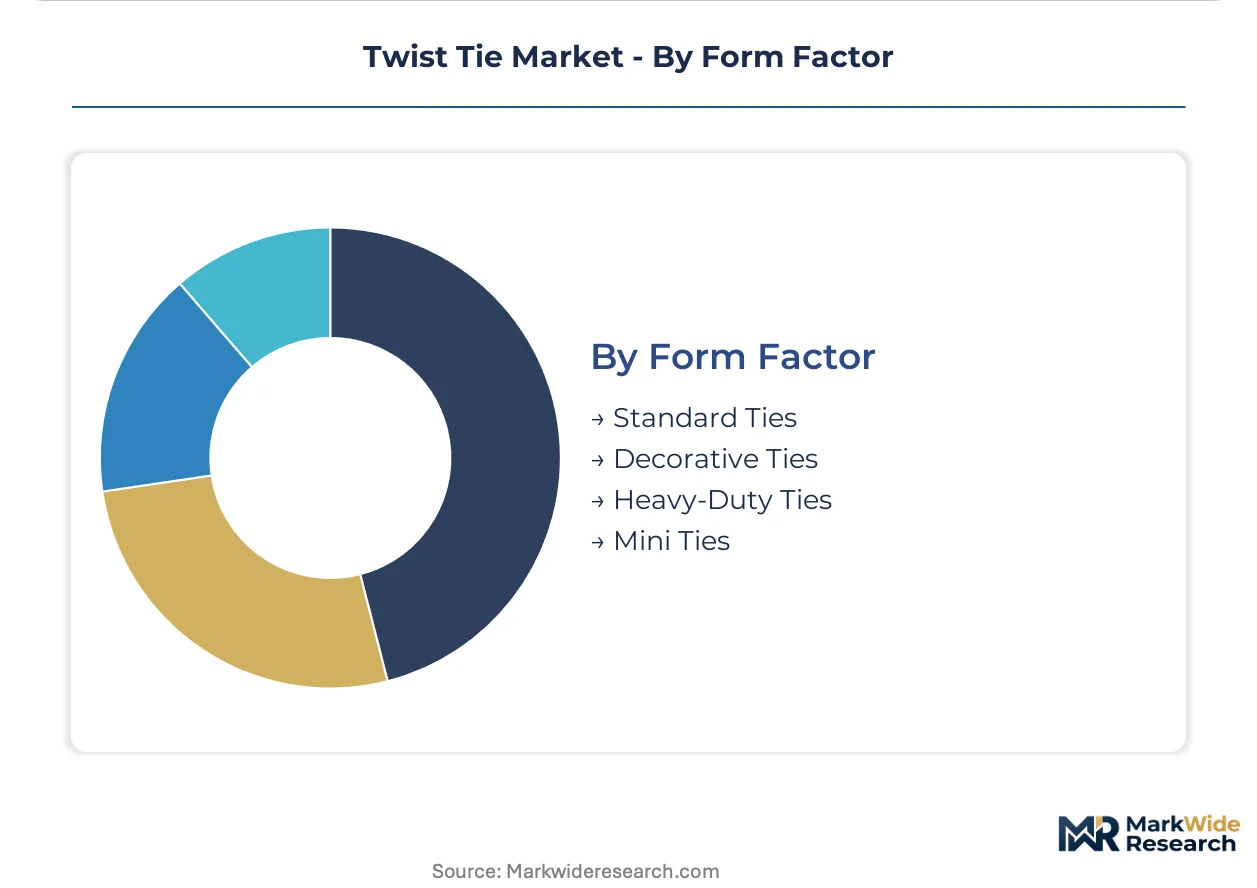
- Heavy-Duty Ties:15+ pound tensile ratings command premium pricing in industrial cable management where breakage tolerance justifies cost over standard consumer grades.
- Standard Ties:5-10 pound ratings serve mass-market fresh produce and bread bagging through high-speed packaging lines.
- Mini Ties:Reduced gauge wire and shortened length target confectionery and small-format retail packaging.
- Decorative Ties:Color-printed and shaped variants support gift and seasonal merchandise presentation.
Standard Ties anchor volume economics; Heavy-Duty Ties deliver the steepest expansion trajectory on infrastructure demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters in East Asia supply twist tie components to import-dependent packaging markets across Europe and North America. Trade flows concentrate wire-coating capacity in coastal manufacturing zones while compliance-heavy end-markets drive specification premiums in developed economies.
Germany
Fresh produce retailers in the Netherlands and Germany are integrating twist ties into automated bagging lines with food-contact certification mandates. REACH Annex XVII phthalate restrictions enforced by ECHA compel coating reformulation toward bio-based alternatives. The Rhine-Ruhr industrial corridor hosts wire-processing specialists serving pan-European supermarket buying groups.
United States
Data center construction and renewable energy installations are absorbing heavy-duty twist ties rated for 15+ pound loads in cable management applications. FDA 21 CFR migration limits govern direct food-contact specifications for bakery and produce packaging. California's advancing extended producer responsibility framework is mandating recycled-content minimums ahead of federal standards.
China
Galvanized wire core manufacturing concentrates in Jiangsu and Zhejiang provinces where energy-intensive zinc coating operations face input cost pressure. The country's national standards body sets migration limits for food-contact polymer sheaths destined for export markets. Shanghai-based coating specialists supply European retailers with compostability-certified variants.
Netherlands
Centralized supermarket procurement in Amsterdam and Rotterdam is bundling twist tie contracts with flexible packaging agreements favoring multi-product vendors. EFSA migration limit testing is now mandatory for coating approval in direct food-contact applications. The Port of Rotterdam serves as the primary entry point for Asian-manufactured components into German retail supply chains.
India
Bread and confectionery packaging automation in Maharashtra and Gujarat is driving specification upgrades for tensile consistency. The Food Safety and Standards Authority of India enforces coating migration limits for domestic food-contact applications. Mumbai-based distributors serve as intermediaries between East Asian manufacturers and emerging South Asian retail networks.
Twist Tie Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and compliance capability dimensions. The vendor base stratifies into three tiers: integrated wire-coating operators with in-house polymer development, regional converters dependent on outsourced materials, and commodity assemblers competing on manufacturing scale. Archetypes include vertically integrated specialists, regional packaging converters, and volume-driven private-label suppliers. Capacity expansion and strategic partnerships dominate competitive moves as suppliers secure qualified coating chemistry and compostability certification.
Among North American fabricators, Bedford Industries exemplifies the integrated specialist archetype through captive wire-coating capabilities. Plas-Ties occupies a position within the European compliance-focused tier, while Zhenjiang Hongda Commodity represents the scale-driven segment serving private-label supermarket programs. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive positioning vectors across premium certification, regional compliance, and cost-engineered volume tiers.
| Leading Market Players |
|---|
| Bedford Industries |
| Plas-Ties |
| Twist-Ease |
| AndFel Corporation |
| Felins USA |
| Multi-Pak USA |
| Allied Plastics |
| Zhenjiang Hongda Commodity |
| AmeriTwist |
| Others |
Value Network & Pricing Analysis
Water-soluble PVOH coating adoption in German and French fresh produce channels simultaneously redraws supply geography toward polymer development specialists and compresses pricing premiums for legacy polyolefin-sheathed inventories. This substitution dynamic concentrates procurement power with qualified vendors possessing in-house coating chemistry capabilities while eroding margins for converters dependent on outsourced materials.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the twist tie market. Price differentiation stems from FDA 21 CFR certification grade and tensile load rating, with heavy-duty 15+ pound variants commanding substantial premiums over standard 5-10 pound consumer grades. Cost compression in standard-grade tiers is intensifying because galvanized wire input volatility and REACH reformulation expenses squeeze converter margins. Supermarket buying groups exhibit the highest price sensitivity through centralized procurement, while industrial cable management contractors prioritize breakage tolerance over unit cost.
Supply Chain Analysis
China and India anchor global twist tie manufacturing through concentrated galvanized wire core production in Jiangsu, Zhejiang, and Gujarat industrial corridors. Raw material dependencies draw from zinc coating operations, polymer sheath extrusion capacity, and food-grade pigment supply chains. Single-source vulnerability concentrates in East Asian coating capacity where over sixty percent of global polymer-sheath extrusion sits in concentrated manufacturing zones. Distribution runs through Rotterdam and Hamburg as primary entry points for Asian-manufactured components into European retail supply chains, with secondary flows reaching North American ports for industrial heavy-duty applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The twist tie market sits in early-cycle expansion as biodegradable material R&D achieves cost parity with conventional plastics in Scandinavian pilot programs, signaling penetration inflection ahead of mandated plastic phase-outs.
For Market Incumbents: Compound defensive positioning through captive coating chemistry capabilities and accelerated compostability certification investments. Threats from water-soluble PVOH substitutes and REACH Annex XVII enforcement timelines demand backward integration into polymer development to sustain supplier qualification status. Priority lever rests on securing TÜV and BPI approvals ahead of regulatory deadlines to lock in German and Dutch retail contracts. For New Entrants and Emerging Players: Lead with industrial cable management specialization targeting data center and renewable energy installation markets in the United States and Germany where heavy-duty specification premiums offset volume scale disadvantages. The most penetrable white-space sits in e-commerce fulfillment bundling through third-party logistics providers, with go-to-market execution anchored on corrugated box compression and cable organization applications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-label supermarket suppliers lacking in-house polymer development capabilities and facing stranded inventory risk from EU Single-Use Plastics Directive timelines. Long-term viability over a multi-year window favors targets with certified biodegradable formulations and established relationships with pan-European buying groups. Signal to monitor: compostability certification approval velocity relative to mandated phase-out deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Development | Captive coating chemistry capabilities secure REACH compliance and German retail procurement relationships. |
| Compostability Certification Acceleration | TÜV and BPI approvals ahead of regulatory deadlines lock in Dutch and Scandinavian supermarket contracts. |
| Industrial Heavy-Duty Capacity Expansion | 15+ pound tensile rating production serves data center construction demand in the United States and Germany. |
| Extended Producer Responsibility Program Launch | California and New York packaging waste laws create first-mover advantage for certified recycled-content offerings. |
| E-commerce Fulfillment Channel Partnership | Third-party logistics provider relationships penetrate corrugated box compression and cable organization applications. |
Research Methodology
A spread of perspectives from polymer R&D directors, supermarket category buyers, wire-coating plant managers, and industrial procurement officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, REACH regulatory filings, FDA 21 CFR guidance documents, and SEC filings from listed packaging converters. Bottom-up volume modeling across material type, application, and form factor segments triangulated with top-down macroeconomic indicators to establish market sizing.
Segmentation dimensions modeled include material chemistry tier, food-contact versus industrial application, distribution channel structure, and load rating specification across the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory enforcement timelines and substitution elasticity parameters. Industry-specific forecast inputs incorporated ECHA plasticizer restriction implementation schedules and German retail automation adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement, stable zinc input costs, or continued fresh produce packaging automation would require recalibration. Forecasts reflect documented assumptions regarding REACH Annex XVII compliance timelines and EU Single-Use Plastics Directive phase-out adherence. Specific risks that could revise projections include accelerated biodegradable material cost parity, tariff disruption to East Asian coating capacity, or adhesive clip substitution advances in bread and produce bagging. Recalibration cycles align with material shifts in regulatory enforcement velocity and raw material input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
China Packaging Market
Packaging Materials
Box and Carton Overwrap Films Market