
 Primary Packaging Market | 2026-2036
Primary Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Packaging Market Intelligence
Manufacturing capacity expansion in India is fragmenting the supply base for commodity packaging formats. Amcor plc leverages its global scale to serve multinational food and beverage clients. Sonoco Products specializes in rigid paper and composite can solutions for a diverse customer base. In contrast, Schott Pharma dominates the high-value pharmaceutical glass vial and syringe segment, demonstrating deep specialization.
Primary packaging refers to the layer of material in direct contact with a product, serving as its principal containment. Its core function is to protect the contents from contamination, physical damage, and environmental factors like moisture or light. Plastic bottles and metal cans continue to lead in volume, particularly within the food and beverage application. However, blister packs and advanced glass vials for pharmaceuticals represent the highest-margin categories, driven by stringent quality and safety requirements.
Regulatory frameworks from the US FDA, Europe's EMA, and China's NMPA dictate material safety standards, especially for food-contact and pharmaceutical-grade packaging. These bodies enforce strict protocols on extractables and leachables, directly influencing material choices and validation costs. The central strategic decision for manufacturers is balancing the push toward sustainable, biodegradable polymers with the performance and barrier properties of traditional materials.
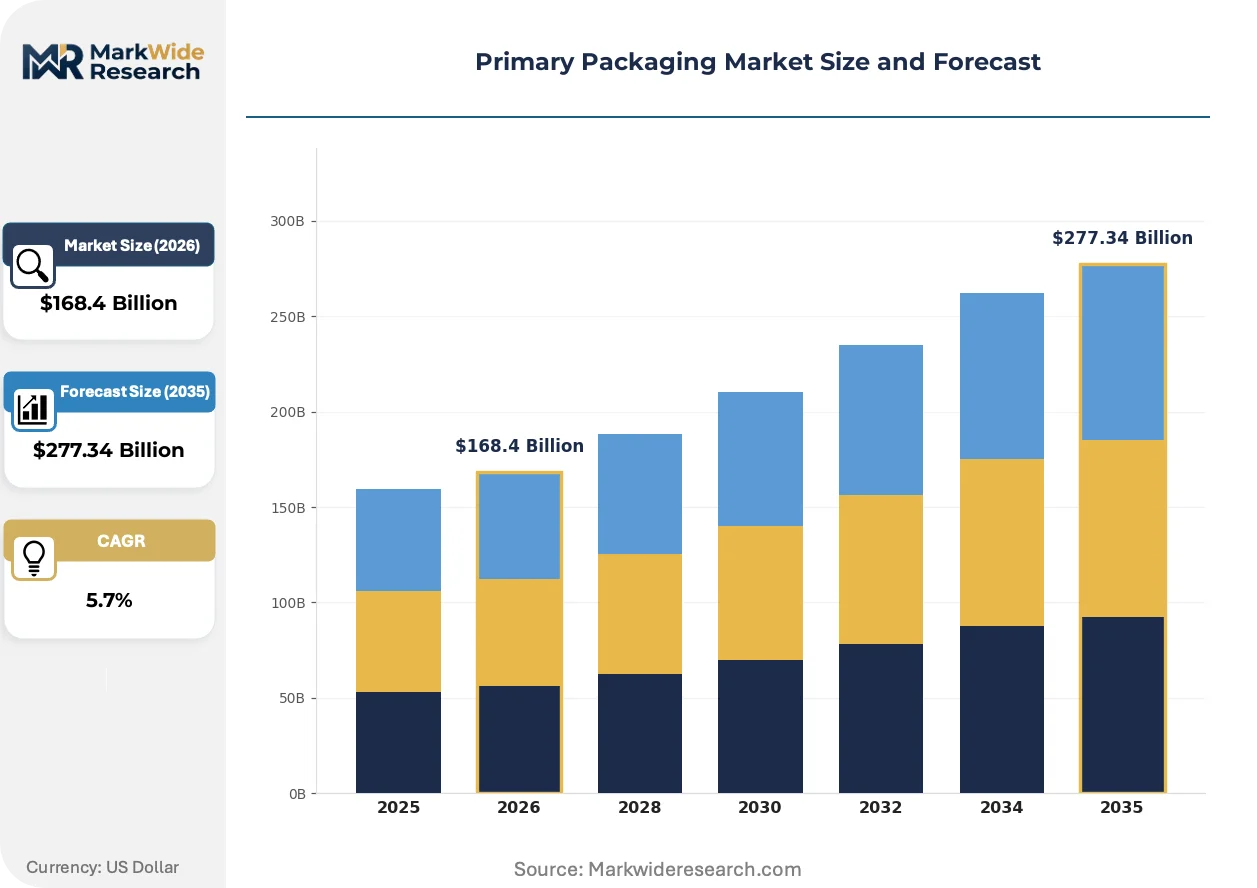
Market Dynamics
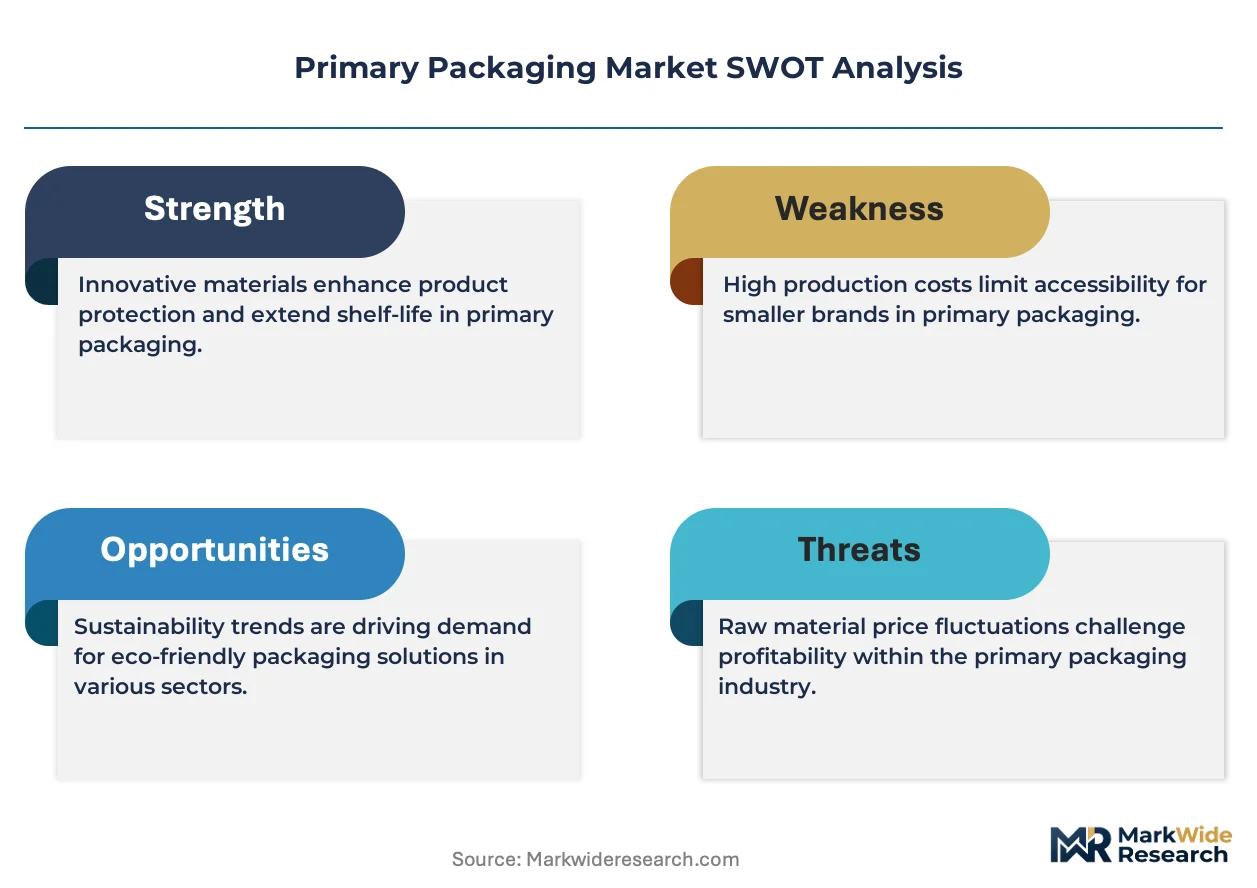
The central tension defining the primary packaging market is the conflict between stringent regulatory mandates for sustainability, such as the EU Green Deal, and the unyielding performance requirements for product protection, particularly in the pharmaceutical and food sectors.
Growth Catalysts
- Recycled Content Mandates:European Union regulations requiring minimum post-consumer recycled (PCR) content in plastic packaging are compelling brand owners to secure long-term supply of food-grade rPET and other recycled polymers, stimulating investment in advanced recycling.
- Chinese Consumer Market:The expansion of China's food, beverage, and personal care industries creates substantial volume demand for commodity formats like flexible films, plastic bottles, and metal cans to serve a growing urban consumer base.
- Aseptic Processing Technologies:Advances in aseptic and extended shelf-life (ESL) filling technologies enable the use of lightweight cartons and pouches for sensitive products like dairy alternatives and juices, displacing heavier glass and metal containers.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of crude oil and natural gas create significant price volatility for virgin polymer resins like polyethylene (PE) and polypropylene (PP), complicating cost management for converters.
- Biodegradable Material Limitations:Many current-generation biodegradable and compostable polymers lack the robust gas and moisture barrier properties of conventional plastics, limiting their application for sensitive, long-shelf-life products without additional, often non-compostable, layers.
- Regulatory Validation Costs:The rigorous and costly extractables and leachables (E&L) testing protocols mandated by the FDA and EMA for new pharmaceutical-contact materials act as a significant barrier to innovation and rapid material substitution.
Strategic Opportunities
- High-Barrier Mono-Materials:Developing mono-material flexible packaging, such as all-polyethylene pouches, that provides sufficient barrier protection while being fully compatible with existing recycling streams presents a major commercial opportunity.
- Pharmaceutical Packaging in India:Supplying advanced sterile packaging, including pre-fillable syringes and coated vials, to India's expanding pharmaceutical export manufacturing base offers a high-value growth avenue for specialized suppliers.
- Smart Packaging Integration:Incorporating sensor technology for temperature, integrity, and authentication into primary packs for high-value goods like biologics, vaccines, and luxury cosmetics opens new service-based revenue models.
Industry Challenges
- Capital Investment for Retooling:Converting production lines from manufacturing traditional multi-material laminates to new, recyclable mono-material structures requires significant capital expenditure and process requalification, slowing industry-wide transition.
- Fragmented EPR Schemes:The lack of harmonization in Extended Producer Responsibility (EPR) regulations and fee structures across different countries and even sub-national jurisdictions creates significant compliance complexity and cost for multinational brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Packaging Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $277.34 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Metal, Paperboard, Biodegradable Polymers Packaging Format: Bottles, Cans, Blister Packs, Sachets, Tubes, Jars Application: Pharmaceuticals, Cosmetics, Food & Beverages, Household Chemicals, Agricultural Products, Personal Care End User: Drug Manufacturers, Beauty Brands, Food Producers, Chemical Firms, Agrochemical Companies, Consumer Goods Corporations |
| Companies Covered | Ardagh Group, Sonoco Products, Amcor plc, Smurfit Kappa, Schott Pharma, Berry Global, West Pharmaceutical Services, International Paper, Mondi plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Packaging Market Strategic Shifts & Innovations
Material science innovation is colliding with circular economy principles, forcing a re-evaluation of packaging design. This dynamic prioritizes solutions that reduce material footprint and improve recyclability without compromising essential product protection and safety functions, especially in regulated end-markets.
Technology and Product Evolution
Active barrier coatings applied as ultra-thin layers onto polymer films are a key area of material science development. The food and beverage sector is adopting this technology to enhance the oxygen and moisture resistance of standard PET or PE films. This technology is hybridizing commodity substrates with high-performance functionality, creating a pathway to replace complex, non-recyclable multi-layer laminates with more sustainable mono-material alternatives.
Regulatory and Policy Shifts
The European Union’s Packaging and Packaging Waste Regulation (PPWR) is a pivotal policy driver. It establishes legally binding targets for recycled content, reuse, and waste reduction, fundamentally altering design and material selection criteria. Manufacturers of rigid plastic containers for consumer goods are most directly impacted, accelerating investment in chemical recycling to produce food-contact grade recycled polymers and redesigning packs for easier disassembly.
Demand-Side and Behavioral Shifts
A notable behavioral change is the adoption of refillable and reusable packaging systems by major consumer brands. This model directly challenges the dominant single-use paradigm in categories like home care, personal care, and beverages. This trend is most pronounced in Western Europe, where retailer-led initiatives and supportive consumers are creating viable ecosystems for returnable packaging loops.
Primary Packaging Market Segmentation
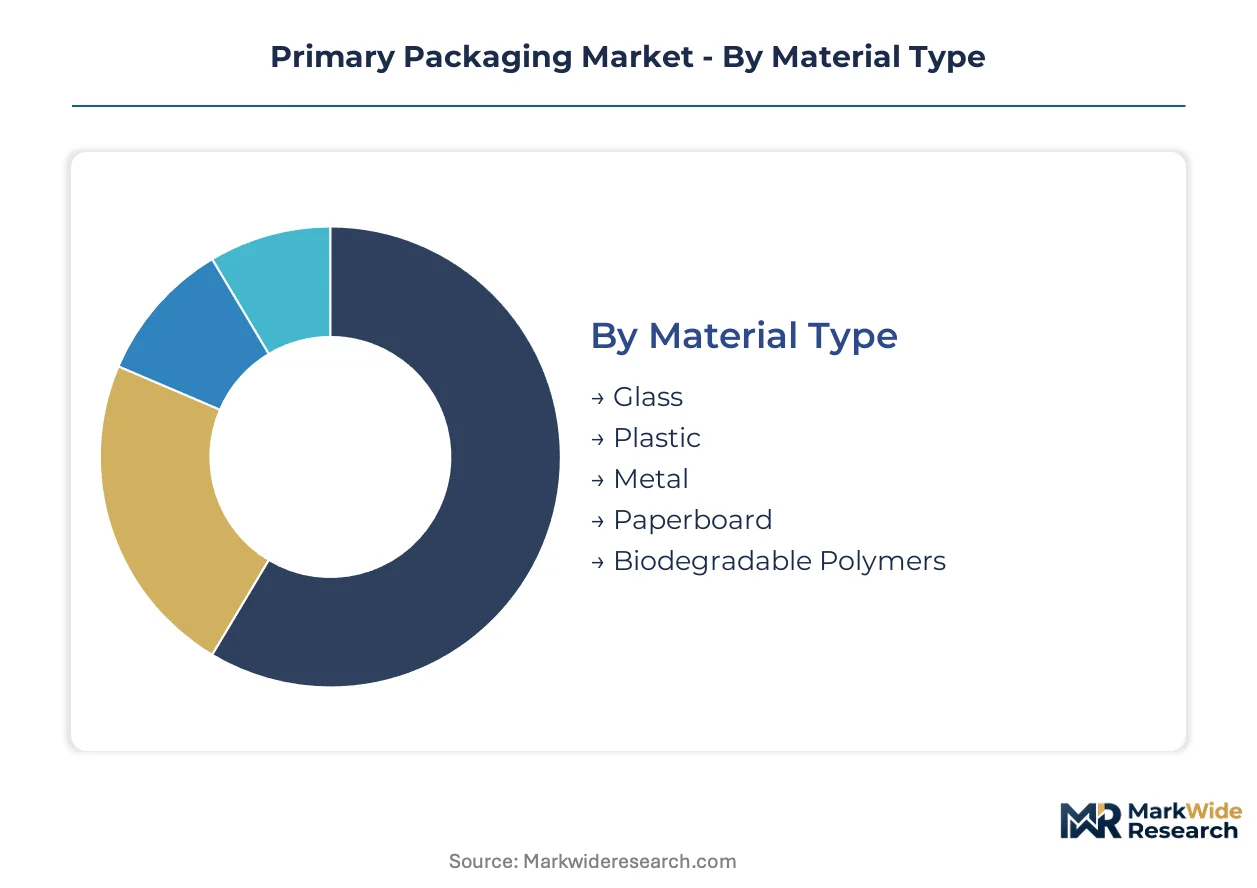
Understanding the primary packaging market requires a granular view of its diverse components. Product protection requirements vary significantly across industries, influencing material selection and format innovation. This segmentation highlights the critical intersections between material science, functional design, and end-user demand.
Material Type:
Material composition dictates the fundamental barrier properties and sustainability profile of primary packaging. Each material type offers distinct advantages and faces specific challenges in meeting evolving market demands.
- Plastic:Polymeric resins form lightweight, versatile containers, offering excellent barrier properties for many products. Demand concentrates in the food and beverage sector across China, driven by convenience and cost-effectiveness.
- Glass:Inert, transparent silicate material provides superior product integrity and aesthetic appeal, particularly for sensitive formulations. Pharmaceutical demand for vials and ampoules is high in Germany, supported by stringent quality standards.
- Metal:Aluminum and steel provide robust barrier protection against light, oxygen, and moisture for canned goods.
- Paperboard:Renewable cellulose fibers form cartons and boxes, widely used for dry foods and secondary packaging.
- Biodegradable Polymers:Plant-based or synthetic polymers offer compostable or bio-assimilable options for environmentally conscious brands.
Plastic holds installed capacity. Biodegradable Polymers are rotating up the share rankings.
Packaging Format:
Functional design defines how products are contained, protected, and dispensed, directly impacting user experience and supply chain logistics.
- Bottles:Rigid containers, often plastic or glass, provide secure liquid containment and dispense functionality for beverages and personal care items. Volume demand is substantial in the US market for bottled water and soft drinks.
- Blister Packs:Thermoformed plastic cavities sealed with a lidding material offer unit-dose protection and tamper evidence for pharmaceuticals. Pharmaceutical manufacturers in India increasingly adopt these for precise dosage and patient compliance.
- Cans:Metal containers provide hermetic sealing and extended shelf life for food and carbonated beverages.
- Sachets:Flexible, small-format pouches deliver single-serve portions for condiments, powders, and personal care samples.
- Tubes:Collapsible cylindrical containers dispense viscous products like toothpaste, creams, and gels.
- Jars:Wide-mouthed rigid containers, typically glass or plastic, store creams, spreads, and preserves.
Bottles maintain high volume. Blister Packs expand most quickly.
Application:
End-use industry requirements drive specific packaging innovations, balancing product protection with regulatory compliance and consumer appeal.
- Food & Beverages:This segment requires diverse packaging solutions to preserve freshness, extend shelf life, and ensure consumer safety. Convenience and sustainability trends influence material choices across European markets.
- Pharmaceuticals:Stringent regulatory requirements for product integrity, sterility, and tamper evidence characterize this high-value segment. Advanced glass vials and pre-filled syringes dominate specialized drug delivery in Japan.
- Cosmetics:Aesthetic appeal and product protection against degradation are central to packaging for skincare, makeup, and fragrances.
- Household Chemicals:Robust, child-resistant containers are essential for detergents, cleaners, and other home care products.
- Agricultural Products:Packaging protects seeds, fertilizers, and pesticides from environmental factors, often requiring durable, moisture-resistant materials.
- Personal Care:Shampoos, lotions, and soaps utilize a variety of plastic bottles, tubes, and jars for convenience and branding.
Food & Beverages drives substantial volume. Pharmaceuticals show the steepest expansion trajectory.
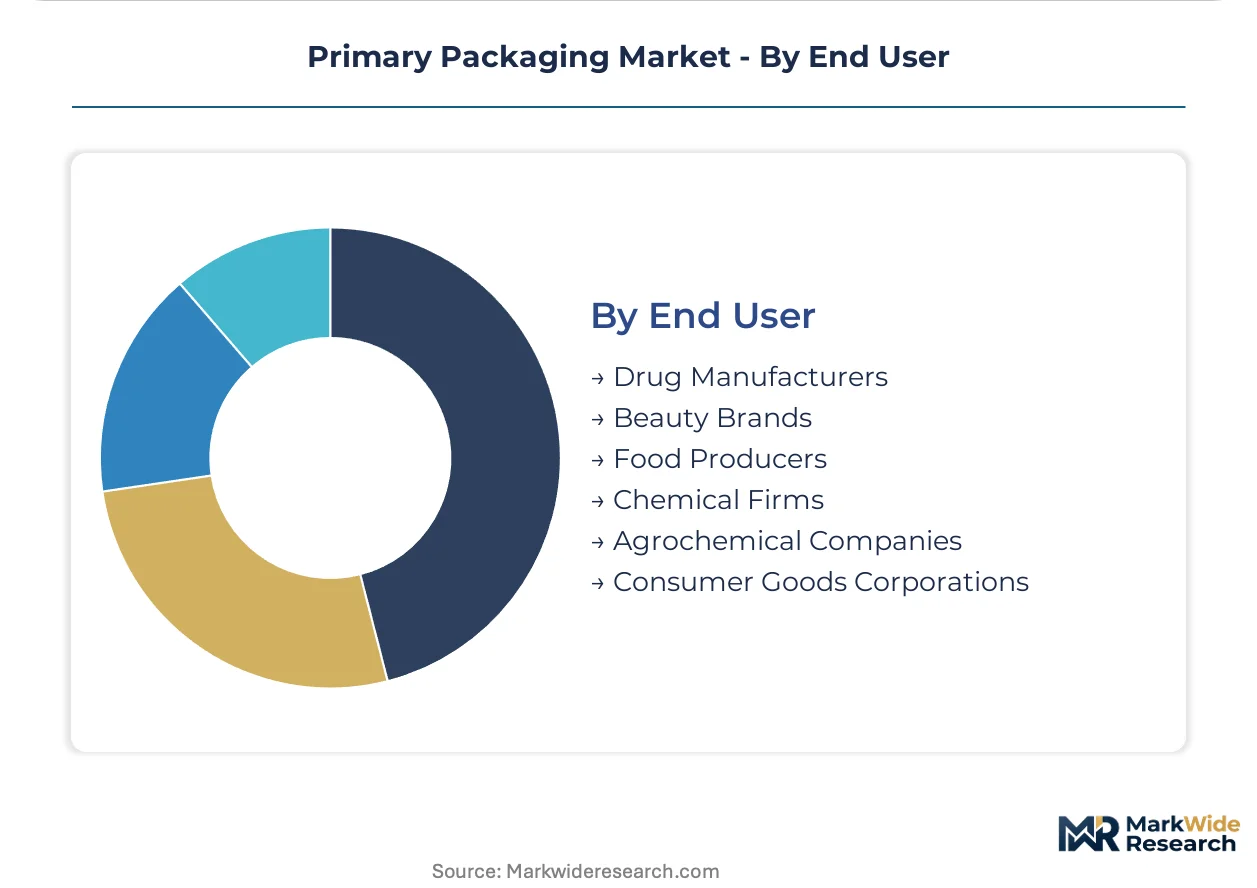
End User:
Customer operational models influence packaging procurement decisions, focusing on supply chain efficiency, cost, and regulatory adherence.
- Food Producers:These entities require high-volume, cost-effective packaging solutions that ensure product safety and extend shelf life for a wide range of perishable goods. Supply chain efficiency drives material selection for large-scale operations in Brazil.
- Drug Manufacturers:Pharmaceutical companies demand sterile, compliant, and often specialized primary packaging to protect sensitive drug formulations and meet regulatory standards. Validation costs are a significant factor for new suppliers in the US.
- Beauty Brands:Packaging for cosmetics emphasizes aesthetic design, brand differentiation, and product preservation, often utilizing premium materials.
- Chemical Firms:Industrial and household chemical producers require durable, chemical-resistant packaging with clear labeling and safety features.
- Agrochemical Companies:These companies need robust, tamper-evident packaging for pesticides, herbicides, and fertilizers, capable of enduring harsh conditions.
- Consumer Goods Corporations:Diverse packaging needs span multiple product categories, focusing on convenience, sustainability, and brand recognition for mass-market appeal.
Food Producers command significant purchasing power. Drug Manufacturers prioritize specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The primary packaging market exhibits varied regional dynamics, with supply-side concentration influencing material availability and innovation pathways. China, for example, represents a significant production hub for commodity packaging formats, driven by its vast domestic consumer market and export capabilities. This concentration impacts global pricing and supply chain resilience for many basic packaging components.
China
Expanding food, beverage, and personal care industries drive substantial demand for flexible films and plastic bottles in China. The NMPA and GB standards dictate material safety, particularly for food-contact applications. Manufacturing clusters in the Yangtze River Delta region focus on high-volume production of diverse packaging solutions for both domestic consumption and international markets.
United States
Demand for primary packaging in the United States stems from its large food & beverage sector and advanced pharmaceutical industry. The US FDA mandates rigorous extractables and leachables testing for drug-contact materials, influencing innovation in pharmaceutical vials. Packaging manufacturers in the Midwest and Northeast regions concentrate on developing high-performance plastic and glass solutions.
Germany
Germany's primary packaging market is shaped by stringent sustainability goals and a strong pharmaceutical manufacturing base. The EU Green Deal and Packaging and Packaging Waste Regulation (PPWR) compel investment in recycled content and monomaterial designs. Specialized production facilities in Bavaria and North Rhine-Westphalia lead in pharmaceutical glass vials and advanced sustainable packaging solutions.
India
India's pharmaceutical export manufacturing base creates a substantial requirement for advanced sterile packaging formats like pre-fillable syringes. The CDSCO sets quality and safety standards for pharmaceutical packaging materials within the country. Major packaging hubs in Gujarat and Maharashtra are expanding capacity to support the growing domestic and international drug markets.
Japan
Japanese demand centers on high-quality pharmaceutical packaging and advanced materials for sensitive products. The PMDA ensures strict regulatory oversight for medical device and drug packaging. Research and development in the Kanto region focuses on active barrier coatings and smart packaging integration for enhanced product protection and consumer interaction.
Primary Packaging Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, shaping the primary packaging market's competitive dynamics. The market structure features a tiered landscape, with global diversified players alongside specialized regional manufacturers. Strategic archetypes include large-scale commodity producers, high-value pharmaceutical packaging specialists, and sustainable material innovators. Dominant competitive moves involve strategic partnerships for material innovation and targeted capacity expansion in high-growth segments.
Specialists in high-value pharmaceutical glass vials and syringes, such as Schott Pharma GmbH, exemplify deep expertise in regulated segments. Global packaging leaders like Amcor plc leverage extensive manufacturing networks to serve multinational food and beverage clients with diverse material formats. Sonoco Products Company occupies a distinct position, specializing in rigid paper and composite can solutions for a broad industrial and consumer base, showcasing material-specific focus.
| Leading Market Players |
|---|
| Ardagh Group |
| Sonoco Products |
| Amcor plc |
| Smurfit Kappa |
| Schott Pharma |
| Berry Global |
| West Pharmaceutical Services |
| International Paper |
| Mondi plc |
Cost & Logistics Intelligence
Input cost volatility for virgin polymer resins like polyethylene and polypropylene determines both pricing tier spreads and the supply chain shape for primary packaging. This fluctuation complicates cost management for converters and influences material selection decisions across the industry.
Pricing Analysis
The EU Green Deal and Packaging and Packaging Waste Regulation (PPWR) dictate the pricing tier structure, especially for sustainable primary packaging. Pricing largely follows a contract-based long-term offtake model, with differentiation driven by certification level for pharmaceutical-grade materials and volume scale for commodity formats. Pricing pressure intensifies due to the capital investment required for retooling production lines for mono-materials. Food producers exhibit high price sensitivity for commodity packaging, while drug manufacturers prioritize specialized solutions, showing less price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive nature of primary packaging production. Supply concentration centers on China for commodity formats, while Germany and India are key for pharmaceutical glass vials and sterile packaging. The supply chain relies on virgin polymer resins and glass cullet, creating dependency on upstream chemical and glass industries. Fragmented Extended Producer Responsibility schemes across jurisdictions pose a significant structural risk, complicating material flow and cost recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The primary packaging market is undergoing a high-growth disruption, driven by the EU Green Deal's mandates for recyclability and recycled content. This regulatory inflection forces a re-evaluation of material science and packaging design across the industry.
For Market Incumbents:Insulate core business segments by investing in advanced recycling technologies to secure food-grade recycled polymers. Simultaneously, deepen R&D into high-barrier mono-materials to counter the performance limitations of current biodegradable options. Expand specialized sterile packaging capacity in India, leveraging its pharmaceutical export manufacturing base to mitigate regulatory validation costs for new materials.
For New Entrants and Emerging Players:India's pharmaceutical export manufacturing base presents a significant underpenetration for advanced sterile primary packaging. New entrants should target this market with specialized solutions like pre-fillable syringes and coated vials. A go-to-market angle focusing on rapid regulatory compliance and localized manufacturing can capture high-value segments.
For Investors and Strategic Acquirers:The market sits at a transformative growth phase that favors specialized material science innovators and compliant pharmaceutical packaging providers. Long-term viability remains strong for companies offering solutions that balance sustainability mandates with stringent product protection. Investors should target mid-cap firms with proprietary high-barrier mono-material technologies or established positions in advanced sterile packaging. The adoption rate of mono-material flexible packaging in the food and beverage sector signals broader industry transition.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increase production of advanced sterile packaging in India to support pharmaceutical exports. |
| Green Manufacturing Transition | Implement chemical recycling processes to produce food-contact grade recycled polymers for EU markets. |
| Product Launch | Introduce new high-barrier mono-material flexible films compatible with existing recycling streams. |
| Strategic Partnership | Collaborate with sensor technology firms to integrate smart packaging features for biologics authentication. |
| Regulatory Approval Pathway | Accelerate FDA and EMA validation for new pharmaceutical contact materials to reduce market entry barriers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU Green Deal policy documents, FDA guidance, and industry association reports. This study incorporates insights from interviews with packaging R&D directors, pharmaceutical procurement managers, and food & beverage brand managers. Both bottom-up and top-down triangulations ensure data consistency and market sizing accuracy.
Forecast inputs being considered include raw material price volatility and evolving regulatory landscapes across the analysis window. The analytical framework segments the market by material type, packaging format, application, end user, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends and projected future growth drivers, such as recycled content mandates and aseptic processing technology adoption.
Practitioners should monitor geopolitical shifts affecting trade and unexpected material science breakthroughs for early signals of market shifts. These forecasts reflect assumptions documented across the analysis period. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Punnet Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Card Films Market
Packaging Materials
US Packaging Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Metallized Rollstock Film Market