
 MDO Films Market | 2026-2036
MDO Films Market Size, Share, and Industry Trends Forecast 2026-2036
MDO Films Market Outlook
ASTM D882 tensile qualification is unwinding competitive access for converters lacking calibrated MDO line capabilities. Amcor leverages its integrated film-to-package pipeline across European food contracts. Berry Global sustains manufacturing scale through captive resin partnerships and multi-site extrusion networks. Klöckner Pentaplast differentiates via pharmaceutical-grade cleanroom certification and barrier layer precision.
Machine direction oriented films are polyolefin substrates stretched uniaxially during extrusion to achieve controlled shrinkage, elevated tensile strength, and thickness reduction down to sub-twenty-micron gauges for lightweight packaging. Polypropylene grades dominate current volume owing to stiffness-to-weight performance in label and overwrap applications, while biodegradable formulations represent the fastest-expanding margin pool as EU packaging directives harden material substitution timelines. Coating technology commands premium positioning where multi-layer barrier specifications exceed standard extrusion limits.
EMA medical device packaging standards, FDA food contact notification requirements, and EU REACH substance restrictions collectively govern resin selection, additive migration limits, and market access pathways for film suppliers. These frameworks compel converters to maintain dual-certification portfolios and traceable supply documentation. Stakeholders must calibrate capital allocation between biopolymer R&D scale-up and legacy polyolefin line retrofitting as regulatory thresholds diverge across destination markets.
Market Dynamics
EU F-Gas Regulation phase-down schedules and REACH substance restrictions are compressing incumbent fluoropolymer supply chains while accelerating converter investment in bio-based polypropylene alternatives. This regulatory compression is redrawing competitive access around certified MDO line capabilities and traceable resin documentation systems.
Growth Catalysts
- High-barrier food packaging formats:Retail meat and cheese processors are specifying MDO-PE structures to replace multi-material laminates under extended producer responsibility frameworks.
- REACH SVHC disclosure mandates:Film converters with full additive traceability are capturing pharmaceutical contract volumes as ECHA substance restrictions tighten migration limits.
- Germany's converter corridor:Dense clustering of extrusion lines around BASF and LyondellBasell polymer hubs enables just-in-time resin delivery and technical service proximity.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in Northwest Europe transmit directly to MDO-PP margin compression for non-integrated converters.
- Biopolymer scale limitations:Industrial composting infrastructure gaps in France and Italy constrain certified biodegradable film uptake despite regulatory mandates.
- Coating equipment concentration:Vacuum metallization and PVD coating line supply concentrates among three German and Austrian equipment builders, creating 14-month delivery backlogs.
Strategic Opportunities
- Pharmaceutical serialization compliance:EU MDR unique device identification requirements are opening specification windows for tamper-evident MDO-PP lidding films with integrated tear-initiation features.
- Poland and Czech Republic converter expansion:Lower energy costs and available skilled extrusion labor are attracting MDO line investments from Western European film specialists.
- Digital printing substrate compatibility:Water-based ink adhesion improvements on corona-treated MDO films are enabling short-run label production for craft beverage brands.
Industry Challenges
- MDO line operator scarcity:Stretch ratio calibration and gauge control expertise requires 18-24 month apprenticeship periods that outpace available technical training program output.
- Dual-certification documentation burden:Maintaining parallel FDA food contact notification and EFSA compliance dossiers consumes 12-15% of quality assurance headcount at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MDO Films Market |
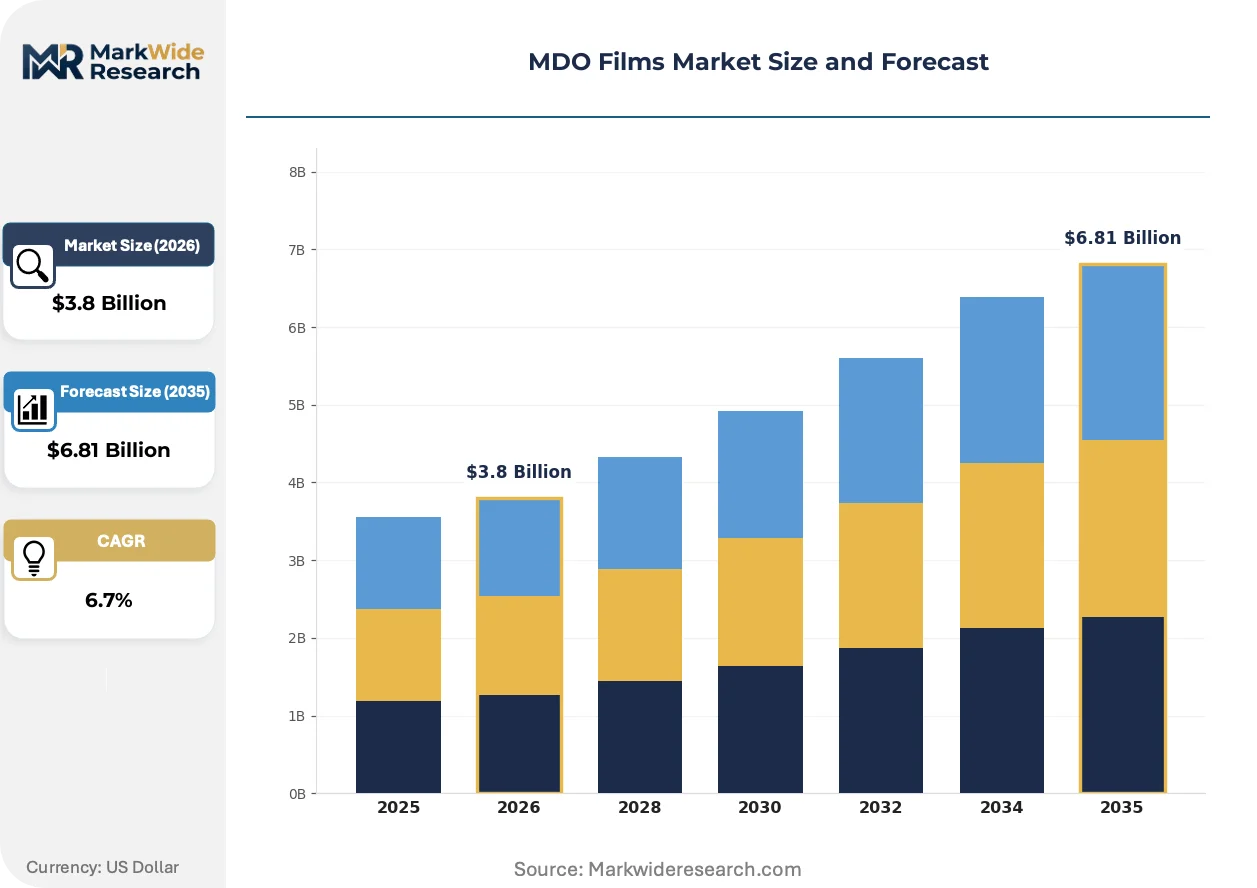
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polymer Blends, Biodegradable Application: Packaging, Agriculture, Automotive, Electronics End User: Food Industry, Retail, Pharmaceuticals, Consumer Goods Technology: Extrusion, Coating, Laminating, Printing |
| Companies Covered | Avery Dennison Corporation, CCL Label Eclipse Films, Amcor, Borealis AG, Berry Global, ExxonMobil, UPM Raflatac, Klöckner Pentaplast, NOWOFOL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MDO Films Market Strategic Shifts
Active alignment between film surface engineering and downstream converting equipment is compressing development cycles. Coating chemistries and orientation protocols are converging around specific end-use performance thresholds rather than generic material specifications.
Water-based barrier coatings with graphene oxide nanofillers are displacing conventional EVOH coextrusion in chilled food lidding applications. Ready-meal processors in the Netherlands and Belgium are qualifying these structures for 21-day shelf life targets. The technology is displacing established five-layer coextrusion lines that require fluoropolymer tie layers now restricted under F-Gas Regulation quotas.
EU REACH Annex XIV authorization requirements for phthalate plasticizers are forcing reformulation of standard PP impact modifiers. Compounders serving the MDO film segment are accelerating migration to bio-based citrate and adipate alternatives. Pharmaceutical blister packaging manufacturers in Germany and Switzerland are demanding full substance inventory disclosure to preempt future SVHC listing disruptions.
Brand-owner sustainability scorecards are restructuring procurement qualification criteria. Major European dairy and meat processors are prioritizing film suppliers with ISCC PLUS mass-balance certification over conventional price-competitive tenders. This behavioral shift is most pronounced in Nordic markets where retailer climate pledges have advanced ahead of regulatory minimums.
MDO Films Market Segmentation
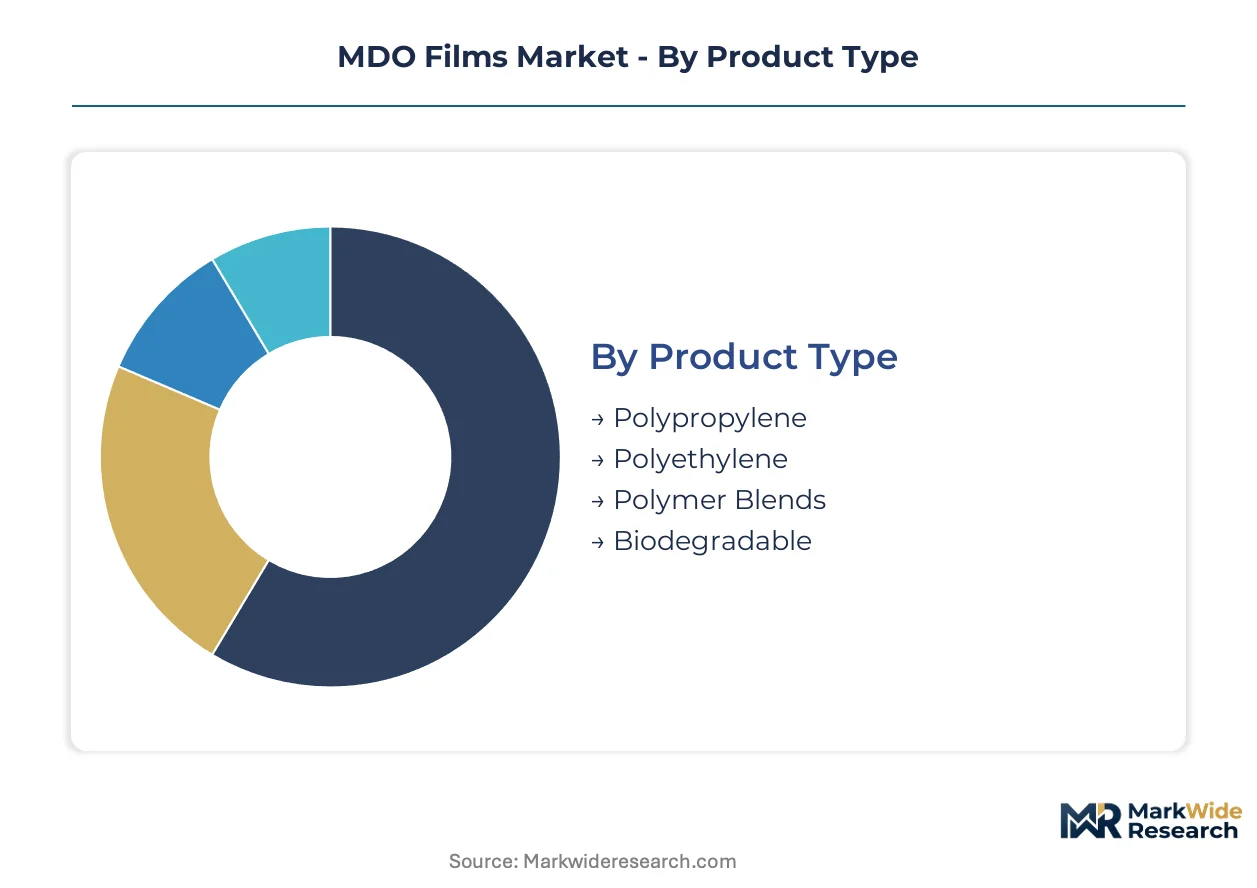
MDO film specifications diverge sharply across substrate chemistry, end-use performance thresholds, and converting technology. Procurement decisions hinge on barrier requirements, regulatory compliance documentation, and line compatibility with existing packaging equipment.
Product Type:
Margin pools concentrate in specialty grades where regulatory pressure on legacy polymers creates substitution premiums and certification scarcity.
- Polypropylene:Stiffness-to-weight ratios of oriented PP grades enable downgauging to sub-twenty-micron specifications for label and overwrap applications. Demand clusters around Germany's converter corridor where technical service proximity to BASF and LyondellBasell polymer hubs enables just-in-time resin qualification.
- Biodegradable:Bio-based polypropylene alternatives are capturing share as EU F-Gas Regulation phase-down schedules compress fluoropolymer supply chains and REACH substance restrictions tighten migration limits. Industrial composting infrastructure gaps in France and Italy currently constrain uptake velocity despite regulatory mandates.
- Polyethylene:MDO-PE structures are displacing multi-material laminates in retail meat and cheese packaging under extended producer responsibility frameworks.
- Polymer Blends:Impact-modified compounds serve pharmaceutical blister applications requiring cold-forming ductility.
Polypropylene holds installed capacity. Biodegradable is rotating up the share rankings.
Application:
Volume concentration tracks food contact compliance burdens and barrier specification intensity.
- Packaging:High-barrier food packaging formats dominate procurement specifications, with MDO-PE and MDO-PP structures replacing conventional laminates. Ready-meal processors in the Netherlands and Belgium are qualifying water-based barrier coatings with graphene oxide nanofillers for twenty-one-day shelf life targets.
- Pharmaceuticals:EU MDR unique device identification requirements are opening specification windows for tamper-evident MDO-PP lidding films with integrated tear-initiation features. EMA medical device packaging standards and FDA food contact notification requirements govern resin selection and additive migration limits.
- Agriculture:Mulch films and silage wrap applications specify UV-stabilized grades with controlled degradation profiles.
- Electronics:Static-dissipative coatings on oriented substrates serve component packaging for sensitive semiconductor devices.
Packaging commands the largest installed base. Pharmaceuticals is gaining share fastest on serialization compliance requirements.
End User:
Procurement authority concentrates with brand owners operating sustainability scorecards and mass-balance certification programs.
- Food Industry:Retail meat and cheese processors are specifying MDO-PE structures to replace multi-material laminates. Major European dairy and meat processors prioritize suppliers with ISCC PLUS mass-balance certification over conventional price-competitive tenders, particularly in Nordic markets where retailer climate pledges have advanced ahead of regulatory minimums.
- Pharmaceuticals:Blister packaging manufacturers in Germany and Switzerland demand full substance inventory disclosure to preempt future REACH SVHC listing disruptions. Dual-certification documentation burdens consume twelve to fifteen percent of quality assurance headcount at mid-scale converters serving this segment.
- Retail:Private-label overwrap and label applications drive volume throughput with standardized specifications.
- Consumer Goods:Craft beverage brands are adopting short-run label production enabled by water-based ink adhesion improvements on corona-treated MDO films.
Food Industry holds dominant procurement volume. Pharmaceuticals is climbing the fastest on compliance-driven specification windows.
Technology:
Equipment differentiation separates commodity converters from certified barrier specialists.
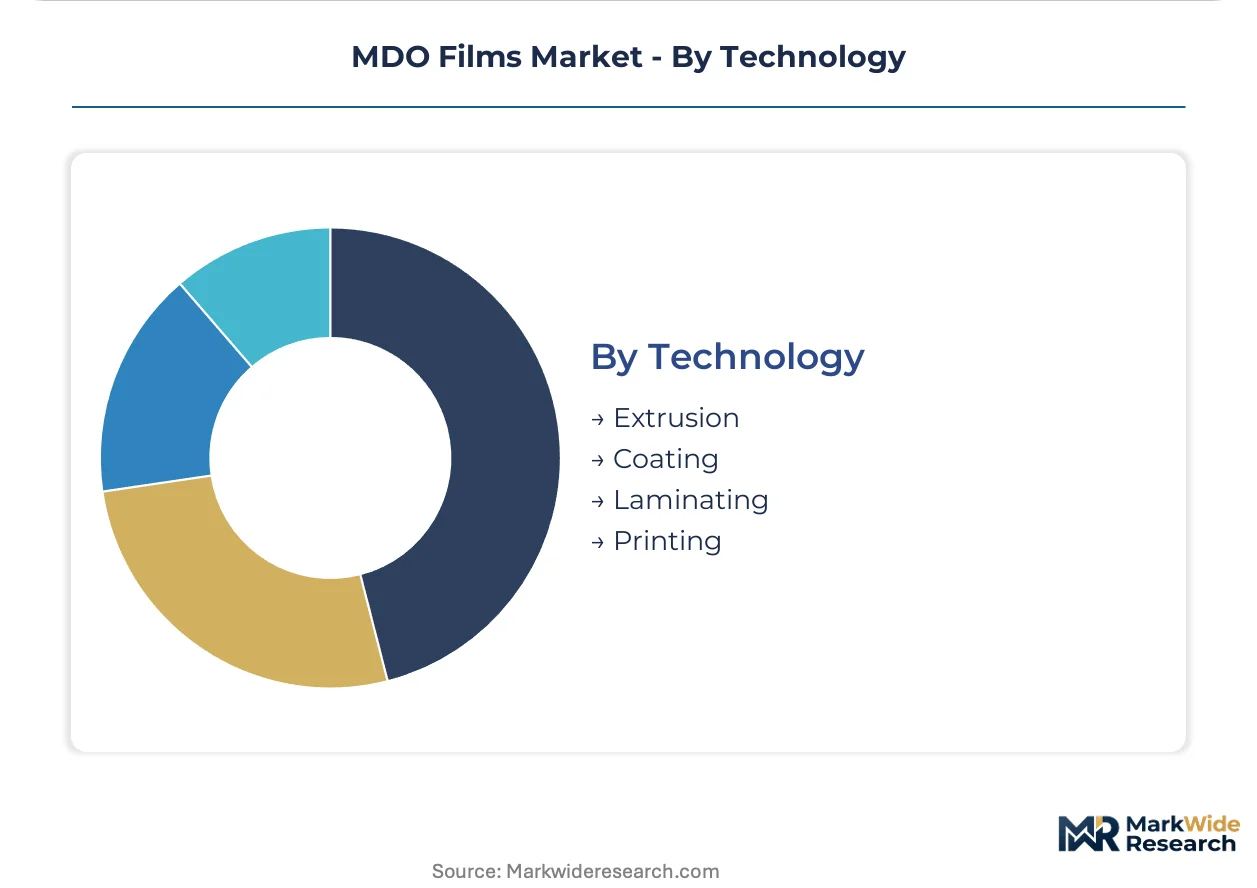
- Extrusion:Machine direction orientation protocols require stretch ratio calibration and gauge control expertise with eighteen to twenty-four month apprenticeship periods. ASTM D882 tensile qualification is unwinding competitive access for converters lacking calibrated MDO line capabilities.
- Coating:Vacuum metallization and PVD coating line supply concentrates among three German and Austrian equipment builders, creating fourteen-month delivery backlogs. Water-based barrier coatings with graphene oxide nanofillers are displacing conventional EVOH coextrusion in chilled food lidding applications.
- Laminating:Multi-layer adhesive bonding serves high-barrier specifications exceeding standard extrusion limits.
- Printing:Digital printing substrate compatibility is enabling short-run production for craft beverage brands.
Extrusion holds the deepest installed base. Coating is rotating up the share rankings on barrier specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processors and pharmaceutical contract manufacturers concentrate procurement authority in industrial corridors with polymer supply proximity and regulatory certification density. Converter networks cluster around major resin hubs where technical service and just-in-time logistics converge.
Germany
Blister packaging manufacturers in Baden-Württemberg and pharmaceutical converters near Frankfurt demand full REACH substance inventory disclosure. The EU F-Gas Regulation phase-down compresses fluoropolymer supply chains while accelerating bio-based PP qualification. BASF and LyondellBasell polymer hubs in Ludwigshafen and Cologne anchor dense extrusion line networks with 14-month coating equipment backlogs.
United States
FDA food contact notification requirements and EMA parallel dossiers drive dual-certification investments among mid-scale converters. Retail meat processors specify MDO-PE structures under extended producer responsibility frameworks emerging in California and New York. The Midwest polymer corridor around Houston and Chicago channels propylene feedstock to film specialists with ASTM D882 calibrated lines.
China
GB standards compliance and dual carbon goals redirect resin selection toward bio-based alternatives in Yangtze River Delta packaging clusters. NMPA medical device packaging standards govern pharmaceutical film exports to EU markets. Converter expansion concentrates in Zhejiang and Jiangsu provinces where extrusion equipment supply localizes.
Netherlands
Ready-meal processors in Rotterdam and Utrecht qualify water-based graphene oxide barrier coatings for 21-day shelf life targets. ECHA SVHC disclosure mandates capture pharmaceutical contract volumes as migration limits tighten. Coating technology providers cluster around Eindhoven with vacuum metallization line supply concentrated among German and Austrian equipment builders.
Switzerland
Swissmedic pharmaceutical packaging standards and cleanroom certification requirements differentiate barrier layer precision specialists. Dual-certification documentation burdens consume quality assurance headcount at converters serving EU and US markets simultaneously. Basel and Zurich anchor high-specification film development for tamper-evident lidding applications.
MDO Films Market Competitive Environment
Player mix skews toward integrated polymer-to-film specialists with captive resin partnerships and multi-site extrusion networks. Market structure concentrates around three strategic tiers: diversified packaging conglomerates with film-to-package pipelines, regional converters with certified MDO line capabilities, and specialty compounders serving pharmaceutical-grade specifications. Dominant competitive moves include backward integration into resin supply and geographic expansion into lower-cost extrusion labor markets.
Within the integrated packaging tier, Amcor and Berry Global exemplify scale-driven positions through multi-site manufacturing footprints and polymer supply control. Klöckner Pentaplast occupies a specialist position where pharmaceutical-grade cleanroom certification and barrier layer precision differentiate procurement access. Among diversified chemical conglomerates, Borealis AG and ExxonMobil anchor upstream resin positions that channel feedstock toward captive and third-party film converters. Avery Dennison Corporation represents the label substrate specialist archetype with corona-treated film development for digital printing compatibility.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Label Eclipse Films |
| Amcor |
| Borealis AG |
| Berry Global |
| ExxonMobil |
| UPM Raflatac |
| Klöckner Pentaplast |
| NOWOFOL |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with naphtha-indexed resin pricing lock in feedstock access for German and Dutch converters while compressing margin visibility for spot-market purchasers. These contracts tether MDO film pricing to Northwest European cracker output cycles, amplifying volatility transmission to non-integrated processors.
Pricing Analysis
Cost-plus contracts with propylene monomer indexation dominate procurement between polymer suppliers and film converters. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-label tiers reflects certification burden and barrier specification intensity. Pricing pressure stems from biopolymer scale limitations that prevent cost parity with conventional PP grades. Retail meat processors exhibit highest price sensitivity, while pharmaceutical blister manufacturers absorb premiums for REACH-compliant traceability.
Supply Chain Analysis
Inventory buffers stretch to fourteen months for vacuum metallization equipment sourced from German and Austrian builders. Raw material flows concentrate in Germany, Belgium, and the Netherlands where BASF and LyondellBasell polymer hubs anchor extrusion networks. Feedstock volatility in naphtha-cracker output and fluoropolymer restrictions under EU F-Gas Regulation constitute primary supply risks. Distribution runs through converter corridors with just-in-time resin delivery to food and pharmaceutical end-users.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDO film incumbents face substitution pressure from water-based graphene oxide barrier coatings that displace conventional EVOH coextrusion in chilled food lidding. Defending market position requires preemptive capability investments.
For Market Incumbents: Shield core food packaging volumes by accelerating ISCC PLUS mass-balance certification ahead of retailer sustainability scorecard deadlines. Backward integration into bio-based PP resin supply secures feedstock access as EU F-Gas Regulation compresses fluoropolymer availability. Coating equipment capacity expansion addresses fourteen-month delivery backlogs constraining barrier film output. For New Entrants and Emerging Players: Technical apprenticeship gaps in MDO line operation create service-layer opportunities for contract calibration and gauge control consulting. Poland and Czech Republic converter expansion zones offer lowest-barrier entry points with available skilled labor and energy cost advantages. Digital printing substrate compatibility for craft beverage labels provides a narrow specification window with limited incumbent lock-in. For Investors and Strategic Acquirers: Pharmaceutical-grade cleanroom certification specialists with EU MDR serialization compliance capabilities represent the most defensible acquisition profile. Long-term viability hinges on dual-certification infrastructure that spans FDA and EMA requirements simultaneously. Watch for REACH SVHC listing announcements as inflection indicators for additive reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Resin Supply | Captive feedstock secures margin stability under EU F-Gas phase-down schedules. |
| ISCC PLUS Mass-balance Certification | Qualifies access to Nordic retailer procurement scorecards prioritizing climate pledges. |
| Coating Equipment Capacity Expansion | Addresses vacuum metallization backlogs constraining barrier film output in Germany. |
| Poland/Czech Republic Extrusion Footprint | Captures lower energy costs and skilled labor availability for Western European demand. |
| REACH SVHC Traceability System Investment | Preempts pharmaceutical contract disruption from ECHA substance restriction announcements. |
Study Parameters
The analysis maps polypropylene, biodegradable, polyethylene, and polymer blend substrate segments, each validated through extrusion line operators, resin procurement managers, pharmaceutical packaging engineers, and food industry sustainability directors. Primary fieldwork combined with secondary validation from ECHA substance databases, EU F-Gas Regulation compliance filings, customs trade records, and polymer producer technical disclosures. Bottom-up capacity modeling and top-down demand estimation triangulate volume outputs.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions include substrate chemistry, application (packaging, pharmaceuticals, agriculture, electronics), end-user industry, and technology (extrusion, coating, laminating, printing). CAGRs derive from installed capacity utilization trends, regulatory substitution timelines, and end-user procurement pattern shifts. Forecast inputs incorporate EU MDR serialization compliance deadlines and REACH SVHC disclosure mandate expansion.
Forecasts assume regulatory continuity in EU REACH, F-Gas Regulation, and EMA medical device frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Packaging Reel Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Construction Films Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Finish Foils Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Anti-Static Liners Market