
 United States Single Use Packaging Market | 2026-2036
United States Single Use Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Single Use Packaging Market Analytics
The capital-intensity divergence between integrated resin producers and converter-only operators is unwinding competitive stability across the United States single use packaging landscape. Novolex leverages captive film extrusion and recycling infrastructure to control input costs across the Midwest and Southeast. Berry Global Inc anchors its position through blown film capacity concentrated in food and healthcare-grade applications. Dart Container Corporation specializes in thermoformed foam and rigid containers, sustaining margin pools in institutional food service channels where price sensitivity remains acute.
Single use packaging denotes containers, wraps, carriers, and dispensers engineered for one product cycle before disposal, typically manufactured through thermoforming, injection molding, or extrusion processes using resins, paperboard, or aluminum substrates with barrier coatings measured in micrometers. Its primary commercial purpose centers on product protection, portion control, and sanitation assurance across distributed supply chains. Plastic material type still leads volume but faces margin compression from bio-based alternatives, while food packaging application captures the deepest profit pools due to stringent FDA compliance requirements that deter commodity entrants. Medical packaging represents the fastest-growing application segment as sterilization-grade films and pouches command premium pricing tied to USP Class VI validation protocols.
FDA food contact notification rules, EPA hazardous waste generator requirements for solvent-based printing, and state-level plastic bag bans in California, New York, and New Jersey collectively reshape formulation choices and regional manufacturing footprints. OSHA process safety management standards govern resin handling at high-volume extrusion sites, particularly along the Gulf Coast petrochemical corridor. Stakeholders must monitor pending federal extended producer responsibility legislation and preemptive state labeling mandates to determine whether to regionalize production or consolidate compliance infrastructure.
Market Dynamics
State-level extended producer responsibility mandates are fragmenting manufacturing footprints across the United States single use packaging market, forcing converters to regionalize compliance infrastructure or absorb cross-border logistics costs.
Growth Catalysts
- Quick-service restaurant expansion:Chains are scaling paper-based clamshell and molded fiber container procurement across California, Texas, and New York fulfillment networks.
- FDA food contact notification pathways:Streamlined pre-market clearance for bio-based barrier coatings is accelerating material substitution timelines for food-grade films.
- E-commerce fulfillment center density:Last-mile packaging demand concentrates in metropolitan clusters where automated sortation requires standardized dimensional tolerances.
Market Restraints
- Resin input cost volatility:Gulf Coast petrochemical corridor supply disruptions transmit directly to extrusion converter margins.
- California plastic bag ban enforcement:Retail compliance deadlines compress regional inventory turnover for polyethylene film producers.
- Technical limitation in barrier performance:Polylactic acid substrates fail moisture vapor transmission rate thresholds for protein packaging applications.
Strategic Opportunities
- Medical packaging sterilization films:USP Class VI validation protocols command premium pricing in healthcare supply chains.
- Ohio River Valley converter consolidation:Underpenetrated thermoforming capacity exists between Pittsburgh and Cincinnati industrial corridors.
- IRA clean manufacturing tax credits:Incentives for recycled content integration reward Midwestern integrated producers with captive recycling infrastructure.
Industry Challenges
- Extrusion technician skill scarcity:Gulf Coast resin handling sites face OSHA process safety management certification gaps.
- Legacy printing press solvent recovery:EPA hazardous waste generator requirements demand capital retrofitting for flexographic operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Single Use Packaging Market |
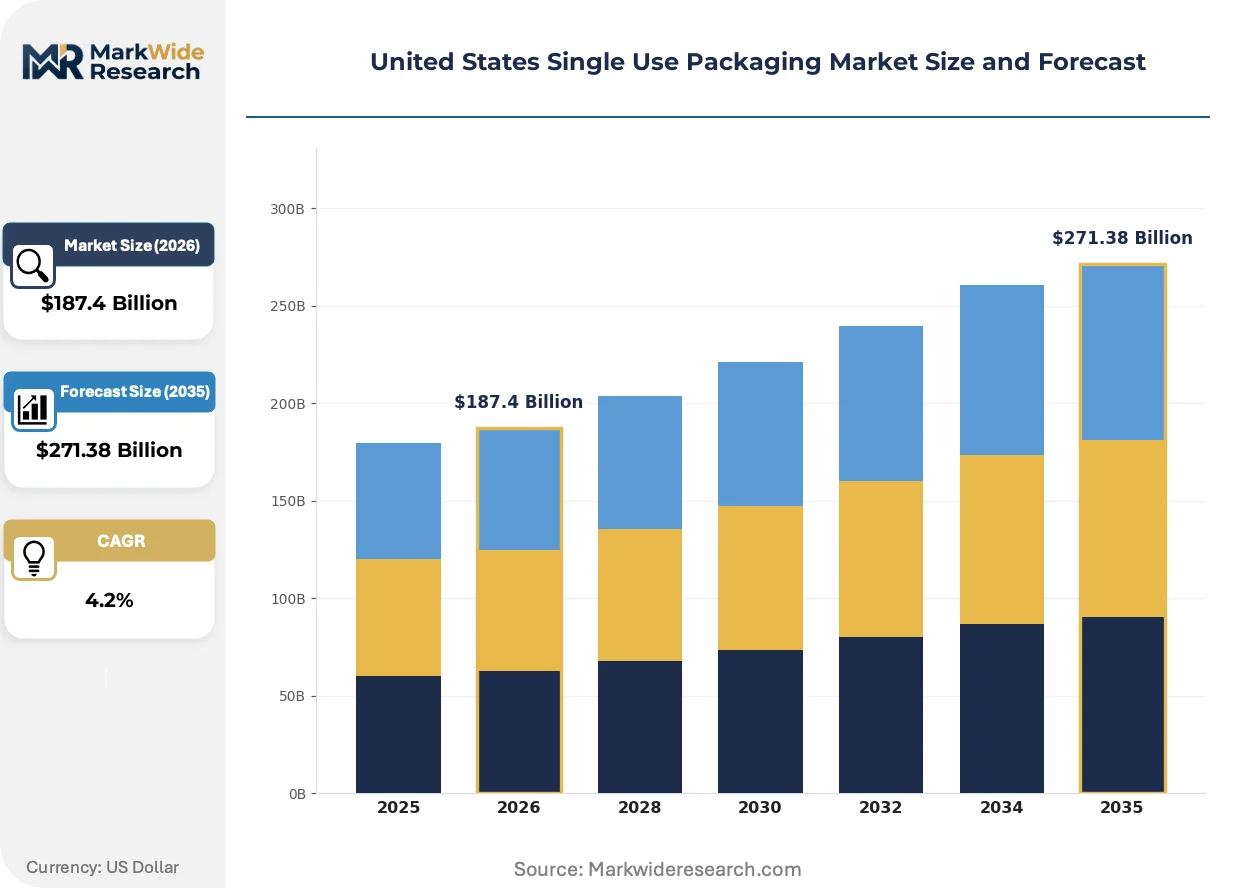
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Bio-based End User: Food Service, Retail, Healthcare, Personal Care Application: Food Packaging, Beverage Packaging, Medical Packaging, Industrial Packaging Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Novolex, Berry Global Inc, Dart Container Corporation, Winpak Ltd, Amcor Group GmbH, Georgia-Pacific LLC, Pactiv LLC, Huhtamaki Oyj, Graphic Packaging International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Single Use Packaging Market Evolving Landscape
Material science breakthroughs and compliance automation are compressing product development cycles across the United States single use packaging market, redefining competitive advantage around formulation agility rather than scale economies alone.
Polylactic acid barrier coatings engineered for thermoformed trays are decomposing petroleum-based polyethylene terephthalate dominance in fresh produce packaging. Regional grocery chains in the Pacific Northwest are piloting these substrates at 15,000-unit store counts. The technology is decomposing incumbent resin supplier relationships by enabling direct agricultural waste feedstock contracts.
California's SB 54 extended producer responsibility framework mandates 30% recycled content thresholds by weight for single-use plastic packaging. Converters must reconfigure supply chains to source post-consumer resin or face prohibited sales in the state's $3.2 trillion economy. Food-contact applications face the steepest compliance burden given FDA contamination risk protocols.
Quick-service restaurant procurement teams are consolidating supplier rosters to three-tier certified partners who demonstrate chain-of-custody documentation for bio-based content claims. This concentration displaces fragmented local converters who lack third-party verification infrastructure. The shift is most visible in Texas and Florida markets where franchisee density supports direct manufacturer relationships.
United States Single Use Packaging Market Segmentation
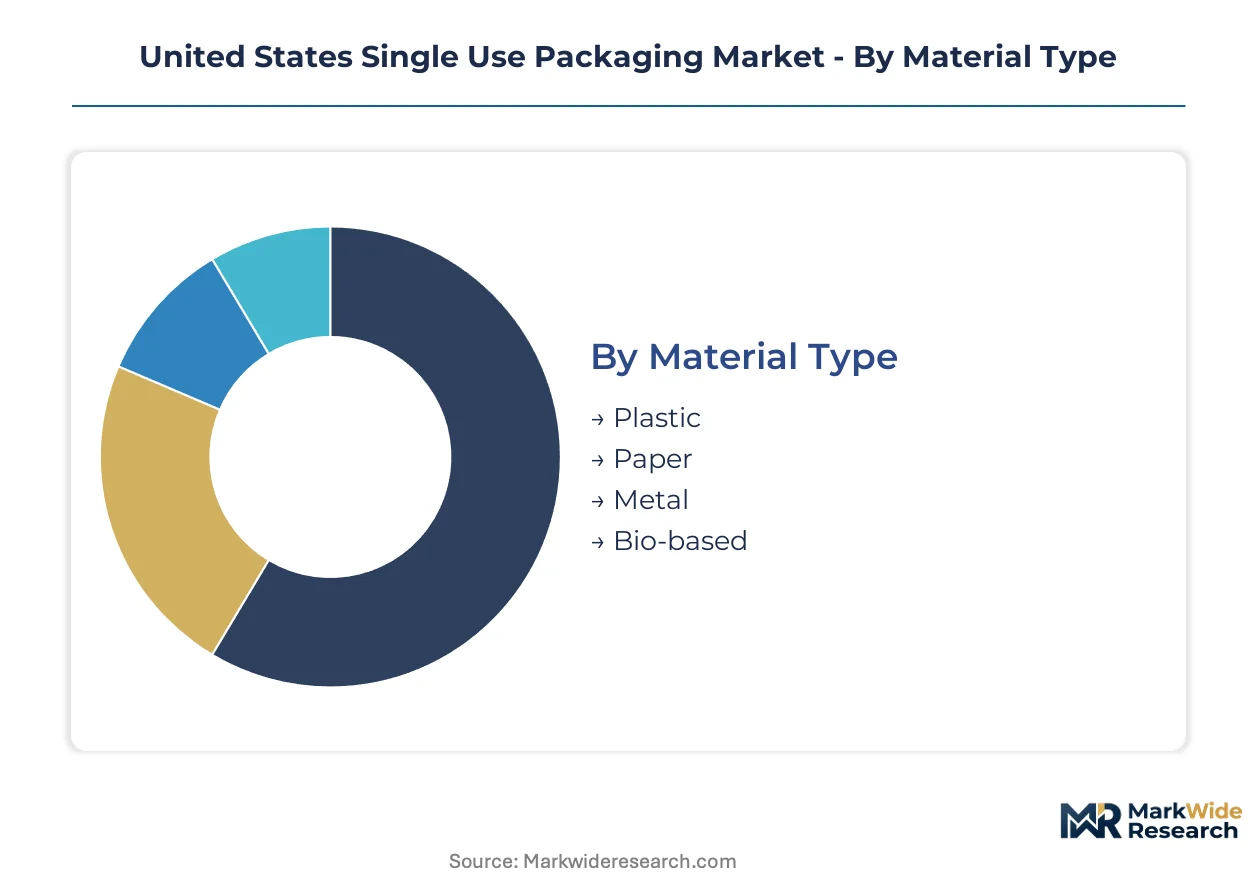
Regulatory differentiation across FDA food contact tiers and state-level extended producer responsibility mandates fragments the United States single use packaging landscape into distinct compliance zones. Material composition and end-use application determine which converters capture margin pools versus commodity volume.
Material Type:
FDA food contact notification pathways and California SB 54 recycled content mandates impose divergent compliance burdens on substrate categories.
- Plastic:Polyethylene terephthalate and polypropylene films dominate thermoformed trays and flexible pouches. Quick-service restaurant procurement in Texas and Florida concentrates demand for standardized clamshells with precise dimensional tolerances for automated fulfillment.
- Paper:Molded fiber containers and paperboard clamshells engineered with bio-based barrier coatings decompose petroleum-based dominance in fresh produce channels. Pacific Northwest grocery chains pilot these substrates at scale, sourcing agricultural waste feedstocks directly to bypass resin supplier relationships.
- Metal:Aluminum substrates with micrometer-scale barrier coatings serve sterile medical and premium food applications requiring absolute oxygen exclusion.
- Bio-based:Polylactic acid formulations face moisture vapor transmission rate limitations in protein packaging despite FDA streamlined pre-market clearance for food-grade films.
Plastic handles the majority of throughput; bio-based is gaining share fastest as agricultural waste feedstock contracts reshape upstream sourcing economics.
End User:
Customer procurement sophistication separates certified supply chain documentation requirements from spot-market commodity purchasing.
- Food Service:Quick-service restaurant chains consolidate supplier rosters to three-tier certified partners demonstrating chain-of-custody verification. Franchisee density in California, Texas, and New York supports direct manufacturer relationships that displace fragmented local converters.
- Retail:California plastic bag ban enforcement compresses regional inventory turnover for polyethylene film producers serving supermarket and convenience store channels.
- Healthcare:USP Class VI validation protocols for sterilization-grade films command premium pricing in medical supply chains where contamination risk tolerance approaches zero.
- Personal Care:Flexible pouches and dispensing containers face less stringent FDA compliance burdens than food-contact applications, enabling faster material substitution timelines.
Food service generates the deepest volume concentration; healthcare shows the steepest margin expansion as sterilization protocols intensify.
Application:
Barrier performance specifications and sterilization requirements stratify applications into distinct technology tiers with diverging capital intensity.
- Food Packaging:Thermoformed trays and flexible films with oxygen and moisture barriers protect distributed supply chains. FDA food contact substance regulations deter commodity entrants through pre-market notification requirements and contamination risk protocols.
- Beverage Packaging:Bottles, cartons, and flexible pouches require dimensional standardization for automated sortation in e-commerce fulfillment centers concentrated in metropolitan clusters.
- Medical Packaging:Sterilization films and pouches undergo USP Class VI validation to demonstrate biocompatibility. This segment climbs the fastest as healthcare supply chains prioritize contamination assurance over cost minimization.
- Industrial Packaging:Protective wraps and dunnage face minimal regulatory oversight but compete on cost against reusable alternatives in circular economy pilot programs.
Food packaging anchors current revenue; medical packaging is expanding most quickly on sterilization-grade premium capture.
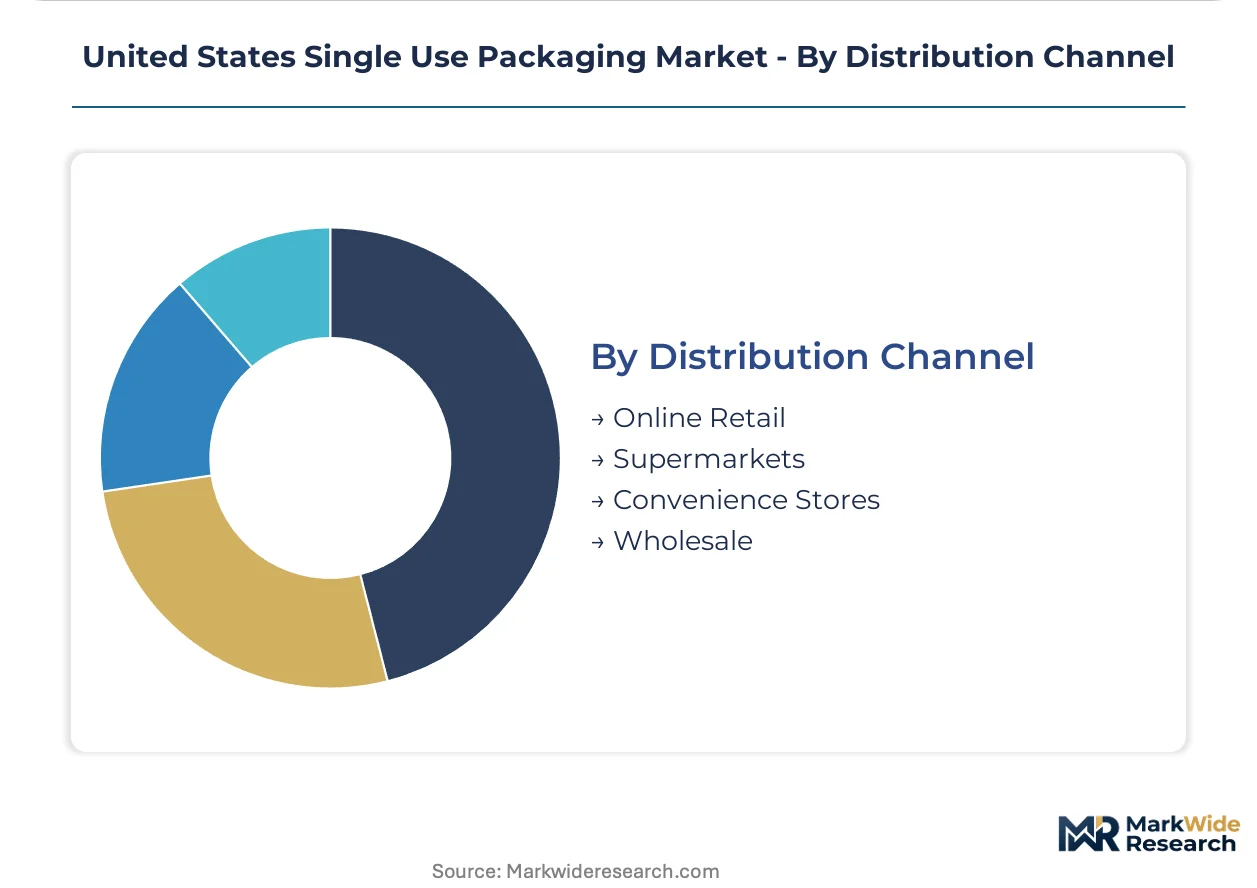
Distribution Channel:
Fulfillment velocity and lot-size flexibility separate channels serving fragmented local demand from consolidated national procurement.
- Online Retail:E-commerce fulfillment center density demands packaging with standardized dimensional tolerances for automated sortation systems. Last-mile concentration in metropolitan clusters favors converters with regional manufacturing footprints.
- Supermarkets:California's extended producer responsibility framework mandates 30% recycled content thresholds, forcing reconfiguration of supply chains for post-consumer resin sourcing or face prohibited sales in the state's economy.
- Convenience Stores:High-velocity, small-lot procurement favors distributors with fragmented local converter networks rather than integrated producers.
- Wholesale:Institutional food service channels sustain margin pools for thermoformed foam and rigid containers where price sensitivity remains acute among budget-constrained operators.
Supermarkets impose the most concentrated compliance burden; online retail is scaling fastest on fulfillment center automation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US sub-regions. California buyers absorb premium pricing for compliant substrates, while Texas and Florida operators prioritize cost minimization in high-volume quick-service channels.
California
Quick-service restaurant chains and Pacific Northwest grocery buyers drive paper-based clamshell procurement. SB 54 mandates 30% recycled content thresholds by weight, forcing converters to reconfigure post-consumer resin sourcing. Los Angeles and San Francisco Bay Area fulfillment centers concentrate e-commerce packaging demand requiring standardized dimensional tolerances.
Texas
Franchisee density in Dallas-Fort Worth and Houston supports direct manufacturer relationships displacing fragmented local converters. Quick-service procurement teams consolidate supplier rosters to three-tier certified partners. Gulf Coast petrochemical corridor proximity reduces resin logistics costs for integrated producers with captive extrusion capacity.
New York Metro
State-level plastic bag bans compress regional inventory turnover for polyethylene film producers serving supermarket and convenience store channels. FDA food contact notification requirements deter commodity entrants through pre-market clearance burdens. Metropolitan cluster e-commerce fulfillment drives last-mile packaging standardization.
Southeast
Florida quick-service expansion and Georgia logistics hub growth concentrate thermoformed container demand. OSHA process safety management standards govern resin handling at high-volume extrusion sites. Atlanta and Miami industrial corridors attract converters regionalizing compliance infrastructure to avoid cross-border logistics costs.
Midwest
Ohio River Valley underpenetrated thermoforming capacity exists between Pittsburgh and Cincinnati industrial corridors. IRA clean manufacturing tax credits reward integrated producers with captive recycling infrastructure. Chicago distribution networks serve institutional food service channels where price sensitivity sustains margin pools for foam and rigid containers.
United States Single Use Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States single use packaging landscape. Integrated resin producers with captive film extrusion and recycling infrastructure control input costs, while converter-only operators face margin compression from bio-based substitution. Three archetypes dominate: vertically integrated specialists with upstream resin control, regional converters with FDA certification infrastructure, and diversified packaging conglomerates with healthcare-grade validation capabilities. Competitive moves center on M&A to secure post-consumer resin supply chains and capacity expansion near Gulf Coast petrochemical feedstocks.
Among integrated North American operators, Novolex, Berry Global Inc, and Dart Container Corporation exemplify distinct strategic positions. Novolex represents the captive infrastructure archetype with Midwest and Southeast manufacturing concentration. Berry Global Inc occupies the diversified healthcare-food crossover tier. Dart Container Corporation anchors the institutional food service specialization segment where price sensitivity remains acute and thermoformed foam margins persist.
| Leading Market Players |
|---|
| Novolex |
| Berry Global Inc |
| Dart Container Corporation |
| Winpak Ltd |
| Amcor Group GmbH |
| Georgia-Pacific LLC |
| Pactiv LLC |
| Huhtamaki Oyj |
| Graphic Packaging International Inc. |
| Others |
Value Network & Pricing Analysis
Polylactic acid barrier coatings displacing petroleum-based polyethylene terephthalate in fresh produce channels simultaneously redraw raw material sourcing maps toward agricultural waste feedstocks and compress legacy resin supplier pricing power across Pacific Northwest grocery networks.
Pricing Analysis
After-sales service contracts for sterilization-grade film validation and technical support drive lifetime value capture in healthcare channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by USP Class VI certification grade and FDA food contact notification tier. Cost compression in commodity thermoformed foam intensifies as institutional food service buyers consolidate procurement volumes. Quick-service restaurant chains exhibit acute price sensitivity, while medical packaging buyers prioritize contamination assurance over unit cost minimization.
Supply Chain Analysis
Inventory buffers for Gulf Coast petrochemical corridor resin inputs have shortened as converters regionalize production to comply with state-level extended producer responsibility mandates. Raw material supply draws from Texas and Louisiana petrochemical complexes, with secondary sourcing from Midwestern post-consumer resin processors. Single-source vulnerability concentrates around high-density polyethylene and polypropylene pellet supply from integrated producers. Distribution runs through converter-direct relationships with quick-service restaurant chains and third-party distributors serving fragmented convenience store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against bio-based barrier coatings and molded fiber containers that threaten petroleum-based substrate margins across food service and fresh produce channels.
For Market Incumbents: Consolidate captive recycling infrastructure to secure California SB 54 compliant post-consumer resin supply chains before 30% recycled content thresholds take effect. Acquire thermoforming capacity in the Ohio River Valley corridor between Pittsburgh and Cincinnati to preempt regional competitor positioning. Vertical integration into agricultural waste feedstock contracts bypasses traditional resin supplier relationships that bio-based substitutes are eroding.
For New Entrants and Emerging Players: Anchor in USP Class VI sterilization-grade film production where validation protocols create defensible barriers against commodity converters. Target the medical packaging application segment where contamination risk tolerance approaches zero and premium pricing persists. Pursue direct manufacturer relationships with quick-service restaurant franchisees in Texas and Florida markets where three-tier certification requirements displace fragmented local suppliers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed converter-only operators lacking captive resin extrusion or recycling infrastructure that California compliance mandates now require. Five-to-ten-year viability hinges on post-consumer resin supply chain control and FDA food contact notification pathway expertise. Monitor federal extended producer responsibility legislation progression as the inflection signal determining whether regionalized production or consolidated compliance infrastructure wins.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Supply Chain Integration | Secures California SB 54 compliance thresholds and defends market access in the state's economy. |
| USP Class VI Validation Infrastructure Investment | Captures sterilization-grade film premiums in healthcare supply chains requiring biocompatibility assurance. |
| Ohio River Valley Thermoforming Capacity Expansion | Addresses underpenetrated industrial corridor demand between Pittsburgh and Cincinnati logistics networks. |
| Agricultural Waste Feedstock Direct Contracting | Bypasses incumbent resin supplier relationships that polylactic acid substitutes are decomposing. |
| Three-Tier Certification Documentation Systems | Meets quick-service restaurant procurement consolidation requirements for chain-of-custody verification. |
Research Methodology
A spread of perspectives from converter operations managers, quick-service restaurant procurement directors, FDA regulatory affairs consultants, and healthcare supply chain administrators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA hazardous waste generator filings, FDA food contact substance notifications, state-level extended producer responsibility legislative databases, and SEC 10-K disclosures from integrated packaging producers. Bottom-up volume modeling across material type, end user, application, and distribution channel dimensions triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include material composition tier, FDA compliance classification, end-use industry vertical, geographic regulatory cluster, and distribution channel fulfillment velocity across the projection horizon. CAGRs derived from regression analysis against historical volume trends, substitution elasticity parameters, and regulatory implementation timelines. Industry-specific forecast inputs incorporated resin price volatility indices and quick-service restaurant unit expansion pipelines.
Material uncertainties — Gulf Coast petrochemical supply disruptions, federal extended producer responsibility legislation progression, and bio-based barrier coating performance breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as regulatory frameworks crystallize and substitution dynamics accelerate. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Primary Packaging Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Nigeria Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Mylar Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Postal Packaging Market