
 Honeycomb Packaging Market | 2026-2036
Honeycomb Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Honeycomb Packaging Market Outlook
Skilled paperboard engineering talent is redrawing competitive boundaries across the honeycomb packaging sector. DS Smith leverages its European recycling infrastructure to secure recycled fiber supply. Smurfit Kappa anchors its position through integrated corrugated and honeycomb manufacturing networks. Sonoco Products Company differentiates via specialized protective packaging design capabilities for fragile goods transit.
Honeycomb packaging consists of hexagonal cellular structures manufactured from kraft paper, recycled paperboard, or polymer substrates, engineered to achieve high strength-to-weight ratios through continuous bonding of flat liner sheets to corrugated core material. The primary industrial purpose centers on protective cushioning, palletization, and structural containment for heavy or fragile products during distribution. Paper-based honeycomb dominates material selection due to cost efficiency and fiber recyclability, while customized design configurations command premium positioning in electronics and pharmaceutical end-use applications where dimensional precision prevents product damage.
EPA guidelines on recycled content requirements and EU REACH standards for chemical treatments in packaging substrates are elevating compliance costs while accelerating substitution toward biodegradable design types. FDA food-contact material regulations shape barrier specifications for honeycomb structures serving food and beverage distribution channels. Stakeholders must weigh fiber sourcing security against design customization investments as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
E-commerce fulfillment velocity is compressing design-to-delivery cycles across honeycomb packaging, forcing converters to collapse prototyping lead times while maintaining structural integrity for fragile goods transit.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are accelerating fiber-based honeycomb substitution for expanded polystyrene in protective shipping applications across member states.
- Automotive parts exporters:Germany's precision component manufacturers require high-strength cushioning solutions for just-in-time delivery networks serving assembly plants.
- Paperboard engineering talent:Specialized structural design capabilities are enabling customized cellular configurations for electronics and pharmaceutical dimensional precision requirements.
Market Restraints
- Recycled fiber cost volatility:Kraft paper and recycled paperboard input prices fluctuate with pulp commodity cycles, squeezing converter margins during supply tightness.
- Polymer substrate competition:Polypropylene honeycomb alternatives offer moisture resistance that paper-based structures cannot match in cold-chain pharmaceutical distribution.
- REACH compliance friction:Chemical treatment restrictions for water-resistant coatings limit substrate modification options for food-contact barrier specifications.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution is creating demand for insulated honeycomb thermal shippers with phase-change material integration.
- EU Green Deal procurement incentives:Public sector packaging tenders now weight circularity scores, favoring suppliers with closed-loop fiber recovery systems.
- India's PLI scheme for electronics manufacturing:Domestic mobile device assembly is generating localized demand for protective shipping structures previously imported from Southeast Asia.
Industry Challenges
- Skilled paperboard engineering scarcity:Structural packaging designers with honeycomb-specific FEA simulation expertise command premium compensation, constraining mid-tier converter expansion.
- Multi-jurisdiction certification timelines:FDA food-contact material approvals for novel barrier coatings extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honeycomb Packaging Market |
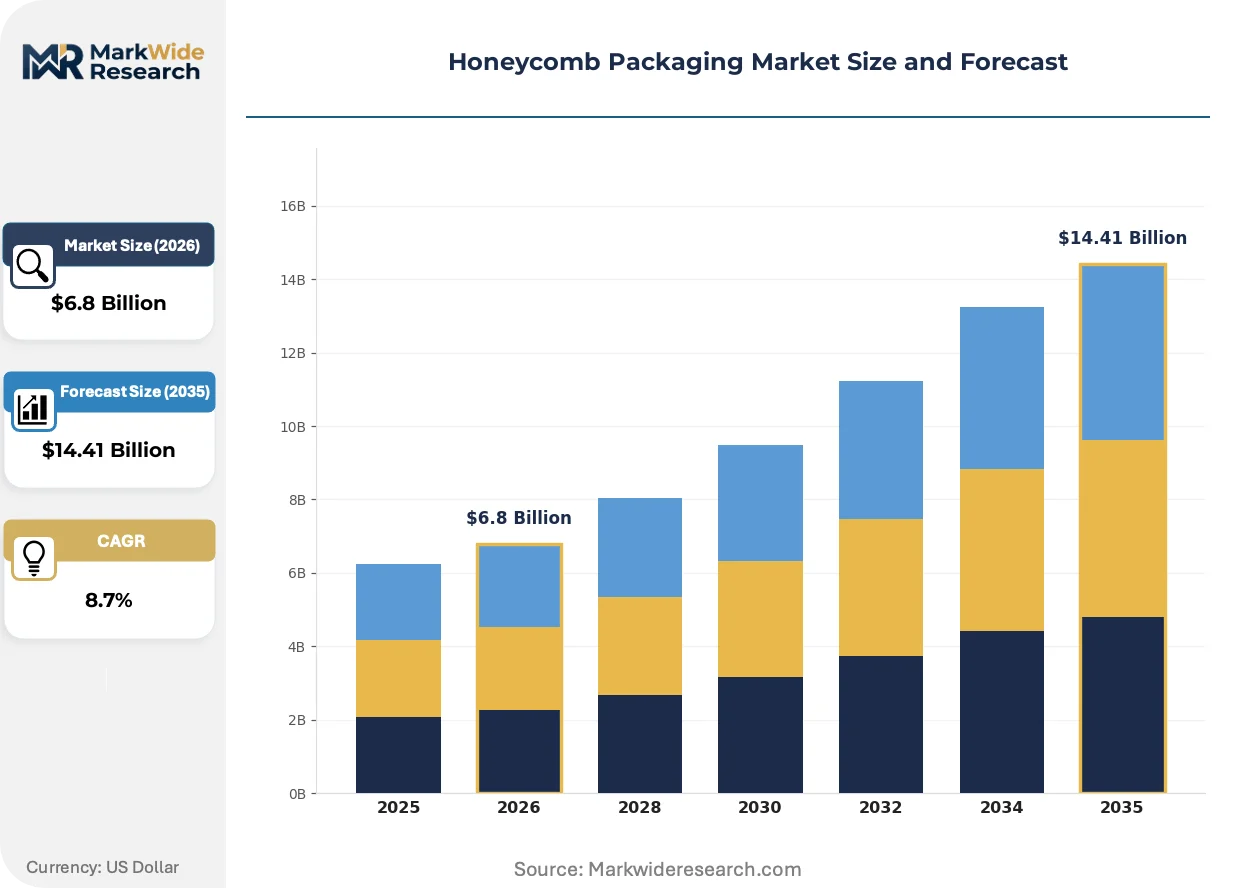
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Paper, Plastic, Wood, Metal End User: Food & Beverage, Electronics, Furniture, Pharmaceutical Design Type: Customized, Standard, Biodegradable, Recyclable Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Axxor, NEFAB Group, DS Smith, Signode, Honecore, Smurfit Kappa, Sonoco Products Company, Grigeo, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honeycomb Packaging Market Strategic Shifts
Digital manufacturing integration and substrate chemistry advances are redefining performance thresholds across protective packaging, collapsing the gap between standardized commodity supply and engineered custom solutions.
Automated honeycomb core production lines equipped with real-time density monitoring are displacing manual calibration-dependent equipment across European converter facilities. Automotive tier-one suppliers in Germany and France are adopting these systems to achieve lot-to-lot compressive strength consistency for powertrain component shipments. The displacement of variable-output machinery is compressing quality assurance overhead while enabling just-in-time cellular geometry adjustments.
EPA recycled content guidelines are elevating post-consumer fiber thresholds for federal procurement eligibility in protective packaging categories. US-based converters serving defense and aerospace logistics channels must now document minimum 50% recycled fiber mass balance through third-party chain-of-custody certification. Electronics original equipment manufacturers in California and Texas are reformulating supplier scorecards to weight these verified content claims.
Consolidated procurement desks at multinational e-commerce platforms are unbundling protective packaging specification from logistics service contracts. Direct converter relationships are replacing distributor-mediated supply for high-volume fulfillment operations in the Netherlands and United Kingdom. This disintermediation is compressing margin capture for traditional packaging distributors while rewarding converters with design-to-delivery integration capabilities.
Honeycomb Packaging Market Segmentation

Material composition determines regulatory compliance pathways and recyclability credentials across honeycomb packaging applications. End-use specifications drive structural engineering requirements, while design type and channel selection shape margin capture and customer acquisition economics.
Material:
REACH chemical restrictions and FDA food-contact standards create divergent compliance burdens across substrate categories, elevating fiber traceability requirements for paper-based structures.
- Paper:Kraft paper and recycled paperboard honeycomb achieves high strength-to-weight ratios through hexagonal cellular bonding with flat liner sheets. Germany's automotive parts exporters demand this material for just-in-time powertrain component cushioning, driven by EU Packaging and Packaging Waste Regulation recyclability mandates that disadvantage polymer alternatives.
- Plastic:Polypropylene honeycomb substrates deliver moisture resistance and dimensional stability in cold-chain pharmaceutical distribution where temperature cycling degrades fiber structures. Polymer substrate competition intensifies as biologics shippers prioritize barrier performance over circularity scores in FDA-regulated lanes.
- Wood:Engineered wood honeycomb panels serve heavy-load palletization for industrial machinery and furniture distribution, leveraging compressive strength from laminated veneer core structures.
- Metal:Aluminum honeycomb provides aerospace-grade structural containment for defense and satellite component shipping, commanding premium positioning in low-volume, high-specification applications.
Paper handles the majority of throughput; Plastic is expanding most quickly on share as pharmaceutical cold-chain requirements harden.
End User:
Dimensional precision requirements and damage liability exposure create tiered specification intensity across downstream industries.
- Electronics:Smartphone, semiconductor, and display manufacturers require sub-millimeter tolerance honeycomb cushioning to prevent surface scratching and shock fracture during multi-modal transit. India's PLI scheme for electronics manufacturing is generating localized protective packaging demand previously served by Southeast Asian converters.
- Pharmaceutical:Temperature-sensitive biologics distribution demands insulated honeycomb thermal shippers with phase-change material integration and validated cold-chain performance documentation. FDA food-contact material regulations and EMA distribution guidelines shape barrier coating specifications for primary and secondary packaging layers.
- Food & Beverage:Honeycomb palletization and containment structures for bottled goods and processed food distribution face FSSAI and FDA migration limits on barrier treatments.
- Furniture:Flat-pack and assembled furniture shippers utilize honeycomb corner protectors and edge cushioning to prevent finish damage in e-commerce fulfillment velocity environments.
Electronics commands the largest specification volume; Pharmaceutical is climbing the fastest as biologics distribution networks expand.
Design Type:
Certification grade differentiation separates premium engineered solutions from commodity supply, with circularity credentials increasingly weighted in procurement scorecards.
- Customized:Application-specific cellular geometry, density gradients, and die-cut void patterns engineered through FEA simulation for fragile goods transit. Electronics OEMs in California and Texas reformulate supplier scorecards to weight verified recycled content claims alongside dimensional precision.
- Biodegradable:Unbleached kraft paper honeycomb with compostable adhesive systems designed for EU Green Deal procurement incentives and public sector tender circularity scoring. EPA recycled content guidelines elevate post-consumer fiber thresholds for federal procurement eligibility in protective packaging categories.
- Standard:Catalog dimension honeycomb panels and blocks serving high-volume, low-variability protective packaging applications with compressed design-to-delivery cycles.
- Recyclable:Closed-loop fiber recovery systems with third-party chain-of-custody certification enabling converter participation in circular economy procurement frameworks.
Customized absorbs the highest margin concentration; Biodegradable is gaining share fastest as EU member states tighten packaging waste directives.
Distribution Channel:
Channel selection determines customer intimacy depth and margin capture architecture, with disintermediation pressures reshaping traditional distributor economics.
- Direct Sales:Converter-direct relationships with multinational e-commerce platforms and automotive tier-one suppliers, unbundling protective packaging specification from logistics service contracts. Consolidated procurement desks in the Netherlands and United Kingdom reward design-to-delivery integration capabilities.
- Distributors:Traditional packaging distributors facing margin compression as high-volume fulfillment operations bypass intermediary layers for direct converter engagement.
- Online Retail:Digital catalog and configuration platforms enabling small-batch honeycomb procurement for mid-market electronics and furniture shippers.
- Others:Cooperative purchasing networks and industry association procurement consortia serving fragmented end-user bases with aggregated volume leverage.
Direct Sales captures the dominant value flow; Online Retail is accelerating fastest as digital manufacturing integration collapses minimum order quantities.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys honeycomb packaging primarily for automotive powertrain cushioning, whereas the United States concentrates procurement in e-commerce fulfillment channels and the United Kingdom weights circularity scoring in public tenders. This consumption-mix differential shapes divergent converter capability investments across major demand centers.
Germany
Automotive tier-one suppliers in Stuttgart and Munich require high-strength cellular structures for just-in-time powertrain component delivery. The EU Packaging and Packaging Waste Regulation enforces recyclability thresholds that favor fiber-based honeycomb over expanded polystyrene alternatives. Converter facilities in Baden-Württemberg deploy automated core production lines with real-time density monitoring to satisfy lot-to-lot compressive strength consistency mandates.
United States
E-commerce fulfillment platforms in California and Texas reformulate supplier scorecards to weight verified recycled content claims alongside dimensional precision. EPA guidelines mandate minimum post-consumer fiber thresholds for federal procurement eligibility in protective packaging categories. Electronics original equipment manufacturers in the Austin and San Jose metro areas drive demand for sub-millimeter tolerance cushioning configurations.
United Kingdom
Consolidated procurement desks at multinational logistics operators unbundle protective packaging specification from service contracts, rewarding direct converter relationships. EU Green Deal procurement incentives weight circularity scores in public sector tenders, favoring suppliers with closed-loop fiber recovery systems. Converter networks in the Midlands and Greater Manchester regions invest in third-party chain-of-custody certification to participate in circular economy frameworks.
India
Domestic mobile device assembly under the PLI scheme for electronics manufacturing generates localized protective packaging demand previously served by Southeast Asian converters. FSSAI migration limits on barrier treatments shape substrate specifications for food-contact applications. Manufacturing clusters in Maharashtra and Karnataka attract converter capacity expansion to serve smartphone and semiconductor shipment requirements.
Netherlands
Distribution hub operators serving pan-European e-commerce channels compress design-to-delivery cycles through digital manufacturing integration. REACH chemical restrictions elevate fiber traceability requirements for paper-based structures entering pharmaceutical distribution lanes. Converter facilities in the Randstad region specialize in insulated thermal shippers with phase-change material integration for temperature-sensitive biologics.
Honeycomb Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on design customization and regional proximity. The upper tier commands procurement relationships with multinational e-commerce platforms and automotive OEMs through captive fiber supply and in-house production of cellular core structures. Mid-scale converters occupy positions based on FEA simulation expertise and rapid prototyping capabilities. Competitive moves center on backward integration into recycled paperboard supply and geographic expansion into electronics manufacturing clusters.
Within the integrated packaging conglomerate tier, DS Smith and Smurfit Kappa exemplify the fiber-circular model with European recycling infrastructure and integrated corrugated-honeycomb manufacturing networks. Sonoco Products Company occupies a position emphasizing specialized protective packaging design capabilities. Among specialists, Axxor and NEFAB Group represent the engineering-intensive archetype focused on automotive and aerospace structural containment applications.
| Leading Market Players |
|---|
| Axxor |
| NEFAB Group |
| DS Smith |
| Signode |
| Honecore |
| Smurfit Kappa |
| Sonoco Products Company |
| Grigeo |
| Packaging Corporation of America |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German automotive tier-one suppliers and Baden-Württemberg converter facilities lock in recycled kraft paper supply while providing twelve-month price visibility against pulp commodity cycles. These contracts bundle volume commitments with lot-to-lot compressive strength specifications, insulating procurement desks from spot market volatility while embedding quality assurance overhead into unit economics.
Pricing Analysis
Contract-based long-term offtake dominates converter-buyer relationships, with pricing stratifying across premium, standard, and economy tiers based on certification grade and customization level. Premium positioning commands FEA-simulated cellular configurations for electronics OEMs, while standard catalog dimensions serve high-volume e-commerce fulfillment. Cost compression in the standard tier is intensifying because consolidated procurement desks at multinational platforms unbundle specification from logistics contracts. Mid-market furniture shippers exhibit highest price sensitivity; pharmaceutical cold-chain operators show least sensitivity due to validated thermal performance requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites Middle Eastern pulp supply routes that feed European recycled paperboard production, creating logistics chokepoint exposure for kraft paper input security. Manufacturing concentrates in Germany, the United States, and India, with Baden-Württemberg facilities serving automotive demand, Texas and California clusters feeding electronics OEMs, and Maharashtra plants supporting PLI-scheme mobile assembly. Raw material dependencies center on post-consumer fiber streams, unbleached kraft pulp, and water-resistant coating chemistries. Single-source vulnerability runs through European recycling infrastructure controlled by integrated conglomerates. Distribution feeds from converter-direct relationships with multinational e-commerce platforms and automotive procurement desks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as polypropylene honeycomb alternatives capture pharmaceutical cold-chain share through moisture resistance performance that fiber structures cannot match.
For Market Incumbents: Shield market position by accelerating backward integration into closed-loop fiber recovery systems that satisfy EU Green Deal circularity scoring requirements. Prioritize in-house production of automated honeycomb core lines with real-time density monitoring to compress quality assurance overhead. The polypropylene threat in temperature-sensitive biologics distribution demands barrier coating R&D investment to recover pharmaceutical specification share.
For New Entrants and Emerging Players: Anchor in India's PLI-scheme electronics manufacturing clusters where localized protective packaging demand outstrips converter capacity expansion. Target mid-tier smartphone and semiconductor shippers requiring sub-millimeter tolerance cushioning with compressed design-to-delivery cycles. A digital manufacturing integration angle collapses minimum order quantities and enables direct platform relationships bypassing traditional distributor layers.
For Investors and Strategic Acquirers: Capital is best deployed toward engineering-intensive specialists with FEA simulation expertise and rapid prototyping capabilities serving automotive and aerospace structural containment applications. Long-term viability hinges on fiber circularity credentials and multi-jurisdiction certification navigation capabilities. Watch for inflection signals in EU Packaging and Packaging Waste Regulation enforcement intensity that would accelerate fiber-based substitution mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Supply | DS Smith and Smurfit Kappa leverage European recycling infrastructure to secure kraft paper input security against pulp volatility. |
| Automated Core Production Line Deployment | German automotive tier-one suppliers adopt real-time density monitoring to achieve lot-to-lot compressive strength consistency. |
| FEA Simulation Capability Investment | Specialist converters command premium positioning for electronics and pharmaceutical dimensional precision requirements. |
| Direct Platform Relationship Development | Consolidated procurement desks in the Netherlands and United Kingdom reward design-to-delivery integration capabilities. |
| Pharmaceutical Cold-Chain Thermal Shipper Expansion | Randstad region converters specialize in phase-change material integration for temperature-sensitive biologics distribution. |
Study Parameters
The analysis maps paper-based honeycomb, polymer substrates, and engineered wood panels, each validated through converter operations directors, automotive tier-one procurement managers, e-commerce platform supply chain leads, and pharmaceutical logistics specialists. Primary fieldwork combined with secondary validation from EPA recycled content guidelines, EU REACH regulatory filings, FDA food-contact material standards, and customs trade data for kraft paper imports. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks including pulp commodity price indices, automotive production forecasts, and e-commerce fulfillment growth trajectories. The analytical framework modeled material composition, end-user industry, design type certification grade, and distribution channel structure across the projection horizon. CAGRs derived from segment-level demand elasticity analysis incorporating EU regulatory enforcement timelines and PLI scheme electronics manufacturing capacity expansion.
Decision-makers should treat outputs as directional under assumptions of sustained EU Packaging and Packaging Waste Regulation enforcement and continued e-commerce fulfillment velocity; material deviation in pulp commodity cycles or polypropylene substitution rates would warrant model refresh. Practitioners should keep alternative scenarios live as REACH chemical restriction scope and pharmaceutical cold-chain validation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Twist Tie Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Finish Foils Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Brazil Packaging Market