
 Printed Aluminium Foil Packaging Market | 2026-2036
Printed Aluminium Foil Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Aluminium Foil Packaging Market Analytics
Modular pouch-and-rip configurations for single-serve pharmaceutical and food portions is pivoting buyer preference away from bulk roll formats. Hindalco Industries Ltd. anchors India's upstream aluminium supply and extends into value-added foil conversion for domestic drug packaging. Amcor plc dominates flexible packaging integration and competes across multi-layer barrier structures that incorporate printed foil substrates. Constantia Flexibles specializes in pharmaceutical blister lidding and navigates European regulatory complexity through dedicated compliance infrastructure.
Printed aluminium foil packaging consists of aluminium alloy substrates, typically between six and fifty micrometres thick, that undergo surface treatment, primer coating, and rotary printing before lamination or direct forming into barrier packages. Flexographic and gravure techniques occupy the highest volume share across pharmaceutical and food applications due to proven ink adhesion on treated aluminium and cost efficiency at long production runs. Pouches lead product-type demand in food and beverage end uses where resealability and shelf visibility matter, while thin-gauge sheets command premium positioning in pharmaceutical blister packs where precise dose protection and child-resistance standards apply.
FDA enforces pharmaceutical packaging integrity and traceability through drug master file requirements that directly shape foil supplier qualification protocols in the United States. EMA and REACH jointly govern material migration limits and substance registration for aluminium packaging entering European pharmaceutical and food channels. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate recyclability mandates, as regulatory pressure on multi-material laminate recovery will increasingly influence printed foil specification decisions and supplier selection criteria.
Market Dynamics
Pharmaceutical serialization mandates and food-contact migration limits are compressing supplier qualification timelines while concentrating buyer spend on vertically integrated converters capable of certifying full material traceability from smelter to printed reel.
Growth Catalysts
- REACH substance registration:European pharmaceutical and food channels now require comprehensive chemical dossiers for aluminium surface treatments, elevating demand for compliant printed foil from qualified converters.
- Blister pack serialization:Track-and-trace regulations across multiple jurisdictions mandate unique identifiers on pharmaceutical lidding, directly expanding printed foil volume in dose-protection applications.
- India domestic manufacturing:PLI scheme incentives for active pharmaceutical ingredient and formulation production are scaling local demand for printed blister foil from integrated packaging suppliers.
Market Restraints
- Alumina price volatility:Smelter energy costs and bauxite supply disruptions transmit directly to foil substrate pricing, compressing converter margins on fixed-price annual contracts.
- Multi-material laminate recovery:Extended producer responsibility frameworks in Europe impose fees based on non-recyclable packaging fractions, disadvantaging printed foil when laminated to incompatible polymer layers.
- Paper-based barrier coatings:Fibre-based alternatives with metallized or mineral-filled structures are displacing thin-gauge aluminium in select ambient food segments where oxygen sensitivity is moderate.
Strategic Opportunities
- Domestic Indian food processing:Export-oriented spice and ready-to-eat meal producers are localizing printed pouch supply chains, creating demand for foil conversion capacity beyond pharmaceutical applications.
- Mono-material aluminium recyclability:Pure aluminium barrier structures qualify for higher recycling stream values under EU packaging waste directives, incentivizing format redesign away from multi-layer laminates.
- Digital print integration:Inkjet and electrophotographic systems are converging with conventional gravure lines, enabling short-run customization for clinical trial supplies and regional brand variants without cylinder costs.
Industry Challenges
- Migration testing capacity:Analytical laboratory throughput for extractables and leachables validation is constraining new product qualification timelines, particularly for novel primer and ink chemistries.
- Legacy equipment retrofit:Converting lines designed for bulk roll formats require mechanical and control system upgrades to handle modular pouch configurations demanded by single-serve pharmaceutical packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Aluminium Foil Packaging Market |
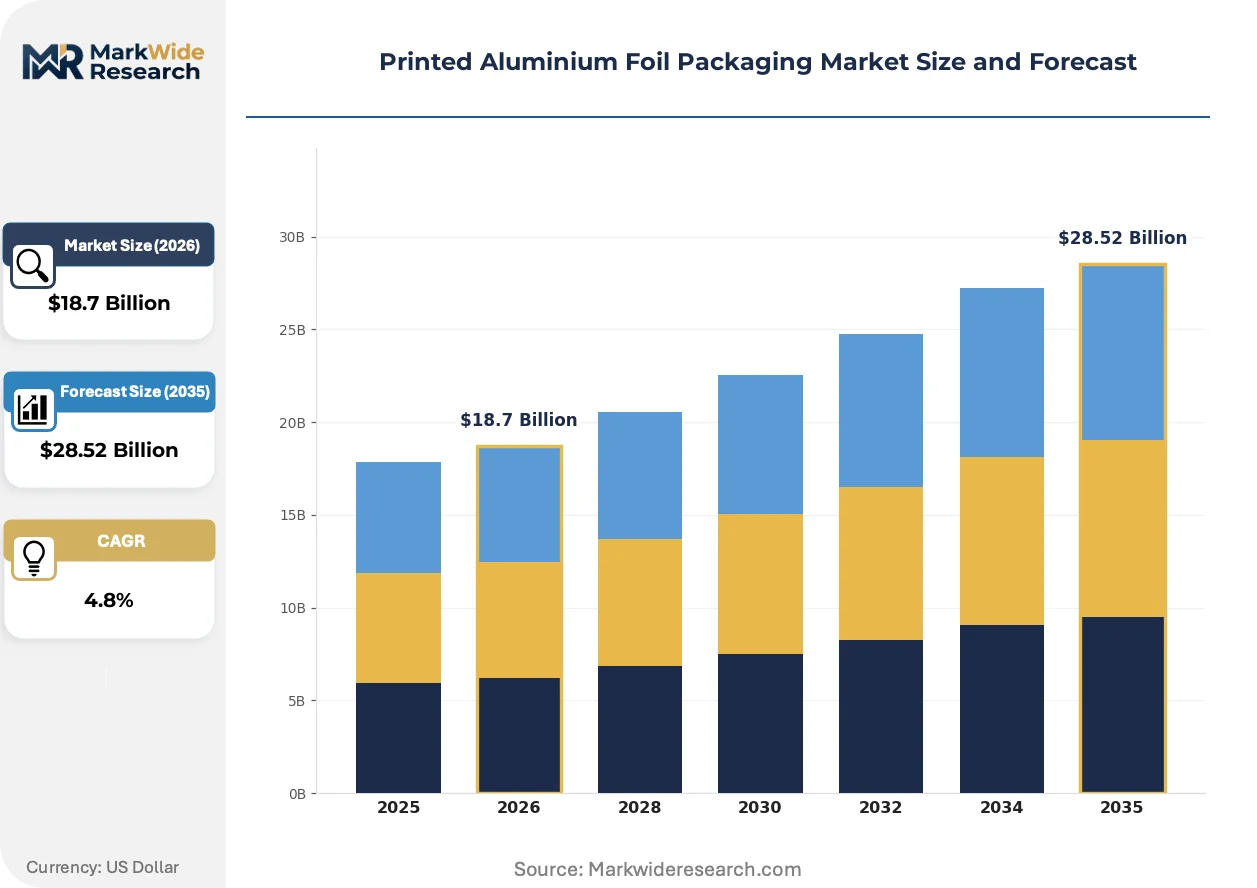
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, Rolls, Sheets, Labels End User: Pharmaceuticals, Food & Beverage, Cosmetics, Electronics Thickness: Thin, Medium, Heavy, Extra Heavy Printing Technique: Flexographic, Gravure, Digital, Lithographic |
| Companies Covered | UACJ Corporation, Hindalco Industries Ltd., Novelis Inc., Southwest Aluminum Industrial (Group) Co., Ltd., China Hongqiao Group Limited, Amcor plc, Reynolds Consumer Products LLC, Eurofoil Luxembourg S.A., Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Aluminium Foil Packaging Market Evolving Landscape
Active and intelligent packaging functionalities are migrating from premium positioning to standard pharmaceutical specifications, while regulatory pressure on material circularity is forcing substrate and format redesign across both medical and food channels.
High-barrier oxide coatings deposited through atomic layer deposition and plasma-enhanced chemical vapor deposition are converging with conventional aluminium foil substrates to create hybrid structures with reduced metal gauge. Pharmaceutical blister manufacturers in Germany and Switzerland are piloting these laminates for moisture-sensitive biologics. The technology is converging with established foil supply chains by allowing converters to maintain existing forming and sealing equipment while meeting tightened water vapor transmission specifications.
EMA's updated guidelines on elemental impurities in pharmaceutical packaging now explicitly reference aluminium alloy composition limits and surface treatment residues, extending the scope of ICH Q3D compliance to primary packaging materials. Contract manufacturers in Ireland and the Netherlands are rejecting foil lots lacking full smelter certificates of analysis. The regulation is compressing supplier qualification timelines and elevating documentation burdens on non-integrated importers.
Hospital and pharmacy procurement consortia are consolidating annual printed foil requirements into multi-year framework agreements with tiered performance guarantees. Large pharmaceutical distributors in the United States are displacing spot purchasing for standard blister formats, instead mandating vendor-managed inventory with consignment stock at regional distribution centers. The shift is concentrating volume with converters capable of integrating directly into customer ERP systems and maintaining safety stock across multiple SKUs.
Printed Aluminium Foil Packaging Market Segmentation
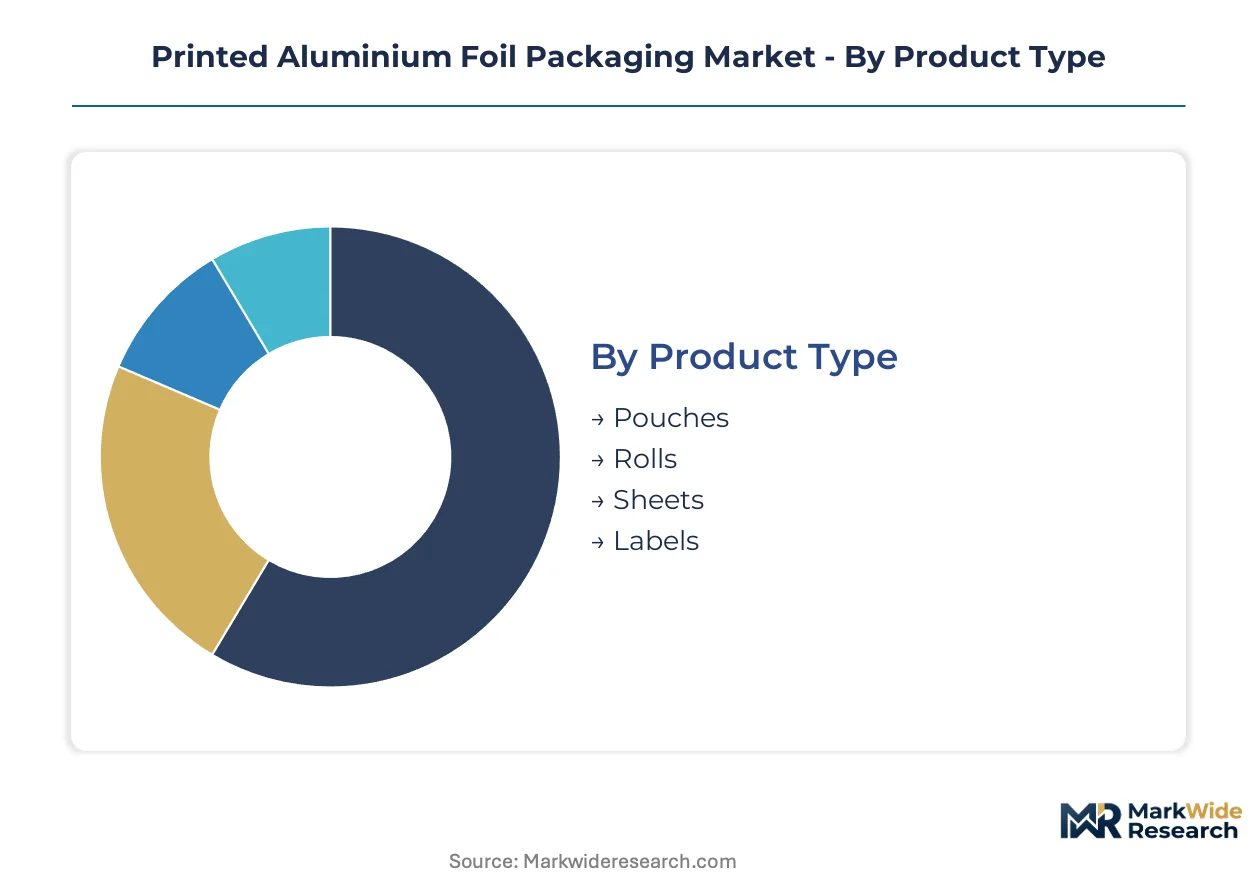
Converters configure production assets around distinct product formats, end-use specifications, and gauge requirements. Each segmentation axis determines capital allocation, regulatory compliance pathways, and customer qualification protocols.
Product Type:
Roll-to-roll converting capacity concentrates in South Korea and Germany, where integrated lines serve high-volume pharmaceutical and food customers.
- Pouches:Pre-formed three-side-seal and stand-up configurations incorporate resealable zippers and tear notches. Indian spice exporters and European ready-meal producers are driving demand for printed pouch formats with extended shelf-life barriers.
- Rolls:Bulk master reels feed downstream form-fill-seal operations and represent the highest throughput format for converters with continuous coating and printing assets. Pharmaceutical contract manufacturers in Ireland and the Netherlands specify rolls for in-house blister forming lines.
- Sheets:Die-cut lidding and formed trays for unit-dose pharmaceuticals.
- Labels:Pressure-sensitive and shrink-sleeve formats for secondary branding.
Rolls absorb the bulk of installed capacity; pouches are expanding most quickly.
End User:
Regulatory intensity varies sharply across customer verticals, with pharmaceutical and food channels imposing distinct migration testing and traceability requirements.
- Pharmaceuticals:Blister lidding and cold-form foil for solid oral dosage forms must satisfy FDA drug master file requirements and EMA elemental impurity guidelines. German and Swiss manufacturers are qualifying next-generation oxide-coated laminates for moisture-sensitive biologics.
- Food & Beverage:Retort pouches, chocolate wrapping, and dairy lidding demand heat-seal integrity and oxygen barrier performance. Indian export-oriented processors are localizing printed foil supply chains under PLI scheme incentives.
- Cosmetics:Sachets and sample packets for premium skincare and fragrance products.
- Electronics:Static-dissipative pouches and moisture barrier bags for semiconductors.
Pharmaceuticals commands the highest margin tier; food and beverage is gaining share fastest.
Thickness:
Gauge selection determines forming behavior, barrier performance, and material cost per unit area.
- Thin:Six to twelve micrometre substrates for pharmaceutical blister lidding where precise forming and minimal material usage are prioritized. Swissmedic-registered facilities in Switzerland specify thin-gauge foil for high-speed packaging lines.
- Medium:Twelve to twenty-five micrometre range for general-purpose food pouches and labels.
- Heavy:Twenty-five to fifty micrometre gauges for deep-drawn trays and industrial applications.
- Extra Heavy:Above fifty micrometre specialty gauges requiring dedicated rolling mill capacity.
Thin gauge dominates pharmaceutical volume; medium gauge is climbing the fastest in food applications.
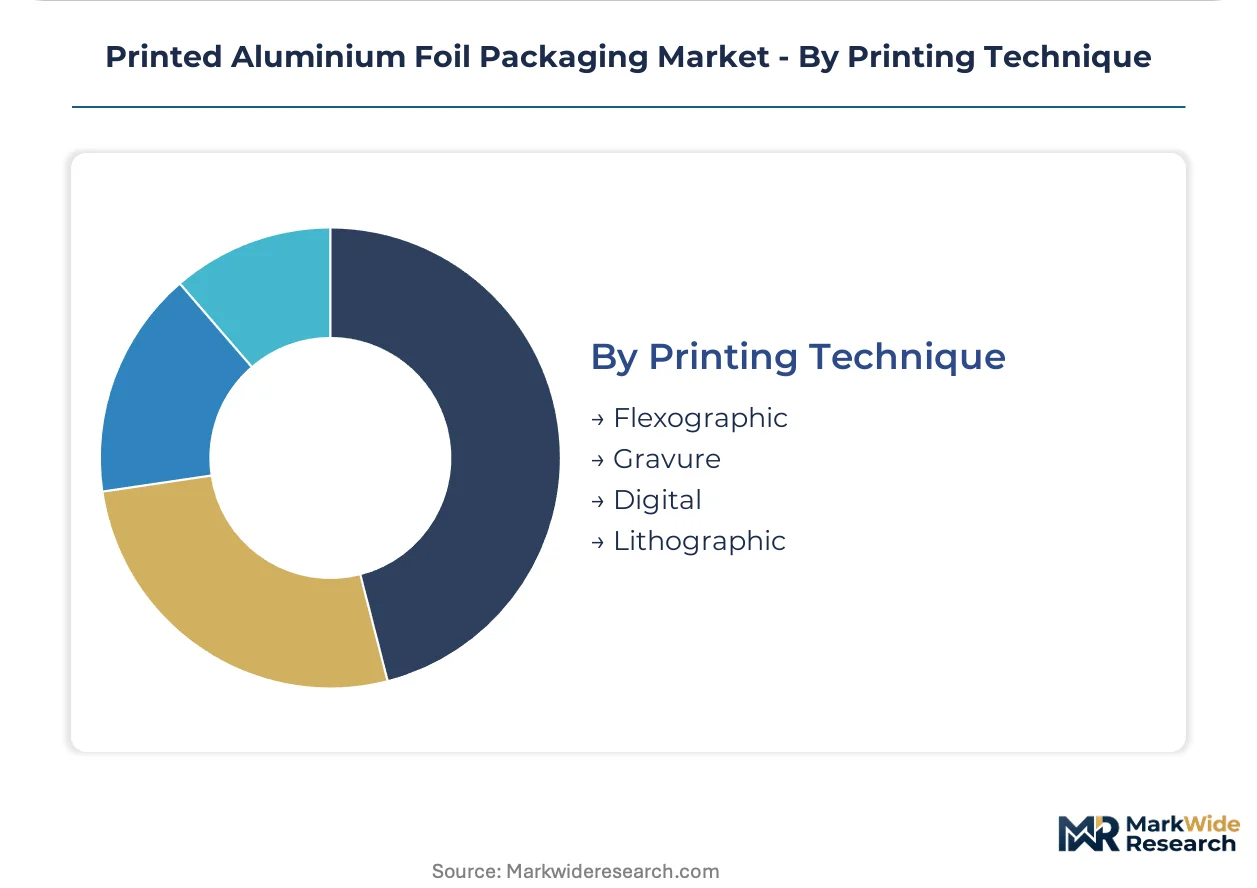
Printing Technique:
Capital investment in cylinder engraving and digital print heads shapes converter service models and minimum order economics.
- Flexographic:Water-based and UV-curable ink systems on central impression drums deliver cost efficiency at medium-to-long runs. The technique anchors volume production for Indian pharmaceutical exporters serving regulated markets.
- Gravure:Engraved cylinder processes achieve superior ink laydown and color consistency for premium food and cosmetic applications. Italian and Japanese converters maintain gravure leadership for high-definition brand reproduction.
- Digital:Inkjet and electrophotographic systems enable short-run customization without cylinder costs. Clinical trial supplies and regional brand variants in the United States are adopting digital for serialization and variable data.
- Lithographic:Offset processes for high-resolution sheet-fed applications.
Gravure and flexographic together hold the majority of installed capacity; digital is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of printed aluminium foil concentrates in smelter-proximate regions, while consumption clusters around pharmaceutical manufacturing corridors and food processing hubs. This geographic split shapes logistics costs, regulatory compliance pathways, and converter investment decisions across major economies.
United States
Pharmaceutical contract manufacturers in New Jersey and North Carolina drive blister foil demand as FDA drug master file requirements tighten supplier qualification. Serialization mandates under the Drug Supply Chain Security Act expand printed foil volume for track-and-trace applications. The Philadelphia-Baltimore corridor hosts converting capacity serving both domestic drug packaging and Latin American export markets.
Germany
EMA elemental impurity guidelines and REACH substance registration compress timelines for foil suppliers serving pharmaceutical manufacturers in Baden-Württemberg. Oxide-coated laminate pilots for moisture-sensitive biologics operate from Swiss border-adjacent facilities. The Rhine-Main industrial cluster integrates gravure printing with pharmaceutical packaging lines under combined EU regulatory oversight.
India
PLI scheme incentives for active pharmaceutical ingredient production scale domestic demand for printed blister foil from integrated packaging suppliers. FSSAI food-contact regulations and DGFT export protocols shape converter compliance investments. Gujarat and Maharashtra host captive foil conversion capacity serving both pharmaceutical exporters and spice processing clusters.
Switzerland
Swissmedic-registered facilities specify thin-gauge foil for high-speed pharmaceutical packaging lines serving European and Asian markets. The Basel-Zurich corridor concentrates cold-form foil innovation for biologics dose protection. Domestic converters maintain dedicated compliance infrastructure for ICH Q3D elemental impurity documentation.
South Korea
MFDS pharmaceutical packaging standards and export-oriented electronics barrier demand sustain roll-to-roll converting capacity. The Seoul-Incheon industrial zone supplies printed foil for semiconductor moisture barrier bags and pharmaceutical pouches. Domestic smelter relationships provide upstream substrate security for converters serving Japanese and Chinese customers.
Printed Aluminium Foil Packaging Market Competitive Landscape
The competitive structure tilts toward integrated aluminium producers with downstream converting capabilities. Smelter-backed players and independent flexible packaging specialists divide the market, with regulatory compliance infrastructure serving as the primary differentiation mechanism. Two archetypes dominate: upstream-integrated metal producers controlling substrate supply, and pharmaceutical-focused converters with dedicated compliance teams. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players seek to bridge the smelter-to-printed-reel traceability requirements tightening across regulated markets.
Within the upstream-integrated tier, Hindalco Industries Ltd. and Novelis Inc. exemplify smelter-backed positioning, while Amcor plc occupies a position among flexible packaging integrators. Constantia Flexibles sits within the pharmaceutical-specialist archetype, with Eurofoil Luxembourg S.A. representing European converter concentration. UACJ Corporation anchors Japanese supply relationships. These named entities illustrate the geographic and structural diversity of competitive positioning without exhaustively cataloguing market presence.
| Leading Market Players |
|---|
| UACJ Corporation |
| Hindalco Industries Ltd. |
| Novelis Inc. |
| Southwest Aluminum Industrial (Group) Co., Ltd. |
| China Hongqiao Group Limited |
| Amcor plc |
| Reynolds Consumer Products LLC |
| Eurofoil Luxembourg S.A. |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between REACH-compliant pharmaceutical foil and commodity food-contact grades manifests in both pricing premiums and supply chain configurations, with European drug packaging buyers paying substantial uplifts for full smelter-to-reel traceability while Indian spice processors optimize for landed cost per square meter.
Pricing Analysis
Cost-down pressure on thin-gauge pharmaceutical grades accelerates because EMA elemental impurity documentation requirements have elevated converter qualification costs. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-registered suppliers from FDA drug master file holders from regional food-contact converters. Alumina price volatility transmits directly to substrate costs, squeezing margins on fixed-price annual contracts. Contract manufacturers in Ireland and the Netherlands exhibit lowest price sensitivity; Indian export-oriented food processors demonstrate highest.
Supply Chain Analysis
Freight differentials between smelter-proximate converting and end-use pharmaceutical corridors shape total delivered cost structures. Primary foil rolling capacity concentrates in India, South Korea, and Germany, with downstream printing and lamination clustering near drug manufacturing hubs in Switzerland, the United States, and the Netherlands. Supply chains draw from bauxite refineries in Australia and Guinea, alumina smelters in China and India, and specialized ink and primer chemical producers in Germany and Japan. Single-source vulnerability sits with Hindalco's captive aluminium supply for Indian pharmaceutical converters. Distribution runs through vendor-managed inventory arrangements at regional pharmaceutical distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical laboratory throughput for extractables and leachables validation constitutes the binding capacity constraint, propping pricing power for qualified converters with in-house migration testing infrastructure.
For Market Incumbents: Cement qualification advantages by deepening backward integration into smelter relationships and expanding dedicated compliance teams for REACH substance registration. Paper-based barrier coatings with metallized structures threaten thin-gauge aluminium displacement in ambient food segments; defend by piloting oxide-coated hybrid laminates for moisture-sensitive biologics in German and Swiss facilities. For New Entrants and Emerging Players: Pharmaceutical contract manufacturers in Ireland and the Netherlands present the most penetrable channel partner type, given their rejection of foil lots lacking full smelter certificates of analysis. Target digital print integration for clinical trial supplies and regional brand variants, where short-run economics bypass gravure cylinder cost barriers. Position through direct ERP integration capabilities and consignment stock offerings. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap converters possessing dedicated ICH Q3D compliance infrastructure given EMA's expanded elemental impurity guidelines. Long-term viability favors players bridging smelter-to-printed-reel traceability requirements across the analysis window. Watch for extended producer responsibility framework fee structures in Europe as the inflection indicator for mono-material aluminium recyclability investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smelter Relationships | Captive aluminium supply secures substrate traceability for FDA drug master file qualification. |
| Migration Testing Capacity Expansion | In-house analytical laboratories compress new product qualification timelines for novel primer chemistries. |
| Digital Print System Integration | Inkjet and electrophotographic convergence enables short-run clinical trial supply without cylinder costs. |
| Mono-Material Format Redesign | Pure aluminium barrier structures qualify for higher EU recycling stream values under packaging waste directives. |
| Vendor-Managed Inventory Implementation | Consignment stock at regional distribution centers satisfies large US pharmaceutical distributor procurement consolidation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with foil converting plant managers, pharmaceutical packaging procurement leads, regulatory affairs directors at contract manufacturers, and technical R&D heads at ink and primer suppliers. Secondary validation drew from FDA drug master file submissions, EMA guidance documents, REACH substance registration databases, and EU packaging waste directive implementation reports. Bottom-up volume modeling triangulated against top-down value estimates.
Reconciliation of production capacity data, import-export flows, and end-use consumption patterns informed the analytical framework across the projection horizon. Segmentation dimensions included product format, end-use vertical, gauge thickness, printing technique, and regional regulatory cluster. CAGRs derived from trend extrapolation of pharmaceutical serialization mandates, food-contact migration limits, and India PLI scheme incentive disbursements.
Caveats apply where alumina price volatility, extended producer responsibility fee structures, or paper-based barrier coating substitution could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Fanfold Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Window Packaging Market
Packaging Materials
US Packaging Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
MDO Films Market
Packaging Materials
PET Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Card Films Market