
 Kraft Packaging Market | 2026-2036
Kraft Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Packaging Market Foresight
Capital-intensity divergence between integrated pulp-to-box operators and non-integrated converters is rotating competitive advantage toward captive fiber supply. International Paper Company leverages its North American timberland base and mill network to control input costs through market cycles. Mondi Group anchors its Central and Eastern European position with on-site kraft paper production feeding dedicated corrugated plants. Smurfit Kappa Group differentiates through a pan-European recycling collection system that sustains closed-loop fiber economics at scale.
Kraft packaging denotes paper-based containers and wraps manufactured from sulfate pulp, typically exhibiting burst strengths of 150–400 kPa and basis weights from 80 to 350 gsm, engineered to protect goods during handling, storage, and transit. The material derives structural integrity from long cellulose fibers preserved in the alkaline cooking process, yielding tear resistance superior to mechanical pulp alternatives. Boxes dominate product-type revenue by volume, though pouches are gaining share in dry-food segments where barrier-coated kraft replaces multi-layer plastic laminates. Virgin grade commands premium positioning in moisture-sensitive electronics and personal-care applications, while recycled grade competes aggressively on unit economics in retail-ready display packaging.
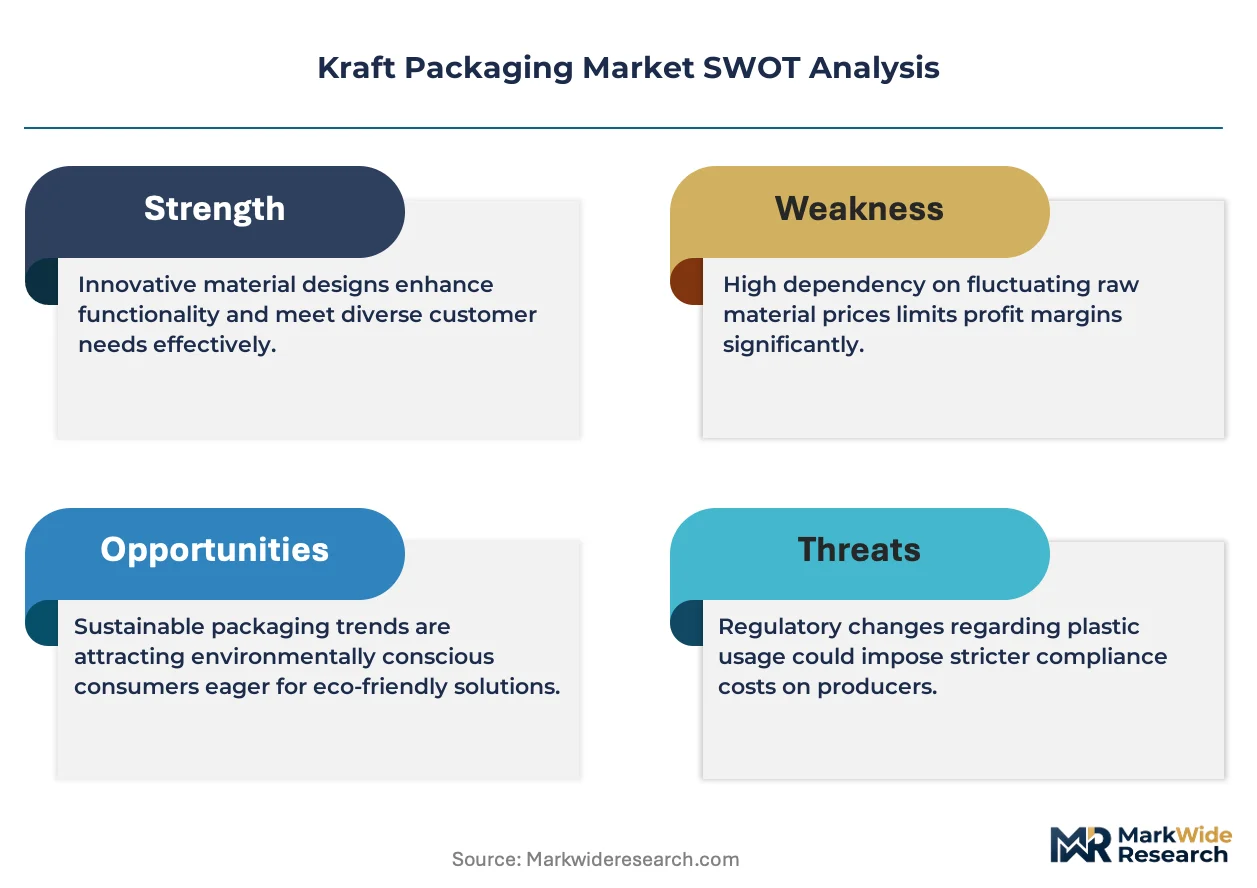
The EU Green Deal and F-Gas Regulation indirectly shape kraft demand by restricting plastic alternatives, while FDA food-contact substance notifications govern kraft migration limits in US food-service applications. REACH compliance on coating chemistries and California's extended producer responsibility framework add compliance layers that favor larger converters with dedicated regulatory staff. Stakeholders must monitor fiber cost volatility and emerging state-level packaging EPR laws to calibrate capacity commitments and grade-mix strategies.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery windows, forcing kraft packaging converters to engineer lighter-weight corrugated grades that maintain burst strength while reducing dimensional weight charges. This pressure is reshaping capital allocation across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled-content thresholds are pulling virgin-fiber converters toward higher-recovery kraft linerboard grades to avoid compliance penalties.
- Food-contact barrier coatings:Water-based polymer treatments are enabling kraft pouches to replace multi-layer plastic laminates in dry-food segments, opening new volume channels.
- Southeast Asia organized retail:Modern grocery expansion in Vietnam and Indonesia is outpacing domestic kraft linerboard mill capacity, creating import-dependent demand pockets.
Market Restraints
- Softwood pulp cost volatility:Northern bleached softwood kraft pulp prices swing with Canadian and Scandinavian mill operating rates, compressing converter margins unpredictably.
- Geographic supply concentration:Containerboard machine capacity clusters in the US Gulf Coast and coastal China, exposing buyers to port congestion and freight spikes.
- Plastic film substitution in moisture-critical applications:Linear low-density polyethylene retains performance advantages in frozen-food and fresh-produce logistics.
Strategic Opportunities
- India domestic capacity gap:Per capita kraft consumption remains below 10 kg annually versus 35 kg in Germany, signaling runway for greenfield mill investment.
- Reusable shipper-box models:Closed-loop rental systems for appliance and electronics fulfillment are creating demand for higher-durability triple-wall kraft constructions.
- California extended producer responsibility framework:State-level EPR mandates are accelerating design-for-recycling investments that favor mono-material kraft over composite alternatives.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for food-contact barrier layers sits concentrated with legacy flexible-packaging specialists, not traditional paper converters.
- Corrugator fleet modernization cycles:Autonomous set-up and AI-driven waste-reduction systems demand eight-figure capital commitments that mid-tier converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Packaging Market |
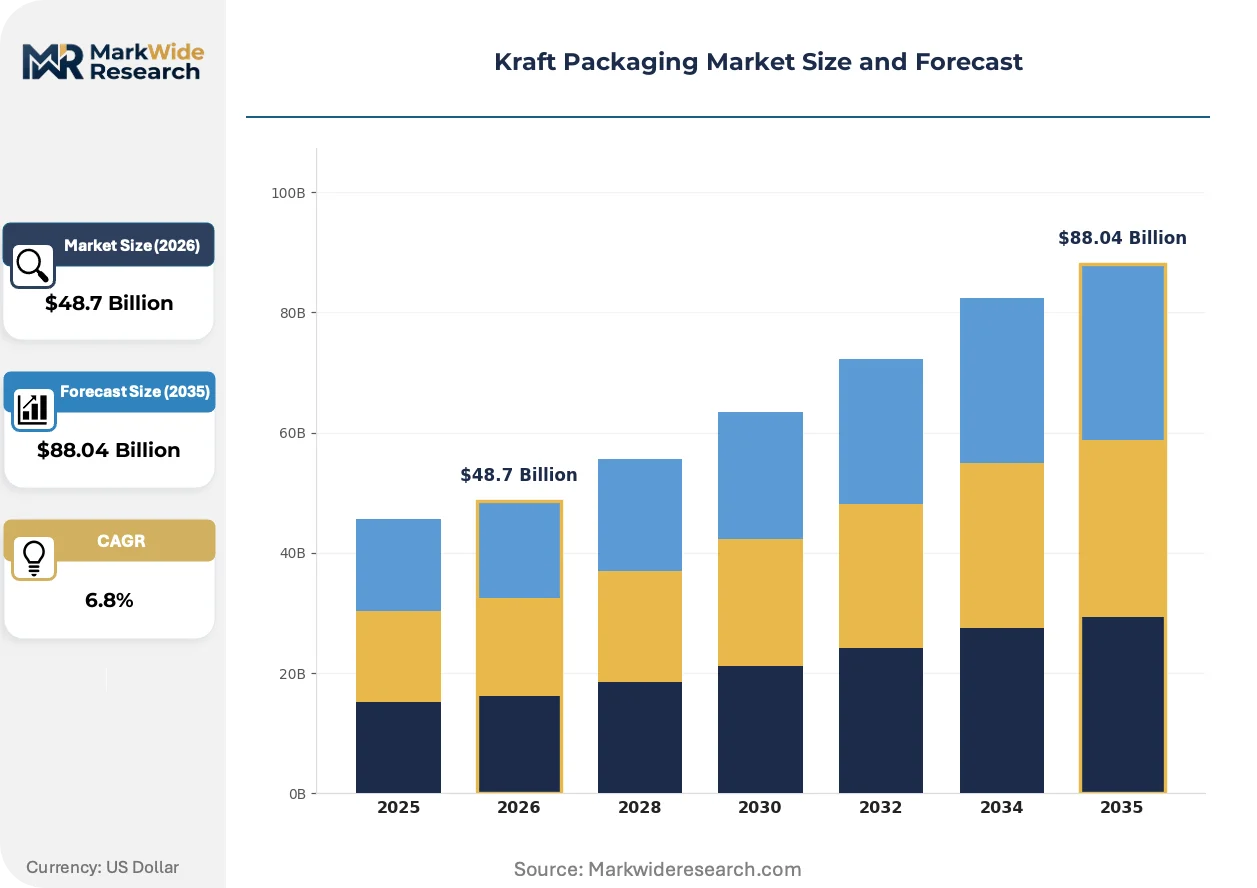
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Pouches End User: Food & Beverage, Retail, Electronics, Personal Care Grade: Recycled, Virgin, Coated, Uncoated Distribution Channel: Online, Retail Stores, Distributors, Wholesalers |
| Companies Covered | International Paper Company, WestRock Company, Mondi Group, DS Smith Plc, Smurfit Kappa Group, Stora Enso, BillerudKorsnäs, Segezha Group, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory compression of plastic alternatives are jointly elevating kraft from commodity wrapper to engineered performance substrate. Three developments merit particular attention.
Barrier-coated kraft paper is decomposing the traditional separation between fiber-based and plastic-based food packaging. European dry-goods brands are adopting grease-resistant fluorochemical-free treatments at pilot scale. This technology is decomposing incumbent multi-layer laminate structures by delivering equivalent shelf-life extension with simpler recovery streams.
REACH compliance on coating chemistries is forcing reformulation of conventional polyethylene extrusion layers used in frozen-food kraft applications. ECHA substance-of-very-high-concern listings are accelerating migration toward bio-based alternatives. European converters with dedicated regulatory affairs teams are securing first-mover advantage in compliant grade certification.
Direct-to-consumer brand procurement teams are consolidating supplier panels and demanding carbon-footprint transparency at the SKU level. Third-party verified lifecycle data is displacing generic industry averages in vendor scorecards. This pattern is most pronounced in German and Dutch electronics and personal-care verticals where B2C shipment volumes concentrate.
Kraft Packaging Market Segmentation
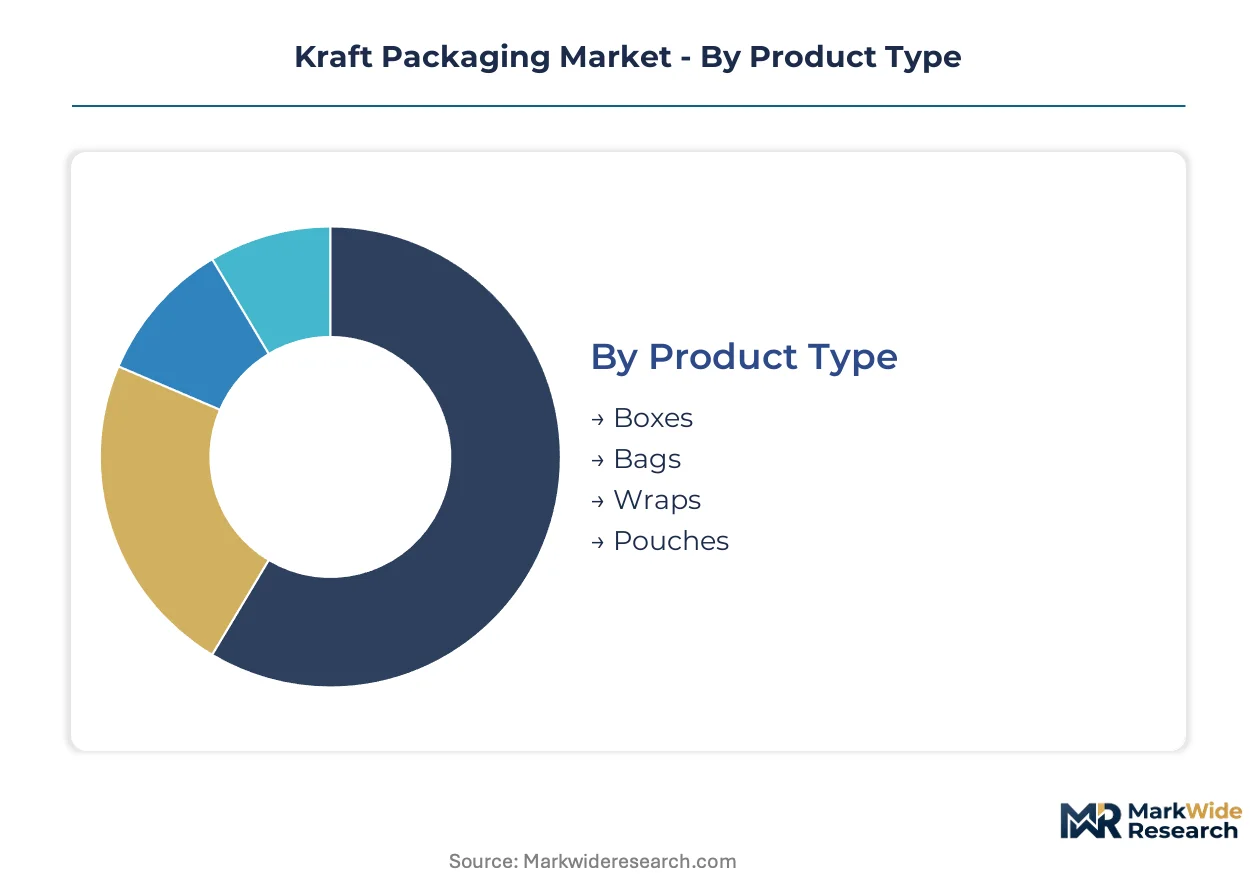
Segmentation in kraft packaging separates commodity-grade volume plays from engineered performance premiums. Grade purity and barrier functionality determine pricing power, while end-use concentration shapes regional capacity deployment.
Product Type:
Margin pools concentrate in protective formats where e-commerce damage rates drive specification intensity.
- Boxes:Corrugated fiberboard constructions with burst strengths of 150–400 kPa dominate fulfillment infrastructure. Demand concentrates in North American and European e-commerce hubs where dimensional weight optimization and automated sortation compatibility command specification premiums.
- Pouches:Flexible kraft laminates with heat-sealable layers are displacing multi-layer plastics in dry-food segments. European dry-goods brands and specialty coffee roasters in Germany and the Netherlands are pulling coated kraft into barrier-sensitive applications.
- Bags:Open-mouth and valve configurations serve cement, chemicals, and agricultural bulk. Construction activity in India and Southeast Asia sustains volume.
- Wraps:Lightweight kraft paper for interleaving and surface protection competes on unit economics in furniture and glass logistics.
The dominant share belongs to boxes, while pouches are closing the gap fastest.
End User:
Application requirements split the market between moisture-sensitive precision and cost-driven commodity flow.
- Food & Beverage:FDA food-contact notifications and EU food-grade certifications govern kraft migration limits. Frozen-food logistics in the US and fresh-produce distribution in Europe sustain virgin-grade demand despite polyethylene competition.
- Retail:Shelf-ready display packaging and branded shopping bags prioritize printability and structural rigidity. German and French mass-market retailers specify recycled-content thresholds under EU Packaging and Packaging Waste Regulation compliance.
- Electronics:Anti-static coatings and moisture vapor transmission rate specifications protect semiconductors and consumer devices. Premium positioning justifies virgin kraft linerboard in Japanese and South Korean export corridors.
- Personal Care:Aesthetic surface quality and fragrance barrier properties support premium unboxing experiences. Direct-to-consumer brands in California and New York are mandating carbon-footprint transparency at the SKU level.
Food & Beverage holds the volume base, with Electronics expanding most quickly on specification intensity.
Grade:
Fiber origin and surface treatment create four distinct cost-performance tiers with divergent supply dynamics.
- Virgin:Northern bleached softwood kraft pulp delivers superior tear resistance and dimensional stability. Electronics and personal-care applications in Japan, Germany, and the US specify virgin grades for moisture-critical transit.
- Coated:Polyethylene extrusion or bio-based barrier layers extend kraft into frozen-food and grease-resistant applications. REACH compliance on coating chemistries is forcing reformulation toward fluorochemical-free alternatives in European production.
- Recycled:Post-consumer fiber content satisfies EU mandatory recycled-content thresholds and California extended producer responsibility frameworks. Retail and e-commerce fulfillment in Europe and the US West Coast are pulling supply toward higher-recovery grades.
- Uncoated:Basic kraft paper for void fill, wrapping, and non-food contact applications competes aggressively on unit economics.
Virgin grade commands the premium tier, though recycled grade is gaining share fastest on regulatory pull.
Distribution Channel:
Channel selection reflects order scale, customization depth, and inventory velocity requirements.
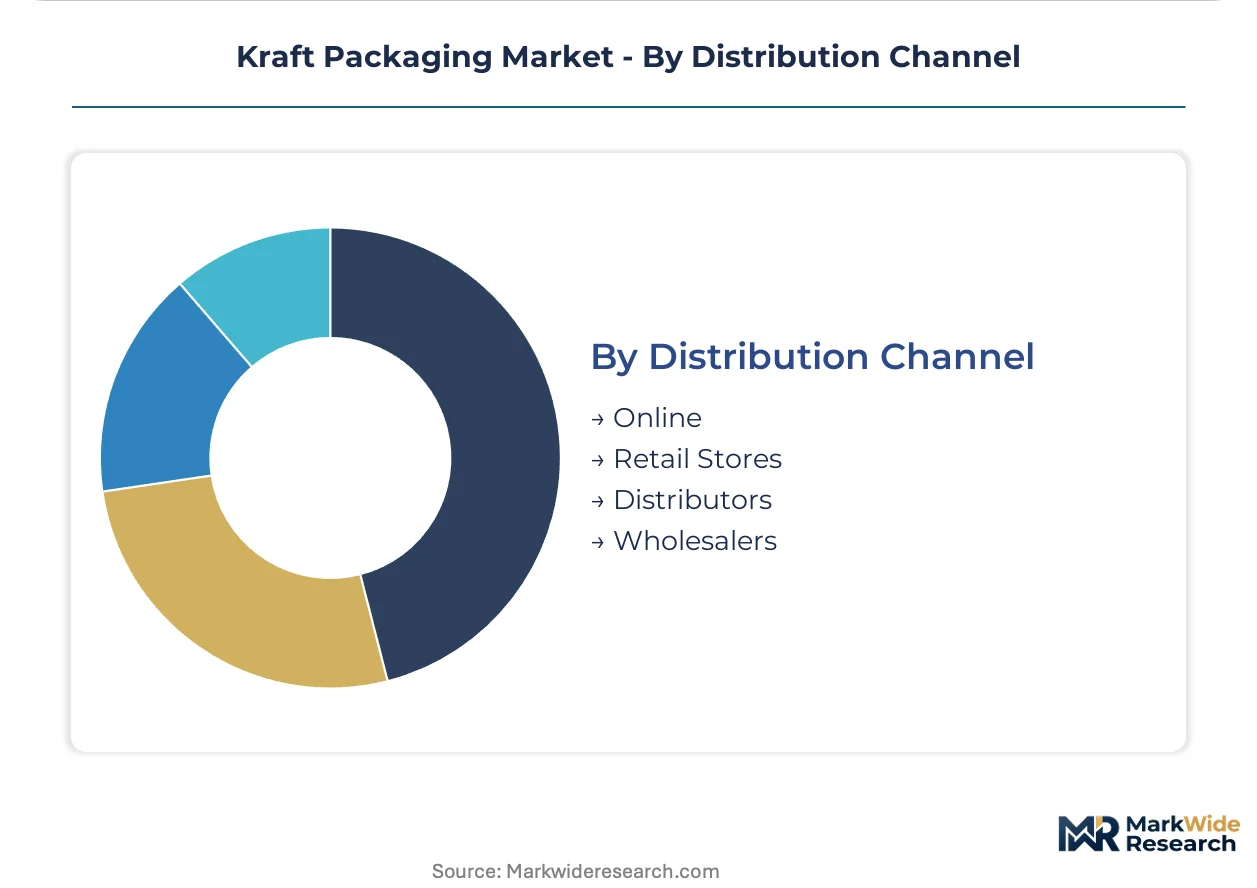
- Distributors:Regional stocking points aggregate fragmented converter output for mid-tier buyers. The US Southeast and coastal China host concentration of containerboard distribution hubs.
- Online:E-procurement platforms and direct mill portals serve standardized specifications with transparent pricing. German and Dutch electronics verticals are consolidating supplier panels through digital channels.
- Wholesalers:Bulk aggregation of commodity grades for price-sensitive packaging buyers in construction and agriculture.
- Retail Stores:Limited to specialty and small-format packaging for immediate consumption segments.
Distributors maintain the foundational volume position, while online channels are climbing the fastest on procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the Netherlands exceeds that in Vietnam and Indonesia by substantial margins, reflecting fiber supply security and regulatory premium capture versus import dependency and domestic capacity constraints.
United States
E-commerce fulfillment networks in Chicago and Dallas-Fort Worth drive specification intensity for lighter-weight corrugated grades. The FDA governs food-contact migration limits for kraft serving frozen-food logistics. Pacific Northwest timberland operators supply captive fiber to integrated mills in Washington and Oregon.
Germany
Specialty coffee roasters and dry-goods brands in Hamburg and Berlin pull coated kraft into barrier-sensitive applications. REACH compliance on coating chemistries forces reformulation toward fluorochemical-free alternatives. The Ruhr Valley hosts concentrated corrugated converting capacity feeding pan-European distribution.
China
Containerboard machine clusters along the Yangtze River Delta serve electronics export corridors to Japan and South Korea. The Ministry of Ecology and Environment enforces dual carbon goals pressuring mill efficiency upgrades. Guangdong Province concentrates import-dependent kraft linerboard demand for appliance manufacturing.
India
Organized retail expansion in Maharashtra and Karnataka outpaces domestic kraft linerboard mill capacity. The Bureau of Indian Standards certifies packaging materials for food-contact applications. Gujarat hosts emerging greenfield mill investments targeting the per capita consumption gap versus European benchmarks.
Vietnam
Modern grocery chains in Ho Chi Minh City and Hanoi generate import-dependent demand for retail-ready display packaging. The country's national environmental regulator tightens industrial wastewater standards for pulp and paper operations. The Mekong Delta region supplies agricultural bulk bag demand for rice and aquaculture exports.
Kraft Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the kraft packaging value chain. The market structure consolidates around integrated pulp-to-box operators with captive fiber supply and specialized converters with barrier-coating expertise. Three archetypes dominate: timberland-backed integrated producers, recycling-loop specialists with collection infrastructure, and regional converters serving fragmented local demand. M&A activity concentrates on recycling collection networks and coating technology acquisitions, while capacity expansion focuses on lighter-weight corrugator upgrades.
Among North American timberland-backed operators, International Paper Company and WestRock Company occupy positions reflecting scale-driven fiber cost control. European recycling-loop specialists include Mondi Group and Smurfit Kappa Group, exemplifying closed-loop fiber economics at scale. These named entities represent archetype anchors rather than exhaustive market coverage, with competitive dynamics shaped by fiber security, regulatory compliance capability, and e-commerce specification responsiveness.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Mondi Group |
| DS Smith Plc |
| Smurfit Kappa Group |
| Stora Enso |
| BillerudKorsnäs |
| Segezha Group |
| Oji Holdings Corporation |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation compliance gates both supplier qualification and price differentiation simultaneously, as converters lacking certified recycled-content grades face exclusion from retail procurement panels while premium virgin grades command specification premiums in moisture-sensitive electronics applications.
Pricing Analysis
Configured-to-order pricing for custom-printed retail-ready displays commands substantial premiums over standard corrugated box quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber grade purity and barrier coating complexity. Cost compression in recycled linerboard is intensifying because EU mandatory thresholds are pulling supply toward higher-recovery grades. Small-format e-commerce merchants exhibit greatest price sensitivity, while pharmaceutical and electronics OEMs prioritize performance specifications over unit economics.
Supply Chain Analysis
Canada and Scandinavia anchor northern bleached softwood kraft pulp production feeding North American and European converter networks. The kraft packaging supply chain draws from timberland operations, chemical recovery boiler capacity, and coating formulation expertise. Single-source vulnerability concentrates in containerboard machine corridors along the US Gulf Coast and coastal China. Distribution runs through integrated mill-to-box plant networks and regional corrugated sheet feeders serving fragmented local demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kraft packaging incumbents face sustained substitution defense against multi-layer plastic laminates and emerging molded fiber alternatives in food-contact applications.
For Market Incumbents: Shield market position through captive fiber supply investments in timberland-backed pulp operations and accelerated barrier-coating R&D to match plastic shelf-life performance. Prioritize certification pre-positioning ahead of California extended producer responsibility framework expansion. Defensive consolidation should target recycling collection infrastructure to secure closed-loop fiber economics.
For New Entrants and Emerging Players: Lead with coated kraft pouch specialization targeting European dry-goods brands seeking fluorochemical-free barrier solutions. White-space concentration sits in India domestic mill capacity gaps where organized retail expansion outpaces supply. Go-to-market positioning should emphasize carbon-footprint transparency at SKU level for German and Dutch direct-to-consumer brand procurement panels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across corrugator fleet modernization cycles demanding autonomous set-up and AI-driven waste-reduction systems. Long-term viability over the coming decade rests on coating chemist talent acquisition and regulatory affairs capability buildout. Acquisition target archetype: regional converters with established FDA food-contact notification pathways. The signal to watch is state-level packaging EPR law proliferation beyond California.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberland Assets | International Paper leverages Pacific Northwest timberland to control input costs through market cycles. |
| Barrier Coating Technology Acquisition | European converters secure first-mover advantage in REACH-compliant fluorochemical-free food-contact grades. |
| Recycling Collection Network Expansion | Smurfit Kappa's pan-European closed-loop system sustains fiber economics at scale. |
| Lightweight Corrugated Grade Development | E-commerce fulfillment networks in Chicago compress dimensional weight charges through specification engineering. |
| Greenfield Mill Investment in India | Gujarat-based capacity targets per capita consumption gaps versus German benchmarks. |
Research Methodology
Initial hypotheses were tested against primary input from corrugated plant managers, retail procurement directors, coating R&D chemists, and paper mill operations heads and refined through secondary validation against customs trade data, SEC 10-K filings of integrated producers, FDA food-contact substance notifications, and EU Packaging and Packaging Waste Regulation compliance databases. Bottom-up volume triangulation across grade-tier and end-use segments was cross-checked against top-down macroeconomic drivers.
Variance-decomposition framing separates volume growth from mix-shift and pricing components across the analysis window. Segmentation dimensions modeled include product type, end-use vertical, fiber grade purity, and geographic regulatory cluster. CAGRs were derived from trend extrapolation calibrated to disclosed capacity expansion timelines and pulp cost cycle assumptions. Industry-specific forecast inputs incorporate e-commerce shipment density trajectories and EU recycled-content threshold implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce penetration rates or abrupt plastic substitution reversals would require recalibration. Forecasts reflect documented assumptions on fiber cost volatility and regulatory enforcement intensity. Recalibration cycles align with material shifts in state-level EPR law adoption and coating chemistry reformulation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Urn Liners Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Global Strapping Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Finish Foils Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Fanfold Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Water Soluble Pods Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Card Films Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market