
 Global Thin Wall Packaging Market | 2026-2036
Global Thin Wall Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thin Wall Packaging Market Outlook
ISO 22000 certification for food-contact materials is rotating supplier eligibility across the thin wall packaging value chain. Huhtamaki Oyj leverages its thermoforming expertise to dominate Nordic dairy applications. Amcor plc anchors global supply through in-house resin compounding capabilities. Berry Global Inc. competes via multi-site injection molding networks across North America.
Thin wall packaging denotes rigid containers manufactured with wall thickness below 0.8 mm, typically through injection molding or thermoforming of polypropylene, polystyrene, or polyethylene terephthalate, engineered to minimize material weight while preserving stack strength and barrier performance for perishable goods distribution. Plastic material commands the largest volume share due to cost efficiency in high-speed conversion, though paperboard alternatives are capturing premium shelf-ready segments where fiber-based recyclability commands retailer preference. Food & Beverage end users generate the dominant demand pool, with Healthcare applications offering higher margin potential through sterilization-grade validation requirements.
FDA food-contact substance notifications govern material composition for US-bound exports, while EFSA migration limits and EU Single-Use Plastics Directive enforcement shape formulation choices across European supply chains. China's GB standards for food packaging and India's BIS certification for plastic articles create divergent compliance thresholds that fragment cross-border product standardization. Stakeholders must monitor evolving extended producer responsibility frameworks to anticipate which material platforms will retain cost-competitive market access.
Market Dynamics
The EU Single-Use Plastics Directive is redirecting material innovation toward certified recyclable substrates while Southeast Asian foodservice procurement accelerates polypropylene container volumes. This regulatory-material tension is compressing legacy polystyrene conversion economics and fragmenting supplier eligibility across ISO 22000 certification tiers.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework mandates recycled content thresholds and bans specific single-use formats, redirecting R&D investment toward polypropylene and PET monomaterial structures that qualify for extended producer responsibility credits.
- Vietnam manufacturing corridor expansion:Foodservice operators are concentrating procurement near Ho Chi Minh City, leveraging integrated resin-to-conversion infrastructure that reduces landed costs for export-bound dairy and ready-meal containers.
- High-speed thermoforming automation:Servo-driven forming and trim-in-place systems are compressing cycle times below 2.5 seconds per cavity, enabling converters to absorb resin volatility through throughput gains rather than price premiums.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker margins and PDH unit economics in the Middle East create input cost instability that converters cannot fully pass through to price-sensitive foodservice accounts.
- China GB standard fragmentation:Divergent national food-contact substance notification requirements versus EU and US regimes force SKU proliferation and inventory segmentation for cross-border suppliers.
- Paperboard barrier performance ceiling:Fiber-based alternatives lack the oxygen and moisture barrier properties required for protein-rich prepared meals, limiting substitution in high-value chilled distribution.
Strategic Opportunities
- India BIS certification gap:Domestic converters with in-house testing laboratories can capture share from import-dependent food brands as enforcement of plastic article standards tightens in urban distribution.
- Chemical recycling feedstock integration:Pyrolysis-derived polypropylene is achieving food-contact regulatory acceptance, creating closed-loop supply partnerships with quick-service restaurant chains under science-based target commitments.
- Direct-to-processor digital platforms:B2B marketplaces are compressing distributor margins by connecting Vietnamese injection molders with European dairy cooperatives for spot container procurement.
Industry Challenges
- ISO 22000 auditor scarcity:Third-party certification bodies face backlogs exceeding eight months for food-contact material audits, delaying new supplier qualification for healthcare and infant nutrition contracts.
- Multi-site mold standardization:Converters operating distributed injection networks across North America struggle to maintain cavity-to-cavity weight consistency when transferring tools between presses with differing hydraulic response profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thin Wall Packaging Market |
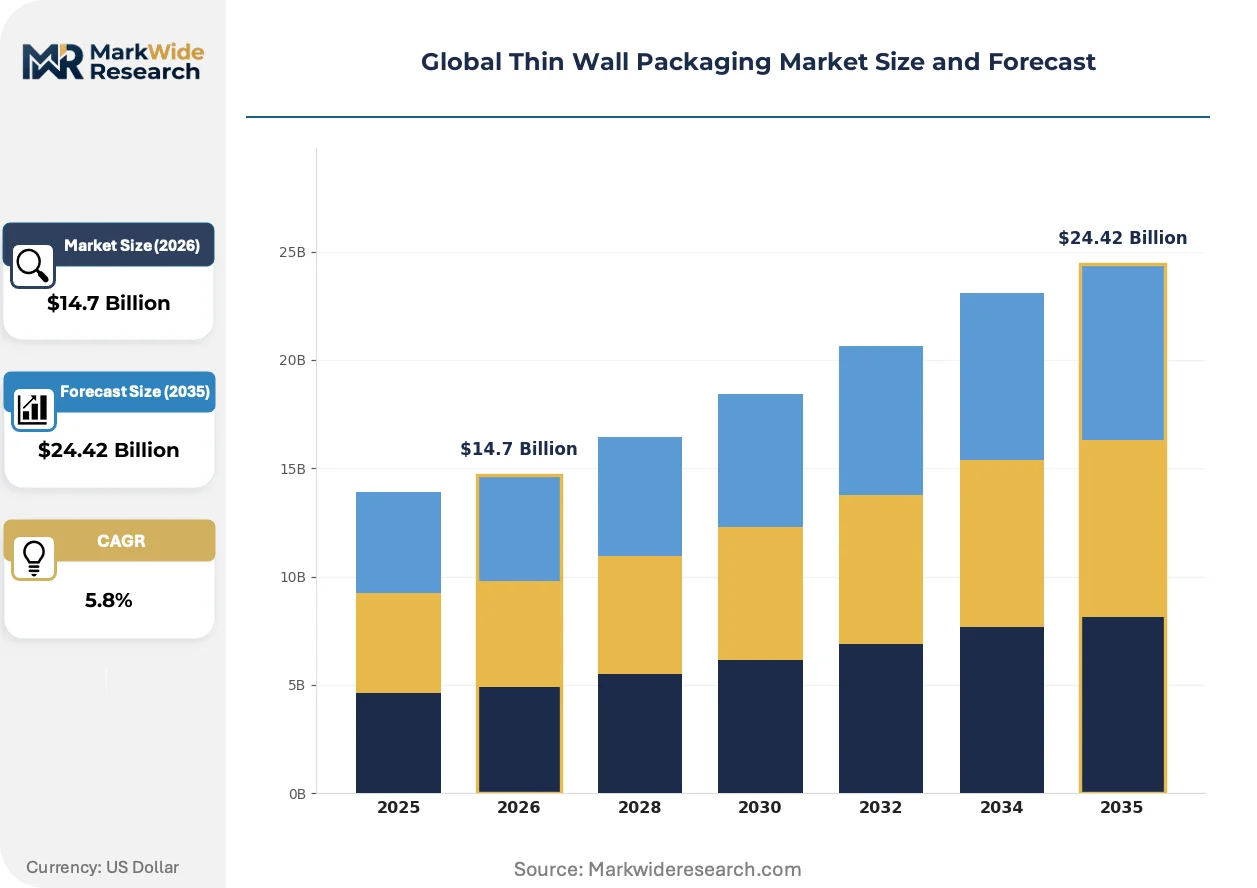
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Cups, Trays, Lids Material: Plastic, Paperboard, Aluminum, Glass End User: Food & Beverage, Personal Care, Healthcare, Electronics Application: Retail, Industrial, Institutional, Disposable |
| Companies Covered | Silgan Holdings Inc., Huhtamaki Oyj, Amcor plc, RPC Group Plc, Faerch Group, Berry Global Inc., ALPLA, Plastipak Holdings, Greiner Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thin Wall Packaging Market Strategic Shifts
Material science advances and regulatory compliance automation are compressing development cycles for next-generation barrier structures. Digital manufacturing integration is simultaneously reshaping quality assurance protocols and supplier-buyer data exchange.
Thin-wall injection molding with in-mold labeling integration is displacing post-decorated thermoformed containers in premium dairy applications. Nordic retailers are specifying IML-compatible polypropylene pails for private-label yogurt lines. The technology is displacing secondary labeling operations and enabling real-time traceability through embedded QR codes.
EFSA migration limit revisions for mineral oil saturated hydrocarbons are forcing reformulation of recycled polypropylene feedstocks. Converters must deploy super-cleaning technologies or virgin blending strategies to meet specific migration thresholds. The dairy segment is responding with segregated collection partnerships and mass-balance certification through ISCC PLUS schemes.
Consolidated procurement by pan-European foodservice buying groups is compressing supplier margins and accelerating qualification of secondary-tier molders. These cooperatives are mandating real-time production data access and carbon footprint disclosure as contract conditions. The shift is most visible in Germany and the Netherlands where foodservice distribution has concentrated under three major procurement alliances.
Global Thin Wall Packaging Market Segmentation
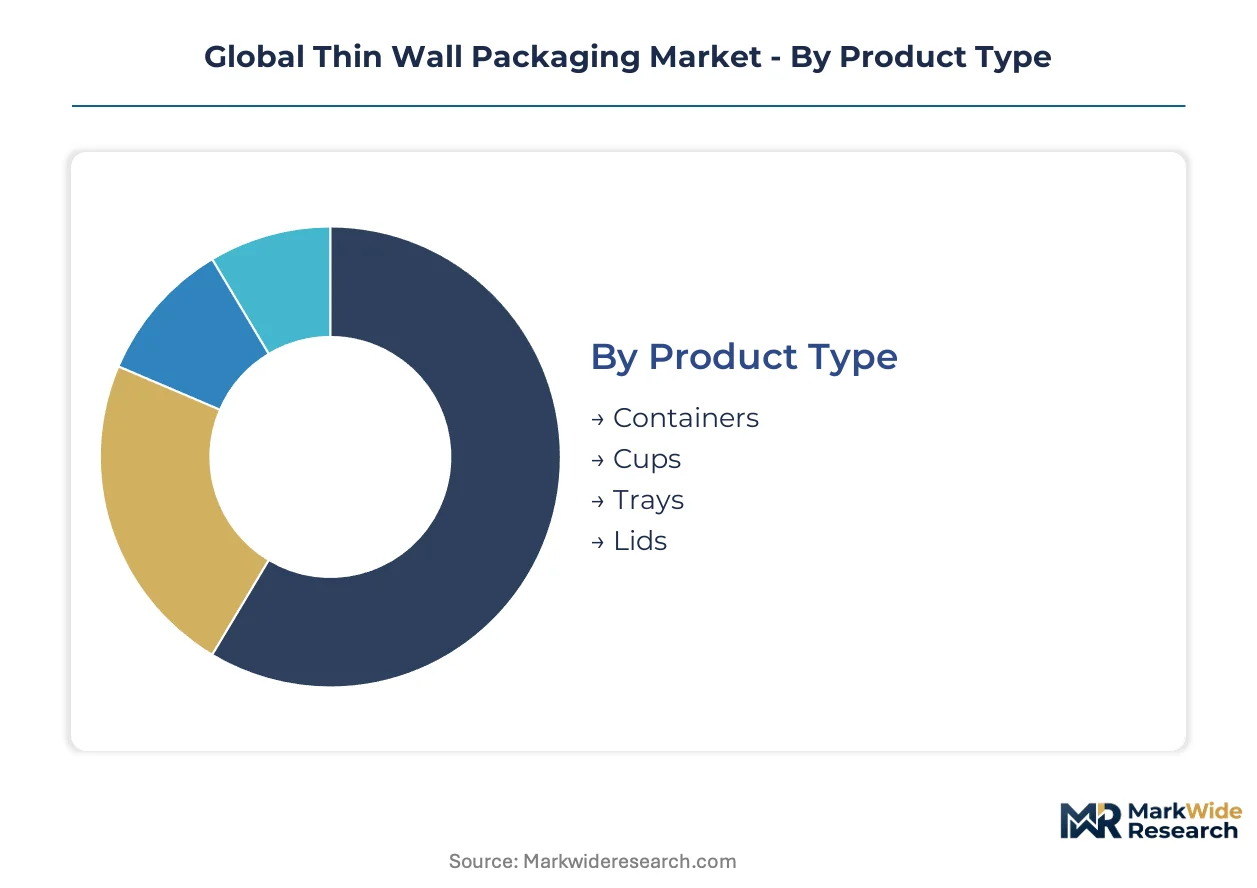
Thin wall packaging segmentation reveals divergent margin structures across material platforms and end-use specifications. Product geometry and barrier performance requirements determine converter economics more than volume scale alone.
Product Type:
Margin pools concentrate in lidded container systems where multi-component assembly justifies premium pricing over single-piece formats.
- Containers:Injection-molded polypropylene tubs with integrated stacking ribs dominate dairy and ready-meal distribution. Vietnamese foodservice operators near Ho Chi Minh City are scaling procurement of tamper-evident container-lid combinations for export-bound seafood and noodle applications.
- Cups:Thermoformed polystyrene and polypropylene cups serve beverage and portion-control markets. Nordic dairy cooperatives specify IML-compatible polypropylene cups with embedded QR traceability, displacing post-decorated alternatives through real-time production data access.
- Trays:Multi-cavity designs for protein packaging require precise cavity-to-cavity weight consistency.
- Lids:Peelable and resealable lid structures command specification premiums in healthcare and infant nutrition segments.
The dominant share belongs to Containers, while Cups are gaining share fastest through IML integration and foodservice procurement concentration.
Material:
Cost tier stratification separates commodity resin converters from certified recyclable substrate specialists capturing EPR credit value.
- Plastic:Polypropylene, polystyrene, and polyethylene terephthalate dominate through high-speed injection molding and thermoforming conversion. EFSA migration limit revisions for mineral oil saturated hydrocarbons are forcing super-cleaning technology deployment or virgin blending strategies in recycled polypropylene feedstocks.
- Paperboard:Fiber-based alternatives capture premium shelf-ready segments where retailer recyclability preferences override barrier limitations. Protein-rich prepared meal distribution remains constrained by oxygen and moisture barrier performance ceilings.
- Aluminum:Foil-laminated structures serve pharmaceutical blister and high-barrier dairy applications.
- Glass:Thin-walled borosilicate and soda-lime formats retain niche positions in premium cosmetic and pharmaceutical packaging.
Plastic retains volume leadership, though Paperboard is expanding most quickly in private-label retail specifications.
End User:
Application maturity varies sharply, with healthcare validation requirements creating defendable margin premiums over commoditized foodservice supply.
- Food & Beverage:Dairy, ready-meals, and quick-service restaurant packaging generate the dominant demand pool. Pan-European foodservice buying groups in Germany and the Netherlands are mandating carbon footprint disclosure and real-time production data access as contract conditions.
- Healthcare:Sterilization-grade containers for medical devices and pharmaceutical distribution offer higher margin potential. ISO 22000 certification backlogs exceeding eight months are delaying new supplier qualification for infant nutrition contracts.
- Personal Care:Cosmetic and hygiene applications favor aesthetic surface finishes and fragrance barrier properties.
- Electronics:Antistatic and moisture-barrier trays protect sensitive components during distribution.
Food & Beverage commands the largest volume position, while Healthcare is climbing the fastest through sterilization validation premiums.
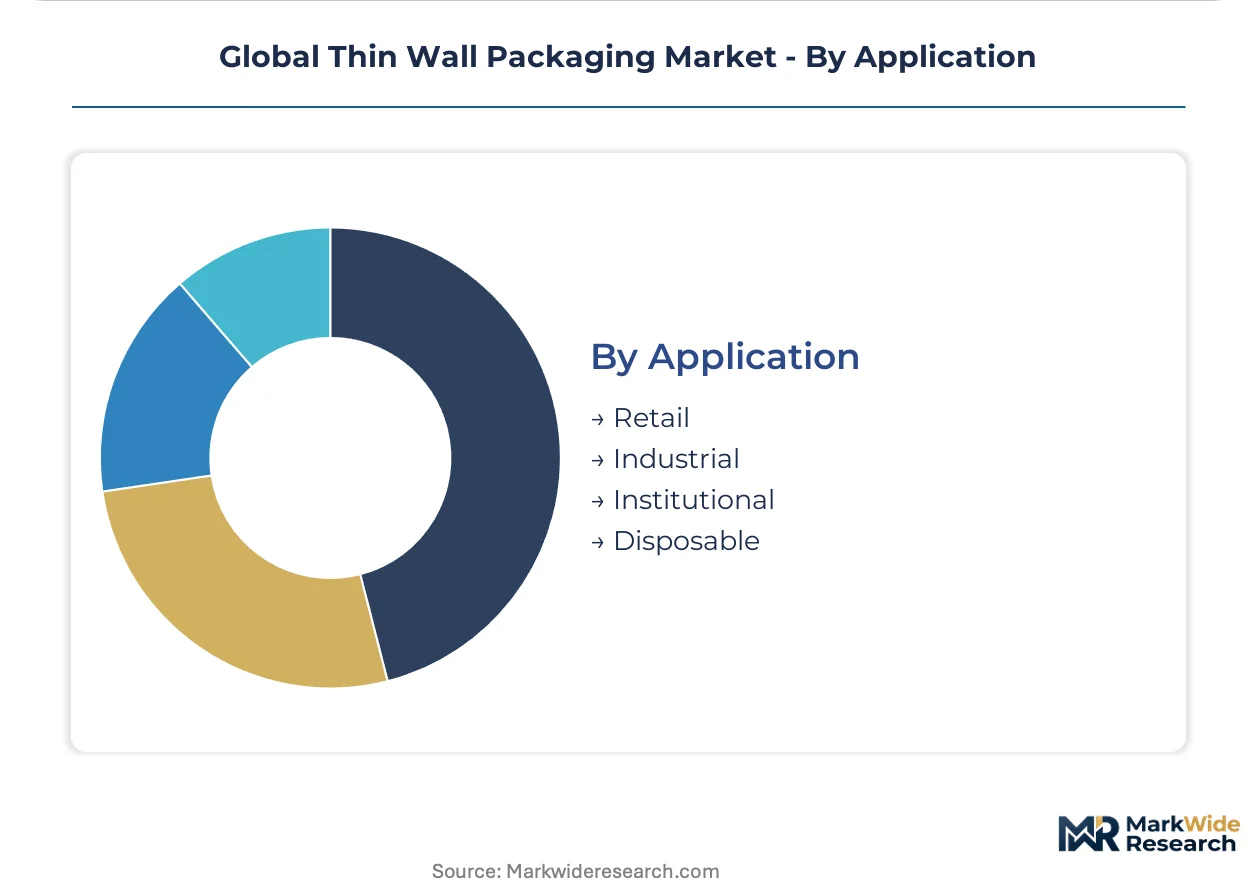
Application:
Customer type determines specification intensity, with institutional procurement favoring standardization and retail demanding customization.
- Retail:Shelf-ready packaging with embedded traceability and premium decoration serves supermarket and convenience store distribution. Nordic retailers specify IML-compatible polypropylene pails for private-label yogurt lines.
- Industrial:Bulk intermediate packaging for ingredient and component supply chains prioritizes stack strength and cube efficiency over aesthetic finish.
- Institutional:Foodservice and healthcare facility supply contracts emphasize cost control and supply assurance through multi-year agreements.
- Disposable:Single-use formats face regulatory pressure from EU Single-Use Plastics Directive mandates on recycled content thresholds and banned formats.
Retail holds the dominant share, though Industrial is expanding most quickly through B2B marketplace procurement platforms connecting Vietnamese molders with European buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cai Mep-Thi Vai deep-water port complex underwrites Vietnam's emergence as the primary resin-to-conversion hub for thin wall packaging exports to Europe and Japan. Integrated industrial zones within 50 kilometers of this facility cluster injection molders serving dairy and ready-meal supply chains.
United States
Quick-service restaurant chains and dairy cooperatives drive container demand across the Midwest and Southeast manufacturing belts. FDA food-contact substance notifications govern material composition for interstate commerce, creating compliance thresholds that favor converters with in-house regulatory affairs capabilities. Chicago and Dallas-Fort Worth host concentrated thermoforming operations supplying national foodservice distribution networks.
Germany
Pan-European foodservice buying groups headquartered in Frankfurt and Munich compress supplier margins through consolidated procurement of polypropylene containers. EFSA migration limits for mineral oil saturated hydrocarbons force super-cleaning technology deployment in recycled feedstock processing. The Baden-Württemberg industrial corridor anchors high-speed IML-compatible cup production for private-label yogurt lines.
China
Domestic quick-service restaurant expansion and cross-border e-commerce fulfillment generate dual demand streams for lightweight containers. GB standards for food packaging create divergent compliance thresholds versus EU and US regimes, forcing SKU proliferation for export-oriented molders. The Yangtze River Delta manufacturing belt near Shanghai concentrates servo-driven thermoforming automation for dairy and ready-meal applications.
India
Urban food brands and quick-service restaurant chains accelerate procurement of tamper-evident containers as BIS certification enforcement tightens. The FSSAI framework for food-contact materials rotates supplier eligibility through testing laboratory requirements. Maharashtra and Gujarat host expanding injection molding capacity serving domestic dairy and spice packaging segments.
Vietnam
Export-bound seafood and noodle applications concentrate procurement near Ho Chi Minh City's integrated resin-to-conversion infrastructure. Foodservice operators leverage the Cai Mep-Thi Vai port corridor to reduce landed costs for European and Japanese dairy container contracts. Binh Duong and Dong Nai provinces cluster high-cavity mold operations with cycle times below 2.5 seconds per cavity.
Global Thin Wall Packaging Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions, producing a tiered structure where scale-driven multinationals anchor global supply alongside regional conversion specialists. Three archetypes dominate: integrated resin compounders with captive polymer supply, multi-site injection molders with distributed North American networks, and Nordic thermoforming specialists with dairy application expertise. Competitive moves concentrate on strategic partnerships for chemical recycling feedstock integration and capacity expansion in Vietnamese manufacturing corridors.
Within the integrated compounder tier, Amcor plc and Berry Global Inc. exemplify scale-driven positioning through in-house resin capabilities and multi-site production networks. Huhtamaki Oyj occupies a specialist position representing Nordic thermoforming expertise concentrated in dairy and foodservice applications. These three companies anchor the competitive landscape through divergent strategic postures: global supply chain integration, distributed manufacturing scale, and premium application specialization.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Huhtamaki Oyj |
| Amcor plc |
| RPC Group Plc |
| Faerch Group |
| Berry Global Inc. |
| ALPLA |
| Plastipak Holdings |
| Greiner Packaging International |
| Others |
Value Chain & Pricing Dynamics
Polypropylene's displacement of polystyrene in foodservice applications redraws procurement geography toward Vietnamese resin-to-conversion corridors while compressing legacy converter margins through EPR credit asymmetries. Buyers now capture pricing leverage from material platform switches that simultaneously relocate supply concentration and fragment supplier eligibility tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs converter-buyer negotiations. Premium tiers attach to ISO 22000-certified healthcare and infant nutrition contracts; standard tiers serve pan-European foodservice buying groups with carbon disclosure mandates; economy tiers absorb Southeast Asian spot procurement for export-bound seafood containers. Price differentiation hinges on certification grade and volume scale, with pan-European buying groups extracting steepest discounts through consolidated procurement. Pricing pressure stems from propylene feedstock volatility that converters cannot fully pass to price-sensitive foodservice accounts. Quick-service restaurant chains exhibit highest price sensitivity; healthcare sterilization-grade buyers accept premium positioning.
Supply Chain Analysis
Vietnam and Germany anchor thin wall packaging production through divergent specializations. Vietnamese molders near Ho Chi Minh City concentrate high-cavity injection operations for export-bound dairy and ready-meal containers; German converters in Baden-Württemberg dominate IML-compatible cup production for private-label yogurt lines. Raw material dependencies center on naphtha-derived polypropylene resin, servo-driven thermoforming equipment, and super-cleaning technology for recycled feedstock compliance. Supply chain risk concentrates in single-source vulnerability for EFSA-compliant mineral oil saturated hydrocarbon testing protocols. Distribution runs through B2B digital platforms compressing traditional distributor margins between Vietnamese molders and European dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pan-European foodservice buying groups whose consolidated procurement in Germany and the Netherlands now dictates contract terms including real-time production data access and carbon footprint disclosure.
For Market Incumbents: Shield margin position by accelerating chemical recycling feedstock integration with quick-service restaurant chains under science-based target commitments. Deploy in-house regulatory affairs capabilities to navigate FDA food-contact substance notification backlogs that delay competitor qualification. Prioritize capacity expansion in Vietnam's Binh Duong and Dong Nai provinces to capture export-bound seafood and noodle container procurement migrating toward the Cai Mep-Thi Vai corridor. For New Entrants and Emerging Players: Real-time production data access gaps among legacy converters create entry vectors for digital-native molders serving pan-European buying groups. Target India's domestic food brands facing BIS certification enforcement tightening in Maharashtra and Gujarat urban distribution. Exploit ISO 22000 auditor scarcity exceeding eight months by building in-house testing laboratory capabilities to accelerate healthcare and infant nutrition contract qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Nordic thermoforming specialists holding dairy application expertise but lacking chemical recycling feedstock integration. Five-to-ten-year viability hinges on converters capturing extended producer responsibility credit value through certified recyclable substrate specialization. Watch for EFSA migration limit enforcement tightening as inflection indicator favoring super-cleaning technology deployers over virgin-blending competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Feedstock Integration | Pyrolysis-derived polypropylene achieves food-contact regulatory acceptance, enabling closed-loop partnerships with quick-service restaurant chains. |
| Vietnam Manufacturing Corridor Expansion | Binh Duong and Dong Nai provinces cluster high-cavity mold operations with cycle times below 2.5 seconds per cavity. |
| ISO 22000 Certification Investment | In-house testing laboratories capture share from import-dependent food brands as BIS enforcement tightens in India. |
| IML-Compatible Production Scale-Up | Nordic retailers specify embedded QR traceability for private-label yogurt lines, displacing post-decorated alternatives. |
| B2B Digital Platform Development | Direct-to-processor marketplaces compress distributor margins connecting Vietnamese molders with European dairy cooperatives. |
Study Parameters
A spread of perspectives from thermoforming plant managers, foodservice procurement leads at pan-European buying groups, resin compounding technical directors, and healthcare sterilization validation specialists converged on the working assumptions. Primary interviews combined with secondary validation from SEC 10-K filings, customs and trade data, EFSA migration limit revision notices, and FDA food-contact substance notification databases. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled span material platform, product geometry, end-use application, and regional production hub across the projection horizon. CAGRs derived from regression analysis against resin price volatility indices and foodservice operator procurement expansion rates. Industry-specific forecast inputs incorporated servo-driven thermoforming automation adoption curves and extended producer responsibility framework evolution.
Forecasts assume regulatory continuity in FDA food-contact substance notification regimes and EU Single-Use Plastics Directive enforcement; material policy shifts would require re-modeling. Specific risks include EFSA mineral oil saturated hydrocarbon limit revisions, China GB standard fragmentation forcing SKU proliferation, and propylene feedstock volatility from Middle East PDH unit economics. Recalibration cycles align with material shifts in chemical recycling regulatory acceptance and pan-European buying group procurement consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Shrink Packaging Market
Packaging Materials
VCI Packaging Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Desiccant Market